
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Battery Testing Equipment Market Size 2024 | USD 595.7 million |
| Battery Testing Equipment Market, CAGR | 4.5% |
| Battery Testing Equipment Market Size 2032 | USD 847.14 million |
Market Overview:
The Global Battery Testing Equipment Market size was valued at USD 595.7 million in 2024 and is anticipated to reach USD 847.14 million by 2032, at a CAGR of 4.5% during the forecast period (2024-2032).
Several factors are propelling market growth, including the surge in EV adoption, advancements in battery technologies, and stringent regulatory standards for battery safety. The automotive sector remains a major driver, with manufacturers focusing on enhancing battery performance and durability. Additionally, the growing deployment of energy storage systems and the proliferation of consumer electronics are increasing the demand for battery testing equipment. Government regulations mandating battery safety and performance standards further accelerate market expansion, compelling manufacturers to invest in high-precision testing solutions. The rising trend of battery recycling and second-life applications is also boosting demand for testing solutions to assess used battery viability. Furthermore, collaborations between battery manufacturers and testing equipment providers are fostering innovation in high-accuracy testing systems.
Regionally, Asia-Pacific dominates the market, driven by China, Japan, and South Korea, which lead in battery production and electric vehicle adoption. The region’s strong presence of battery manufacturers and technological advancements contribute to its growth. Government initiatives supporting battery production and EV infrastructure development are further fueling market expansion. Additionally, China’s dominance in lithium-ion battery supply chains strengthens its leadership in battery testing equipment demand. North America and Europe also hold significant market shares due to rising EV adoption, stringent environmental regulations, and investments in R&D for battery innovations. The Middle East and Africa are witnessing gradual growth, supported by increasing investments in renewable energy projects. Meanwhile, Latin America is emerging as a potential market, driven by the demand for energy storage solutions and electrification initiatives. Growing interest in grid-scale battery storage and the rising number of government-backed renewable projects are key factors driving battery testing equipment adoption in these regions.
Market Insights:
- The battery testing equipment market was valued at USD 595.7 million in 2024 and is expected to reach USD 847.14 million by 2032, growing at a CAGR of 4.5%, driven by the rise in EV adoption, battery advancements, and stringent safety regulations.
- The increasing adoption of electric vehicles is a major driver, with governments enforcing emission regulations and incentives, leading to higher demand for battery testing solutions to ensure safety, efficiency, and durability.
- The growing deployment of renewable energy storage systems necessitates advanced battery testing solutions, as large-scale energy storage projects require continuous monitoring for reliability, performance, and compliance.
- Stringent regulatory standards from organizations like IEC, UL, and ISO mandate rigorous battery testing for automotive, aerospace, medical, and consumer electronics applications, pushing manufacturers to invest in high-precision testing solutions.
- Technological advancements such as AI-driven analytics, automation, and real-time monitoring are improving testing accuracy, with innovations in solid-state batteries, fast charging, and high-energy density storage increasing the need for sophisticated testing equipment.
- High costs of advanced testing solutions pose a challenge, particularly for small and medium-sized enterprises, while the complexity of evolving battery technologies and changing regulatory standards creates compliance challenges for manufacturers.
- Asia-Pacific dominates the market with a 45% share, led by China, Japan, and South Korea, followed by North America (25%) and Europe (20%), with growing investments in battery recycling, second-life applications, and sustainable energy solutions driving further demand for testing equipment.
Market Scope
Market Drivers:
Rising Adoption of Electric Vehicles (EVs):
The increasing adoption of electric vehicles is a major driver for the battery testing equipment market. Governments are enforcing stringent emission regulations and offering incentives to promote EV adoption, pushing automakers to invest in advanced battery technologies. For instance, the California Air Resources Board (CARB) has implemented a zero-emission vehicle program, requiring automakers to sell a certain percentage of zero-emission vehicles in the state. The rising demand for high-performance lithium-ion batteries requires rigorous testing for safety, efficiency, and longevity. Battery testing equipment is essential for evaluating parameters such as charge capacity, cycle life, and thermal stability to ensure compliance with regulatory standards. The expansion of EV charging infrastructure further increases the need for robust battery testing solutions to enhance system reliability.
Growing Deployment of Renewable Energy Storage Systems:
The integration of solar and wind power into grids necessitates efficient energy storage solutions to stabilize intermittent energy generation. Grid-scale energy storage projects require continuous monitoring and performance assessment, boosting the demand for high-precision battery testing equipment. For instance, the U.S. Department of Energy's Energy Storage Grand Challenge aims to accelerate the development, commercialization, and utilization of next-generation energy storage technologies. Governments and private enterprises are investing in energy storage projects, further driving market growth. As renewable energy adoption expands, battery testing equipment will play a crucial role in ensuring the reliability and safety of large-scale storage systems.
Stringent Regulatory Standards for Battery Safety:
Regulatory bodies such as IEC, UL, and ISO mandate rigorous testing for batteries used in automotive, aerospace, medical, and consumer electronics applications. Compliance with these standards is essential to prevent product recalls and safety risks. For instance, the United Nations Economic Commission for Europe (UNECE) has established Regulation No. 100, which outlines specific requirements for the safety of electric power train vehicles. Manufacturers must invest in advanced testing equipment to detect defects, thermal runaway risks, and degradation issues before batteries reach the market. Increasing global regulations and stricter safety protocols are further compelling companies to upgrade their battery testing solutions.
Technological Advancements in Battery Testing Solutions:
AI-driven analytics, automation, and real-time monitoring are improving testing accuracy and efficiency. Predictive maintenance enabled by AI helps manufacturers identify potential battery failures early, while automated testing solutions reduce manual errors and increase testing throughput. For instance, the National Renewable Energy Laboratory (NREL) has developed an AI-powered battery management system that can predict battery degradation and optimize charging strategies. As battery technologies evolve, investments in state-of-the-art testing equipment are supporting advancements in solid-state batteries, fast-charging capabilities, and higher energy densities. These technological innovations are driving demand for sophisticated battery testing solutions across industries.
Market Trends:
Increased Adoption of AI and Automation in Battery Testing:
The integration of artificial intelligence (AI) and automation in battery testing is transforming the industry. AI-driven analytics enhance testing accuracy by predicting potential failures and optimizing performance assessments. Automated testing solutions reduce manual intervention, improving efficiency and ensuring consistent results. For instance, Tesla pairs its human engineers with AI software to analyze battery problems, optimize performance, and maintain battery health across all components. These advancements enable real-time monitoring of battery health, allowing manufacturers to detect defects early and enhance safety. As demand for high-performance batteries grows, AI-powered testing is becoming essential for ensuring reliability and regulatory compliance.
Growing Focus on Fast-Charging and High-Energy-Density Batteries:
With the increasing adoption of electric vehicles and portable electronics, there is a strong focus on developing fast-charging and high-energy-density batteries. These advancements require rigorous testing to ensure safety, performance, and longevity. Battery testing equipment manufacturers are introducing specialized solutions to evaluate thermal management, charge cycles, and degradation rates in next-generation batteries. For instance, StoreDot has developed extreme fast charging (XFC) battery cells that can deliver 100 miles of charge in just five minutes, with initial test results confirming their readiness for mass production in passenger cars by 2024. As industries prioritize energy efficiency and reduced charging times, the demand for advanced testing solutions continues to rise.
Expansion of Battery Recycling and Second-Life Applications:
The push for sustainability is driving the adoption of battery recycling and second-life applications. As lithium-ion batteries reach the end of their lifecycle, manufacturers and recycling companies are investing in testing equipment to assess battery health and determine reuse potential. Testing solutions play a crucial role in ensuring the safety and efficiency of repurposed batteries for secondary applications such as grid storage and backup power systems. For instance, Ziptrax collects used lithium batteries from electric vehicles and repurposes them for second-life applications such as energy storage, backup power, and microgrids, using a patented technology that can extend the life of lithium batteries by up to 4 times. This trend is gaining momentum as industries seek to minimize environmental impact and optimize battery life cycles.
Rising Investments in Solid-State Battery Development:
Solid-state batteries are emerging as a breakthrough technology, offering higher energy densities and improved safety over conventional lithium-ion batteries. However, these innovations require specialized testing methodologies to evaluate their performance under various conditions. Battery testing equipment providers are developing new solutions to address the unique challenges of solid-state battery testing. For instance, Mercedes-Benz has started testing a solid-state battery from partner Factorial Energy in a modified EQS this month, with the battery pack expected to offer a range of more than 620 miles (around 1,000 kilometers). As research and development in this field accelerate, the demand for advanced testing systems is expected to grow, shaping the future of the battery industry.
Market Challenges Analysis:
High Cost of Advanced Battery Testing Equipment:
One of the major challenges in the battery testing equipment market is the high cost associated with advanced testing solutions. As battery technologies evolve, testing requirements become more complex, necessitating sophisticated equipment with enhanced accuracy, automation, and real-time monitoring capabilities. These advanced systems require significant investment, making it difficult for small and medium-sized enterprises to adopt high-end testing solutions. Additionally, the cost of maintaining and upgrading battery testing infrastructure adds to operational expenses. Companies must allocate substantial resources to ensure compliance with stringent industry regulations and performance standards, further increasing financial burdens. The high cost of ownership often leads manufacturers to rely on outsourced testing services, limiting their control over quality assurance and testing efficiency. As demand for high-performance batteries rises, the financial burden of testing infrastructure remains a major barrier for new market entrants. Moreover, long return-on-investment periods deter companies from upgrading their testing capabilities despite technological advancements.
Complexity of Evolving Battery Technologies and Standards:
The rapid evolution of battery technologies presents a challenge for testing equipment manufacturers to keep pace with industry advancements. New battery chemistries, such as solid-state batteries, lithium-sulfur, and sodium-ion batteries, require specialized testing methodologies that differ from traditional lithium-ion batteries. Developing testing solutions that accommodate diverse battery types while maintaining accuracy and efficiency is a complex task. Additionally, frequent updates in regulatory standards and safety requirements across different industries and regions create compliance challenges. Manufacturers must continuously upgrade their testing protocols to meet new guidelines, increasing R&D costs and time-to-market delays. The lack of standardized global testing frameworks further complicates testing processes, requiring companies to adapt to multiple certification requirements, which adds to operational inefficiencies. As battery innovation accelerates, testing methodologies must evolve rapidly to ensure product reliability and safety. Furthermore, the absence of uniform global standards increases compliance costs and slows down the adoption of emerging battery technologies.
Market Opportunities:
The battery testing equipment market presents significant growth opportunities driven by the increasing demand for advanced battery technologies across multiple industries. The rapid expansion of the electric vehicle sector, coupled with government incentives and investments in sustainable energy solutions, is creating a strong need for reliable battery testing solutions. As automakers and battery manufacturers focus on enhancing energy density, safety, and charging efficiency, there is a rising demand for innovative testing equipment that can assess battery performance under various conditions. Additionally, the growing adoption of grid-scale energy storage solutions, particularly in renewable energy projects, is further boosting the need for high-precision battery testing systems. Companies that develop cost-effective, automated, and AI-powered testing solutions will be well-positioned to capitalize on this growing market.
Another key opportunity lies in the increasing focus on battery recycling and second-life applications. With the surge in battery usage, particularly lithium-ion batteries, the need for sustainable recycling solutions is becoming critical. Battery testing equipment plays a vital role in assessing the health and viability of used batteries, enabling their reuse in less demanding applications such as energy storage and backup power systems. Furthermore, advancements in next-generation battery technologies, including solid-state and sodium-ion batteries, present a growing demand for specialized testing solutions. As industries continue to innovate and regulatory bodies enforce stricter safety and performance standards, companies investing in adaptable and scalable battery testing technologies will gain a competitive edge in the evolving market landscape.
Market Segmentation Analysis:
By Equipment Type
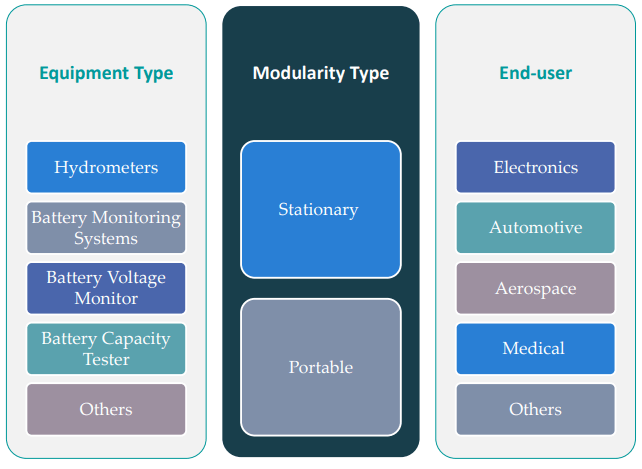
The battery testing equipment market is segmented into hydrometers, battery monitoring systems, battery voltage monitors, battery capacity testers, and others. Hydrometers are primarily used for testing lead-acid batteries by measuring the specific gravity of the electrolyte, ensuring proper charge levels and efficiency. Battery monitoring systems (BMS) provide real-time analysis of battery health, temperature, and performance, making them essential for industries relying on continuous power supply. Battery voltage monitors help in detecting voltage fluctuations and identifying potential failures in batteries, enhancing their reliability in critical applications. Battery capacity testers are used to evaluate the energy storage capabilities of batteries under different load conditions, ensuring optimal performance and safety. The others category includes advanced diagnostic tools and software-based solutions that offer predictive maintenance and analytics for battery systems.
By Modularity Type
Based on modularity, the market is divided into stationary and portable battery testing equipment. Stationary battery testing equipment is commonly used in industrial and laboratory settings where detailed and precise analysis of battery performance is required. These systems are typically integrated into large-scale testing facilities in automotive, aerospace, and medical industries. Portable battery testing equipment, on the other hand, is gaining popularity due to its convenience and ease of use in field applications. These devices are widely used by technicians and engineers for on-site battery diagnostics in automotive workshops, electronic device manufacturing, and maintenance services.
By End-user
The end-user segment consists of electronics, automotive, aerospace, medical, and others. The electronics sector is a key consumer of battery testing equipment due to the rising demand for high-performance batteries in consumer devices such as smartphones, laptops, and wearables. The automotive industry extensively uses battery testing tools to assess the efficiency of electric vehicle (EV) and hybrid vehicle batteries, ensuring compliance with safety standards. In the aerospace sector, battery testing equipment is critical for maintaining the reliability of power sources in aircraft systems, satellites, and unmanned aerial vehicles (UAVs). The medical industry utilizes battery testing tools to ensure the safety and longevity of battery-operated medical devices, including pacemakers, defibrillators, and portable diagnostic equipment. The others segment covers industrial applications, including power grid storage solutions and renewable energy battery systems, where battery testing is essential for optimizing energy storage efficiency.
Segmentations:
By Equipment Type
- Hydrometers
- Battery Monitoring Systems
- Battery Voltage Monitor
- Battery Capacity Tester
- Others
By Modularity Type
- Stationary
- Portable
By End-user
- Electronics
- Automotive
- Aerospace
- Medical
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific
Asia-Pacific holds the largest market share of 45% in the battery testing equipment market, driven by the strong presence of battery manufacturers, rapid adoption of electric vehicles, and advancements in energy storage technologies. Countries such as China, Japan, and South Korea dominate battery production and innovation, fostering demand for advanced testing solutions. Government initiatives promoting electric mobility and renewable energy storage systems further accelerate market growth in the region. China’s leadership in lithium-ion battery manufacturing and supply chain dominance reinforces its demand for high-precision testing equipment. Additionally, investments in solid-state battery research and expanding EV charging infrastructure contribute to the region's market expansion. As consumer electronics production continues to grow, the demand for efficient battery testing equipment remains strong. The emergence of domestic battery startups and partnerships with global technology firms is further driving innovation in testing methodologies across the region.
North America
North America accounts for 25% of the battery testing equipment market, driven by the increasing adoption of electric vehicles, strong regulatory frameworks, and investments in advanced energy storage solutions. The United States leads the region in R&D efforts, particularly in next-generation battery technologies such as solid-state and lithium-sulfur batteries. The region’s focus on stringent battery safety standards and compliance testing enhances demand for specialized testing equipment. The presence of major EV manufacturers, including Tesla, and large-scale renewable energy projects further boost market expansion. Additionally, growing government support through funding initiatives for sustainable energy solutions and the push for domestic battery production strengthen North America's position in the market. The rise of battery recycling programs and second-life applications in North America is further increasing the need for reliable and precise battery testing solutions.
Europe
Europe holds a 20% market share in the battery testing equipment market, supported by the rapid electrification of the automotive sector and strict environmental regulations. The European Union’s commitment to reducing carbon emissions has led to significant investments in battery research, production, and testing infrastructure. Germany, France, and the United Kingdom are key contributors, with strong government incentives driving EV adoption and energy storage deployments. The establishment of large-scale battery manufacturing plants, such as gigafactories, is increasing the demand for reliable testing solutions to ensure quality and safety compliance. Furthermore, the focus on sustainable battery recycling initiatives and second-life applications is creating additional opportunities for testing equipment manufacturers. As battery innovation accelerates in Europe, the demand for advanced testing solutions is expected to rise.
Key Player Analysis:
- CellMax Technologies
- WonATech
- Yangzhou Chengye Test Equipment Co., Ltd
- Bitrode Corporation
- Neware
- HIOKI E.E. CORPORATION
- NOVONIX
- AMETEK Land
- ARBIN Instruments
- Maccor
- Eltek
- Ivium Technologies
Competitive Analysis:
The battery testing equipment market is highly competitive, with key players focusing on innovation, automation, and high-precision testing solutions to strengthen their market position. Leading companies invest in research and development to enhance battery testing capabilities, ensuring compliance with evolving industry standards and safety regulations. For instance, Neware offers the CT/CTE-8000 Simulation Testing System, which is based on their fifth-generation testing system and is capable of performing various tests such as cycle life, rate charging/discharging, pulse simulation, and HPPC. The market is characterized by the presence of global and regional players offering a wide range of testing solutions, from basic performance evaluation to advanced AI-driven diagnostics. Strategic partnerships, mergers, and acquisitions are common as companies seek to expand their technological capabilities and global reach. Increasing demand for electric vehicles, energy storage, and consumer electronics is driving competition among manufacturers to offer cost-effective and efficient testing solutions. Additionally, companies are integrating cloud-based analytics and real-time monitoring features to enhance testing accuracy and efficiency, gaining a competitive edge in the evolving market landscape.
Recent Developments:
- In February 2024, HIOKI E.E. CORPORATION announced the release of the LR8102 (high-function model) and LR8101 (basic-function model) voltage and temperature data loggers. These new data loggers are equipped with insulation performance up to DC 1,500 V and are designed for integration into EV battery testing systems including charge/discharge testers.
- In March 2024, Bitrode Corporation appointed Pierre-Jean Arvers as the new CEO, signaling a strategic move to strengthen its position in the energy storage and battery testing solutions market.
- In November 2024, Neware introduced advanced Battery Testing Systems designed to evaluate various parameters of battery cells, ensuring they meet the highest standards of performance and safety for electric vehicles (EVs).
- In September 2023, NOVONIX announced a collaboration with SandboxAQ to predict the lifespan of lithium-ion batteries. This partnership combines SandboxAQ's AI-driven chemical simulation software with NOVONIX's Ultra-High Precision Coulometry (UHPC) technology and extensive battery cell prototyping and testing capabilities.
Market Concentration & Characteristics:
The battery testing equipment market exhibits a moderate to high market concentration, with a mix of established global players and emerging regional manufacturers competing to provide advanced testing solutions. Leading companies focus on innovation, automation, and AI integration to enhance testing accuracy, efficiency, and compliance with evolving safety regulations. The market is characterized by technological advancements, stringent regulatory requirements, and increasing investments in battery research and development across industries such as automotive, energy storage, and consumer electronics. As the demand for high-performance batteries rises, manufacturers emphasize precision testing, real-time monitoring, and cloud-based analytics to improve product reliability. Strategic collaborations, mergers, and acquisitions are shaping the competitive landscape, with companies expanding their portfolios to cater to solid-state, lithium-sulfur, and second-life battery applications. The industry is also witnessing a shift toward cost-effective and high-speed testing solutions, enabling faster battery certification and commercialization.
Report Coverage:
The research report offers an in-depth analysis based on Battery Type, Test Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for battery testing equipment will continue to rise as industries prioritize safety, efficiency, and performance in next-generation battery technologies.
- Advancements in artificial intelligence and automation will enhance battery testing accuracy, enabling predictive maintenance and real-time performance monitoring.
- The growing adoption of electric vehicles will drive the need for high-precision testing solutions to support fast-charging capabilities and extended battery life.
- Increased investments in solid-state and alternative battery chemistries will create opportunities for specialized testing equipment tailored to emerging technologies.
- The expansion of renewable energy storage systems will fuel demand for advanced battery testing solutions to ensure long-term stability and reliability.
- Strict government regulations and industry standards will compel manufacturers to upgrade their testing infrastructure to meet evolving safety and performance requirements.
- Battery recycling and second-life applications will boost the need for testing solutions that assess used battery health and determine their viability for reuse.
- The shift toward high-speed and cost-efficient battery testing will accelerate, reducing certification time and improving production scalability.
- Strategic collaborations and mergers among battery testing equipment providers and battery manufacturers will drive innovation and market expansion.
- The rise of cloud-based and remote battery testing capabilities will enable enhanced data analysis, improving overall battery lifecycle management.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Electric Vehicles (EVs)
The global shift toward electric mobility, supported by government incentives and emission regulations, is driving automakers to invest in advanced battery technologies. This increases the need for battery testing equipment to ensure safety, efficiency, and compliance with regulatory standards in EV batteries.
Growing Deployment of Renewable Energy Storage Systems
The integration of renewable energy sources such as solar and wind into power grids requires reliable energy storage solutions. Battery testing equipment is essential for monitoring and assessing the performance and safety of large-scale energy storage projects, supporting the expansion of renewables.
Stringent Regulatory Standards for Battery Safety
International and regional regulatory bodies mandate rigorous testing for batteries used in automotive, aerospace, medical, and consumer electronics applications. Compliance with these standards compels manufacturers to invest in high-precision battery testing equipment to prevent safety risks and product recalls.
Technological Advancements in Battery Testing Solutions
Innovations such as AI-driven analytics, automation, and real-time monitoring are enhancing the accuracy and efficiency of battery testing. As battery chemistries evolve, advanced testing equipment is required to support new technologies like solid-state and fast-charging batteries.
Expansion of Battery Recycling and Second-Life Applications
The push for sustainability and circular economy practices is increasing the need for battery testing equipment to assess the health and viability of used batteries. This supports battery recycling and second-life applications, such as grid storage and backup power, further driving demand for testing solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the battery testing equipment market?
Which region dominates the battery testing equipment market?
How does battery recycling impact the market?
What role do government regulations play in market expansion?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 Electronics
- 1.2.2 Automotive
- 1.2.3 Aerospace
- 1.2.4 Medical
- 1.2.5 Others
- 1.3 By Equipment Type
- 1.3.1 Hydrometers
- 1.3.2 Battery Monitoring Systems
- 1.3.3 Battery Voltage Monitor
- 1.3.4 Battery Capacity Tester
- 1.3.5 Others
- 1.4 By Modularity Type
- 1.4.1 Stationary
- 1.4.2 Portable
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 595.7 million → 2032: USD 847.14 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Battery Testing Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Battery Testing Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Battery Testing Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Battery Testing Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Battery Testing Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Battery Testing Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Battery Testing Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Battery Testing Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 595.7 million → 2032: USD 847.14 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Battery Testing Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Electronics
- 12.3.7.2 Automotive
- 12.3.7.3 Aerospace
- 12.3.7.4 Medical
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Equipment Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hydrometers
- 12.4.7.2 Battery Monitoring Systems
- 12.4.7.3 Battery Voltage Monitor
- 12.4.7.4 Battery Capacity Tester
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Modularity Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Stationary
- 12.5.7.2 Portable
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Battery Testing Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Battery Testing Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Battery Testing Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Battery Testing Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 CellMax Technologies
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 WonATech
- 18.4 Yangzhou Chengye Test Equipment Co., Ltd
- 18.5 Bitrode Corporation
- 18.6 Neware
- 18.7 HIOKI E.E. CORPORATION
- 18.8 NOVONIX
- 18.9 AMETEK Land
- 18.10 ARBIN Instruments
- 18.11 Maccor
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

