
Bio Lubricants Market Overview:
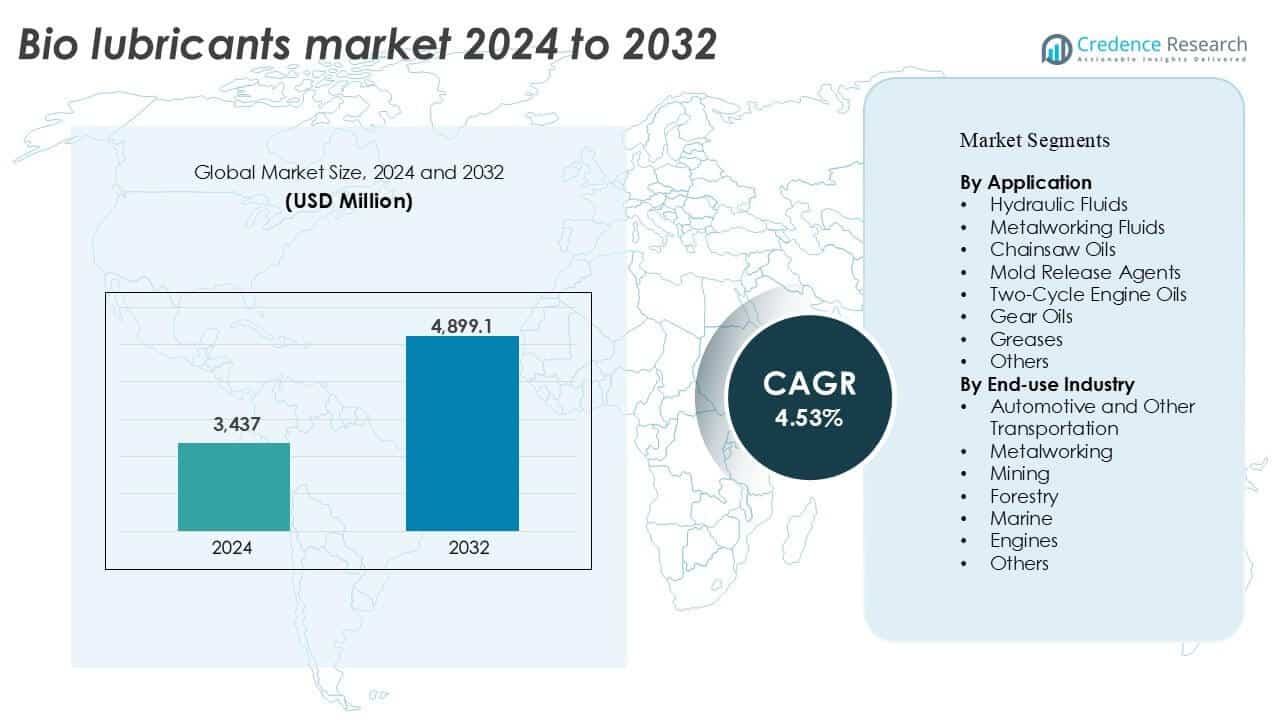
The Bio Lubricants Market size was valued at USD 3,437 million in 2024 and is anticipated to reach USD 4,899.1 million by 2032, at a CAGR of 4.53% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Bio Lubricants Market Size 2024 | USD 3,437 million |
| Bio Lubricants Market, CAGR | 4.53% |
| Bio Lubricants Market Size 2032 | USD 4,899.1 million |
Bio Lubricants Market Insights
- Environmental regulations and demand for biodegradable lubricants in sensitive areas drive market expansion across industrial and automotive sectors.
- Leading players like Shell, bp, Total, and Cargill are investing in high-performance formulations, while innovation in synthetic esters supports broader adoption across gear oils and hydraulic fluids.
- High production costs and limited user awareness, especially in developing regions, remain key restraints despite growing sustainability mandates.
- North America leads with a 35% market share, followed by Europe at 30%, while Asia-Pacific is the fastest-growing region. Hydraulic fluids dominate the application segment with 32% share, and the automotive and transportation sector leads end-use industries with over 35% share.
Bio Lubricants Market Segmentation Analysis:
By Application:
Hydraulic fluids dominated the bio lubricants market in 2024, accounting for over 32% of the total share. Their widespread use in mobile and stationary equipment across industries such as construction, agriculture, and manufacturing drives this dominance. Bio-based hydraulic fluids offer high biodegradability and low toxicity, making them suitable for environmentally sensitive areas. Rising regulatory pressure to replace mineral oils in hydraulic systems supports segment growth. Metalworking fluids also show steady adoption, driven by demand in machining operations. Greases and gear oils contribute to niche applications where high performance and reduced environmental impact are required. Chainsaw oils, mold release agents, and two-cycle engine oils collectively represent a moderate market share. Chainsaw oils are favored in forestry and logging, where spill risk is high and biodegradable options are preferred. Mold release agents find applications in plastics and die casting, where clean separation and lower emissions are essential. Two-cycle engine oils gain ground in small engines for lawn equipment and marine use, especially where water contamination risks exist. Growth in these segments remains tied to environmental safety and regulatory standards.
- For instance, TotalEnergies supplies its BIOHYDRAN range, which is classified as 'readily biodegradable' by achieving over 95% biodegradation within the standard 28-day window of the OECD 301B test.
By End-use Industry:
The automotive and other transportation segment led the bio lubricants market with more than 35% share in 2024. This dominance stems from increasing demand for eco-friendly lubricants in vehicle engines, transmissions, and hydraulic systems. OEMs and fleet operators prefer bio lubricants to meet sustainability targets and reduce environmental impact. The marine industry follows closely due to strict discharge regulations and the need for water-safe lubricants. Vessels operating in inland and coastal waters are increasingly using biodegradable oils to comply with IMO and EPA guidelines. The metalworking sector contributes steadily, driven by the need for safer workplace fluids and reduced waste disposal costs. Mining and forestry industries also show rising demand due to operations in environmentally sensitive zones. Bio lubricants reduce soil and water contamination risk during heavy machinery use.
- For instance, Fuchs delivered more than 60,000 metric tons of biodegradable lubricants for automotive, marine, and industrial users in 2023.
Key Growth Drivers
Rising Environmental Regulations and Sustainability Mandates
Strict environmental regulations strongly drive the bio lubricants market. Governments limit mineral oil use due to soil and water risks. Industries operating near forests, water bodies, and farms face tighter discharge rules. Bio lubricants offer high biodegradability and low toxicity benefits. These features support compliance with environmental laws. Regulatory bodies in Europe and North America enforce eco-label standards. Such rules push users toward plant-based and synthetic ester lubricants. Public sector projects increasingly mandate biodegradable lubricants. Corporate sustainability goals also influence procurement decisions. Large manufacturers commit to lower carbon footprints. Bio lubricants help meet ESG and reporting targets. The shift supports long-term adoption across industries.
- For instance, European Commission enforces the EU Ecolabel for lubricants under Decision 2018/1702, requiring strict biodegradability and toxicity thresholds.
Expanding Use in Automotive and Industrial Equipment
Growing equipment fleets raise lubricant consumption across sectors. Automotive, construction, and industrial machinery rely on hydraulic and gear oils. Bio lubricants match performance needs in many applications. Advances improve oxidation stability and temperature resistance. Equipment makers now approve bio-based formulations. Fleet operators adopt them to reduce spill liability. Industrial plants prefer safer fluids for worker protection. Mining and forestry equipment benefits from reduced environmental damage. Longer oil drain intervals also attract users. Maintenance costs decline with improved lubricant quality. These factors support steady demand growth across end-use industries.
- For instance, Shell supplies PANOLIN and Naturelle bio-lubricants approved for hydraulic systems operating up to 120 °C. These products are deployed in construction and industrial fleets to reduce spill risk and extend oil drain intervals.
Volatility in Crude Oil Prices and Resource Security
Crude oil price volatility affects mineral lubricant costs. Bio lubricants rely on renewable feedstocks like vegetable oils. This reduces exposure to fossil fuel price swings. Countries also seek energy and material security. Local bio-based production supports domestic supply chains. Agricultural feedstocks create value for farming economies. Long-term supply contracts improve pricing stability. Manufacturers gain better cost planning visibility. Industries favor predictable input costs. This economic advantage supports bio lubricant adoption over conventional oils.
Key Trend & Opportunities
Technological Advancements in Bio-based Formulations
Innovation improves bio lubricant performance and reliability. New ester chemistries enhance thermal and oxidative stability. Additive technology boosts wear and corrosion protection. These gains expand use in high-load applications. Bio lubricants now suit heavy-duty engines and gears. Performance parity with mineral oils removes adoption barriers. Research focuses on longer service life and lower costs. Improved formulations attract conservative industrial users. This trend opens opportunities in premium equipment segments.
- For instance, Klüber Lubrication developed synthetic ester-based gear oils tested for continuous operation at 150 °C in industrial gearboxes.
Growth in Marine and Environmentally Sensitive Applications
Marine and offshore sectors favor biodegradable lubricants. Strict discharge norms drive demand in waterways. Ports and shipping operators face compliance pressure. Bio lubricants reduce pollution risks during leaks. Inland water transport also adopts green lubricants. Forestry and agriculture show similar trends. Equipment operates directly on land and water. Eco-friendly lubricants reduce cleanup and liability costs. These sectors present strong long-term opportunities.
Key Challenges
Higher Cost Compared to Conventional Lubricants
Bio lubricants often cost more than mineral-based products. Feedstock prices fluctuate due to crop supply and climate factors. Processing and additive costs remain high. Small users hesitate due to upfront expenses. Price sensitivity limits adoption in cost-driven markets. Lack of scale affects manufacturing efficiency. Some users still focus on short-term cost savings. This challenge slows penetration in developing regions.
Performance Perception and Limited Awareness
Some users question bio lubricant performance reliability. Concerns remain around cold flow and oxidation resistance. Older formulations created negative perceptions. Limited technical awareness hinders adoption. Small operators lack knowledge of lifecycle benefits. OEM approvals remain limited in certain equipment types. Education and demonstration programs are still needed. Overcoming perception gaps remains a key market challenge.
Regional Analysis
North America
North America held the largest share in the bio lubricants market, accounting for over 35% in 2024. The region benefits from strict environmental regulations by the EPA and strong demand across transportation and industrial sectors. The United States dominates due to advanced manufacturing, growing use in marine and forestry equipment, and government mandates promoting biodegradability. Bio-based product innovation and OEM approvals further support adoption. The region’s high awareness of sustainability and established supply chains ensure continued growth. Canada and Mexico are also adopting bio lubricants, driven by regulatory alignment and increasing demand in energy and mining sectors.
Europe
Europe accounted for nearly 30% of the global bio lubricants market share in 2024. Countries such as Germany, France, and the Netherlands lead adoption, supported by EU directives promoting green products and circular economy goals. The region’s automotive industry integrates bio lubricants in fleets to meet emission and waste targets. Germany’s industrial and machinery sector heavily favors bio-based hydraulic fluids. Strict REACH and EcoLabel compliance further accelerates usage. Supportive policies, public-private partnerships, and sustainability funding drive research and product rollouts. The market benefits from strong environmental awareness among consumers and industrial users alike.
Asia-Pacific
Asia-Pacific held around 20% share in the bio lubricants market in 2024, with strong growth expected through 2032. China, Japan, and India are key contributors due to expanding construction, manufacturing, and transportation sectors. Government-led sustainability initiatives and industrial modernization in China and India support bio lubricant use. Japan’s strong automotive sector adopts green fluids to meet efficiency standards. Rapid urbanization and rising equipment use in ASEAN countries create new demand. However, cost sensitivity and limited awareness in rural markets slightly restrain wider adoption. Growing environmental regulations and foreign investments in bio-based technologies offer long-term potential.
Latin America
Latin America contributed about 8% of the global bio lubricants market in 2024. Brazil dominates the regional market due to its large agriculture and forestry sectors, where spill-safe lubricants are critical. Argentina and Chile show growing demand from mining and transport industries. Regional adoption is supported by rising awareness of environmental impacts and the availability of vegetable oil feedstocks. Government policies are gradually shifting toward eco-friendly practices. However, limited R&D and high cost barriers affect broader penetration. As sustainability policies strengthen, the market is likely to see gradual expansion across both public and private sectors.
Middle East & Africa (MEA)
The Middle East & Africa held the smallest share at around 7% in 2024 but is emerging with notable growth prospects. In the Middle East, demand is rising in oil & gas and marine operations, where equipment reliability and spill risk reduction are key. South Africa and Gulf nations are exploring biodegradable fluids for environmental protection and global compliance. The region faces challenges such as low awareness, limited local production, and cost concerns. However, growing industrialization and international environmental agreements are creating space for bio lubricant pilot programs, especially in mining, logistics, and power generation sectors.
Bio Lubricants Market Segmentations:
By Application:
- Hydraulic Fluids
- Metalworking Fluids
- Chainsaw Oils
- Mold Release Agents
- Two-Cycle Engine Oils
- Gear Oils
- Greases
- Others
By End-use Industry:
- Automotive and Other Transportation
- Metalworking
- Mining
- Forestry
- Marine
- Engines
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the bio lubricants market features a mix of global oil giants, specialty manufacturers, and bio-based innovators. Leading players such as Shell, Exxon Mobil, bp, and Total leverage their wide distribution networks and R&D capabilities to offer bio-based alternatives alongside conventional products. Companies like FUCHS, PANOLIN AG, and Klüber Lubrication focus on performance-driven formulations for industrial and transport sectors. U.S.-based firms including Cargill, Novvi, and Environmental Lubricants Manufacturing emphasize renewable feedstocks and OEM collaborations. European brands such as BECHEM, Axel Christiernsson, and Repsol target niche applications with advanced esters and high biodegradability. Players compete on product performance, regulatory compliance, and cost-efficiency. Strategic partnerships, sustainable sourcing, and certification (e.g., EU Ecolabel, USDA BioPreferred) remain critical for market positioning. With growing regulatory support and end-user awareness, companies are expanding portfolios to address specific sectoral needs from automotive to marine while investing in local production and sustainable supply chains.
Key Player Analysis
- IGOL (Norway)
- Total (France)
- Novvi, LLC. (U.S.)
- Axel Christiernsson (Sweden)
- Cargill (U.S.)
- Repsol (Spain)
- LanoPro (Norway)
- Klüber Lubrication (Germany)
- Environmental Lubricants Manufacturing, Inc. (U.S.)
- PANOLIN AG (Switzerland)
- Emery Oleochemicals (Malaysia)
- bp p.l.c. (U.K.)
- BECHEM (Germany)
- Cortec Corporation (U.S.)
- FUCHS (Germany)
- Shell (Netherlands)
- Exxon Mobil Corporation (U.S.)
Recent Developments
- In February 2024, Kraton introduced a new product line, SylvaSolve, which consists of bio-based oils. This product line is designed for various industrial applications, including coatings, adhesives, and personal care products. SylvaSolve oils are derived from renewable sources and offer a more sustainable alternative to traditional petroleum-based products. The company aims to meet the growing demand for eco-friendly solutions while supporting customers' sustainability goals.
- In April 2023, Exxon Mobil planned to invest USD 110 million in a lubricant production facility in India, which is expected to begin operations by the end of 2025. The plant aims for a production capacity of up to 159 million liters of lubricants annually, catering to the growing demand across various sectors, such as manufacturing, steel, power, mining, and construction, as well as the commercial and passenger vehicle industries.
- In July 2022, Chevron Corporation launched a new synthetic grease that complies with the 2013 Vessel General Permit regulations for environmentally acceptable lubricants. This biodegradable product is versatile and exhibits optimal flow characteristics, making it compatible with various sectors. It represents a promising development in sustainable lubricants and is an optimal choice for modern centralized lubrication systems.
Report Coverage
The research report offers an in-depth analysis based on Application, End-use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Bio lubricants demand will grow as regulations favor biodegradable and non-toxic alternatives across sectors.
- Automotive and transport industries will lead adoption due to emission goals and green procurement policies.
- Synthetic esters and advanced base stocks will expand performance range across extreme temperatures and loads.
- Major players will scale bio-based portfolios to match mineral oil standards across industrial and marine uses.
- OEM approvals and technical support will be key for wider adoption across equipment and engine manufacturers.
- North America will maintain dominance, while Asia-Pacific will show highest growth due to industrial expansion.
- Hydraulic fluids and gear oils will remain leading applications, supported by steady demand in heavy machinery.
- High product costs and limited local manufacturing will challenge growth in price-sensitive regions.
- Awareness programs and policy incentives will bridge the adoption gap in emerging markets.
- Partnerships across agri-feedstock suppliers and refiners will ensure sustainable and scalable production chains.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Bio lubricants market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Bio lubricants market projected to grow between 2024 and 2032?
Which Bio lubricants market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Bio lubricants market?
Who are the leading companies in the Bio lubricants market?
Which region commanded the largest share of the Bio lubricants market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,437 million → 2032: USD 4,899.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Bio-Lubricant Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Bio-Lubricant Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Bio-Lubricant Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Bio-Lubricant Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Bio-Lubricant Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Bio-Lubricant Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Bio-Lubricant Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Bio-Lubricant Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,437 million → 2032: USD 4,899.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Bio-Lubricant Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Bio-Lubricant Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Bio-Lubricant Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Bio-Lubricant Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

