
Market Overview:
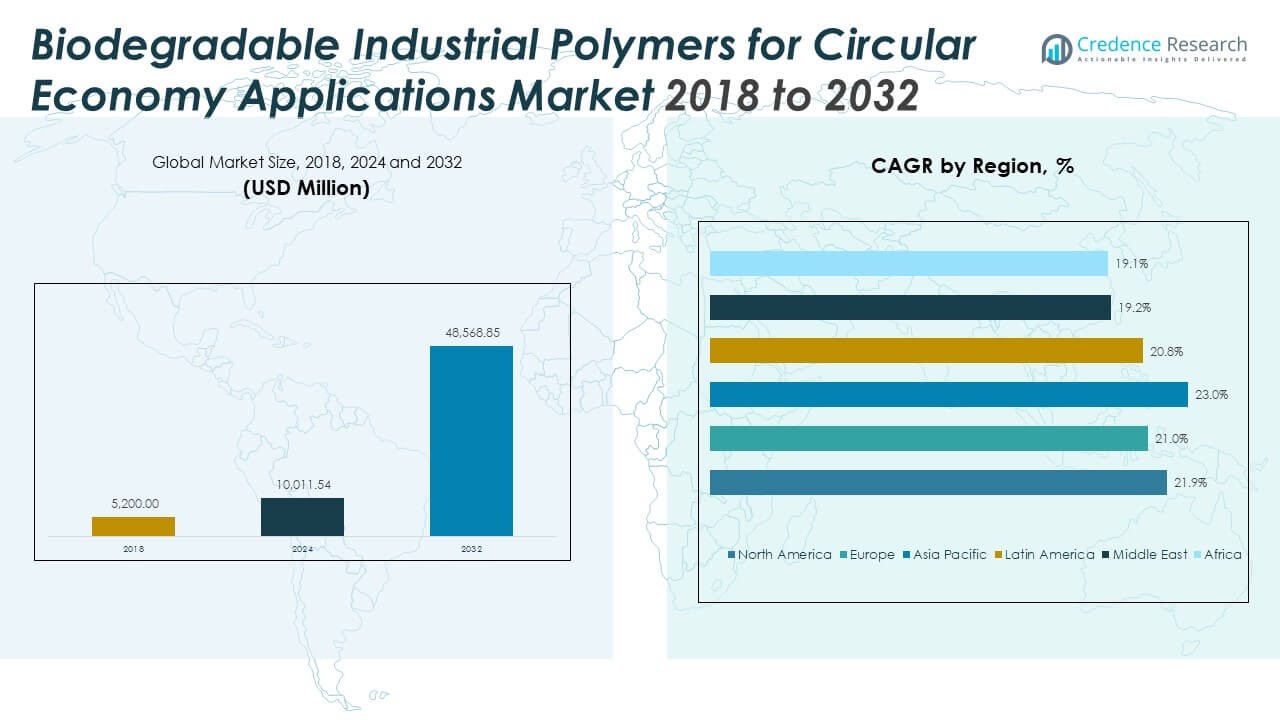
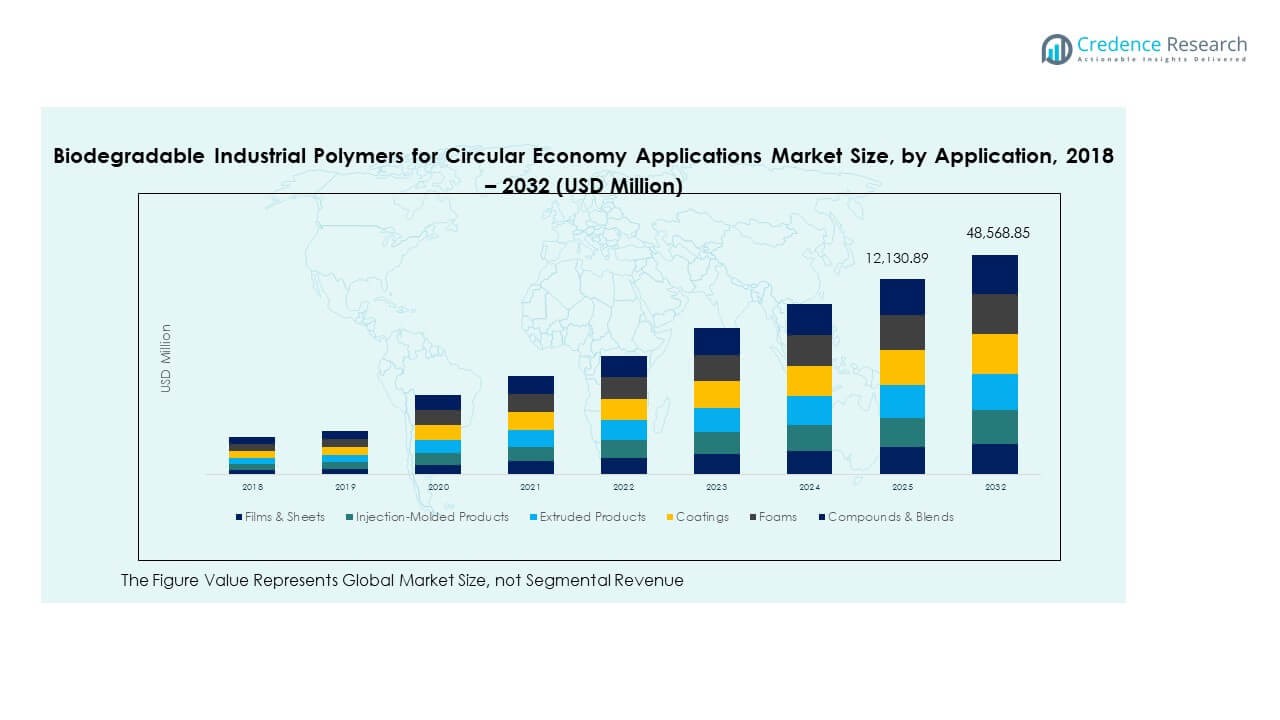
The Biodegradable Industrial Polymers for Circular Economy Applications Market size was valued at USD 5,200.00 million in 2018 to USD 10,011.54 million in 2024 and is anticipated to reach USD 48,568.85 million by 2032, at a CAGR of 21.92% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Biodegradable Industrial Polymers for Circular Economy Applications Market Size 2024 | USD 10,011.54 Million |
| Biodegradable Industrial Polymers for Circular Economy Applications Market, CAGR | 21.92% |
| Biodegradable Industrial Polymers for Circular Economy Applications Market Size 2032 | USD 48,568.85 Million |
Growing environmental awareness and strict government regulations against single-use plastics drive strong adoption of biodegradable polymers. Industries invest in sustainable materials that support closed-loop production systems. The market gains momentum from advances in biopolymer technology, improved compostability standards, and expanding demand from packaging, agriculture, and consumer goods sectors. Manufacturers focus on optimizing feedstock sources such as starch, cellulose, and sugarcane to improve cost efficiency and scalability. Rising corporate sustainability goals and product innovation sustain long-term growth.
Asia Pacific leads the market due to strong manufacturing capacity, favorable policies, and rapid industrial expansion across China, India, and Japan. Europe follows closely with robust regulatory frameworks and high consumer awareness of eco-friendly materials. North America maintains significant demand driven by advanced recycling infrastructure and corporate sustainability initiatives. Emerging markets in Latin America, the Middle East, and Africa show gradual adoption supported by rising environmental reforms and new bio-based production facilities.
Market Insights:
- The Biodegradable Industrial Polymers for Circular Economy Applications Market was valued at USD 5,200.00 million in 2018, reached USD 10,011.54 million in 2024, and is projected to attain USD 48,568.85 million by 2032, growing at a CAGR of 21.92%.
- Asia Pacific leads with 42.5% share due to its strong manufacturing capacity, policy support, and expanding biopolymer production. North America follows with 27.3% share, supported by advanced R&D and recycling systems, while Europe accounts for 24.4% driven by strict environmental regulations and high consumer awareness.
- Asia Pacific remains the fastest-growing region, propelled by government plastic-reduction initiatives, industrial composting infrastructure, and low-cost feedstock access.
- Films & Sheets hold around 33% share, maintaining dominance due to extensive packaging and agriculture use.
- Compounds & Blends capture about 25% share, reflecting their growing role in performance optimization across consumer and industrial applications.
Market Drivers
Rising Regulatory Support for Sustainable Material Adoption
Government initiatives targeting single-use plastic reduction accelerate the shift toward biodegradable solutions. Global mandates on waste minimization and eco-friendly packaging standards encourage industries to transition to green polymers. The Biodegradable Industrial Polymers for Circular Economy Applications Market benefits from policies promoting compostable alternatives in packaging, agriculture, and manufacturing. Regulations in Europe and North America lead industrial buyers to adopt certified biodegradable materials. Producers integrate renewable feedstocks like starch, cellulose, and PLA to comply with emission and recycling goals. Strong public awareness and retailer commitments to zero-waste supply chains reinforce demand. Brands embrace eco-labeling to enhance market credibility. The regulatory push establishes a structured pathway for circular production systems.
- For instance, multiple U.S. states such as California, New York, and Washington have implemented stringent regulations requiring compostable packaging in food service and retail sectors effective through 2025.
Expansion of Corporate Sustainability Goals and Procurement Standards
Corporations align sustainability goals with global environmental frameworks such as the UN SDGs. Procurement departments prioritize biodegradable materials across product design, packaging, and supply logistics. The Biodegradable Industrial Polymers for Circular Economy Applications Market gains traction as industries replace petroleum-based plastics with renewable alternatives. Multinational brands expand pilot programs integrating biopolymers into consumer goods portfolios. Companies enhance lifecycle assessments to validate environmental performance and strengthen brand value. Biodegradable polymer suppliers form partnerships with FMCG and agriculture sectors to develop cost-efficient blends. These collaborations foster innovation in compostable solutions that meet large-scale commercial requirements. Expanding green procurement policies create consistent demand momentum.
- For instance, Procter & Gamble reported in its 2025 sustainability updates that about 80% of its packaging is now designed to be recyclable or reusable, progressing toward its 100% goal by 2030. The company incorporates sustainable materials, including biopolymers, in select product lines and remains a founding member of the Plant PET Technology Collaborative promoting plant-based PET innovation.
Advancements in Feedstock Diversification and Process Efficiency
Feedstock diversification enhances cost stability and scalability across biodegradable polymer production lines. Research institutions develop new catalysts and fermentation processes for higher yield and reduced waste. The Biodegradable Industrial Polymers for Circular Economy Applications Market benefits from continuous optimization in polymerization techniques. Technology integration allows conversion of agricultural residues into bio-based monomers. Firms deploy energy-efficient reactors to reduce operational costs. Industry players invest in automation and AI-driven process monitoring to enhance material quality. Sustainable sourcing strategies minimize raw material volatility across global supply chains. Expanding production capacity supports long-term adoption by mainstream manufacturers.
Growing Consumer Awareness and Market Penetration of Eco-Friendly Products
Consumers prioritize sustainability when selecting packaged goods and durable materials. Rising public concern over microplastic pollution drives preference for compostable alternatives. The Biodegradable Industrial Polymers for Circular Economy Applications Market experiences steady consumer-driven expansion. Companies invest in marketing that educates buyers about biodegradability and circular value. Retailers promote low-carbon products to differentiate in competitive markets. Social media campaigns amplify awareness of plastic-free lifestyles. Local startups introduce innovative biodegradable packaging and agricultural films. Increasing visibility of certified biodegradable products in retail channels encourages repeat adoption across sectors.
Market Trends
Integration of Circular Design and Closed-Loop Manufacturing Systems
Manufacturers integrate circular design principles to achieve material recapture and reuse efficiency. Production models evolve toward recycling infrastructure capable of handling industrial compostable materials. The Biodegradable Industrial Polymers for Circular Economy Applications Market aligns with circular manufacturing goals that emphasize waste elimination. Firms deploy digital tracking and labeling to trace polymer life cycles. Partnerships emerge to connect waste collection with recycling facilities. Packaging developers incorporate modular designs that simplify disassembly and recovery. Lifecycle extension programs ensure sustainable re-entry of materials into production. The integration of closed-loop systems transforms value chain economics.
- For instance, HP Inc. uses over 110 million pounds of recycled plastics, including ocean-bound plastics, in its production. Approximately 85% of HP's Original Ink Cartridges contain 4-75% post-consumer recycled content, and HP reuses over 1 million plastic bottles daily for ink cartridge manufacturing, demonstrating advanced circular design and closed-loop manufacturing systems with verified digital tracking of materials.
Shift Toward Smart Biopolymer Blends with Functional Additives
Material scientists enhance biopolymers through blending techniques that improve durability and processability. Smart additives provide heat resistance, moisture control, and performance stability. The Biodegradable Industrial Polymers for Circular Economy Applications Market adopts functionalized blends suited for varied industrial uses. Producers experiment with hybrid formulations to match conventional polymer strength while maintaining biodegradability. Demand grows for customized mechanical properties in high-load environments. Research accelerates to reduce brittleness in compostable plastics. Equipment retrofits enable efficient transition without large-scale capital replacement. Such hybrid materials extend usage in automotive, agriculture, and electronics sectors.
- For instance, BASF’s Ecoflex® biopolymer exhibits certified compostability and includes functional additives that improve heat resistance up to ~94 °C while maintaining biodegradability. The biomass-balanced Ecoflex® blend replaces fossil feedstock with renewable biomass, reducing product carbon footprint by 60%, without compromising performance or requiring changes in processing machinery.
Digitalization and Blockchain Adoption for Supply Chain Transparency
Manufacturers introduce blockchain platforms to track polymer origins, processing, and end-of-life status. Transparency boosts buyer confidence in sustainability claims and compliance verification. The Biodegradable Industrial Polymers for Circular Economy Applications Market integrates digital solutions to enhance traceability across multi-tier networks. Smart labeling provides real-time data on carbon footprint and composting compatibility. Blockchain systems support certification authorities in ensuring authenticity. Digitally connected ecosystems link recyclers, producers, and consumers. Data-driven accountability strengthens trust in circular material transitions. Firms gain competitive advantage through verified environmental performance.
Expansion of Bio-Based Material Research and Global Collaborations
Universities and technology consortia collaborate to develop next-generation biodegradable polymer platforms. Cross-industry alliances enable shared funding for advanced R&D. The Biodegradable Industrial Polymers for Circular Economy Applications Market benefits from rising patent activity and innovation clusters. Public-private initiatives encourage commercialization of scalable green polymers. Collaborative pilot plants demonstrate cost-efficient bioplastic manufacturing routes. Industry standards evolve to harmonize compostability criteria across regions. Knowledge transfer accelerates industrial adoption in developing nations. Global cooperation fosters faster evolution of material science for sustainability goals.
Market Challenges Analysis
High Production Costs and Limited Infrastructure for Waste Processing
Production costs remain a major obstacle due to expensive feedstocks and limited economies of scale. Manufacturers struggle to match price parity with petroleum-based alternatives. The Biodegradable Industrial Polymers for Circular Economy Applications Market faces restricted profitability where recycling and composting infrastructure is underdeveloped. Waste segregation inefficiencies reduce the recovery rate of biodegradable polymers. Industrial composting facilities are concentrated in few regions, hindering adoption elsewhere. Logistics and contamination risks complicate large-scale waste management. Companies invest in R&D to develop low-cost feedstocks and localized recycling hubs. Infrastructure investment remains crucial to support circular growth at scale.
Material Performance Constraints and Standardization Gaps Across Industries
Material performance inconsistencies limit acceptance in demanding applications. Some biodegradable polymers exhibit lower thermal or mechanical resistance compared to conventional plastics. The Biodegradable Industrial Polymers for Circular Economy Applications Market contends with limited global standards governing biodegradability testing. Unclear labeling and certification norms confuse consumers and manufacturers. Discrepancies in regulatory compliance create trade barriers across borders. Producers face challenges balancing biodegradability with long shelf life. R&D efforts target improved formulation stability and consistent degradation timelines. Addressing standardization and quality metrics remains essential for market maturity.
Market Opportunities
Emerging Industrial and Agricultural Applications Creating New Growth Avenues Biodegradable polymers find increasing use in mulch films, seed coatings, and industrial packaging. Demand for compostable films and containers from food processors and agriculture expands sharply. The Biodegradable Industrial Polymers for Circular Economy Applications Market stands to gain from customized polymer formulations targeting high-demand sectors. Governments fund initiatives promoting bio-based materials for agricultural modernization. Technological breakthroughs in controlled degradation support broader utility. Growth in biopolymer film manufacturing across Asia opens export potential. Companies develop polymer grades tailored for industrial 3D printing and automotive components.
Strategic Partnerships and Technology Investments Accelerating Market Penetration Major players collaborate with startups and research institutes to improve feedstock supply chains. Investors fund biopolymer startups focusing on cost reduction and performance enhancement. The Biodegradable Industrial Polymers for Circular Economy Applications Market leverages joint ventures to scale global production. Multinational corporations sign long-term procurement deals to ensure sustainable supply continuity. New processing facilities integrate renewable energy sources to improve efficiency. Partnerships between academia and industry advance testing protocols. These strategic collaborations drive faster adoption of biodegradable materials across global industries.
Market Segmentation Analysis:
The Biodegradable Industrial Polymers for Circular Economy Applications Market demonstrates balanced growth across diverse material categories and end-use domains.
By polymer type, Polylactic Acid (PLA) leads due to its wide use in packaging and consumer products, supported by large-scale industrial compostability and renewable feedstock availability. Polyhydroxyalkanoates (PHA) gain traction through superior biodegradation under soil and marine conditions. Polybutylene Succinate (PBS) and PBAT exhibit rising adoption in flexible packaging for their mechanical strength and ease of blending. Emerging categories such as Polycaprolactone (PCL), starch-based blends, and cellulose derivatives enhance market depth with strong performance in coatings and biomedical films.
- For instance, NatureWorks, a leading PLA producer, manufactures Ingeo PLA which is certified for industrial compostability. Their PLA is used widely in packaging films, injection, and fiber applications, with production capacities exceeding 150,000 tons annually attributes confirmed by company sustainability reports and third-party certifications.
By application, films and sheets dominate owing to extensive use in agriculture mulch films and food packaging. Injection-molded and extruded products show steady progress driven by automotive and construction uses. Fibers, foams, and coatings gain interest for sustainable textiles and protective layers, while compounds and blends enable functional versatility across industries.
By end-use, packaging remains the prime segment, followed by agriculture and medical applications, reflecting the sustainability transition across key manufacturing chains.
By degradation type, industrial compostable polymers account for the largest share, supported by certification frameworks and processing infrastructure. Home compostable and soil biodegradable variants witness growth from consumer-facing product lines.
- For instance, Danimer Scientific PHA is undergoing trials and certifications for home compostability with documented biodegradation within six months in typical home compost conditions, information published in company sustainability reports and independent certifications.
By feedstock, corn/starch and sugarcane remain key inputs, while biomass waste and synthetic biodegradable polyesters expand their footprint due to circular material recovery initiatives. The integration of renewable inputs reinforces alignment with global circular economy principles.
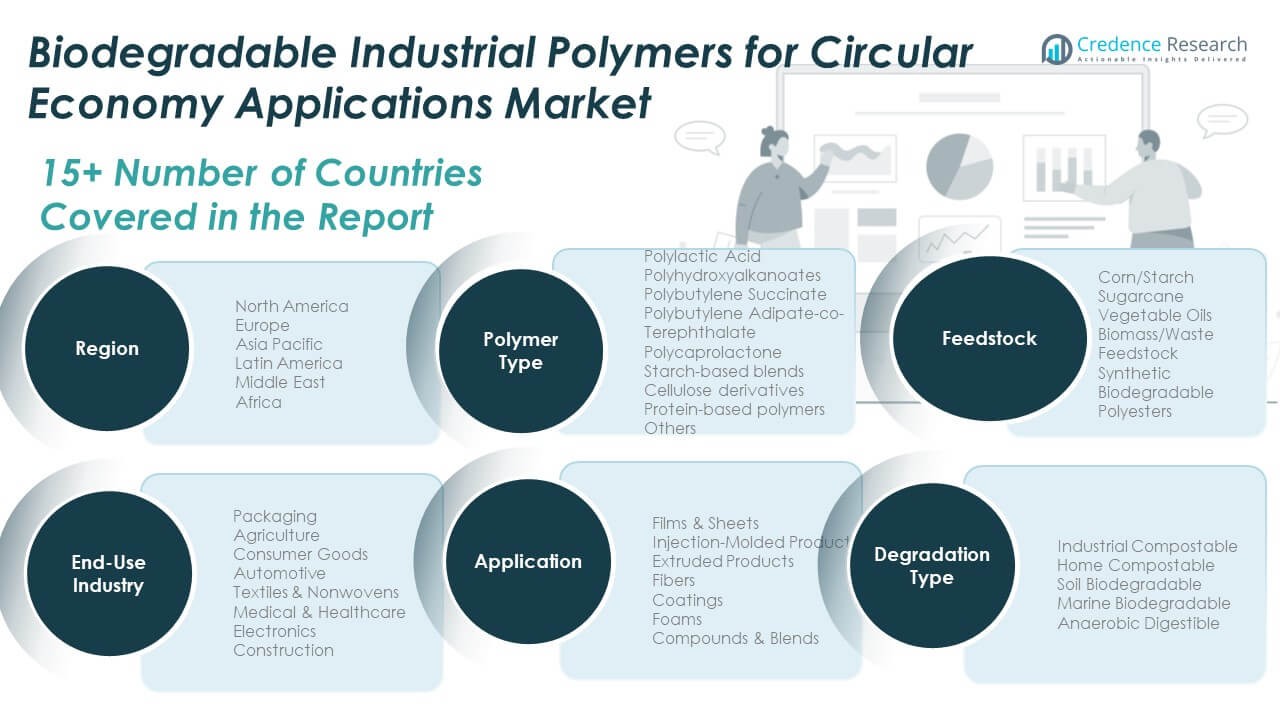
Segmentation:
By Polymer Type
- Polylactic Acid (PLA)
- Polyhydroxyalkanoates (PHA)
- Polybutylene Succinate (PBS)
- Polybutylene Adipate-co-Terephthalate (PBAT)
- Polycaprolactone (PCL)
- Starch-Based Blends
- Cellulose Derivatives
- Protein-Based Polymers
- Others
By Application
- Films & Sheets
- Injection-Molded Products
- Extruded Products
- Fibers
- Coatings
- Foams
- Compounds & Blends
By End-Use Industry
- Packaging
- Agriculture
- Consumer Goods
- Automotive
- Textiles & Nonwovens
- Medical & Healthcare
- Electronics
- Construction
By Degradation Type
- Industrial Compostable
- Home Compostable
- Soil Biodegradable
- Marine Biodegradable
- Anaerobic Digestible
By Feedstock
- Corn/Starch
- Sugarcane
- Vegetable Oils
- Biomass/Waste Feedstock
- Synthetic Biodegradable Polyesters
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Biodegradable Industrial Polymers for Circular Economy Applications Market size was valued at USD 1,447.68 million in 2018 to USD 2,743.10 million in 2024 and is anticipated to reach USD 13,283.67 million by 2032, at a CAGR of 21.9 % during the forecast period. North America holds an estimated 27.3 % share of the global market. The region benefits from strong regulatory policies supporting compostable and bio-based materials. Government incentives and advanced recycling infrastructure accelerate industrial adoption. Key players expand operations in the United States, leveraging mature logistics and R&D ecosystems. Corporate sustainability mandates among large packaging and food companies drive higher demand for biodegradable polymers. It benefits from robust venture capital funding for biopolymer startups. Canada strengthens circular economy projects focused on waste valorization. Mexico expands agricultural film usage through government-backed sustainability programs.
Europe
The Europe Biodegradable Industrial Polymers for Circular Economy Applications Market size was valued at USD 1,316.64 million in 2018 to USD 2,432.53 million in 2024 and is anticipated to reach USD 11,119.97 million by 2032, at a CAGR of 21.0 % during the forecast period. Europe accounts for nearly 24.4 % of the global market. The region benefits from stringent EU directives on plastic waste reduction and producer responsibility regulations. The European Green Deal accelerates the adoption of circular materials across packaging and consumer goods sectors. Countries such as Germany, France, and Italy lead in compostable polymer innovation. Investments in PHA and PLA manufacturing capacity strengthen domestic supply chains. Industry collaboration through bioplastics associations enhances technology standardization. Government procurement programs support bio-based product inclusion in public sectors. Strong R&D partnerships between academia and industry sustain continuous innovation momentum.
Asia Pacific
The Asia Pacific Biodegradable Industrial Polymers for Circular Economy Applications Market size was valued at USD 1,882.40 million in 2018 to USD 3,732.76 million in 2024 and is anticipated to reach USD 19,393.58 million by 2032, at a CAGR of 23.0 % during the forecast period. Asia Pacific represents the largest regional share at 42.5 %. Rapid industrial expansion and population growth strengthen biopolymer adoption. Governments in China, Japan, and India implement plastic reduction initiatives that boost bio-based product demand. Domestic manufacturers expand feedstock sourcing from sugarcane and starch crops. It benefits from cost advantages in large-scale production and export capacity. Regional demand grows across packaging, agriculture, and textiles. Southeast Asian nations invest in composting infrastructure to reduce landfill dependence. Public awareness of sustainability rises through educational campaigns.
Latin America
The Latin America Biodegradable Industrial Polymers for Circular Economy Applications Market size was valued at USD 322.40 million in 2018 to USD 614.61 million in 2024 and is anticipated to reach USD 2,762.11 million by 2032, at a CAGR of 20.8 % during the forecast period. Latin America holds an estimated 6.1 % share of the global market. Countries like Brazil and Argentina lead regional adoption through agricultural and packaging applications. Supportive government frameworks encourage bio-based manufacturing initiatives. Local producers collaborate with European suppliers to improve technological capability. Increasing use of compostable films in agro-industrial sectors promotes circular growth. Urban waste management reforms improve collection systems for biodegradable materials. The region witnesses rising consumer preference for eco-certified packaging. Expanding trade agreements create export opportunities for bio-based resins.
Middle East
The Middle East Biodegradable Industrial Polymers for Circular Economy Applications Market size was valued at USD 122.72 million in 2018 to USD 212.18 million in 2024 and is anticipated to reach USD 859.94 million by 2032, at a CAGR of 19.2 % during the forecast period. The region contributes about 2.0 % to global revenue. Policy reforms toward green manufacturing promote diversification beyond petrochemical dependency. The UAE and Saudi Arabia pioneer regional circular economy initiatives with industrial-scale pilot projects. Demand grows in food packaging and agriculture films. It benefits from public-private partnerships that expand bio-refinery investments. Universities engage in biopolymer research programs aligned with national sustainability goals. Import substitution efforts foster local production of starch-based blends. Eco-labeling initiatives raise awareness across consumer markets.
Africa
The Africa Biodegradable Industrial Polymers for Circular Economy Applications Market size was valued at USD 108.16 million in 2018 to USD 276.36 million in 2024 and is anticipated to reach USD 1,149.59 million by 2032, at a CAGR of 19.1 % during the forecast period. Africa accounts for about 1.8 % of global market share. The region experiences early-stage adoption supported by growing regulatory frameworks in South Africa, Kenya, and Egypt. Rising awareness of sustainable materials in agriculture and packaging drives steady expansion. It benefits from foreign investments targeting regional bio-refinery projects. Multinational companies partner with local governments to develop composting infrastructure. Import reliance for raw materials limits scalability but fosters collaboration opportunities. Educational campaigns promote plastic waste reduction. Gradual infrastructure development supports long-term circular economy integration.
Key Player Analysis:
- NatureWorks LLC
- Danimer Scientific
- BASF SE
- Novamont S.p.A.
- TotalEnergies
- Corbion N.V.
- Biome Bioplastics
- Kaneka Corporation
- Mitsubishi Chemical Corporation
- Eastman Chemical Company
- BioSphere Plastic
- Greenshift Technologies
- Futerro
- Plantic Technologies
- TIPA Corp
- Avantium
- FKUR Kunststoff GmbH
- Toray Industries
- Teijin Limited
Competitive Analysis:
The market features several major players including BASF SE, NatureWorks LLC, Corbion N.V. and Novamont S.p.A. These companies invest heavily in R&D to develop new polymer formulations and scalable manufacturing. Firms compete by securing renewable feedstock supply chains, lowering production costs, and achieving certifications for compostability and biodegradability. Many pursue vertical integration or strategic partnerships to expand product portfolios and strengthen global distribution. Market share is concentrated: a handful of large firms account for over 40 % of revenues. Smaller niche players focus on specialty polymers or additives and often collaborate or license technology from larger firms. Competitive pressure drives continuous cost reductions and performance improvements, pushing lesser-performing producers to differentiate or exit.
Recent Developments:
- In November 2025, KAUST startup Polymeron announced its progress in transforming agricultural waste into high-performance biodegradable plastics. The company is focused on scaling manufacturing capabilities and partnering with other manufacturers globally, with plans to start mass production of biodegradable plastics by the end of 2025, advancing circular economy solutions for biodegradable industrial polymers.
- In November 2025, Braskem and Norsk e‑Fuel entered a strategic collaboration to convert captured CO₂ into circular polymers. The alliance targets production of e-Naphtha feedstock derived from Power-to-Liquid technology which Braskem will convert into bio-based polyethylene and other circular plastics, supporting a low-carbon sustainable materials value chain.
- In July 2025, Teknor Apex acquired Danimer Scientific. The acquisition brought together Teknor Apex’s material-science expertise with Danimer’s biopolymer technology-portfolio, including PHA and PLA formulations, enabling the enlarged company to scale production, accelerate R&D, and reach new end-markets.
Report Coverage:
The research report offers an in-depth analysis based on Polymer Type, Application, End-Use Industry, Degradation Type and Feedstock. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising global sustainability mandates will accelerate demand for biodegradable polymers across industrial sectors.
- Continuous R&D in polymer science will enhance material strength, thermal stability, and process efficiency.
- Expansion of industrial composting infrastructure will improve product lifecycle management and adoption rates.
- Growing integration of circular economy policies will drive collaboration between manufacturers and waste processors.
- Technological advancements in biomass conversion and fermentation will diversify raw material sourcing.
- Strategic partnerships between chemical firms and packaging companies will boost supply chain resilience.
- Market players will focus on regional production hubs to minimize transport emissions and optimize feedstock use.
- Consumer awareness campaigns promoting compostable materials will strengthen brand differentiation and loyalty.
- Regulatory harmonization across regions will simplify global trade and certification processes.
- Investment in pilot-scale facilities will expand commercialization of next-generation bio-based polymers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Biodegradable Industrial Polymers for Circular Economy Applications Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Biodegradable Industrial Polymers for Circular Economy Applications Market projected to grow between 2024 and 2032?
Which Biodegradable Industrial Polymers for Circular Economy Applications Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Biodegradable Industrial Polymers for Circular Economy Applications Market?
Who are the leading companies in the Biodegradable Industrial Polymers for Circular Economy Applications Market?
Which region commanded the largest share of the Biodegradable Industrial Polymers for Circular Economy Applications Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,011.54 million → 2032: USD 48,568.85 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Biodegradable Industrial Polymers for Circular Economy Applications Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Biodegradable Industrial Polymers for Circular Economy Applications Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Biodegradable Industrial Polymers for Circular Economy Applications Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Biodegradable Industrial Polymers for Circular Economy Applications Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Biodegradable Industrial Polymers for Circular Economy Applications Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Biodegradable Industrial Polymers for Circular Economy Applications Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Biodegradable Industrial Polymers for Circular Economy Applications Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Biodegradable Industrial Polymers for Circular Economy Applications Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,011.54 million → 2032: USD 48,568.85 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Biodegradable Industrial Polymers for Circular Economy Applications Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Biodegradable Industrial Polymers for Circular Economy Applications Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Biodegradable Industrial Polymers for Circular Economy Applications Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Biodegradable Industrial Polymers for Circular Economy Applications Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

