
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Boil-in Bags Market Size 2024 | USD 1,810 million |
| Boil-in Bags Market , CAGR | 6.3% |
| Boil-in Bags Market Size 2032 | USD 2,950.83 million |
Market Overview:
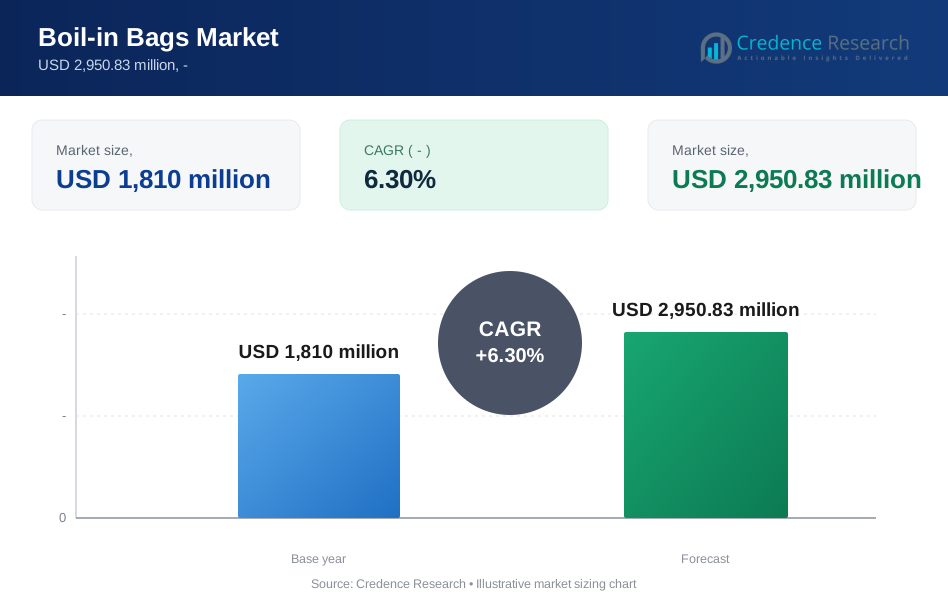
The Boil-in Bags Market is poised for steady growth, projected to expand from USD 1,810 million in 2024 to approximately USD 2,950.83 million by 2032, with a CAGR of 6.3% over the forecast period. This growth is driven by increasing consumer demand for convenient, ready-to-cook meals and easy-to-use food packaging solutions that minimize preparation time. Boil-in bags, designed to withstand high temperatures and safely contain food items during cooking, have gained popularity across various sectors, including frozen foods, ready-to-eat meals, and meal kits. The market benefits from growing demand across the food service industry, retail, and households as consumers prioritize convenience, hygiene, and time efficiency in meal preparation.
Key drivers of this market include shifting consumer lifestyles and rising disposable incomes, which increase the demand for quick, convenient cooking solutions. The growing preference for ready-to-eat and frozen foods, fueled by urbanization and a busy consumer base, has spurred the adoption of boil-in bag packaging. Additionally, technological advancements in materials and sustainable packaging solutions are encouraging manufacturers to develop eco-friendly, biodegradable options, aligning with the increasing consumer preference for environmentally friendly products. The expansion of the food service and online food delivery sectors further supports the demand for boil-in bags, as they provide safe, practical, and efficient food preparation and delivery solutions.
Regionally, North America holds a significant share of the market, driven by high consumption of convenience foods and well-established retail and food service sectors in the United States and Canada. Europe follows closely, with strong demand from countries like the UK, Germany, and France, where sustainable packaging and convenience are key consumer priorities. The Asia-Pacific region is anticipated to experience the fastest growth, propelled by a growing urban population, rising disposable incomes, and expanding food service industries in China, India, and Southeast Asia. Emerging markets in Latin America and the Middle East also show growth potential as consumer habits shift towards convenience and ready-to-eat food options.
Market Drivers:
Rising Demand for Convenience and Ready-to-Eat Foods:
The increasing demand for convenience foods is a major driver in the Boil-in Bags Market. Busy lifestyles and rising workforce participation are prompting consumers to seek easy and quick meal solutions. According to a 2023 survey by the U.S. Department of Agriculture, 56% of Americans prefer quick-preparation foods due to time constraints. This shift in consumer behaviour boosts the demand for packaging solutions like boil-in bags, which allow hassle-free cooking and minimal cleanup, making them ideal for time-pressed consumers.
Growth in the Frozen Food and Meal Kit Sectors:
The expansion of the frozen food and meal kit markets is significantly supporting boil-in bag adoption. Meal kits and frozen foods increasingly feature boil-in bags for portion-controlled and easy-to-cook meals, enhancing convenience for consumers. For instance, HelloFresh, a leading meal kit provider, introduced boil-in bags for certain recipes in 2022, offering users a simplified cooking experience. This trend aligns with the growing preference for home-cooked yet quick-to-prepare meals, supporting boil-in bags as a packaging choice in the meal kit and frozen food segments.
Technological Advancements in Sustainable Packaging:
Advancements in material science have led to the development of environmentally friendly boil-in bags, appealing to the eco-conscious consumer base. Biodegradable and recyclable materials are becoming more common, addressing the demand for sustainable packaging. For instance, Companies such as Amcor introduced eco-friendly, recyclable boil-in bags in 2023, highlighting a commitment to sustainability. As regulatory bodies like the European Union push for stricter environmental standards, packaging companies are innovating to meet both consumer demand and regulatory requirements for sustainable solutions.
Expansion of the Online Food Delivery Sector:
The growth of the online food delivery market is further driving the demand for boil-in bags. With the rise in online grocery and meal delivery services, boil-in bags provide a safe, efficient packaging option that maintains food quality during transport and cooking. In 2022, Uber Eats reported a 30% increase in orders for ready-to-cook meal kits, reflecting growing consumer interest in convenient meal solutions that can be quickly prepared. This trend supports the demand for boil-in bags as a practical, reliable choice for the online food delivery and meal kit industries.
Market Trends:
Shift Toward Biodegradable and Recyclable Materials:
A key trend in the Boil-in Bags Market is the growing adoption of biodegradable and recyclable materials, aligning with consumer and regulatory demands for sustainable packaging. Companies are increasingly developing bags made from plant-based or recyclable materials to reduce environmental impact. For instance, Amcor launched a line of compostable boil-in bags to meet demand for eco-friendly solutions, responding to EU directives pushing for sustainable packaging alternatives. This trend reflects the broader shift across industries to adopt materials that support waste reduction and environmental responsibility.
Innovation in Temperature-Resistant Materials:
The demand for high-temperature resistant materials is rising as consumers seek boil-in bags that offer durability and safety under varied cooking conditions. Manufacturers are focusing on developing bags that can withstand both microwaving and stovetop cooking without compromising food quality. For example, Bemis, a key player in food packaging, introduced a multi-layered boil-in bag in 2022 designed to prevent leaching and withstand high temperatures, providing consumers with a safer cooking experience. These innovations enhance product reliability and expand the versatility of boil-in bags in the ready-to-cook segment.
Customization and Brand Differentiation:
As boil-in bags gain popularity, brands are increasingly customizing packaging to enhance product appeal and create differentiation on retail shelves. Customizable boil-in bags with unique designs and branded messaging have become common, especially for premium and organic food segments. In 2023, Nestlé rolled out a line of customizable boil-in bags for its frozen meals, with product details and cooking instructions printed directly on the packaging. This trend in customization highlights brands’ efforts to enhance consumer engagement and elevate product visibility in a competitive market.
Integration of Smart Packaging Technologies:
Smart packaging technology is gaining traction in the boil-in bags sector, enabling brands to offer added value through features like QR codes and temperature indicators. QR codes, for instance, allow consumers to access recipe ideas or product information, enhancing the cooking experience. HelloFresh added QR codes to its boil-in bag packaging, directing customers to online recipe tutorials and tips. This integration of digital features enhances consumer convenience and aligns with the trend of incorporating smart technology to elevate user experience in the food packaging industry.
Market Challenges Analysis:
High Production Costs and Limited Material Availability:
The Boil-in Bags Market faces significant challenges related to the high production costs associated with durable, heat-resistant, and eco-friendly materials. As consumer and regulatory demand for sustainable packaging rises, manufacturers are pressed to develop biodegradable or recyclable materials, which are often more costly than traditional plastics. Additionally, sourcing these specialized materials can be difficult, especially for smaller manufacturers with limited supply chain access. This cost and availability constraint impacts profitability, particularly as companies strive to balance sustainability with affordability.
Regulatory Compliance and Environmental Standards:
Stringent environmental regulations add complexity to the boil-in bags market, particularly in regions with strict packaging standards. Regulatory bodies like the European Union and the U.S. Environmental Protection Agency (EPA) enforce guidelines on plastic waste reduction, recyclability, and food safety, requiring manufacturers to comply with rigorous standards. Compliance with these regulations often requires significant investment in R&D and production adjustments, which can be challenging, especially for companies working to meet sustainability requirements without significantly raising prices.
Limited Consumer Awareness and Misperceptions:
While demand for sustainable packaging is growing, there remains a gap in consumer awareness and understanding of boil-in bag applications and their environmental benefits. Many consumers associate plastic bags with negative environmental impact, overlooking the advances in biodegradable and recyclable materials within this segment. This misperception can limit market penetration, as consumers may favor perceived “greener” alternatives without understanding the environmental progress made in boil-in bag technology.
Heat Resistance and Safety Challenges:
Developing boil-in bags that meet heat resistance and safety standards is complex, as materials must withstand high temperatures without releasing harmful chemicals or compromising food safety. Maintaining these standards requires advanced technology and precise manufacturing processes, which can drive up costs and limit production capacity. For example, the U.S. Food and Drug Administration (FDA) enforces strict guidelines on food-contact materials, adding a layer of regulatory oversight that requires manufacturers to ensure heat stability and chemical safety, further increasing production complexity and cost.
Market Segmentation Analysis:
By Type
The Boil-in Bags Market is segmented by type into standard boil-in bags and microwaveable boil-in bags. Standard boil-in bags, designed for stovetop cooking, hold a significant share due to their durability and versatility across a range of cooking applications. Microwaveable boil-in bags, which provide convenience for consumers looking for faster meal preparation, are growing in popularity. These bags, crafted from heat-resistant materials that withstand high microwave temperatures, are particularly appealing in the ready-to-eat and meal kit segments as they offer a quick and efficient cooking solution.
By Technology
The market is segmented by technology into heat-sealed and zipper-sealed boil-in bags. Heat-sealed bags dominate the market due to their cost-effectiveness and secure seal, preventing leaks during cooking. Zipper-sealed bags, though more costly, are gaining traction for their reusability and consumer convenience, particularly in premium and organic product lines. Zipper-sealed technology appeals to environmentally conscious consumers, as these bags can often be resealed and reused, enhancing product longevity and reducing waste.
By End User
End users in the boil-in bags market include households, food service providers, and food processing companies. Households represent the largest segment, as boil-in bags are favored by consumers seeking convenience and quick meal preparation at home. Food service providers, such as restaurants and meal delivery services, also contribute to market growth by utilizing boil-in bags to maintain food quality during transportation and ensure easy heating for consumers. Food processing companies increasingly use boil-in bags for frozen foods and meal kits, leveraging their efficiency and ability to preserve product freshness while providing a convenient cooking experience for end consumers.
Segmentations:
By Material Type:
- Paper
- Aluminum foil
- Plastic
- Polyesters
- Cast polypropylene (CPP)
- Polyethylene
- Nylon
- Biodegradable
- Others (ethyl vinyl acetate, fabric, etc.)
By Appearance:
- Opaque
- Transparent
- Printed
By Application:
- Ready to Eat Meals
- Rice and Cereals
- Soups
- Pasta
- Others
- Frozen Foods
- Meat
- Poultry
- Sea Food
- Others
- Fresh Produce
- Bakery & Confectionery
By Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a substantial share in the Boil-in Bags Market, accounting for approximately 30% of global revenue. This region’s demand is driven by high consumer preference for convenience foods, including ready-to-eat meals, frozen foods, and meal kits, which align with the growing demand for quick and efficient cooking solutions. The United States leads this market, benefiting from a well-established food service industry and high household adoption of meal kits that frequently use boil-in bags for easy cooking and minimal cleanup. Additionally, North America’s focus on sustainable packaging aligns with the development of biodegradable boil-in bags, as regulatory agencies like the U.S. Environmental Protection Agency (EPA) push for reduced plastic waste and recyclable materials in food packaging.
Europe
Europe represents around 25% of the global market share, driven by high standards for sustainable packaging and an increasing demand for convenient meal solutions. Countries like the UK, Germany, and France lead the region, where consumer awareness of eco-friendly products has spurred demand for recyclable and biodegradable boil-in bags. The European Union’s stringent environmental regulations have accelerated the development and adoption of sustainable packaging, including boil-in bags crafted from eco-friendly materials. As a result, manufacturers are actively investing in R&D to meet regulatory standards and cater to environmentally conscious consumers. The expansion of the frozen and ready-to-eat food sectors also supports steady growth for boil-in bags across Europe.
Asia-Pacific
The Asia-Pacific region is expected to experience the fastest growth in the boil-in bags market, holding approximately 20% of global market share. This growth is driven by rapid urbanization, rising disposable incomes, and increasing consumer preference for convenient, packaged foods in countries like China, India, and Japan. As the food service industry and online food delivery sectors expand, boil-in bags offer a practical solution for meal preparation, transportation, and consumption. Additionally, the growing popularity of Western-style ready-to-eat meals and meal kits in urban areas has spurred demand for boil-in bag packaging. Asia-Pacific’s role as a major manufacturing hub also allows companies to produce cost-effective boil-in bags that meet regional demand, further driving market expansion.
Latin America, Middle East, and Africa
LAMEA accounts for roughly 15% of the global Boil-in Bags Market, with growth potential largely concentrated in Latin America. Countries like Brazil and Mexico are witnessing an increase in demand for convenient and frozen food products, driven by changing consumer lifestyles and increased purchasing power. In the Middle East, the United Arab Emirates and Saudi Arabia are also seeing growing demand for boil-in bags, particularly in the hospitality and food service industries, where convenience and food quality preservation are prioritized. Africa, while a smaller market, holds potential as urbanization and improved distribution networks make packaged food products more accessible. Limited awareness and higher costs of advanced packaging materials pose challenges, but rising investment in the region’s food processing infrastructure is expected to support gradual growth in boil-in bag adoption.
Key Player Analysis:
- Sealed Air Corporation
- Mondi Group
- Amcor plc
- ProAmpac LLC
- Bemis Company, Inc.
- SABIC (Saudi Basic Industries Corporation)
- The Reynolds Company
- Printpack Inc.
- Glenroy, Inc.
- Constantia Flexibles Group GmbH
Competitive Analysis:
The Boil-in Bags Market is highly competitive, with key players focusing on innovations in material science, sustainability, and convenience to capture market share. Major companies such as Sealed Air Corporation, Amcor, and Mondi Group lead the market, leveraging advanced manufacturing capabilities to develop high-temperature resistant and eco-friendly boil-in bags. These firms benefit from strong R&D investment, enabling them to introduce biodegradable and recyclable packaging options that meet rising consumer and regulatory demand for sustainable solutions. Competitors like ProAmpac and Printpack emphasize customization and branding, catering to food service and retail clients seeking differentiated packaging designs. The competition is further intensified by the growth of the ready-to-eat and meal kit segments, pushing companies to enhance product durability, safety, and user experience. To stay competitive, companies continuously innovate in material technology and partner with food brands to expand their presence in the growing market for convenient cooking solutions.
Recent Developments:
- Amcor PLC collaborated with Stonyfield Organic in February 2024 to introduce the first all-polyethylene (PE) spouted pouch for its YoBaby yogurt. This pouch replaces the previous multi-laminate structure with a recyclable design, supporting Amcor’s commitment to sustainable packaging solutions.
- Sealed Air Corporation expanded its sustainable packaging portfolio in October 2023 with a new line of Modified Atmosphere Packaging (MAP) films. These films offer enhanced puncture resistance, ideal for delicate foods like vegetables and fruits, demonstrating Sealed Air’s focus on durability and food safety in flexible packaging.
- ProAmpac launched its ProActive PCR retort pouches in November 2023, integrating 30% post-consumer recycled (PCR) content. This innovation meets both EU and FDA food safety standards, providing a greener alternative for food and pet food packaging while reducing virgin resin usage.
- Mondi Group invested €20 million in 2023 to expand its Štětí plant in the Czech Republic, enhancing production capacity for sustainable packaging solutions. This investment aligns with Mondi’s strategy to support eco-friendly packaging options, particularly for the European market.
Market Concentration & Characteristics:
The Boil-in Bags Market is moderately concentrated, with a mix of established global companies and specialized packaging providers competing to meet diverse consumer needs. Key players like Amcor, Sealed Air Corporation, and Mondi Group lead the market, benefiting from advanced production capabilities, innovation in heat-resistant and sustainable materials, and broad distribution networks. High entry barriers, including the need for specialized manufacturing technologies and compliance with stringent food safety and environmental standards, limit the entry of smaller players and favor established firms. As demand for eco-friendly and versatile boil-in bags grows, these companies are focusing on sustainable innovations, such as biodegradable and recyclable materials, to enhance their market positions. The competitive landscape is further defined by collaborations with food and meal kit brands, as companies work to meet the rising consumer demand for convenient, safe, and sustainable packaging solutions.
Report Coverage:
The research report offers an in-depth analysis based on material type, appearance, application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for boil-in bags will grow as consumers prioritize convenience and time-saving meal solutions.
- Eco-friendly materials, including biodegradable and recyclable options, will become central as sustainability remains a key consumer priority.
- Technological advancements in heat-resistant materials will enhance safety and versatility for stovetop and microwave applications.
- The expansion of the meal kit and ready-to-eat food sectors will drive demand for boil-in bags, especially in urban and fast-paced markets.
- Partnerships between packaging companies and food brands will increase, offering customized solutions tailored to product-specific needs.
- Innovations in smart packaging, such as QR codes and interactive labels, will enhance consumer engagement and provide cooking guidance.
- Emerging markets in Asia-Pacific and Latin America will see rising demand due to urbanization and growth in packaged food consumption.
- Cost-effective production methods for sustainable materials will gain traction, making eco-friendly packaging more accessible.
- The rise of online grocery and food delivery services will further bolster the market as boil-in bags cater to safe and easy meal preparation.
- Manufacturers will continue to improve durability and design flexibility, catering to varied consumer preferences in the convenience food sector.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Boil-in Bags market?
What factors are driving the growth of the Boil-in Bags market?
What are some challenges faced by the Boil-in Bags market?
Who are the major players in the Boil-in Bags market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Boil-in Bags Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Boil-in Bags Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 1,810 million → forecast year: USD 2,950.83 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Boil-in Bags Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Boil-in Bags Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Boil-in Bags Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Boil-in Bags Market Drivers
- 3.3 Boil-in Bags Market Restraints & Challenges
- 3.4 Boil-in Bags Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Boil-in Bags Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Boil-in Bags Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Boil-in Bags category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Boil-in Bags Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Boil-in Bags Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Boil-in Bags market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Boil-in Bags Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Boil-in Bags Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Boil-in Bags Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Boil-in Bags (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Boil-in Bags Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Boil-in Bags Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Boil-in Bags Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Boil-in Bags Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Boil-in Bags Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Boil-in Bags Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Boil-in Bags Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Boil-in Bags Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Boil-in Bags Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
