
Market Overview:
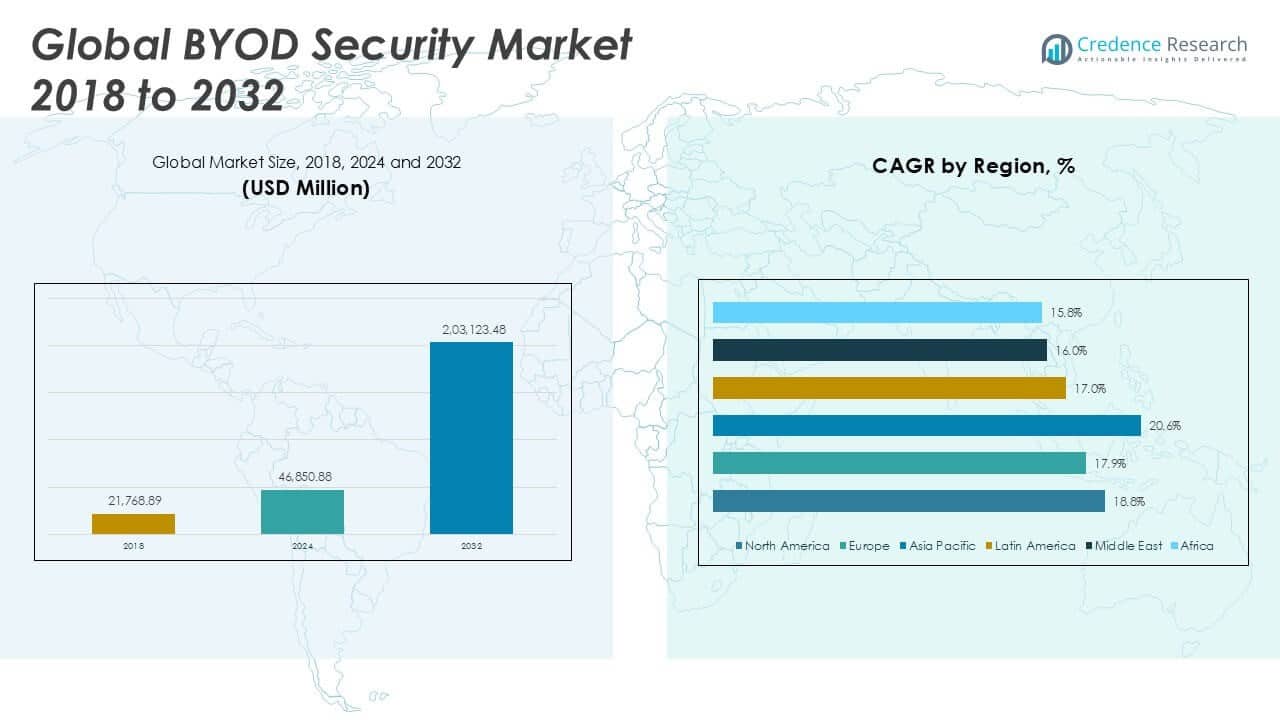
The Global BYOD Security Market size was valued at USD 21,768.89 million in 2018 to USD 46,850.88 million in 2024 and is anticipated to reach USD 2,03,123.48 million by 2032, at a CAGR of 18.77% during the forecast period
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| BYOD Security Market Size 2024 | USD 46,850.88 Million |
| BYOD Security Market, CAGR | 18.77% |
| BYOD Security Market Size 2032 | USD 2,03,123.48 Million |
Key drivers of the BYOD security market include the rising demand for mobile security solutions, increasing cybersecurity threats, and the need for businesses to comply with data protection regulations. As more companies implement BYOD policies to enhance employee productivity and reduce operational costs, securing sensitive data on personal devices becomes crucial. The growing trend of remote work and the expansion of cloud-based services further elevate the importance of securing personal devices in corporate environments. Additionally, the integration of advanced technologies such as Artificial Intelligence (AI) and Machine Learning (ML) is contributing to the development of more efficient and proactive security solutions, enabling real-time threat detection and response.
Regionally, North America holds the largest market share, driven by the presence of key market players and strong cybersecurity infrastructure. The high concentration of cybersecurity investments and government initiatives also bolster market growth in this region. The Asia-Pacific region is expected to experience the highest growth rate due to the growing digitalization of enterprises and the adoption of BYOD policies in emerging markets. The demand for robust BYOD security solutions is also rising in Europe and the Middle East, owing to stricter data privacy regulations. As more organizations in these regions adopt BYOD strategies, the need for comprehensive security frameworks becomes increasingly urgent.
Market Insights:
- The Global BYOD Security Market was valued at USD 21,768.89 million in 2018 and is projected to reach USD 2,03,123.48 million by 2032, growing at a CAGR of 18.77%.
- The rise in BYOD adoption increases the demand for robust security solutions to protect sensitive data on personal devices.
- Growing cybersecurity threats like data breaches and ransomware push organizations to adopt advanced BYOD security solutions.
- Stricter data privacy regulations like GDPR and CCPA require businesses to ensure proper security for personal devices and avoid penalties.
- The integration of AI and ML enhances BYOD security by providing proactive threat detection and real-time responses.
- North America holds the largest market share, benefiting from strong cybersecurity infrastructure and high BYOD adoption rates.
- The Asia Pacific region is experiencing the highest growth rate due to rapid digitalization and the increasing adoption of BYOD policies.
- Latin America and the Middle East see rising demand for BYOD security solutions, driven by new data privacy laws and digital transformations.
Market Drivers:
Increasing Adoption of Bring Your Own Device (BYOD) Policies
The adoption of BYOD policies is rapidly increasing as businesses seek to enhance employee productivity, reduce operational costs, and provide employees with greater flexibility. The Global BYOD Security Market is witnessing this trend, as organizations recognize the value of allowing employees to use their personal devices for work purposes. These policies offer several advantages, including improved employee satisfaction and a reduction in hardware expenses. However, the widespread use of personal devices for work introduces security challenges, making it critical for businesses to implement robust security measures to protect sensitive corporate data on these devices.
- For instance, IBM's On Demand Workplace platform, supporting a global BYOD strategy, facilitated nearly 1 million employee visits daily, directly contributing to measurable productivity improvements as employees leveraged secure access to resources from any device.
Growing Cybersecurity Threats and Risks
The rise in cybersecurity threats is one of the key drivers of the Global BYOD Security Market. Cyberattacks such as data breaches, phishing, and ransomware are becoming more sophisticated and frequent, posing significant risks to businesses that do not secure personal devices. As organizations implement BYOD policies, they inadvertently expose themselves to new vulnerabilities, especially when employees use devices that are not properly secured. It is essential for companies to adopt advanced security solutions to protect against these threats and ensure the integrity of their corporate data.
Regulatory Compliance and Data Privacy Requirements
Increasing data privacy regulations and compliance standards are also contributing to the growth of the Global BYOD Security Market. Governments around the world are introducing stringent laws to protect personal and corporate data, such as the GDPR in Europe and CCPA in California. These regulations require businesses to implement appropriate security measures to protect sensitive data on personal devices. Failure to comply with these regulations can result in severe penalties, prompting organizations to invest in BYOD security solutions to mitigate compliance risks and safeguard customer and employee data.
Technological Advancements in Security Solutions
Technological advancements, particularly in Artificial Intelligence (AI) and Machine Learning (ML), are driving innovation in the BYOD security space. These technologies enable more proactive and intelligent security measures that can detect and respond to potential threats in real time. The integration of AI and ML into security solutions enhances the ability to analyze large volumes of data, identify patterns, and predict possible vulnerabilities. As these technologies continue to evolve, the Global BYOD Security Market will benefit from increasingly sophisticated security systems that can protect personal devices and corporate networks from emerging threats.
- For instance, Cisco Secure Network Analytics processes activity using more than 70 distinct machine learning-based detectors to identify and investigate malicious network events in enterprise environments.
Market Trends:
Increasing Integration of Cloud-Based Security Solutions
The integration of cloud-based security solutions is a significant trend in the Global BYOD Security Market. As businesses continue to embrace remote work and cloud technologies, there is a growing need for security solutions that can protect data across a variety of platforms and devices. Cloud-based solutions offer scalability, flexibility, and easier management, which makes them particularly appealing for organizations adopting BYOD policies. These solutions enable real-time updates and centralized management, making it easier for businesses to enforce security policies and monitor devices from a single platform. The cloud's ability to provide secure access to corporate resources from any device further enhances its adoption in securing personal devices used for work.
- For instance, CrowdStrike’s cloud-native Falcon platform protects over 300 of the Fortune 500 companies and 543 of the Fortune 1,000, highlighting successful real-time threat detection and centralized security for diverse, global enterprises.
Rising Demand for Mobile Threat Defense Solutions
Mobile threat defense (MTD) solutions are increasingly gaining traction in the Global BYOD Security Market. With the growing number of mobile devices in the workplace, companies are seeking more specialized security measures to protect their networks from mobile-specific vulnerabilities. MTD solutions focus on securing mobile endpoints against a variety of threats, including malware, data leakage, and device theft. These solutions are designed to integrate seamlessly with BYOD policies, ensuring that personal devices used by employees meet organizational security standards. As mobile devices become central to the modern workforce, the demand for advanced mobile threat defense solutions will continue to grow, further driving the BYOD security market.
- For instance, Lookout Mobile Endpoint Security analyzes telemetry from over 315 million mobile apps to enable comprehensive threat protection for organizations.
Market Challenges Analysis:
Data Privacy and Compliance Risks
One of the primary challenges in the Global BYOD Security Market is ensuring data privacy and compliance with increasingly stringent regulations. As businesses adopt BYOD policies, managing personal devices becomes more complex, particularly when handling sensitive information. Employees often use personal devices for both work and personal activities, increasing the risk of data leakage or unauthorized access to confidential data. Organizations must implement security measures that comply with regulations like GDPR or CCPA, which impose strict requirements on data protection. Failure to meet these standards can result in severe penalties, making compliance a significant challenge for companies relying on BYOD.
Managing Device and Network Security
Managing device and network security presents another challenge in the Global BYOD Security Market. With the diverse range of devices used by employees, companies face difficulties in maintaining uniform security policies across all endpoints. These devices often run on different operating systems, each with its own set of vulnerabilities. Ensuring that personal devices are secure while connected to the corporate network requires advanced security frameworks, which can be difficult to implement and manage. The complexity of securing a wide array of devices and managing the risks associated with remote access can strain IT resources and increase operational costs for businesses.
Market Opportunities:
Growing Demand for Advanced Endpoint Protection Solutions
A significant opportunity in the Global BYOD Security Market lies in the growing demand for advanced endpoint protection solutions. As companies increasingly rely on personal devices for business operations, the need for comprehensive security tools that can protect various endpoints becomes critical. Endpoint protection platforms (EPP) offer the potential to safeguard devices from malware, data breaches, and unauthorized access, ensuring data integrity across all devices. This shift presents a prime opportunity for security providers to develop innovative solutions that can detect threats in real-time and provide continuous monitoring, helping businesses manage the security challenges posed by BYOD policies.
Integration of Artificial Intelligence and Automation
The integration of Artificial Intelligence (AI) and automation into BYOD security solutions presents another key market opportunity. By incorporating AI and machine learning, security systems can proactively detect and respond to emerging threats, enhancing the overall effectiveness of security measures. AI-powered solutions can analyze large volumes of data, identify potential vulnerabilities, and automate responses, reducing the burden on IT teams. The application of AI and automation in the Global BYOD Security Market can significantly improve the efficiency and scalability of security measures, enabling businesses to better protect their networks and data from sophisticated cyberattacks.
Market Segmentation Analysis:
By Device Type
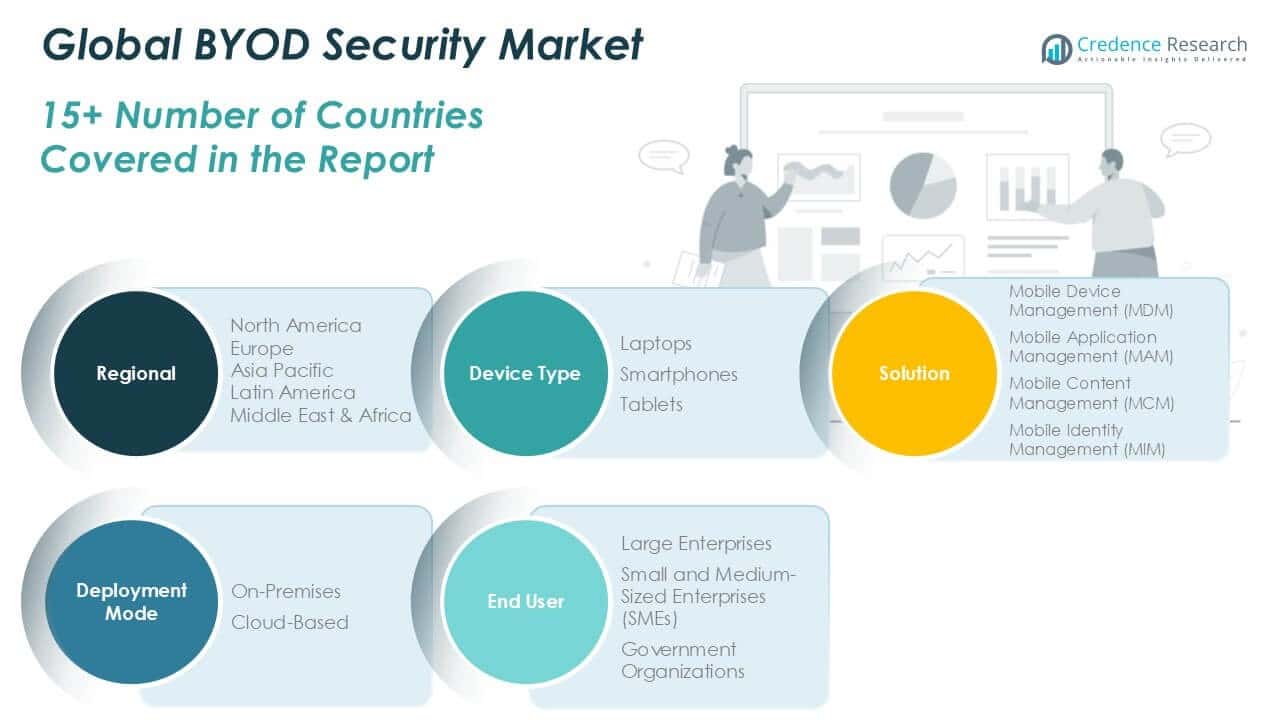
The Global BYOD Security Market is segmented by device type, with laptops, smartphones, and tablets leading the market. Smartphones hold the largest market share due to their widespread use in both personal and professional settings. Tablets and laptops follow, with businesses prioritizing their security as more employees use these devices for work-related tasks. Companies require secure management of personal devices, driving the demand for comprehensive security solutions across all device types.
- For instance, Venn’s Secure BYO-PC technology has been adopted by more than 700 organizations, including companies such as Fidelity, Guardian, and Voya, to safeguard data and applications on employee-owned laptops and desktops.
By Solution
The solutions segment includes Mobile Device Management (MDM), Mobile Deployment Mode Management (MAM), Mobile Content Management (MCM), and Mobile Identity Management (MIM). MDM dominates the market, offering businesses device control features such as remote wipe, encryption, and tracking. MAM and MCM are gaining popularity as companies increasingly focus on securing mobile applications and content. MIM is also growing as organizations aim to protect employee identities and ensure secure access to corporate data on mobile devices.
- For instance, Citrix ShareFile enabled enterprises to securely manage over 35 million files daily within its MCM platform, focusing on secure file sharing and data-centric security controls.
By Deployment Mode
The BYOD security market is further divided into On-Premises and Cloud-Based deployment modes. Cloud-based solutions are witnessing rapid growth due to their scalability, flexibility, and cost-effectiveness. These solutions offer businesses the convenience of managing and securing devices remotely, which is essential for organizations with mobile workforces. On-premises solutions remain relevant for companies with stringent data control needs, especially in industries with high regulatory requirements.
Segmentations:
By Device Type- Laptops
- Smartphones
- Tablets
- Mobile Device Management (MDM)
- Mobile Deployment Mode Management (MAM)
- Mobile Content Management (MCM)
- Mobile Identity Management (MIM)
- On-Premises
- Cloud-Based
- Paint & Coating
- Plastics
- Fibers
- Electric Motors
- Oil and Gas
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Regional Analysis:
North America
The North America Global BYOD Security market size was valued at USD 9,085.14 million in 2018, expected to reach USD 19,340.51 million in 2024, and is anticipated to reach USD 84,095.15 million by 2032, at a CAGR of 18.8% during the forecast period. North America holds the largest market share, driven by strong cybersecurity infrastructure and the presence of key market players. The region’s robust IT security framework, combined with high adoption rates of BYOD policies among businesses, accelerates the demand for advanced security solutions. Regulatory pressures such as GDPR in Europe and similar local regulations further drive the need for compliance-focused security solutions in the region. The U.S. and Canada are the leading countries, with businesses increasingly investing in mobile threat defense solutions and endpoint protection. As more enterprises in North America implement flexible working models, the demand for efficient BYOD security systems is expected to grow significantly.
Europe
The Europe Global BYOD Security market size was valued at USD 6,405.15 million in 2018, projected to reach USD 13,305.96 million in 2024, and expected to reach USD 54,438.45 million by 2032, growing at a CAGR of 17.9%. Europe is witnessing a steady increase in BYOD adoption, especially in sectors like healthcare and finance. Stringent data privacy regulations such as the General Data Protection Regulation (GDPR) are pushing organizations to invest in robust security solutions to meet compliance requirements. The region’s increasing digitalization and mobile workforce create a growing need for comprehensive security measures. Countries such as the UK, Germany, and France lead the market, with businesses investing in advanced BYOD security tools to mitigate cybersecurity risks.
Asia Pacific
The Asia Pacific Global BYOD Security market size was valued at USD 4,298.27 million in 2018, expected to reach USD 10,006.65 million in 2024, and anticipated to reach USD 48,998.46 million by 2032, with a CAGR of 20.6%. This region is expected to witness the highest growth during the forecast period due to rapid technological advancements, digitalization, and the increasing adoption of BYOD policies in emerging economies like India and China. The growing number of internet and mobile device users in the region, along with the shift towards remote working, contributes significantly to the demand for BYOD security solutions. High investments in mobile security and the increasing need for compliance with data privacy regulations in countries like Japan and South Korea further fuel market growth.
Latin America
The Latin America Global BYOD Security market size was valued at USD 1,028.14 million in 2018, projected to reach USD 2,185.26 million in 2024, and expected to reach USD 8,385.50 million by 2032, growing at a CAGR of 17.0%. In Latin America, the adoption of BYOD policies is growing, particularly in industries such as banking, education, and manufacturing. The region is undergoing a digital transformation, driving the need for secure management of mobile devices in the workplace. Brazil and Mexico are the leading markets in the region, with increasing awareness about the security risks associated with personal devices used for business purposes. The implementation of data privacy laws is also contributing to market growth, as businesses look to comply with new regulations and safeguard corporate data.
Middle East
The Middle East Global BYOD Security market size was valued at USD 571.09 million in 2018, expected to reach USD 1,116.34 million in 2024, and anticipated to reach USD 4,027.43 million by 2032, at a CAGR of 16.0%. The Middle East is experiencing a rapid adoption of BYOD policies, driven by the increasing mobile workforce and the shift towards digital enterprises. The growing focus on cybersecurity due to rising cyberattacks and the need to comply with international data protection regulations are key factors contributing to the market’s expansion. Countries like the UAE, Saudi Arabia, and Qatar are investing in mobile security solutions to secure personal devices accessing corporate networks, creating a lucrative opportunity for security vendors in the region.
Africa
The Africa Global BYOD Security market size was valued at USD 381.11 million in 2018, expected to reach USD 896.17 million in 2024, and anticipated to reach USD 3,178.49 million by 2032, growing at a CAGR of 15.8%. Africa’s market for BYOD security is growing steadily, primarily due to the increased adoption of mobile devices and the rise in internet penetration across the continent. As businesses in Africa shift towards flexible work arrangements, the need for securing personal devices used for work purposes becomes critical. Key markets like South Africa, Nigeria, and Kenya are seeing an increasing demand for BYOD security solutions. However, challenges such as limited cybersecurity infrastructure and budget constraints may slow down market growth in some regions, presenting opportunities for innovative solutions tailored to the unique needs of the African market.
Key Player Analysis:
- Alcatel-Lucent Enterprise (Nokia Oyj)
- Aruba Networks (Hewlett Packard Enterprise)
- Avaya Inc.
- BlackBerry Limited
- Broadcom Inc.
- Cisco Systems Inc.
- Citrix Systems Inc.
- Forescout Technologies Inc.
- IBM Corporation
- iPass Inc. (Pareteum Corporation)
- Ivanti
Competitive Analysis:
The Global BYOD Security Market is highly competitive, with several key players striving to offer comprehensive security solutions. Companies such as Cisco Systems Inc., IBM Corporation, and BlackBerry Limited dominate the market, leveraging advanced technologies like Artificial Intelligence (AI) and Machine Learning (ML) to enhance mobile security features. These industry leaders focus on delivering scalable solutions that can secure diverse device types, such as smartphones, laptops, and tablets. New entrants and smaller players are carving out niches by offering specialized solutions tailored to specific industries or regions. The increasing demand for cloud-based security solutions has prompted many companies to expand their offerings, creating a dynamic and evolving competitive landscape. Companies are investing heavily in research and development to provide innovative solutions that can address emerging security threats, positioning themselves to capture a larger share of the growing BYOD security market.
Recent Developments:
- In May 2025, HPE’s Aruba Networking announced new distributed services switches-the CX 10K and CX 10040-plus new Wi-Fi 7 access points, aimed at serving enterprise AI and high-performance computing needs.
- In April 2025, Avaya launched its Avaya Infinity™ platform, created to unify fragmented customer experiences and strengthen enterprise relationships with new AI and intelligent orchestration tools.
- In June 2025, Alcatel-Lucent Enterprise expanded its partnership with Versa Networks to offer enhanced Zero Trust Network Access and Secure SD-WAN security solutions to enterprise customers.
Market Concentration & Characteristics:
The Global BYOD Security Market exhibits moderate concentration, with a few dominant players holding a significant share. Leading companies like Cisco Systems, IBM Corporation, and BlackBerry Limited control the majority of the market by offering comprehensive security solutions that cater to a wide range of industries. These players focus on developing scalable and customizable security features to address the growing demand for mobile device protection. Smaller players and new entrants focus on niche markets, offering specialized solutions or targeting specific regions. The market is characterized by rapid technological advancements, especially in AI and cloud-based security, which drive competition and innovation. Companies invest in research and development to enhance their product offerings and stay competitive in this dynamic market. As more businesses adopt BYOD policies, the demand for secure, efficient, and cost-effective solutions continues to grow, fostering competition within the market.
Report Coverage:
The research report offers an in-depth analysis based on Device Type, Solution, Deployment Mode, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The increasing adoption of remote and hybrid work models will drive the demand for secure BYOD solutions to ensure safe access to corporate data from personal devices.
- Organizations are investing in advanced mobile security solutions to mitigate the growing risks associated with data breaches, malware, and other cyber threats.
- The integration of artificial intelligence (AI) and machine learning (ML) into BYOD security systems will enhance threat detection, enabling proactive security measures and real-time responses.
- Cloud-based BYOD security solutions will continue to gain traction due to their flexibility, scalability, and ability to secure data across multiple devices in a decentralized work environment.
- Compliance with data privacy regulations such as GDPR and CCPA will remain a key driver, prompting businesses to strengthen their BYOD security measures to meet legal requirements.
- The rise of Internet of Things (IoT) devices in the workplace will increase the attack surface, leading to more comprehensive security strategies that address both mobile and IoT risks.
- Zero-trust security models will become more widely adopted, focusing on minimizing unauthorized access and ensuring that all devices, including personal ones, meet security standards before accessing corporate resources.
- Businesses will focus on developing user-friendly security solutions to address employee resistance to invasive security measures, balancing security with ease of use.
- The ongoing shift to mobile-first strategies will increase the need for secure mobile application management, content protection, and identity management.
- Organizations will prioritize ongoing employee training to minimize insider threats and ensure adherence to company-wide BYOD security policies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global BYOD Security Market?
What factors are driving the growth of the Global BYOD Security Market?
What are the key segments within the Global BYOD Security Market?
What are some challenges faced by the Global BYOD Security Market?
Who are the major players in the Global BYOD Security Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 BYOD Security Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2024)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global BYOD Security Market Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2024) (2018: USD 21,768.89 million → 2024: USD 46,850.88 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 BYOD Security Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2018 vs. 2024
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. BYOD Security Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 BYOD Security Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 BYOD Security Market Drivers
- 3.3 BYOD Security Market Restraints & Challenges
- 3.4 BYOD Security Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 BYOD Security Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 BYOD Security Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, BYOD Security category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 BYOD Security Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2024
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2024
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. BYOD Security Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2018)
- 5.1.2 Global Export Volume by Country (2018) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2018)
- 5.1.4 Global Import Volume by Country (2018) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to BYOD Security. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 BYOD Security Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2018
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 BYOD Security Market Share Analysis – 2018
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2018)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 BYOD Security Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in BYOD Security (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in BYOD Security
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global BYOD Security Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2024) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2018-2024)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2024
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America BYOD Security Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe BYOD Security Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific BYOD Security Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America BYOD Security Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East BYOD Security Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa BYOD Security Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. BYOD Security Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
