
Calcineurin Inhibitors Market Overview:
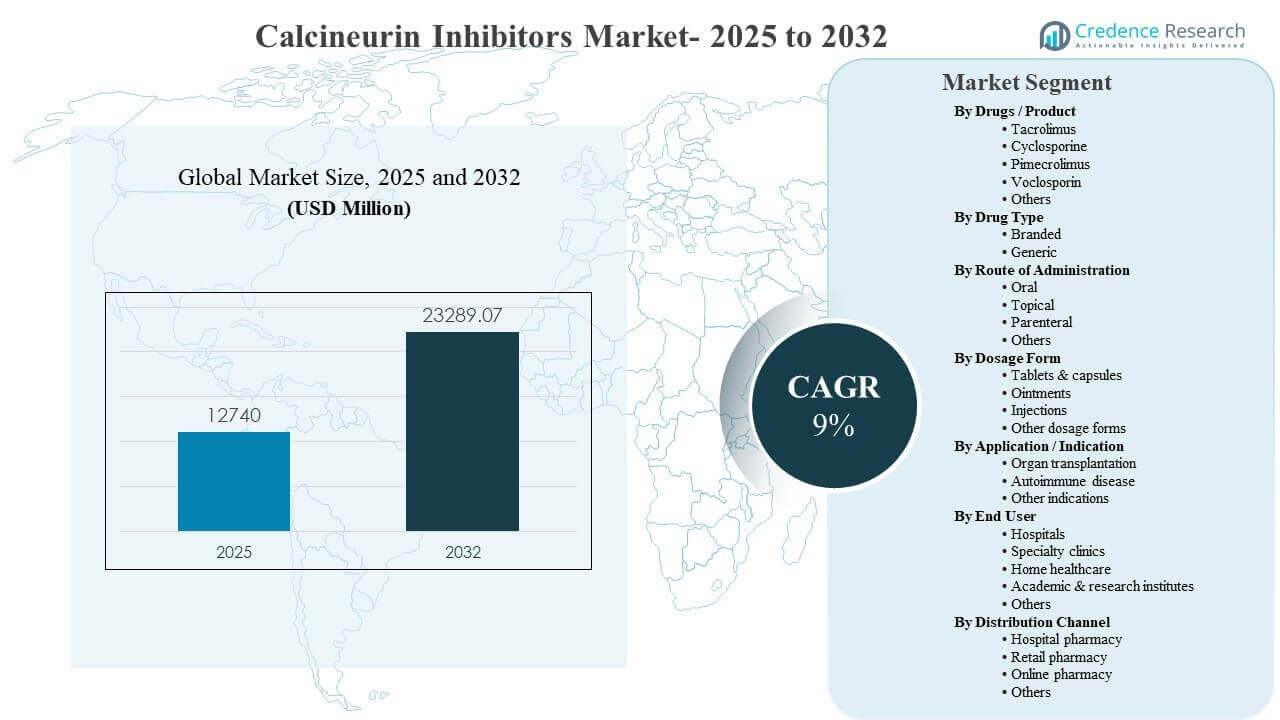
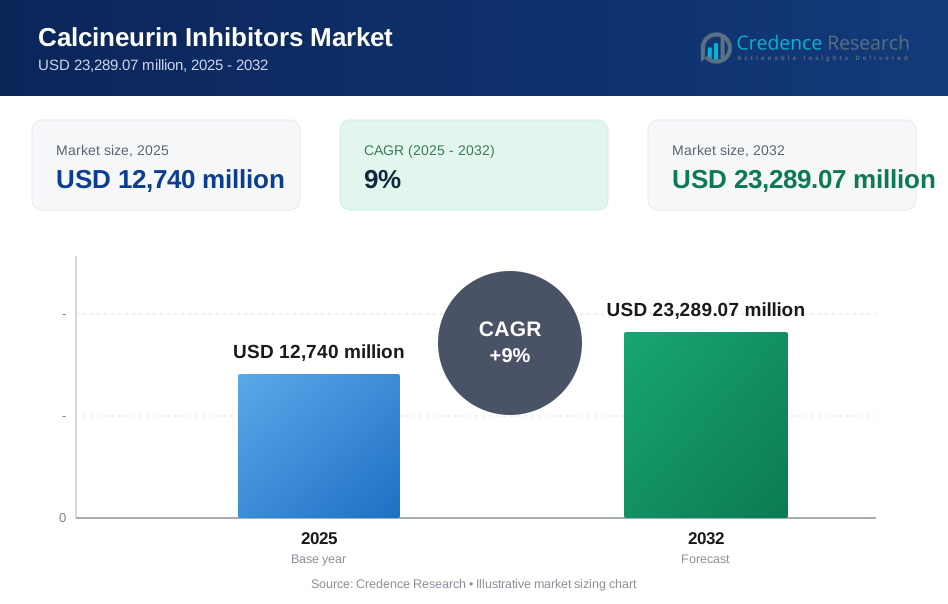
The global Calcineurin Inhibitors Market size was estimated at USD 12,740 million in 2025 and is expected to reach USD 23,289.07 million by 2032, growing at a CAGR of 9% from 2025 to 2032. Expanding reliance on long-term immunosuppression in solid-organ transplantation continues to anchor demand, supported by standardized post-transplant protocols and close therapeutic monitoring that sustains chronic utilization. Broader specialty prescribing in autoimmune conditions and gradual access expansion in large emerging markets further strengthens volume growth across branded and generic portfolios.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Calcineurin Inhibitors Market Size 2025 | USD 12,740 million |
| Calcineurin Inhibitors Market, CAGR | 9% |
| Calcineurin Inhibitors Market Size 2032 | USD 23,289.07 million |
Key Market Trends & Insights
- The Calcineurin Inhibitors Market is projected to expand from USD 12,740 million (2025) to USD 23,289.07 million (2032), reflecting a 9% CAGR (2025–2032).
- Tacrolimus held 47.9% share in 2025, supported by extensive use across transplant maintenance regimens and wide availability across dosage strengths.
- Oral administration represented 53.1% share in 2025, reflecting chronic maintenance therapy needs and convenience for long-duration treatment pathways.
- North America accounted for 35.6% share in 2025, driven by high transplant center density, specialty follow-up intensity, and mature reimbursement pathways.
- Asia Pacific growth is supported by scaling specialty infrastructure and rising access to immunosuppressive therapy.
Segment Analysis
The Calcineurin Inhibitors Market is shaped by persistent demand from transplant medicine, where calcineurin inhibitors remain core immunosuppressants used across induction-to-maintenance pathways and require ongoing therapeutic monitoring. Long treatment durations, protocol-driven prescribing, and strong clinician familiarity support stable baseline volumes, while pricing and access dynamics increasingly steer product choice between branded and generic options. Expanded capacity in specialty clinics and improved continuity of care are reinforcing refill intensity across chronic users.
Growth also reflects broader use in autoimmune indications and dermatology settings, where topical and systemic calcineurin inhibitors are selected to manage immune-mediated inflammation when steroid-sparing strategies are preferred. Route and dosage-form selection is strongly linked to indication severity and monitoring needs, with oral formulations scaling for systemic control and topicals supporting localized disease management. Competitive positioning increasingly depends on supply reliability, therapeutic equivalence confidence, and portfolio breadth across strengths and dosage forms.
By Drugs / Product Insights
Tacrolimus accounted for the largest share of 47.9% in 2025. Broad transplant adoption, extensive clinical experience, and strong protocol alignment continue to support first-line use across major organ programs. Wide availability across dosage strengths and both branded and generic options improves continuity of supply and affordability. Established monitoring practices enable consistent dose optimization and sustained long-term utilization.
By Drug Type Insights
Branded therapies remain important where prescriber confidence, perceived consistency, and established clinical evidence influence selection for narrow-therapeutic-index immunosuppressants. Generic utilization continues to expand through tender-based procurement and payer-led substitution where therapeutic equivalence is trusted. Price sensitivity and reimbursement constraints shape mix by country and by care setting. Formulary policies and supply reliability increasingly determine share shifts within this segment.
By Route of Administration Insights
Oral administration accounted for the largest share of 53.1% in 2025. Long-duration maintenance regimens in transplantation and systemic autoimmune therapy favor oral dosing due to convenience and adherence advantages. Broad availability of oral tacrolimus and cyclosporine supports large-scale outpatient management. Mature therapeutic drug monitoring workflows reinforce confidence in oral dosing optimization over time.
By Dosage Form Insights
Tablets and capsules remain widely utilized because chronic systemic therapy is commonly managed in outpatient settings with routine dose titration and refill-based continuity. Ointments support dermatology indications where localized immunomodulation is preferred and steroid-sparing strategies are prioritized. Injections are used when inpatient initiation, acute stabilization, or protocol-driven administration is required in select settings. Dosage-form choice remains closely tied to indication, severity, and monitoring intensity.
By Application / Indication Insights
Organ transplantation continues to represent a primary demand center because calcineurin inhibitors are embedded in standard immunosuppressive protocols designed to reduce rejection risk. Chronic maintenance requirements create recurring utilization across long follow-up horizons. Autoimmune disease use supports incremental expansion where systemic control is needed or steroid-sparing approaches are adopted. Treatment intensity and monitoring needs preserve specialist-led prescribing, sustaining stable demand across major applications.
By End User Insights
Hospitals remain central to therapy initiation and early post-transplant management due to the need for protocol oversight, lab monitoring, and dose optimization. Specialty clinics support long-term follow-up across transplantation, nephrology, dermatology, and rheumatology, reinforcing sustained refill patterns. Home healthcare strengthens adherence and continuity for chronic users through coordinated care and medication management. Academic and research institutes contribute by improving protocols and generating clinical evidence that supports optimized utilization.
By Distribution Channel Insights
Hospital pharmacy channels are critical during initiation phases and early post-transplant care, where monitoring intensity and inpatient dispensing remain common. Retail pharmacy channels support long-term maintenance refills as patients stabilize and transition to outpatient management. Online pharmacy growth is supported by home delivery convenience for chronic users, particularly in markets with robust e-pharmacy infrastructure. Channel mix is shaped by reimbursement, controlled dispensing rules, and specialist monitoring requirements.
Calcineurin Inhibitors Market Drivers
Expanding Solid-Organ Transplant Activity And Long-Term Maintenance Demand
Solid-organ transplantation remains a primary utilization engine for the Calcineurin Inhibitors Market because calcineurin inhibitors are embedded in standard immunosuppressive regimens. Long treatment durations and lifelong maintenance needs sustain recurring prescription volumes across transplant programs. Protocol-driven dosing, titration, and therapeutic monitoring increase continuity of therapy and reduce switching frequency in many settings. Growth is reinforced by expanding transplant capacity, improving follow-up pathways, and broader access to immunosuppressive medicines across developed and select emerging markets.
- For instance, Veloxis states that ENVARSUS XR uses MeltDose technology to deliver tacrolimus over 24 hours, with 50% greater bioavailability than Prograf or Astagraf XL and target trough levels achieved at a 20% lower total daily dose versus immediate-release tacrolimus in kidney transplant patients.
Rising Autoimmune Disease Burden Supporting Specialist Prescribing
Autoimmune diseases contribute to demand expansion as clinicians seek immune-modulating options that can complement or reduce long-term steroid exposure. Specialist-led prescribing in rheumatology, nephrology, and dermatology supports continued use where systemic control is required. Treatment persistence is supported by chronic disease management pathways and structured follow-up in specialty clinics. Broader access to diagnostics and specialist care increases the identifiable treated population, strengthening utilization across major autoimmune indications and supporting diversified demand beyond transplantation.
- For instance, Aurinia reported in the Phase 3 AURORA 1 study that LUPKYNIS (voclosporin) 23.7 mg twice daily, added to standard therapy, achieved a 41% complete renal response rate at 52 weeks versus 23% in the control arm across 357 enrolled patients, with efficacy separation observed as early as 4 weeks.
Wider Generic Availability And Formulary Access Expansion
Generic availability improves affordability and expands access across public health systems and price-sensitive markets, supporting higher treatment penetration. Hospital procurement and payer strategies increasingly emphasize cost-effective options when therapeutic equivalence confidence is high. Wider competition also supports more consistent supply coverage across strengths and dosage forms, reducing therapy interruptions for chronic users. Formulary inclusion and substitution policies can accelerate volume growth even when per-unit pricing declines, supporting overall demand expansion in high-population markets.
Dermatology Adoption Of Steroid-Sparing Immunomodulators
Topical calcineurin inhibitors support demand in dermatology where localized immunomodulation is preferred and steroid-sparing approaches are clinically valued. Chronic relapsing skin conditions drive repeat utilization in outpatient settings, supported by specialist guidance and patient education. Portfolio expansion in topical forms, patient-friendly packaging, and improved treatment adherence can strengthen refill continuity. Growth in dermatology is reinforced by rising awareness, improved access to specialists, and expanding patient preference for long-term management strategies with reduced steroid exposure.
Calcineurin Inhibitors Market Challenges
Pricing pressure and procurement-driven substitution remain persistent challenges for the Calcineurin Inhibitors Market, particularly in mature markets with high generic penetration. Narrow-therapeutic-index considerations can create cautious switching behavior, increasing complexity for substitution policies and requiring consistent monitoring practices. Reimbursement variability across countries can limit access, especially for newer or differentiated therapies in autoimmune indications. Competitive intensity also compresses margins, placing greater emphasis on efficient manufacturing, supply reliability, and disciplined portfolio management.
Safety monitoring requirements and adherence variability create additional constraints because calcineurin inhibitors require dose optimization and ongoing oversight in many systemic uses. Side-effect management, drug-drug interaction considerations, and patient follow-up intensity can limit initiation in lower-resource settings. Supply disruptions or quality events can disproportionately impact patient continuity, especially for transplant recipients with low tolerance for interruptions. These factors raise operational and regulatory expectations for manufacturers and providers across the therapy lifecycle.
- For instance, CareDx’s AlloSure Kidney platform was evaluated in 1,092 kidney transplant recipients across 7 transplant centers over a follow-up period of up to 3 years, demonstrating a 62% relative improvement over serum creatinine for rejection identification. It also detected elevated donor-derived cell-free DNA a median of 91 days before donor-specific antibody identification, underscoring the value of advanced monitoring technologies in long-term transplant care.
Calcineurin Inhibitors Market Trends and Opportunities
The Calcineurin Inhibitors Market is seeing increasing emphasis on differentiated formulations and adherence-supporting approaches that improve dosing consistency across chronic users. Extended-release options, optimized strength coverage, and improved patient support programs can strengthen real-world persistence where monitoring requirements remain high. Specialty-pharmacy models and coordinated care pathways can improve refill continuity, especially for transplant and severe autoimmune patients. These shifts create opportunities for manufacturers that combine reliable supply with portfolio breadth and service-driven differentiation.
- For instance, Veloxis Pharmaceuticals' LCP-tacrolimus (Envarsus XR) demonstrated a statistically significant reduction in non-adherence from 66% at study entry to 30.9% at 12 months post-conversion from twice-daily immediate-release tacrolimus, measured using the Basel Assessment of Adherence with Immunosuppressive Medications Scale (BAASIS; p < 0.001).
Emerging-market expansion remains a key opportunity as specialty infrastructure scales and access to transplant and autoimmune care improves. Growing specialist networks, increased diagnostic capacity, and improving reimbursement pathways can lift treatment penetration over time. E-pharmacy and outpatient dispensing growth can strengthen channel reach for chronic therapies, improving convenience for long-term users. Companies that align pricing strategy, regulatory execution, and localized distribution partnerships can improve access and sustain competitive positioning in high-growth geographies.
Regional Insights
North America
North America represented 35.6% share in 2025, supported by strong transplant center capacity, structured follow-up pathways, and mature therapeutic monitoring practices. Specialty prescribing across nephrology, dermatology, and rheumatology supports diversified use beyond transplantation. Reimbursement depth and established specialty pharmacy capabilities strengthen refill continuity for chronic users. Competitive dynamics emphasize supply reliability, therapeutic equivalence confidence, and portfolio breadth across strengths and dosage forms.
Europe
Europe accounted for 18.6% share in 2025, underpinned by established clinical pathways for transplantation and stable access through public reimbursement systems. Hospital procurement and tender mechanisms influence product mix, supporting steady generic penetration alongside select branded usage. Specialist-led follow-up models strengthen treatment persistence and monitoring adherence. Market performance remains shaped by country-level reimbursement variability and procurement-driven pricing dynamics.
Asia Pacific
Asia Pacific held 26.7% share in 2025, reflecting a mix of high population scale, expanding specialty infrastructure, and growing access to chronic immunosuppressive therapy. Growth is supported by rising transplant capability in major markets and increasing diagnosis and treatment of autoimmune diseases in specialty settings. Pricing sensitivity and reimbursement variation shape branded versus generic utilization by country. Strengthened distribution coverage and improving continuity of care can further lift treatment penetration across the region.
Latin America
Latin America accounted for 11.5% share in 2025, supported by expanding specialty access in major urban centers and increasing availability of cost-effective generics. Transplant programs in larger economies contribute steady demand, while autoimmune and dermatology indications support incremental outpatient utilization. Reimbursement constraints and uneven access remain limiting factors outside top-tier centers. Supply reliability and competitive pricing remain key determinants of volume growth across public and private channels.
Middle East & Africa
Middle East & Africa represented 7.6% share in 2025, driven by concentrated demand in higher-resource markets and select specialist hubs. Transplant and advanced autoimmune care remain unevenly distributed, shaping lower overall regional penetration. Access constraints, reimbursement variability, and affordability considerations influence therapy continuity in many settings. Distribution partnerships and localized supply strategies can support gradual expansion where specialty care capacity continues to develop.
Competitive Landscape
Competition in the Calcineurin Inhibitors Market is shaped by a balance between established branded franchises and high-volume generics, with differentiation increasingly centered on supply reliability, formulation breadth, and confidence in therapeutic equivalence. Manufacturers compete through portfolio coverage across strengths and dosage forms, regulatory execution, and alignment with hospital procurement and payer policies. Specialty-channel reach and patient support capabilities influence persistence in chronic users, particularly for transplant recipients. Quality systems and manufacturing resilience remain essential due to the clinical sensitivity of systemic immunosuppression.
Astellas Pharma maintains a strong presence through established tacrolimus-based products that are deeply embedded in transplant protocols, supported by long-standing clinical familiarity and structured monitoring practices. Portfolio positioning benefits from alignment with transplant center workflows and sustained specialist confidence in consistent dosing. Strategic focus emphasizes continuity of supply, lifecycle management across formulations, and reinforcing clinical confidence in settings where therapeutic switching requires careful oversight. Competitive response increasingly depends on balancing franchise defense with evolving procurement dynamics and expanding generic competition.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Astellas Pharma
- Viatris
- AbbVie
- Sandoz
- Glenmark
- Dr. Reddy’s Laboratories
- Biocon
- Lupin
- Novartis
- Roche
- Aurinia
- LEO Pharma
- Bausch Health
- Apotex
- Veloxis Pharmaceuticals
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In January 2026, Bora Pharmaceuticals announced that the U.S. FDA approved cyclosporine ophthalmic emulsion 0.05%, a generic equivalent of RESTASIS, and said the product will be marketed in the U.S. by its subsidiary Upsher-Smith.
- In December 2025, Nexus Pharmaceuticals announced the launch of Tacrolimus Injection, USP 5 mg/mL, describing it as the first and only tacrolimus vial-format product for prophylaxis of organ rejection in liver or kidney transplant patients.
- In December 2025, Amneal Pharmaceuticals announced U.S. FDA approval of cyclosporine ophthalmic emulsion 0.05%, the generic equivalent of RESTASIS, with commercial launch expected in Q1 2026.
- In January 2025, Biocon Pharma said China’s National Medical Products Administration approved its tacrolimus capsules in 0.5 mg, 1 mg, and 5 mg strengths, adding that the product would be commercialized in the region expeditiously.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 12,740 million |
| Revenue forecast in 2032 | USD 23,289.07 million |
| Growth rate (CAGR) | 9% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Drugs / Product Outlook: Tacrolimus, Cyclosporine, Pimecrolimus, Voclosporin, Others; By Drug Type Outlook: Branded, Generic; By Route of Administration Outlook: Oral, Topical, Parenteral, Others; By Dosage Form Outlook: Tablets & capsules, Ointments, Injections, Other dosage forms; By Application / Indication Outlook: Organ transplantation, Autoimmune disease, Other indications; By End User Outlook: Hospitals, Specialty clinics, Home healthcare, Academic & research institutes, Others; By Distribution Channel Outlook: Hospital pharmacy, Retail pharmacy, Online pharmacy, Others |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Astellas Pharma; Viatris; AbbVie; Sandoz; Glenmark; Dr. Reddy’s Laboratories; Biocon; Lupin; Novartis; Roche; Aurinia; LEO Pharma; Bausch Health; Apotex; Veloxis Pharmaceuticals |
| No.of Pages | 341 |
Segmentation
By Drugs / Product
- Tacrolimus
- Cyclosporine
- Pimecrolimus
- Voclosporin
- Others
By Drug Type
- Branded
- Generic
By Route Of Administration
- Oral
- Topical
- Parenteral
- Others
By Dosage Form
- Tablets & capsules
- Ointments
- Injections
- Other dosage forms
By Application / Indication
- Organ transplantation
- Autoimmune disease
- Other indications
By End User
- Hospitals
- Specialty clinics
- Home healthcare
- Academic & research institutes
- Others
By Distribution Channel
- Hospital pharmacy
- Retail pharmacy
- Online pharmacy
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Calcineurin Inhibitors Market in 2025 and its outlook for 2032?
What is the CAGR for the Calcineurin Inhibitors Market during 2025–2032?
Which segment is the largest in the Calcineurin Inhibitors Market?
What factors are driving growth in the Calcineurin Inhibitors Market?
Who are the leading companies in the Calcineurin Inhibitors Market?
Which region leads the Calcineurin Inhibitors Market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 12,740 million → 2032: USD 23,289.07 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Calcineurin Inhibitors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Calcineurin Inhibitors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Calcineurin Inhibitors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Calcineurin Inhibitors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Calcineurin Inhibitors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Calcineurin Inhibitors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Calcineurin Inhibitors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Calcineurin Inhibitors Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 12,740 million → 2032: USD 23,289.07 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Calcineurin Inhibitors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Calcineurin Inhibitors Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Calcineurin Inhibitors Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Calcineurin Inhibitors Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

