
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Canada Healthcare Supply Chain Management Market Size 2024 | USD 93.49 million |
| Canada Healthcare Supply Chain Management Market, CAGR | 11.59 % |
| Canada Healthcare Supply Chain Management Market Size 2032 | USD 224.80 million |
Market Overview
The Canada Healthcare Supply Chain Management Market is projected to grow from USD 93.49 million in 2024 to an estimated USD 224.80 million by 2032, with a compound annual growth rate (CAGR) of 11.59 % from 2025 to 2032. This robust expansion reflects escalating demand for efficient logistics, inventory optimization, and end-to-end visibility across hospitals, clinics, and long-term care facilities.
Market drivers include mounting pressure to contain operational expenses and ensure regulatory compliance, while trends center on the integration of IoT-enabled sensors, artificial intelligence (AI)-driven demand forecasting, and blockchain-based traceability solutions. Providers increasingly adopt predictive analytics to anticipate usage patterns of critical medical supplies and pharmaceuticals, thereby curbing waste and expediting replenishment cycles. Concurrently, mobile-friendly dashboards and real-time tracking tools are gaining traction, empowering supply chain managers to make data-backed decisions and streamline order fulfillment processes.
Regionally, Ontario dominates the Canada Healthcare Supply Chain Management Market due to its concentration of tertiary care centres and large-scale research hospitals, followed by Quebec and British Columbia, where provincial health authorities are investing in centralized distribution hubs. Western provinces, led by Alberta and Saskatchewan, are pilots for AI-augmented logistics networks, while Atlantic Canada focuses on cross-province collaboration to overcome geographic dispersion. Key players driving market innovation include McKesson Canada, Cardinal Health, GHX, Oracle’s Cerner, and SAP, all of which offer comprehensive platforms tailored to Canada’s regulatory framework and bilingual requirements.
Market Insights
- The Canada Healthcare Supply Chain Management Market will grow from USD 93.49 million in 2024 to USD 224.80 million by 2032, reflecting a CAGR of 11.59 percent.
- Mounting pressure to contain operational expenses drives adoption of cloud-based SCM platforms and AI-driven demand forecasting.
- Strict Health Canada regulations on traceability and cold-chain integrity create compliance obligations and audit challenges for providers.
- Aging demographics and rising patient volumes force organizations to modernize procurement workflows and inventory controls.
- Ontario leads market penetration with centralized distribution hubs, while Quebec and British Columbia prioritize bilingual, compliant solutions.
- Western provinces pilot AI-augmented logistics and cold-chain monitoring to extend reach into remote and rural areas.
- Atlantic Canada leverages shared-services models and cross-provincial procurement to reduce costs and strengthen supply resilience.
Report Scope
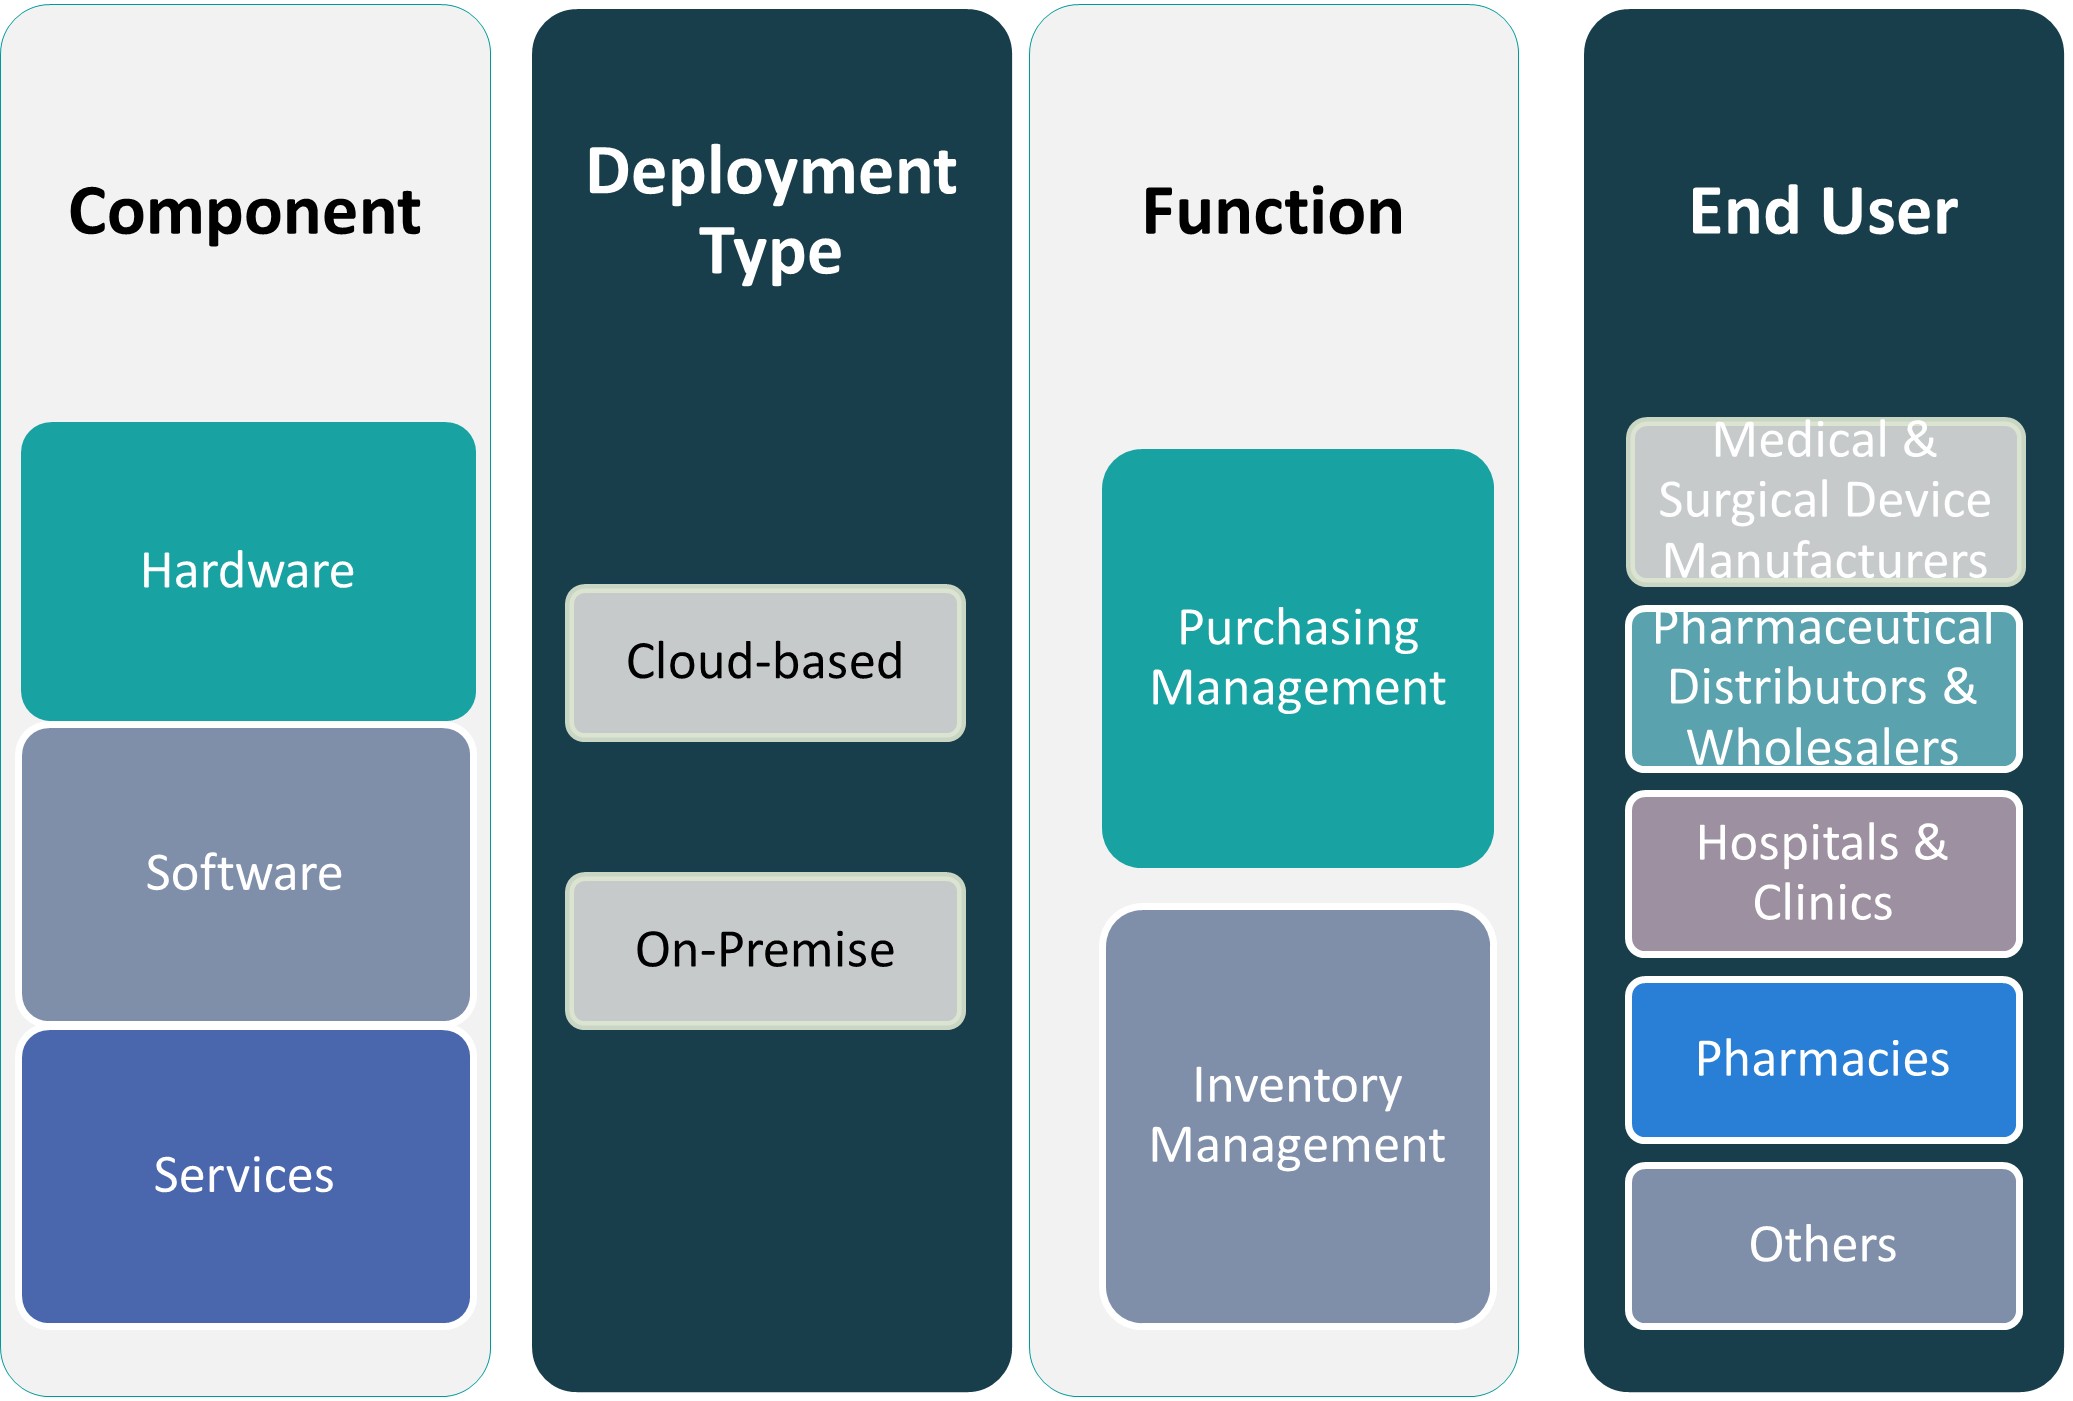
This report segments the Canada Healthcare Supply Chain Management Market as follows:
Market Drivers
Escalating Demand for Digital Supply Chain Solutions
Healthcare providers face mounting pressure to adopt advanced logistics platforms. The Canada Healthcare Supply Chain Management Market emphasizes implementation of cloud-based systems that centralize procurement workflows and data analytics. Stakeholders deploy real-time tracking tools to improve order accuracy and reduce lead times. It enables seamless coordination among distributors, manufacturers, and care facilities. Integrated dashboards support data-driven decision making for critical inventory levels. Providers scale operations without heavy capital outlay by leveraging software-as-a-service models. Vendors enhance interoperability with existing hospital information systems to drive faster adoption.
- For instance, the Canadian government allocated 200 million toward digital health transformation in 2023, emphasizing supply chain modernization initiatives.
Governmental Regulations Driving System Upgrades
Recent policy mandates require transparent reporting on medical supplies and device provenance. The Canada Healthcare Supply Chain Management Market reflects a shift toward compliance-focused software that automates audit trails. Health agencies audit procurement records to ensure patient safety and regulatory adherence. Suppliers integrate serialization features to track products from manufacturer to end user. It strengthens recall management and minimizes counterfeit risks. Regulatory bodies push for standardized data formats to facilitate cross-jurisdictional oversight. Organizations accelerate vendor qualification processes to meet evolving legal requirements.
- For instance, Health Canada implemented new tracking requirements for medical devices in 2023, enhancing safety monitoring and regulatory compliance.
Growing Need for Inventory Visibility and Risk Mitigation
Unplanned stockouts of essential drugs and equipment jeopardize patient care. The Canada Healthcare Supply Chain Management Market prioritizes predictive analytics that forecast demand based on historical usage patterns. Supply chain leaders conduct risk assessments to identify bottlenecks and single points of failure. It empowers logistics teams to preposition critical items in regional hubs. Automated alerts trigger replenishment orders when thresholds fall below safe levels. Organizations adopt multi-sourcing strategies to diversify vendor networks. Enhanced visibility reduces overstock expenses and safeguards against supply disruptions.
Pressure to Contain Costs and Optimize Procurement
Budget constraints compel healthcare networks to seek cost-effective sourcing solutions. The Canada Healthcare Supply Chain Management Market drives adoption of contract management modules that enforce negotiated pricing and volume discounts. Procurement teams centralize purchasing decisions to leverage bulk-buy advantages. It supports approval workflows that prevent maverick spending and contract leakage. Analytics tools benchmark supplier performance and identify opportunities for cost reduction. Hospitals refine vendor scorecards to reward on-time deliveries and quality compliance. Continuous monitoring of spend data uncovers inefficiencies and guides strategic sourcing.
Market Trends
Integration of Advanced Analytics and IoT for Real-Time Visibility
Healthcare providers adopt advanced analytics and IoT to track shipments in real time. The Canada Healthcare Supply Chain Management Market demands solutions that integrate AI-driven demand forecasting with sensor-based asset monitoring. It reduces lead times and minimizes stock discrepancies across hospitals and clinics. Vendors integrate robotics for automated warehouses to improve order accuracy. It supports centralized dashboards that deliver actionable insights on inventory performance. Stakeholders partner with software firms to leverage blockchain for secure data sharing and product traceability. Executives evaluate platform interoperability to streamline workflows and accelerate deployment.
- For instance, over 1,500 healthcare facilities in Canada implemented IoT-based inventory tracking systems last year, improving supply chain efficiency and reducing stock discrepancies.
Emphasis on Sustainability and Decentralized Distribution Models
Health systems pursue eco-friendly packaging and route optimization to lower carbon footprint. The Canada Healthcare Supply Chain Management Market reflects pressure to implement green policies across procurement and logistics. It drives adoption of temperature-controlled transport networks to safeguard biologics and vaccines. Providers develop multi-tier distribution networks to support telehealth and home-based care. It enhances patient convenience and reduces reliance on centralized warehouses. Supply chain leaders invest in vendor scorecards that include sustainability and service reliability metrics. They explore collaborative platforms that connect rural facilities with urban distribution centers.
- For instance, a government-backed initiative in Canada reported that over 1,200 healthcare providers adopted sustainable packaging solutions in their supply chain operations, reducing environmental impact.
Market Challenges
Navigating Complex Regulatory Compliance and Traceability Requirements
Hospitals and health authorities face rigorous federal and provincial regulations that dictate every step of procurement and distribution. The Canada Healthcare Supply Chain Management Market must comply with Health Canada mandates for product quality, cold-chain management, and recall procedures. Stakeholders maintain audit-ready records for inspections and internal reviews. Complex reporting demands create administrative burden for procurement teams and divert focus from patient care. IT teams work to integrate legacy EHR systems with new supply-chain platforms. Inconsistent data formats and disparate systems hamper end-to-end visibility. Procurement staff require specialized training to operate advanced tracking tools.
- For instance, over 75% of Canadian healthcare facilities have adopted digital supply chain solutions to improve procurement efficiency and compliance
Balancing Cost Containment Pressures with Operational Resilience
The Canada Healthcare Supply Chain Management Market faces relentless pressure to reduce costs while ensuring continuous availability of medical supplies. Fluctuating demand for pharmaceuticals and surgical kits creates risks of overstock or shortage. It challenges budget planning and ties up working capital in excess inventory. Supply chain leaders negotiate vendor-managed inventory agreements to share risk with suppliers. They build predictive analytics into purchasing workflows, which demands significant upfront investment. Smaller facilities struggle to secure scalable solutions under tight financial constraints. Diverse regional infrastructures further complicate standardization of logistics processes.
Market Opportunities
Expanding Digital Integration and Predictive Analytics Adoption
The Canada Healthcare Supply Chain Management Market can leverage growing demand for unified digital platforms to improve inventory forecasting. Cloud-native solutions provide real-time dashboards that boost operational visibility across hospitals and clinics. It supports predictive analytics that align purchase schedules with patient care demands. Standardized data exchange between EHRs and procurement systems cuts manual errors and saves labor. Stakeholders can pilot AI-assisted replenishment tools to reduce stockouts without large capital outlays. Early adopters gain competitive edge by demonstrating supply resilience. Providers that embrace these innovations strengthen their financial performance.
Leveraging Strategic Partnerships and Vendor-Managed Inventory Models
Strategic collaboration between healthcare facilities and vendors unlocks flexible inventory models and risk-sharing agreements. The Canada Healthcare Supply Chain Management Market can expand vendor-managed inventory programs to lower holding costs. It enables custom service-level agreements that match supply cadence to fluctuating demand. Engaging third-party logistics providers enhances distribution reach in remote and rural regions. Partnerships with technology firms deliver tailored solutions that address local regulatory requirements. Shared investment in training programs raises proficiency with advanced supply tools. Coordinated networks boost negotiation power and enable volume discounts.
Market Segmentation Analysis
By Component
The Canada Healthcare Supply Chain Management Market splits into hardware, software, and services. Hardware includes barcode scanners, RFID readers, and IoT sensors that ensure traceability. Software delivers inventory dashboards, analytics modules, and procurement workflows. Services cover consulting, training, and system integration to optimize supply operations and maximize return on investment.
By Deployment Type
The Canada Healthcare Supply Chain Management Market offers cloud-based and on-premise solutions. Cloud-based platforms grant real-time access, seamless updates, and rapid scalability. On-premise installations give organizations direct control over data security and system customization. Providers select deployment models that match IT resources, compliance requirements, and budget parameters.
Segments
Based on Component
- Hardware
- Software
- Services
Based on Deployment Type
- Cloud-based
- On-Premis
Based on Function
- Purchasing Management
- Inventory Management
Based on End User
- Medical & Surgical Device Manufacturers
- Pharmaceutical Distributors & Wholesalers
- Hospitals & Clinics
- Pharmacies
- Others
Based on Region
- Ontario
- British Columbia
- Quebec
Regional Analysis
Ontario and Quebec Drive Market Penetration through Large-Scale Implementations
The Canada Healthcare Supply Chain Management Market gains momentum in Ontario, where major hospitals and research centres adopt centralized distribution hubs. It improves order accuracy and reduces lead times for high-demand items. Quebec’s health authorities champion bilingual platforms that support both English and French documentation. They invest in training programs that empower procurement teams to operate advanced tracking tools. Provincial partnerships with technology vendors secure preferential pricing on SaaS solutions. These initiatives establish Ontario and Quebec as primary hubs for supply chain innovation and set benchmarks for other regions.
Wesrn Provinces Emphasize Collaborative Pilots and Technology Trials
The Canada Healthcare Supply Chain Management Market finds fertile ground in Alberta, British Columbia, and Saskatchewan. It benefits from pilot programs that explore AI-driven demand forecasting and robotics in warehouse operations. Health networks partner with local universities to validate real-time monitoring technologies under cold-chain conditions. Joint ventures with logistics firms extend reach into remote communities and First Nations territories. Provincial health ministries fund proof-of-concept projects that test interoperability between legacy EHR systems and new supply platforms. These efforts pave the way for scalable deployments across dispersed populations.
Atlantic Provinces Invest in Cross-Provincial Standardization and Shared Services
The Canada Healthcare Supply Chain Management Market receives focused attention in New Brunswick, Nova Scotia, Prince Edward Island, and Newfoundland and Labrador. It leverages shared-service models to consolidate purchasing and reduce per-unit costs. Provincial regulators approve uniform compliance frameworks that simplify audit processes across borders. Health authorities coordinate bulk tenders for high-volume commodities like PPE and vaccines. Regional consortia negotiate volume-based contracts with device manufacturers and distributors. This cooperative approach strengthens supply resilience and maximizes value for smaller care facilities.
Key players
- Oracle Corporation
- SAP SE
- McKesson Corporation
- Cardinal Health
- TECSYS Inc.
Competitive Analysis
The Competitive Analysis of the Canada Healthcare Supply Chain Management Market reveals intense rivalry among leading vendors, each leveraging distinct strengths to win clients. Oracle Corporation offers a unified cloud platform with advanced analytics and real-time inventory forecasting. SAP SE delivers modular software tailored to hospital logistics, procurement workflows, and compliance tracking. McKesson Corporation combines a comprehensive distribution network with consultative deployment services that optimize order fulfillment. Cardinal Health pairs its software solutions with strategic consulting and vendor-managed inventory programs to minimize stockouts. TECSYS Inc. focuses on warehouse automation and dynamic order management, providing configurable workflows for diverse facility sizes. It drives each provider to refine pricing strategies, bolster platform functionality with IoT-enabled tracking, and expand mobile access. Providers compete by offering deep service customization and data-driven insights that improve decision making. Future leadership will require seamless integration with electronic health records and demonstrable cost savings in procurement and distribution processes.
Recent Developments
- On Feb 9, 2023, McKesson Canada is pleased to announce the appointment of veteran executive Joan Eliasek as President of McKesson Canada. Eliasek succeeds Rebecca McKillican who has led the company since August 2020
- On March 5, 2025, in its Q3 FY2025 report (ended January 31, 2025), Tecsys posted record quarterly revenue of $45.2 M, with SaaS revenue up 22% to $17.3 M.
Market Concentration and Characteristics
The Canada Healthcare Supply Chain Management Market exhibits moderate concentration, with a handful of global and national vendors capturing the majority of contracts. It features leading providers such as McKesson Canada, Cardinal Health, GHX, Oracle’s Cerner, and SAP that leverage comprehensive solution suites and extensive service networks. Mid-tier players and niche specialists address specific needs-such as cold-chain monitoring or blockchain traceability-while regional integrators tailor platforms to provincial regulations. High implementation costs and deep integration with electronic health record systems create significant barriers for new entrants. Contract renewals and vendor-managed inventory agreements reinforce customer loyalty. This structure drives continuous innovation and competitive pricing, ensuring that hospitals and distributors receive robust support for complex supply operations.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Type, Function, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outloo
- The Canada Healthcare Supply Chain Management Market will integrate advanced AI models to refine demand forecasting and minimize stock discrepancies. It will empower procurement teams with real-time insights for precise order planning.
- Providers will expand blockchain-based traceability solutions to secure product provenance and prevent counterfeit entry. They will offer immutable audit trails that satisfy stringent regulatory standards.
- It will adopt modular, microservices-driven architectures that accelerate feature deployment and simplify system upgrades. Clients will benefit from reduced downtime and predictable maintenance cycles.
- The market will see growing partnerships between healthcare networks and last-mile logistics specialists. These alliances will enhance delivery speed to remote clinics and home-care settings.
- Vendors will develop user-centric mobile applications that streamline order approvals and receipt confirmations at the point of care. They will reduce reliance on desktop portals and paper processes.
- It will embrace predictive maintenance of cold-chain equipment through IoT sensor analytics. Facilities will avoid product spoilage by scheduling preemptive service interventions.
- The Canada Healthcare Supply Chain Management Market will leverage digital twins of distribution centres to simulate process optimizations. Managers will test layout changes virtually before physical implementation.
- Companies will offer embedded sustainability metrics within supply platforms to track carbon emissions per shipment. Hospitals will monitor environmental impact alongside operational KPIs.
- It will support multi-enterprise networks that share inventory pools across regions to balance surplus and shortage. Health authorities will coordinate allocations during crisis events.
- The market will invest in role-based training modules delivered via immersive VR simulations. Staff will gain hands-on experience with new tools in a risk-free virtual environment.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Escalating Demand for Digital Supply Chain Solutions
Healthcare providers in Canada are rapidly adopting cloud-based and AI-driven supply chain management platforms to centralize procurement, improve order accuracy, and reduce lead times. This digital transformation is driven by the need for real-time visibility and seamless coordination among distributors, manufacturers, and care facilities.
Governmental Regulations Driving System Upgrades
Stringent Health Canada regulations on traceability, cold-chain integrity, and audit trails are compelling providers to upgrade to compliance-focused software. Automated tracking and standardized data formats are now essential to meet evolving legal requirements and ensure patient safety.
Growing Need for Inventory Visibility and Risk Mitigation
Unplanned stockouts and supply disruptions have highlighted the necessity for predictive analytics and risk assessment tools. Enhanced inventory visibility allows healthcare organizations to preposition critical items, automate replenishment, and diversify vendor networks, reducing both overstock expenses and supply chain vulnerabilities.
Pressure to Contain Costs and Optimize Procurement
Budget constraints across Canadian healthcare networks are driving the adoption of contract management modules, centralized purchasing, and analytics tools. These solutions help enforce negotiated pricing, prevent maverick spending, and identify cost-saving opportunities, supporting operational efficiency.
Integration of Advanced Analytics and IoT for Real-Time Visibility
The adoption of IoT-enabled sensors, AI-driven demand forecasting, and blockchain-based traceability is transforming supply chain operations. Real-time tracking and analytics improve order accuracy, minimize stock discrepancies, and support data-driven decision making across hospitals and clinics.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size in 2023, what will it be by 2032, and what is the CAGR?
What factors are driving the growth of the Canada Healthcare Supply Chain Management market?
What are the key segments within the Canada Healthcare Supply Chain Management market?
Who are the major players in the Canada Healthcare Supply Chain Management market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Medical & Surgical Device Manufacturers
- 1.2.2 Pharmaceutical Distributors & Wholesalers
- 1.2.3 Hospitals & Clinics
- 1.2.4 Pharmacies
- 1.2.5 Others
- 1.3 By Function
- 1.3.1 Purchasing Management
- 1.3.2 Inventory Management
- 1.4 By Component
- 1.4.1 Hardware
- 1.4.2 Software
- 1.4.3 Services
- 1.5 By Deployment Type
- 1.5.1 Cloud-based
- 1.5.2 On-Premise
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 83.8 million → 2032: USD 224.80 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Canada Healthcare Supply Chain Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Canada Healthcare Supply Chain Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Canada Healthcare Supply Chain Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Canada Healthcare Supply Chain Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Canada Healthcare Supply Chain Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Canada Healthcare Supply Chain Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Canada Healthcare Supply Chain Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Canada Healthcare Supply Chain Management Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 83.8 million → 2032: USD 224.80 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Canada Healthcare Supply Chain Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Medical & Surgical Device Manufacturers
- 12.3.7.2 Pharmaceutical Distributors & Wholesalers
- 12.3.7.3 Hospitals & Clinics
- 12.3.7.4 Pharmacies
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Function - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Purchasing Management
- 12.4.7.2 Inventory Management
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Component - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hardware
- 12.5.7.2 Software
- 12.5.7.3 Services
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Deployment Type - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Cloud-based
- 12.6.7.2 On-Premise
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Canada Healthcare Supply Chain Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Canada Healthcare Supply Chain Management Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Canada Healthcare Supply Chain Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Canada Healthcare Supply Chain Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 McKesson Canada
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cardinal Health
- 18.4 GHX
- 18.5 Oracle Cerner
- 18.6 SAP SE
- 18.7 TECSYS Inc.
- 18.8 Infor
- 18.9 Descartes Systems Group
- 18.10 IBM
- 18.11 Siemens Healthineers
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

