
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Canada Personalized Gift Card Market Size 2024 | USD 893.89 million |
| Canada Personalized Gift Card Market, CAGR | 8.7% |
| Canada Personalized Gift Card MarketSize 2032 | USD 1,895.12 million |
Market Overview
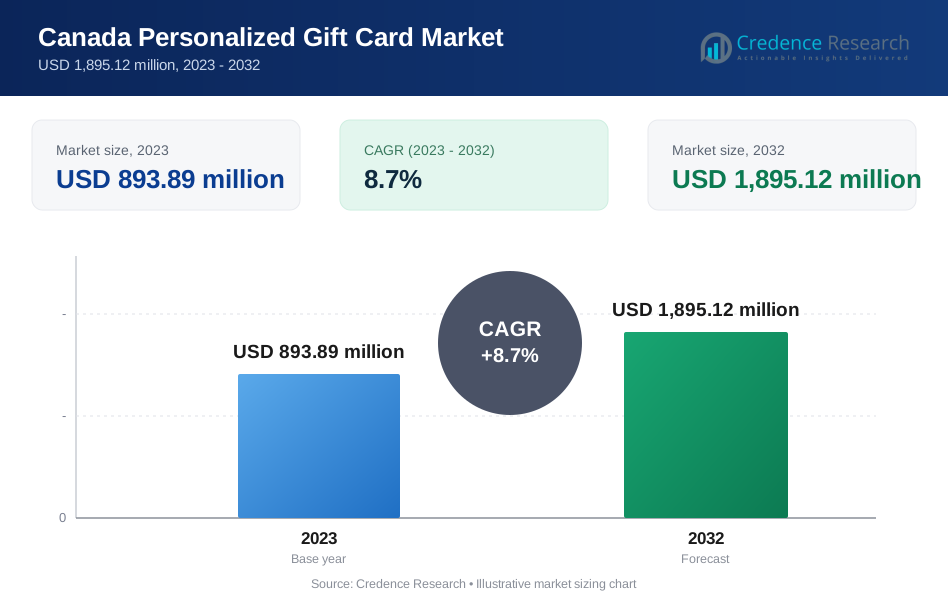
Canada Personalized Gift Card market size was valued at USD 893.89 million in 2023 and is anticipated to reach USD 1,895.12 million by 2032, at a CAGR of 8.7% during the forecast period (2023-2032).
The Canada Personalized Gift Card Market is driven by the growing preference for customized gifting solutions, fueled by rising disposable income and increasing consumer inclination toward personalized experiences. Businesses and retailers are leveraging personalized gift cards as strategic tools for customer engagement and brand loyalty, further accelerating market growth. The integration of digital technologies, such as AI-driven customization and blockchain for secure transactions, enhances the appeal of personalized gift cards. E-commerce expansion and mobile payment adoption also contribute to market growth, making digital gift cards more accessible and versatile. Additionally, the demand for corporate gifting solutions is increasing, as businesses use personalized gift cards for employee rewards and client retention. Key market trends include the rise of eco-friendly digital gift cards, enhanced security features, and seamless omnichannel redemption experiences, ensuring convenience for both consumers and retailers. These factors collectively propel the market’s expansion across Canada.
The Canada Personalized Gift Card Market is witnessing significant growth across various regions, with Ontario, Quebec, Western Canada, and British Columbia driving demand. Ontario and Quebec benefit from strong retail and digital payment infrastructures, while Western Canada and British Columbia see increasing adoption of digital and eco-friendly gift card solutions. Businesses in these regions are leveraging technological advancements, including mobile wallets and AI-driven personalization, to enhance customer experiences. Key players in the market include Cardly, Canada Post Corporation, Walmart Inc., Fiserv Inc., Givex Corporation, Paytronix Systems, Inc., CafePress Inc., Blackhawk Network, InComm Payments LLC, American Express Company, Mars Incorporated, Shutterfly, American Greetings Corporation, Etsy Inc., and Amazon.com Inc. These companies focus on expanding their digital offerings, improving security, and enhancing customer engagement through innovative, customizable gift card solutions. As e-commerce and corporate gifting trends continue to grow, market players are expected to strengthen their presence and introduce more personalized gifting options.
Market Insights
- The Canada Personalized Gift Card Market was valued at USD 893.89 million in 2023 and is projected to reach USD 1,895.12 million by 2032, growing at a CAGR of 8.7% from 2023 to 2032.
- Increasing demand for customized and digital gift cards is driven by rising e-commerce adoption and corporate gifting trends.
- Consumers prefer digital gift cards due to convenience, personalization options, and seamless integration with mobile wallets.
- Leading market players focus on expanding digital offerings, enhancing security, and improving customer engagement.
- Challenges include concerns over fraud, cybersecurity threats, and limited acceptance of certain gift card types.
- Ontario and Quebec dominate the market due to strong retail and digital payment infrastructure, while Western Canada and British Columbia experience growing adoption of digital and eco-friendly gift cards.
- The competitive landscape includes key players like Cardly, Walmart Inc., Fiserv Inc., Givex Corporation, Blackhawk Network, Amazon.com Inc., and others focusing on technological advancements and expanding distribution channels.
Market Drivers
Rising Demand for Personalized Gifting Solutions
The increasing consumer preference for customized and meaningful gifting options is a key driver of the Canada Personalized Gift Card Market. Shoppers are moving away from traditional gifts and seeking more personalized options that add a unique touch to their presents. Personalized gift cards offer the flexibility of choice while allowing recipients to enjoy a customized gifting experience. The ability to add personal messages, images, and designs enhances their appeal, making them a preferred option for birthdays, anniversaries, corporate gifting, and other special occasions. This shift in consumer behavior, driven by the desire for meaningful connections and thoughtful presents, is significantly contributing to the growth of the market.
Corporate Adoption and Brand Loyalty Strategies
Businesses and corporations are increasingly adopting personalized gift cards as part of their marketing and employee engagement strategies. Companies use customized gift cards for employee rewards, incentives, and client appreciation, recognizing their effectiveness in enhancing customer retention and brand loyalty. For instance, a study by a prominent human resources consulting firm revealed that a majority of Canadian employees feel more valued when receiving personalized rewards. Retailers and service providers leverage these gift cards to drive customer engagement, offering promotions and discounts that encourage repeat purchases. Additionally, co-branded and promotional gift cards featuring personalized branding elements help businesses strengthen customer relationships and expand their market presence. The corporate sector’s growing reliance on these solutions is expected to sustain the market's expansion in the coming years.
Technological Advancements and Digital Transformation
The rapid adoption of digital payment technologies and AI-driven personalization tools is revolutionizing the personalized gift card market in Canada. The integration of AI enables businesses to offer tailored recommendations based on consumer preferences, enhancing the customization experience. Furthermore, blockchain technology is improving transaction security and fraud prevention, making digital gift cards more reliable. Mobile wallet integration and contactless payment solutions further boost market demand by ensuring convenient transactions. The growing influence of e-commerce platforms and digital marketplaces has also accelerated the shift toward digital and virtual gift cards, driving their widespread adoption among consumers and businesses alike.
Growing Popularity of Eco-Friendly and Digital Gift Cards
Sustainability concerns are influencing consumer preferences, leading to increased demand for eco-friendly and digital gift cards. Many consumers are opting for paperless or biodegradable gift cards as part of their commitment to environmental responsibility. For instance, a survey conducted by an environmental organization found that a significant number of Canadian consumers prioritize eco-friendly options when making purchasing decisions. Retailers and gift card providers are responding by introducing recyclable or digital alternatives to reduce plastic waste. Additionally, digital gift cards eliminate the need for physical production and logistics, making them a cost-effective and environmentally friendly solution. The shift towards sustainability aligns with broader industry trends, further propelling the adoption of digital and personalized gift cards in Canada.
Market Trends
Increasing Adoption of Digital and Virtual Gift Cards
The shift toward digitalization is significantly influencing the Canada Personalized Gift Card Market, with consumers and businesses preferring digital and virtual gift cards over traditional physical ones. The growing reliance on mobile wallets and e-commerce platforms has made digital gift cards more accessible and convenient for gifting purposes. Consumers appreciate the ease of purchasing and sending these cards via email or mobile applications, eliminating the need for physical handling. Additionally, retailers are integrating personalized digital gift cards into their loyalty programs, offering customers seamless redemption experiences across multiple channels. This trend is expected to drive sustained market growth in the coming years.
Expanding Use of Personalized Gift Cards in Corporate Gifting
The corporate sector is increasingly recognizing the value of personalized gift cards for employee rewards, customer appreciation, and promotional campaigns. For instance, data from human resource departments shows that personalized gift cards are among the most popular employee incentives. Businesses are using customized gift cards as part of their incentive programs, allowing employees to choose their preferred rewards. Additionally, companies are integrating personalized gift cards into customer loyalty programs to strengthen engagement and retention. The ability to customize corporate gift cards with branding elements, personalized messages, and tailored offers makes them a powerful marketing tool. As businesses continue to invest in personalized gifting solutions, the demand for customized gift cards in the corporate sector is expected to grow substantially.
Rising Integration of AI and Personalization Technologies
Artificial Intelligence (AI) and machine learning are transforming how personalized gift cards are created and marketed. AI-driven platforms enable businesses to offer dynamic personalization options, such as customized designs, messages, and even tailored gift card recommendations based on user behavior and purchase history. Retailers are leveraging AI to enhance customer engagement by providing targeted promotions and personalized discounts through digital gift cards. This technological advancement ensures a more interactive and meaningful gifting experience, encouraging wider consumer adoption and increasing brand loyalty.
Growing Demand for Sustainable and Eco-Friendly Gift Cards
Sustainability is a key trend influencing the personalized gift card market in Canada, as consumers and businesses seek environmentally friendly alternatives. The rising awareness of plastic waste has led to the introduction of biodegradable, recycled, and digital gift card options. Many retailers are shifting towards paperless transactions and virtual gift cards to align with sustainability goals while reducing production and distribution costs. Consumers are also showing a preference for brands that prioritize environmental responsibility, making eco-friendly gift card solutions an important factor in market expansion. This trend is expected to gain further momentum as companies emphasize corporate social responsibility initiatives.
Market Challenges Analysis
Security Concerns and Fraud Risks
One of the primary challenges facing the Canada Personalized Gift Card Market is the increasing risk of fraud and security breaches. Digital and virtual gift cards, while convenient, are vulnerable to cyber threats such as hacking, phishing attacks, and unauthorized access. Fraudsters often target digital gift card systems due to their monetary value and ease of transfer, leading to financial losses for both consumers and businesses. Additionally, insufficient security measures can result in counterfeit gift cards and balance theft, eroding consumer trust. To mitigate these risks, companies must invest in robust security protocols, including encryption, tokenization, and multi-factor authentication. However, implementing these measures can increase operational costs, posing a challenge for smaller retailers and independent businesses looking to offer personalized gift card services.
High Competition and Market Saturation
The growing popularity of personalized gift cards has led to intense competition among retailers, financial institutions, and third-party providers. Established brands dominate the market with extensive customization options, competitive pricing, and widespread distribution networks, making it challenging for new entrants to gain traction. For instance, market studies reveal that a significant portion of the gift card market share is held by major retailers and e-commerce platforms. Additionally, the increasing availability of alternative gifting options, such as subscription services and experience-based gifts, further intensifies market saturation. To stay competitive, businesses must continuously innovate by offering unique personalization features, seamless omnichannel experiences, and value-added services. However, maintaining differentiation in a crowded market requires ongoing investment in technology and marketing, which can be a barrier for smaller players with limited resources.
Market Opportunities
The Canada Personalized Gift Card Market presents significant growth opportunities driven by the increasing integration of advanced digital technologies. Businesses can leverage artificial intelligence (AI) and data analytics to enhance personalization, offering tailored gift card recommendations based on consumer preferences and purchase history. The growing adoption of mobile wallets and contactless payment solutions also creates opportunities for seamless digital gift card transactions, improving user convenience and engagement. Additionally, blockchain technology offers a secure and transparent way to manage gift card transactions, reducing fraud risks and enhancing consumer trust. Companies that invest in these technological advancements can differentiate themselves and capture a larger share of the evolving market.
Another major opportunity lies in the expanding corporate gifting sector, where personalized gift cards are increasingly used for employee rewards, client appreciation, and promotional campaigns. Businesses are recognizing the value of customized gift cards as a flexible and effective tool for engagement, driving demand across various industries. Furthermore, the rising consumer preference for eco-friendly solutions provides an avenue for retailers to introduce sustainable, biodegradable, or fully digital gift card options. By aligning with environmental and corporate social responsibility initiatives, companies can appeal to eco-conscious consumers and strengthen brand loyalty. As personalization trends continue to evolve, businesses that offer innovative, customizable gift card solutions will gain a competitive edge in Canada’s growing market.
Market Segmentation Analysis:
By Type:
The Canada Personalized Gift Card Market is segmented into closed-loop and open-loop gift cards, each catering to different consumer and business needs. Closed-loop gift cards are retailer-specific, allowing customers to make purchases exclusively at the issuing brand's stores or platforms. These cards are widely used by businesses for customer retention, promotional offers, and loyalty programs, as they encourage repeat purchases within the brand’s ecosystem. Retailers benefit from closed-loop cards by gaining insights into customer spending habits, enabling targeted marketing strategies. On the other hand, open-loop gift cards provide greater flexibility, as they are typically issued by financial institutions and can be used at multiple locations, including online and in-store purchases. Consumers prefer open-loop gift cards for their convenience and broad usability, making them a popular choice for corporate gifting and personal use. As digital payment adoption continues to rise, the demand for both types of personalized gift cards is expected to grow, with open-loop cards gaining significant traction due to their versatility.
By Distribution Channel:
The market is also segmented based on distribution channels, including online and offline platforms, each playing a crucial role in the accessibility of personalized gift cards. Online distribution channels have gained significant prominence due to the widespread adoption of e-commerce and mobile payment solutions. Consumers increasingly prefer digital gift cards, as they offer instant delivery, easy customization, and seamless redemption through email, mobile apps, or digital wallets. Retailers leverage online platforms to enhance personalization options, allowing customers to design and purchase gift cards with custom messages, images, and brand-specific themes. Meanwhile, offline distribution channels, including retail stores, supermarkets, and financial institutions, continue to serve a large customer base. Physical gift cards remain popular, especially for in-store purchases and corporate gifting, where tangible presentation adds value. While online channels are driving market expansion, offline distribution still holds relevance for consumers who prefer traditional purchasing methods, ensuring a balanced growth trajectory across both segments.
Segments:
Based on Type:
- Closed-loop gift cards
- Open-loop gift cards
Based on Distribution Channel:
- Online
- Offline
Based on Form:
- Virtual
- Physical
Based on End User:
- Retail consumers
- Corporate institutions
Based on the Geography:
- Ontario
- Quebec
- Western Canada
- British Columbia
- Atlantic Canada
Regional Analysis
Ontario
Ontario holds the largest share in the Canada Personalized Gift Card Market, accounting for approximately 35% of the total market. The province's dominance is driven by its high population density, strong retail sector, and widespread adoption of digital payment solutions. Major urban centers such as Toronto and Ottawa serve as hubs for e-commerce, financial institutions, and corporate headquarters, fueling demand for both closed-loop and open-loop personalized gift cards. The increasing use of digital wallets and online transactions has further strengthened the online distribution of gift cards in Ontario. Additionally, businesses are integrating personalized gift cards into their customer loyalty programs and promotional campaigns, contributing to the market’s expansion.
Quebec
Quebec follows as the second-largest regional market, representing around 25% of the total share. The province's strong consumer spending habits and growing digital commerce ecosystem drive significant demand for personalized gift cards. Montreal, as a financial and technological hub, plays a crucial role in market growth by fostering innovation in digital gifting solutions. The increasing preference for bilingual personalized gift cards, catering to both French- and English-speaking consumers, gives businesses a competitive edge in Quebec. Additionally, corporate gifting trends are gaining momentum, with organizations utilizing customized gift cards for employee incentives and client appreciation. The province's robust retail infrastructure, combined with a rising trend of mobile-based gift card usage, continues to support market expansion.
Western Canada
Western Canada, comprising Alberta, Saskatchewan, and Manitoba, holds approximately 18% of the total market share. The region is witnessing steady growth in the personalized gift card market, driven by increasing adoption of digital gifting solutions. The corporate sector in Western Canada is actively using personalized gift cards for employee rewards and customer engagement strategies. Consumers in this region are increasingly shifting toward digital and virtual gift cards, aligning with the broader national trend of online payments and mobile wallet integration. Additionally, the rise of e-commerce platforms and contactless payment solutions is further strengthening the demand for digital gift cards. While physical gift cards remain relevant, digital alternatives are gaining traction due to their convenience, security, and instant delivery.
British Columbia
British Columbia accounts for approximately 15% of the Canada Personalized Gift Card Market, supported by its strong retail sector and flourishing tourism industry. Vancouver, a major economic hub, drives consumer spending on gift cards for various occasions, including corporate gifting and tourism-related purchases. Retailers in British Columbia are expanding their personalized gift card offerings to cater to both local consumers and international visitors, who often buy gift cards as travel-related expenses or souvenirs. Additionally, the province’s growing focus on sustainability is boosting demand for eco-friendly and digital gift card solutions, as environmentally conscious consumers prefer paperless transactions. As businesses in British Columbia continue to invest in digital transformation, the market for personalized gift cards is expected to witness steady growth in both physical and digital formats.
Key Player Analysis
- Cardly
- Canada Post Corporation
- Walmart Inc.
- Fiserv Inc.
- Givex Corporation
- Paytronix Systems, Inc.
- CafePress Inc.
- Blackhawk Network
- InComm Payments LLC
- American Express Company
- Mars Incorporated
- Shutterfly
- American Greetings Corporation
- Etsy Inc.
- com Inc.
- Others
Competitive Analysis
The Canada Personalized Gift Card Market is highly competitive, with key players focusing on innovation, digital transformation, and customer engagement strategies. Leading companies such as Cardly, Walmart Inc., Fiserv Inc., Givex Corporation, Blackhawk Network, Amazon.com Inc., Canada Post Corporation, Paytronix Systems, Inc., CafePress Inc., InComm Payments LLC, American Express Company, Mars Incorporated, Shutterfly, American Greetings Corporation, and Etsy Inc. dominate the market by offering personalized and digital gift card solutions. Businesses are investing in AI-driven personalization, blockchain for secure transactions, and mobile wallet integrations to enhance user experience. For instance, the growing demand for digital and eco-friendly gift cards has led to increased innovation, with companies expanding their offerings to cater to both individual consumers and corporate clients. Retail giants leverage their vast distribution networks to strengthen market presence, while financial service providers focus on secure, open-loop gift card solutions. Companies specializing in gift card solutions emphasize omnichannel strategies, enabling seamless redemption both online and offline. As competition intensifies, businesses are prioritizing security enhancements, innovative loyalty programs, and strategic partnerships to gain a competitive edge. The increasing shift toward e-commerce and digital transactions continues to reshape the market, with players striving to enhance convenience, security, and customer satisfaction.
Recent Developments
- In January 2025, Walmart Inc. introduced an updated brand look and feel, including changes to its gift card designs and digital gifting options as part of a comprehensive brand refresh.
- In January 2025, com Inc. expanded Amazon Pay gift card options, allowing customization with over 1,000 designs in 7 regional languages. Added the ability to personalize gift cards with custom messages and share via email or messaging apps.
- In December 2023, Blackhawk Network entered into a strategic partnership with Affirm to enable Affirm users to buy gift cards directly from the Affirm app.
- In October 2023, Givex Corporation launched new customizable and animated e-gift card features for its Givex Ecommerce platform, allowing customers to personalize digital gift cards with images, video messages, and animations.
- In March 2023, Qwikcilver Solutions Pvt Ltd partnered with Woolworths Group's payments entity Wpay to extend gift card processing solutions and services in Australia and New Zealand.
Market Concentration & Characteristics
The Canada Personalized Gift Card Market exhibits a moderately concentrated structure, with a mix of established financial institutions, retail giants, and specialized gift card solution providers shaping the competitive landscape. Large retailers and digital payment firms dominate the market, leveraging their extensive distribution networks and technological advancements to enhance customer engagement. The market is characterized by a strong shift toward digital and mobile-based gift cards, driven by increasing consumer demand for convenience, security, and personalization. Companies focus on omnichannel distribution strategies, integrating gift card services across online platforms, mobile wallets, and physical retail stores. Additionally, AI-driven personalization and blockchain-based security solutions are becoming key differentiators in the market. The increasing adoption of open-loop gift cards and corporate gifting solutions further supports market expansion. While competition remains intense, businesses continue to innovate by offering eco-friendly digital options and loyalty-based rewards programs to attract and retain customers in a dynamic gifting ecosystem.
Report Coverage
The research report offers an in-depth analysis based on Type, Distribution Channel, Form, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Canada Personalized Gift Card Market is expected to grow steadily, driven by increasing digital adoption and personalized gifting trends.
- Businesses will continue investing in AI-driven customization to enhance customer experience and engagement.
- The demand for eco-friendly and digital gift cards will rise as sustainability becomes a key consumer preference.
- Mobile wallet integration will become more widespread, making digital gift cards more accessible and convenient.
- Corporate gifting will expand further, with companies using personalized gift cards for employee rewards and client incentives.
- Blockchain technology will play a crucial role in improving security and reducing fraud in digital gift card transactions.
- Retailers and financial institutions will enhance omnichannel strategies to strengthen market reach across online and offline platforms.
- The adoption of open-loop gift cards will increase as consumers seek more flexible and versatile gifting options.
- Strategic partnerships between retailers and payment service providers will drive innovation in the market.
- Continuous advancements in security features will enhance consumer trust and accelerate the shift toward digital gift cards.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Canada Personalized Gift Card Market?
What factors are driving the growth of the Canada Personalized Gift Card Market?
What are some challenges faced by the Canada Personalized Gift Card Market?
Who are the major players in the Canada Personalized Gift Card Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Canada Personalized Gift Card Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Canada Personalized Gift Card Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 893.89 million → 2032: USD 1,895.12 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Canada Personalized Gift Card Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Canada Personalized Gift Card Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Canada Personalized Gift Card Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Canada Personalized Gift Card Market Drivers
- 3.3 Canada Personalized Gift Card Market Restraints & Challenges
- 3.4 Canada Personalized Gift Card Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Canada Personalized Gift Card Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Canada Personalized Gift Card Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Canada Personalized Gift Card category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Canada Personalized Gift Card Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Canada Personalized Gift Card Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Canada Personalized Gift Card market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Canada Personalized Gift Card Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Canada Personalized Gift Card Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Canada Personalized Gift Card Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Canada Personalized Gift Card (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Canada Personalized Gift Card Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Canada Personalized Gift Card Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Canada Personalized Gift Card Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Canada Personalized Gift Card Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Canada Personalized Gift Card Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Canada Personalized Gift Card Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Canada Personalized Gift Card Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Canada Personalized Gift Card Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Canada Personalized Gift Card Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
