
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Canada Women Apparel Market Size 2023 | USD33,882.94 million |
| Canada Women Apparel Markett, CAGR | 2.55% |
| Canada Women Apparel Market Size 2032 | USD42,491.02 million |
Market Overview
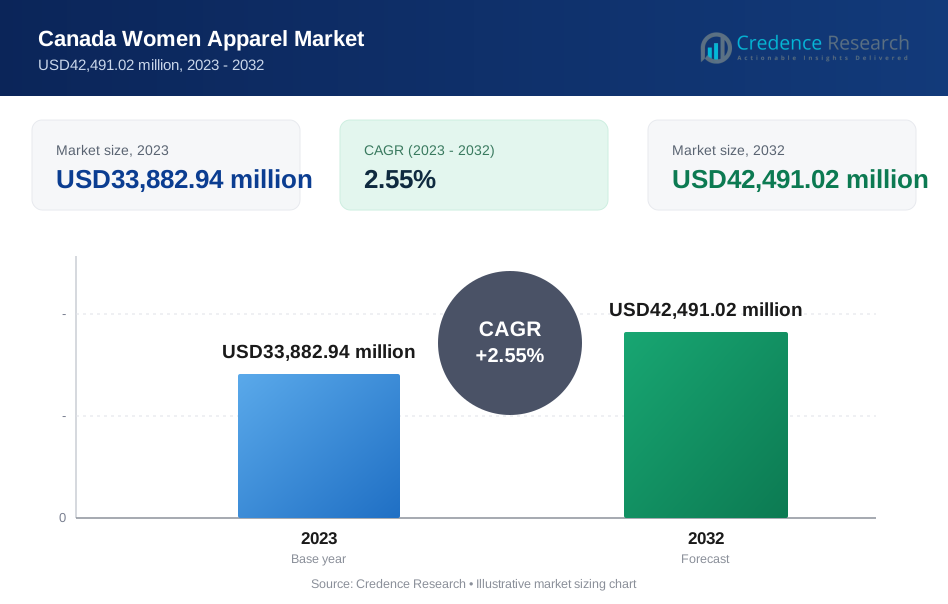
The Canada Women Apparel Market is projected to grow from USD33,882.94 million in 2023 to an estimated USD42,491.02 million by 2032, with a compound annual growth rate (CAGR) of 2.55% from 2024 to 2032. This growth is driven by increasing consumer demand for fashion-forward, sustainable, and diverse clothing options, reflecting the evolving lifestyle preferences of Canadian women.
Key drivers of the market include a growing focus on eco-friendly and sustainable apparel, with consumers seeking clothing options that align with environmental values. The increasing adoption of online shopping, driven by advancements in e-commerce platforms and digital marketing, is also shaping purchasing behavior. Additionally, the rising popularity of athleisure and casual wear has further expanded product categories in the market, providing consumers with versatile, comfortable clothing choices for various occasions.
Geographically, the Canada Women Apparel Market is dominated by key provinces such as Ontario and Quebec, which house large urban centers and a significant proportion of the country’s population. The key players in this market include global and regional brands such as Lululemon Athletica, Aritzia, H&M, and Zara. These companies are focusing on product innovation, customer-centric marketing strategies, and sustainability initiatives to capture a larger market share and meet the diverse needs of Canadian women.
Market Insights
- The Canada Women Apparel Market is projected to grow from USD33,882.94 million in 2023 to USD42,491.02 million by 2032, with a CAGR of 2.55% from 2024 to 2032.
- Increasing consumer interest in eco-friendly and sustainable clothing is driving market growth, with brands focusing on ethical production practices.
- The expansion of e-commerce platforms is shaping purchasing behavior, as Canadian women embrace the convenience and variety offered by online retail.
- The growing demand for athleisure and casual wear is fueling the growth of the sportswear and casual segments, as more women prioritize comfort and versatility.
- Ongoing supply chain challenges, including rising costs and production delays, are impacting the market's ability to meet demand efficiently.
- Ontario and Quebec lead the market, with large urban populations and higher disposable incomes, contributing significantly to market expansion.
- Major players like Lululemon Athletica, Aritzia, H&M, and Zara continue to innovate in product offerings, sustainability, and digital engagement to maintain market share.
Market Drivers
Rising Consumer Demand for Sustainable Fashion
The increasing demand for sustainable fashion is one of the most prominent drivers of the Canada Women Apparel Market. Canadian consumers are becoming increasingly aware of the environmental and social impacts of the apparel industry, which has led to a significant shift towards eco-friendly and sustainable clothing options. Many consumers are now seeking brands that prioritize environmental responsibility, including those that use recycled materials, organic fabrics, and ethical manufacturing processes. This growing preference for sustainability has prompted numerous apparel brands to adopt eco-conscious practices, from reducing carbon footprints to promoting circular fashion models. As the trend towards sustainability continues to grow, it is expected to drive the development of innovative and environmentally friendly apparel, influencing purchasing behavior and driving market growth. Retailers are also responding by enhancing their sustainability messaging and offering consumers the ability to track the environmental impact of their purchases, which is further fueling demand for sustainable women’s apparel in Canada.For instance, brands like Tentree are leading the way by using eco-conscious materials and planting trees for every item sold, reflecting the growing consumer preference for environmentally responsible fashion practices. This approach not only appeals to environmentally conscious consumers but also contributes to a broader cultural shift towards sustainability in the fashion industry.
Expansion of Online Shopping and E-Commerce Platforms
The ongoing expansion of online shopping and e-commerce platforms is significantly contributing to the growth of the Canada Women Apparel Market. The increasing penetration of the internet, the proliferation of smartphones, and the rise of digital payment systems have transformed how consumers in Canada shop for apparel. Online retail has grown at an accelerated pace, providing convenience and accessibility to a wide range of women’s clothing. Consumers now prefer shopping online due to the convenience of browsing through extensive product ranges, comparing prices, and having items delivered to their doorsteps. Additionally, e-commerce platforms often provide a more personalized shopping experience through advanced data analytics, which allows brands to recommend products based on previous purchases or browsing behavior. The popularity of fast fashion and the ability to make quick, trend-driven purchases online has further amplified the demand for women’s apparel, as Canadian shoppers are increasingly gravitating toward the ease and speed of digital platforms. With the rise of social media influencers and the growing impact of digital marketing, e-commerce is expected to remain a dominant force in shaping the market dynamics of the women’s apparel sector.For instance, Walmart Canada has seen a significant surge in e-commerce sales, driven by the convenience of online shopping and enhanced digital services, which are transforming how Canadians purchase apparel. This shift highlights the importance of digital platforms in meeting consumer demand for convenience and accssibility.
Shift Towards Athleisure and Casual Wear
Another key driver of the Canada Women Apparel Market is the rising popularity of athleisure and casual wear. Athleisure, a hybrid of athletic and leisurewear, has grown exponentially in recent years, with consumers increasingly opting for comfortable, versatile clothing that can transition between workout sessions and casual outings. This trend has been accelerated by the growing emphasis on health and wellness, as more women in Canada engage in fitness and active lifestyles. Additionally, the COVID-19 pandemic has further catalyzed the shift towards more relaxed and comfortable clothing, as remote working and stay-at-home mandates led to increased demand for loungewear and casual apparel. Athleisure garments such as leggings, sports bras, and hoodies have become staples in many women’s wardrobes, as they provide both comfort and functionality. The versatility of athleisure makes it suitable for a variety of occasions, from running errands to attending virtual meetings, contributing to its rising popularity. As Canadian women continue to seek apparel that blends style and comfort, athleisure is expected to remain a driving force within the women’s apparel market, with brands constantly innovating to meet consumer demand for high-performance yet stylish garments. For instance, the popularity of athleisure has been evident in Canada, where it has become a staple in many wardrobes due to its comfort and versatility, allowing consumers to transition seamlessly between workouts and casual outings. This trend reflects a broader shift towards prioritizing comfort and practicality in fashion choices.
Influence of Celebrity Endorsements and Social Media
Celebrity endorsements and the influence of social media play a significant role in driving the Canada Women Apparel Market. Social media platforms like Instagram, TikTok, and Pinterest have become key channels for apparel brands to showcase their collections and engage with consumers. Social media influencers, celebrities, and fashion bloggers often promote specific clothing brands, styles, and trends, which have a direct impact on purchasing behavior. Many women in Canada look to these influencers for fashion inspiration, and as a result, items endorsed by high-profile figures tend to see an increase in demand. Brands often collaborate with celebrities and influencers to launch exclusive collections, further driving consumer interest. Additionally, the viral nature of social media content means that fashion trends can spread rapidly, creating a sense of urgency and desire for the latest styles. This culture of “buy now, wear now” has led to a shift towards fast fashion, where trends emerge and disappear quickly. The ability of social media to rapidly influence consumer preferences is shaping the purchasing habits of Canadian women, particularly younger demographics who are highly active on these platforms. As the role of digital influencers continues to grow, the relationship between social media trends and apparel purchases is expected to drive sustained growth in the Canada Women Apparel Market.For instance, social media platforms like Instagram and TikTok have become crucial for fashion brands to engage with consumers and promote trends, often through collaborations with influencers and celebrities, which significantly influence purchasing decisions. This digital influence not only shapes fashion trends but also drives consumer engagement with apparel brands
Market Trends
Increased Focus on Sustainable and Ethical Fashion
One of the most significant trends in the Canada Women Apparel Market is the growing emphasis on sustainability and ethical fashion. With consumers becoming more environmentally conscious, there has been a noticeable shift towards eco-friendly materials, ethical production practices, and brands that promote sustainability. Canadian women are increasingly seeking apparel options that align with their values of environmental responsibility, leading to the widespread adoption of sustainable fabrics such as organic cotton, bamboo, hemp, and recycled polyester. Brands that prioritize ethical sourcing, fair labor practices, and transparency in their supply chains are gaining favor among consumers. This trend is not just about environmental awareness; it also includes a growing interest in supporting brands that contribute positively to social causes. As a result, many companies in the women’s apparel market are responding by embracing sustainable business models, offering eco-conscious clothing lines, and even establishing take-back or recycling programs to extend the life cycle of their products. Major Canadian retailers are integrating sustainability into their marketing strategies, positioning themselves as leaders in responsible fashion. This shift towards sustainability is expected to continue, as both younger and older generations increasingly demand that brands adopt more environmentally friendly practices, making it one of the most defining trends in the market.
Rise of Personalized and Customizable Apparel
Personalization and customization have become a key trend in the Canada Women Apparel Market, driven by technological advancements and the desire for unique fashion items. Canadian consumers are no longer satisfied with mass-produced garments and are increasingly seeking out clothing that reflects their personal style. This has led to a rise in brands offering customized options, allowing consumers to personalize everything from the color and fabric of their clothing to adding initials, patches, or other embellishments. The trend is particularly prominent in the activewear and casual wear segments, where women look for items that reflect their individuality while maintaining functionality and comfort. In addition, the use of technology, such as 3D design and virtual fitting rooms, is enabling a more personalized shopping experience. Brands are leveraging data analytics and artificial intelligence to offer tailored recommendations and personalized shopping experiences online. Moreover, some companies are allowing consumers to co-create their clothing by choosing fabrics, patterns, and designs, which further enhances the uniqueness of the products. This shift towards individualized apparel is expected to continue as consumer preferences evolve towards more self-expressive and customized fashion choices, especially among younger demographics.
Growth of Activewear and Athleisure
Activewear and athleisure continue to dominate the Canada Women Apparel Market, driven by a growing interest in health, wellness, and a more casual lifestyle. As more Canadian women adopt fitness-conscious lifestyles, the demand for performance-driven apparel that combines style with functionality is on the rise. Athleisure, which includes clothing that is designed for both athletic activities and casual wear, has become a staple in many women’s wardrobes. Popular items in this category include leggings, sports bras, tank tops, and hoodies, all of which are designed to be comfortable, breathable, and versatile. This trend has been further accelerated by the COVID-19 pandemic, as more women began working from home and sought comfortable clothing for their daily activities. The rise of fitness culture, coupled with a growing emphasis on mental and physical well-being, has propelled the popularity of athleisure. Moreover, athleisure brands are increasingly incorporating cutting-edge fabrics with moisture-wicking, anti-odor, and stretch capabilities, improving the functionality and appeal of the clothing. The global influence of wellness and fitness trends, combined with the growing preference for casual, comfortable clothing, positions activewear as one of the most important segments in the Canada Women Apparel Market. The trend is expected to continue expanding, with more brands introducing athleisure collections that cater to both the fitness enthusiast and the fashion-conscious consumer.
Influence of Digital and Social Media on Fashion Trends
The influence of digital media and social platforms on fashion trends has been growing rapidly in recent years, shaping the way Canadian women discover and purchase apparel. Platforms like Instagram, TikTok, Pinterest, and YouTube have become powerful marketing tools for fashion brands, as they allow for direct engagement with consumers through influencer collaborations, live-streamed fashion shows, and targeted advertising. Social media has democratized fashion, enabling smaller brands to gain recognition through viral marketing and user-generated content. Influencers, celebrities, and fashion bloggers have a direct impact on shaping consumer preferences, as Canadian women increasingly turn to these figures for inspiration on the latest trends and styling tips. The rapid spread of trends via social media has also given rise to the concept of "fast fashion," where trends emerge and disappear within weeks, encouraging consumers to make quick, trend-driven purchases. Moreover, e-commerce platforms have integrated social media features, allowing users to shop directly from Instagram or TikTok posts, making the shopping experience seamless and convenient. As social media continues to play a pivotal role in driving fashion trends, brands are leveraging these platforms to connect with consumers, increase brand visibility, and create interactive, engaging campaigns. This trend is reshaping the fashion retail landscape and continues to influence how Canadian women shop for and interact with apparel brands
Market Challenges
Supply Chain Disruptions and Rising Costs
One of the primary challenges facing the Canada Women Apparel Market is the disruption of global supply chains and rising production costs. The apparel industry relies heavily on complex global supply chains, and any disruptions-such as those caused by the COVID-19 pandemic, geopolitical tensions, or raw material shortages-can severely impact production timelines and cost structures. For many apparel brands, sourcing materials from overseas and relying on third-party manufacturers means that delays and cost increases in one part of the chain can have a ripple effect throughout the market. Additionally, rising labor costs and increasing transportation expenses have placed additional pressure on margins, forcing brands to make difficult decisions regarding pricing and profit margins. In some cases, this has led to higher prices for consumers, which can dampen demand, particularly in more price-sensitive market segments. As brands work to navigate these challenges, there is also a growing need to rethink supply chain strategies, including increasing reliance on local manufacturing, investing in technology to improve logistics, and exploring more sustainable sourcing practices. However, these adjustments come with their own set of complexities and costs, creating an ongoing challenge for businesses in the market.
Intense Competition and Changing Consumer Preferences
Another significant challenge for the Canada Women Apparel Market is the intense competition and the rapidly changing consumer preferences. The market is highly fragmented, with both global and local players vying for market share. Fast fashion giants, premium brands, and emerging direct-to-consumer labels all compete for the attention of Canadian women, making it increasingly difficult for companies to differentiate themselves. The rise of e-commerce and digital platforms has intensified competition by allowing smaller, niche brands to reach a broader audience and compete on an equal footing with established names. Furthermore, Canadian consumers are becoming more discerning, with a greater emphasis on value, quality, and sustainability. This shift in consumer behavior requires brands to constantly innovate and adapt their offerings to meet the evolving demands for personalized, stylish, and ethically produced apparel. The challenge of keeping up with these ever-changing preferences, while maintaining brand loyalty and market share, requires ongoing investment in product development, customer engagement, and marketing strategies. As consumer preferences continue to evolve rapidly, brands must remain agile and responsive to stay relevant in an increasingly competitive market.
Market Opportunities
Growing Demand for Sustainable and Ethical Fashion
The increasing focus on sustainability presents a significant opportunity for the Canada Women Apparel Market. As Canadian consumers become more environmentally conscious, there is a growing preference for brands that prioritize sustainable practices in their production processes. This trend is particularly strong among younger generations, who are more likely to support brands that align with their values of environmental stewardship and ethical sourcing. Apparel brands that invest in eco-friendly materials, such as organic cotton, recycled fabrics, and biodegradable textiles, can tap into this expanding market segment. Additionally, offering transparency in supply chains and demonstrating a commitment to fair labor practices can further differentiate brands and attract environmentally conscious consumers. This shift presents an opportunity for brands to innovate and establish themselves as leaders in sustainable fashion, addressing the demand for both ethical production and fashionable, high-quality apparel.
Expansion of E-Commerce and Digital Engagement
The continued growth of e-commerce offers significant opportunities for the Canada Women Apparel Market, particularly in light of the increased adoption of online shopping during the COVID-19 pandemic. With Canadian women increasingly turning to digital platforms for convenience and variety, there is an opportunity for brands to expand their online presence and leverage digital marketing strategies to engage with consumers. Integrating advanced technologies such as virtual fitting rooms, augmented reality (AR), and personalized shopping experiences can enhance the customer journey, driving higher conversion rates and customer loyalty. Additionally, social media and influencer marketing provide effective channels to reach a broader audience, particularly younger, tech-savvy consumers. By strengthening their e-commerce capabilities and digital engagement, apparel brands can tap into the growing trend of online shopping, ensuring long-term growth and success in the competitive market.
Market Segmentation Analysis
By Type
The Canada Women Apparel Market is segmented by type into casual wear, formal wear, sportswear, nightwear, and innerwear. Casual wear holds a significant share of the market, driven by the increasing preference for comfortable, everyday clothing that aligns with modern lifestyles. The rising demand for fashionable yet relaxed apparel, such as denim, t-shirts, and loungewear, continues to influence purchasing decisions. Formal wear, including business attire and evening dresses, remains relevant, although its demand has been affected by the growing acceptance of casual workwear. The sportswear segment is experiencing strong growth due to the increasing adoption of fitness-focused lifestyles and the continued rise of athleisure trends. Nightwear and innerwear segments are also expanding, driven by innovations in comfort, fabric technology, and growing consumer awareness of premium intimate apparel.
By Application
The market is further divided into mass, premium, and luxury segments. The mass market category accounts for the largest share, catering to price-sensitive consumers looking for affordable yet stylish clothing options. The premium segment is growing steadily, driven by consumers who seek higher quality and brand value. The luxury segment, though niche, continues to thrive, particularly among high-income consumers who prioritize exclusivity, craftsmanship, and designer branding. The increasing presence of global luxury fashion brands in Canada has further strengthened this segment.
Segments
Based on Type
- Casual Wear
- Formal Wear
- Sportswear
- Night Wear
- Inner Wear
Based on Application
- Mass
- Premium
- Luxury
Based on Age group
- 5-16 years
- 16-45 years
- 45-70 years
- 70 and above
Based on Distribution Channel
- Offline
- Online
Based on Region
- Ontario
- Quebec
- British Columbia
- Alberta
Regional Analysis
Ontario (40%)
Ontario is the largest market for women’s apparel in Canada, accounting for approximately 40% of the total market share. The province is home to major metropolitan areas, including Toronto, which serves as the fashion hub of Canada. Ontario's urban population and high disposable income levels make it a dominant region for both mass-market and premium apparel. The region's fashion-conscious consumers are also highly engaged with e-commerce platforms, further boosting online sales. With a growing trend of fashion-forward and sustainable apparel, Ontario remains the key driver of the country’s women’s apparel market.
Quebec (25%)
Quebec follows Ontario closely in terms of market share, contributing around 25% to the total women’s apparel market. Montreal, Quebec’s largest city, is known for its vibrant and diverse fashion scene, where a blend of European and North American styles thrives. Quebec consumers tend to value both style and affordability, making it a significant market for mass-market apparel. However, the premium and luxury segments are also growing in popularity, particularly among younger, fashion-conscious women. The province is witnessing a shift towards sustainable fashion, which presents opportunities for brands offering eco-friendly clothing.
Key players
- Giorgio Armani S.p.A.
- Manolo Blahnik
- Dior
- Louis Vuitton
- Burberry
- Dolce & Gabbana S.R.L
- Prada
- Guccio Gucci S.p.A
- Chanel
- Gianni Versace S.r.l
- Alder
- Allison Wonderland
Competitive Analysis
The Canada Women Apparel Market is highly competitive, with several global luxury and premium brands striving to capture market share. Leading players like Giorgio Armani, Louis Vuitton, and Chanel dominate the luxury segment, offering high-quality, exclusive fashion to high-income consumers. These brands focus on innovation, craftsmanship, and maintaining brand prestige through limited edition collections and high-end retail experiences. On the other hand, brands such as Burberry, Prada, and Gucci combine heritage with modern trends, appealing to a broad consumer base seeking both luxury and contemporary design. Furthermore, niche players like Manolo Blahnik and Gianni Versace maintain strong brand identities with a focus on footwear and distinct fashion styles. As the market grows, these brands face increasing pressure to adopt sustainable practices, invest in e-commerce capabilities, and engage in digital marketing to stay relevant in an evolving consumer landscape.
Recent Developments
- In March 2024, Manolo Blahnik has been focusing on global expansion, particularly in Asia, following the resolution of a trademark dispute in China. While there are no specific developments in Canada, their global strategy might influence Canadian markets indirectly.
- In March 2023, Dior's global influence extends to Canada through its international brand presence. Maria Grazia Chiuri's designs, such as the Fall 2023 collection inspired by Indian textiles, could influence Canadian fashion trends.
- In April 2023, Louis Vuitton's Spring-Summer 2023 collection, featuring exaggerated proportions, might have influenced Canadian fashion trends. However, there are no specific developments reported for the Canadian market.
- In February 2024, Burberry's new arrivals and collections are available globally, including in Canada, but there are no specific Canadian market developments reported.
- In December 2023, Dolce & Gabbana's Spring-Summer 2024 collection reinterprets their style codes with a '60s aesthetic, which might influence Canadian fashion trends. However, no specific Canadian developments were reported.
- In January 2023, Prada's Spring-Summer 2023 collection, designed by Miuccia Prada and Raf Simons, could influence Canadian fashion trends through its global presence. However, no specific Canadian developments were reported.
- In January 2023, Chanel's Spring-Summer 2023 collection, inspired by the film Last Year in Marienbad, reflects a minimalist approach that might influence Canadian fashion trends. However, no specific Canadian developments were reported
Market Concentration and Characteristics
The Canada Women Apparel Market exhibits moderate market concentration, with a mix of global and local players competing for market share. Major international brands like H&M, Zara, and Uniqlo, along with prominent Canadian retailers such as Aritzia and Lululemon, dominate the market, particularly in urban centers like Toronto and Montreal. However, the market also features a growing presence of smaller, niche brands focusing on sustainability, customization, and premium offerings. This competitive landscape is marked by the increasing adoption of e-commerce, with online shopping playing a pivotal role in expanding reach and consumer engagement. The demand for diverse product categories, including casual wear, athleisure, formal wear, and sustainable apparel, continues to shape market dynamics. Additionally, consumer preferences are evolving, with a strong emphasis on comfort, style, and ethical fashion, making innovation and adaptability key characteristics for market success.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Age group , Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Consumer demand for eco-friendly and ethically produced apparel is expected to increase, with brands focusing on sustainable materials and transparent supply chains. Companies that prioritize environmental responsibility will capture a larger market share.
- E-commerce will continue to dominate, with online sales growing due to convenience and the rise of direct-to-consumer models. The integration of virtual try-ons and personalized shopping experiences will enhance online engagement.
- Athleisure and activewear will remain a major growth segment, driven by the growing focus on health, fitness, and comfort. Consumers are increasingly prioritizing versatile clothing suitable for both athletic and casual wear.
- Canadian women will continue to seek more personalized, unique apparel choices that reflect their individuality. The trend towards customized clothing will increase, with brands offering more options for tailored and bespoke garments.
- Retailers will integrate advanced technologies like AI, machine learning, and augmented reality to enhance shopping experiences. Virtual fitting rooms and AI-powered styling tools will become standard features in online and offline stores.
- The demand for inclusive sizing will grow, with more brands expanding their size ranges. The focus on body positivity and diverse representation in marketing will continue to shape the apparel sector.
- The premium and luxury segments will expand, particularly in urban areas where consumers are increasingly willing to invest in high-quality, designer apparel. The demand for exclusive, high-end clothing will remain strong.
- While Ontario and Quebec will continue to dominate, regions like British Columbia and Alberta will see increasing demand for women’s apparel. Growing populations in these areas will drive both online and offline sales.
- Social media marketing and influencer collaborations will play an even greater role in shaping consumer purchasing decisions. Brands will increasingly rely on digital platforms to reach younger, tech-savvy shoppers.
- Innovation in fabrics, such as biodegradable materials and sustainable production processes, will lead the next wave of growth. Brands that combine sustainability with cutting-edge fashion will set new market standards.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Canada Women Apparel Market in 2023 and 2032?
What are the key drivers of growth in the Canada Women Apparel Market?
What is the role of e-commerce in the Canada Women Apparel Market?
Who are the key players in the Canada Women Apparel Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Canada Women Apparel Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Canada Women Apparel Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD33,882.94 million → 2032: USD42,491.02 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Canada Women Apparel Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Canada Women Apparel Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Canada Women Apparel Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Canada Women Apparel Market Drivers
- 3.3 Canada Women Apparel Market Restraints & Challenges
- 3.4 Canada Women Apparel Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Canada Women Apparel Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Canada Women Apparel Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Canada Women Apparel category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Canada Women Apparel Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Canada Women Apparel Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Canada Women Apparel market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Canada Women Apparel Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Canada Women Apparel Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Canada Women Apparel Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Canada Women Apparel (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Canada Women Apparel Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Canada Women Apparel Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Canada Women Apparel Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Canada Women Apparel Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Canada Women Apparel Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Canada Women Apparel Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Canada Women Apparel Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Canada Women Apparel Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Canada Women Apparel Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
