
Canine Atopic Dermatitis Market Overview:
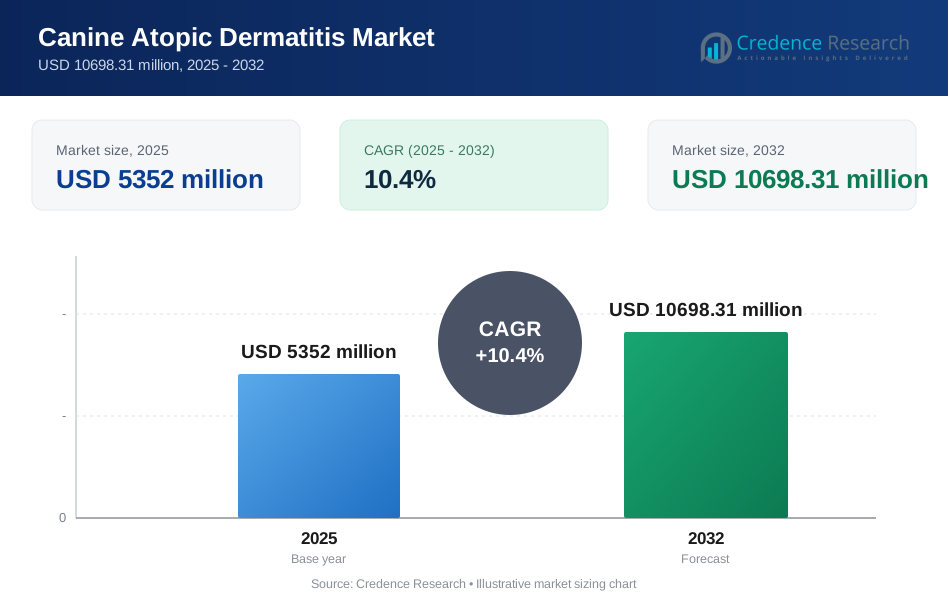
The global Canine Atopic Dermatitis Market size was estimated at USD 5352 million in 2025 and is expected to reach USD 10698.31 million by 2032, growing at a CAGR of 10.4% from 2025 to 2032. Growth is driven primarily by rising diagnosis and long-term management of chronic pruritic dermatitis as companion animal owners and veterinarians shift toward targeted therapies that improve sustained symptom control and treatment adherence. Expanded access to veterinary dermatology services and higher willingness to pay for premium care across developed markets continues to support broader uptake of prescription options and repeat therapy cycles.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Canine Atopic Dermatitis Market Size 2025 | USD 5352 million |
| Canine Atopic Dermatitis Market, CAGR | 10.4% |
| Canine Atopic Dermatitis Market Size 2032 | USD 10698.31 million |
Key Market Trends & Insights
- North America represented 40.6% of 2025 revenue, supported by higher premium therapy penetration and dense veterinary infrastructure.
- Biologics accounted for the largest 2025 share at 56.7%, reflecting strong demand for targeted immune-pathway modulation in chronic cases.
- Oral therapies held 49.3% share in 2025 due to routine-friendly dosing formats that fit maintenance regimens for recurrent disease.
- Monoclonal antibodies and interleukin inhibitors captured 35.2% share in 2025, indicating continued shift away from long-duration systemic steroid reliance.
- Injectable administration is gaining traction over the forecast period, supported by long-acting dosing intervals that reduce missed doses and improve adherence in chronic canine atopic dermatitis management.

Segment Analysis
Therapy selection in the Canine Atopic Dermatitis Market is increasingly influenced by long-term disease control needs, with canine atopic dermatitis commonly described as affecting roughly 10–15% of the dog population in several industry discussions. Higher-risk breeds often show recurrent flare patterns, which increases follow-up visits, add-on therapy, and repeated prescription refills. Growing owner awareness of allergy triggers and secondary skin infections is also encouraging earlier clinical presentation, which expands the addressable prescription base. Premiumization in companion care further supports adoption of newer targeted options when veterinarians prioritize sustained itch control and safety.
Demand is also shaped by product positioning and purchase behavior across prescription maintenance and adjunct skin-care routines. Sales momentum reported for leading targeted oral therapies underscores strong clinician and owner preference for rapid itch relief and predictable outcomes in moderate-to-severe disease management. Broader pet spending expansion, especially in the United States, reinforces the capacity of households to adopt higher-cost dermatology regimens over longer durations. Distribution is gradually diversifying through refills and convenience channels, although initial diagnosis and treatment initiation typically remain clinic-led.
By Drug Class Insights
Monoclonal Antibodies / Interleukin Inhibitors (Lokivetmab) accounted for the largest share of 35.2% in 2025. Leadership reflects strong clinical preference for targeted cytokine-pathway control that supports durable itch reduction in chronic disease profiles. Monthly or longer-interval dosing patterns can improve adherence relative to daily regimens in owner-managed care. Safety considerations also influence therapy choice as veterinarians aim to reduce prolonged systemic steroid exposure. Ongoing lifecycle management and competitive launches continue to reinforce adoption across moderate-to-severe cases.
By Type Insights
Prescription therapies represented the core demand pool in 2025 as most clinically meaningful atopic dermatitis cases require veterinary diagnosis, monitoring, and treatment adjustment over time. Prescription options are commonly preferred for moderate-to-severe pruritus because veterinarians prioritize predictable control and long-term safety. OTC products tend to serve as adjunct support for skin barrier care, cleansing, and mild symptom relief rather than primary disease control. Treatment pathways frequently combine prescription anti-inflammatory therapy with topical support to reduce flare frequency. Channel dynamics also favor prescription continuity through scheduled refills and clinical follow-up.
By Mode of Administration Insights
Oral accounted for the largest share of 49.3% in 2025. Oral formats align with home-based administration routines and are widely used for systemic control when lesions are generalized. Broad product availability across tablets and flavored chewables supports acceptance and repeat purchasing patterns. Injectable options are gaining traction as veterinarians seek adherence advantages through longer dosing intervals and consistent exposure profiles. Topical therapies remain important for focal lesions and barrier maintenance, often complementing systemic regimens rather than replacing them.
By Molecule Type Insights
Biologics accounted for the largest share of 56.7% in 2025. Leadership is tied to targeted immunomodulation that supports symptom control and reduces reliance on broader immunosuppressive approaches in chronic use. Premium pricing is better sustained in biologics due to manufacturing complexity and differentiated clinical positioning. Companion animal care spending growth supports willingness to adopt higher-value therapy options when outcomes are durable. Small-molecule drugs remain essential for rapid control and flexible dosing, but biologics continue to expand their footprint in long-term protocols.
By Indication Insights
Food allergy, ectoparasite-associated dermatitis, and secondary allergic skin infections collectively shape treatment intensity because mixed etiologies frequently overlap with atopic dermatitis presentations. Secondary infections can increase visit frequency and therapy duration as veterinarians address bacterial or yeast complications alongside inflammation control. Trigger identification and elimination strategies often require repeat consultations, diet trials, and ongoing monitoring. Management approaches commonly combine systemic anti-pruritic therapy with antimicrobial or topical support when flare patterns persist. This multi-factor clinical reality increases therapy persistence and overall category demand.
By Dog Breed Insights
Retrievers, terriers, and German Shepherds remain prominent breed groups in clinical discussions because predisposition and recurrence patterns can elevate diagnosis rates and repeat treatment cycles. Breed-linked sensitivity and skin barrier differences are frequently associated with earlier onset and persistent symptom profiles. Owners of predisposed breeds often seek faster veterinary intervention due to visible pruritus and recurrent otitis or skin lesions. This behavior increases uptake of maintenance regimens and follow-up plans. The broader “Others” category still represents substantial demand given the wide breed base across global pet populations.
By Distribution Channel Insights
Veterinary Hospitals / Clinics accounted for the largest share of 41.6% in 2025. Dominance reflects clinic control over diagnosis, prescription initiation, dose optimization, and follow-up evaluation for chronic disease management. Veterinary dispensing also supports bundled care pathways that include diagnostics, prescription therapy, and adjunct topical recommendations. Retail pharmacies are growing where prescription fulfillment is streamlined and pricing is competitive for long-term refills. Online pet pharmacies are gaining relevance for convenience-driven repeat ordering and chronic refill adherence. Despite channel diversification, clinic-led initiation remains central to therapy selection.
Canine Atopic Dermatitis Market Drivers
Rising Diagnosis and Long-Term Disease Management
Chronic pruritic dermatitis is increasingly diagnosed as owners seek veterinary care earlier for persistent scratching, erythema, and recurring infections. Clinical pathways often require long-term therapy and periodic adjustments, which increases repeat purchasing and overall treatment duration. Higher awareness of allergic triggers and co-morbidities supports more frequent consultations and follow-up schedules. Improved diagnostic workflows in clinics and referral settings expand the treated population. These factors collectively strengthen sustained demand for prescription-led management.
- For instance, Zoetis states that one Cytopoint injection can begin working within 1 day and provide 4 to 8 weeks of relief, and in a supporting atopic dermatitis study the product showed a significantly greater reduction from baseline in pruritus on days 1 to 49 and skin condition scores on days 7 to 56 versus placebo at a minimum 2 mg/kg dose. These factors collectively strengthen sustained demand for prescription-led management.
Shift Toward Targeted Immunomodulatory Therapies
Veterinary care is moving toward targeted therapies that offer durable symptom control and improved safety profiles for long-term use. Biologics and selective small-molecule options are increasingly favored when clinicians aim to reduce prolonged reliance on broad immunosuppression. Better control of itch and inflammation supports adherence and improves quality of life outcomes, reinforcing continuation rates. Lifecycle management innovations such as improved formulations can also strengthen patient acceptance. This shift supports premium product uptake and value growth.
- For instance, Elanco markets Zenrelia as a once-daily oral therapy dosed at 0.6 to 0.8 mg/kg, and on its veterinary product page the company reports a head-to-head clinical trial in 338 client-owned dogs in which Zenrelia showed similar efficacy to Apoquel at the primary endpoint on Day 28 while also being positioned for long-term maintenance therapy.
Premiumization in Companion Animal Healthcare Spending
Companion animal owners are allocating higher budgets toward preventive and specialty care, enabling adoption of advanced dermatology regimens. Higher willingness to pay supports uptake of targeted therapies and consistent refills across maintenance cycles. Growth in pet insurance and subscription-based pharmacy fulfillment in some markets further supports affordability and continuity. Increased spending also fuels demand for adjunct skincare products that complement prescription therapy. This premiumization underpins market expansion across developed regions.
Expansion of Veterinary Service Access and Specialty Care
Veterinary clinic networks and referral capacity are improving in many regions, increasing access to dermatology-informed diagnosis and treatment. Greater availability of specialty services supports structured management plans, including trigger identification and therapy optimization. Clinic-led education improves adherence and reduces discontinuation risk for chronic regimens. Better service access also supports earlier intervention, which increases the treated pool. Expanding professional capacity strengthens both volume and value growth.
Canine Atopic Dermatitis Market Challenges
Treatment costs remain a significant barrier for long-duration management, especially when premium biologics or newer targeted therapies are used over repeated cycles. Out-of-pocket payment structures and limited insurance penetration in several regions can restrict therapy continuity. Price sensitivity may push households toward intermittent use or lower-cost alternatives, reducing consistency of disease control. This challenge is amplified in emerging markets where specialty access is uneven. Cost-related switching and discontinuation risk can limit full value capture.
Clinical variability also complicates standardized treatment pathways across breeds and mixed etiologies. Many cases involve overlapping triggers such as environmental allergens, food sensitivities, and secondary infections that require multi-step protocols. Variable response profiles can drive trial-and-adjust cycles that increase monitoring burden for clinics and owners. Adherence can weaken when daily regimens are difficult to maintain or outcomes are inconsistent. These dynamics can slow therapy optimization and affect long-term persistence.
- For instance, Antech’s Heska Allercept platform uses high-affinity IgE receptor technology that can detect as little as 10 picograms of allergen-specific IgE and evaluates 83 environmental allergens plus 24 food allergens in dogs and cats, illustrating the diagnostic breadth often needed before clinicians can narrow down the dominant trigger set and stabilize a treatment plan.
Canine Atopic Dermatitis Market Trends and Opportunities
Targeted therapy innovation is expanding product choice across oral selective inhibitors and injectable biologics designed for sustained symptom control. Long-acting dosing formats are becoming more attractive where adherence challenges are common in chronic dermatology management. Formulation improvements and differentiated delivery options can improve owner compliance and veterinary confidence in long-term use. New pipeline approaches may also broaden the competitive set beyond established mechanisms. These trends support future category expansion and premium mix improvement.
Distribution evolution creates opportunities through refill convenience and chronic therapy continuity. Online pet pharmacies and retail fulfillment models can strengthen repeat ordering behavior and reduce missed doses for maintenance regimens. Integrated clinic-to-pharmacy workflows can also improve adherence and support long-term monitoring plans. Digital engagement tools and subscription refill programs are gaining relevance for chronic disease categories. These models can increase persistence and stabilize recurring revenue.
- For instance, Chewy’s digitally enabled refill model is already operating at substantial scale, with 20.756 million active customers in fiscal Q1 2025, Autoship customer sales of $2.56 billion, and Autoship accounting for 82.2% of net sales, while its websites and mobile applications support roughly 130,000 product and service offerings that help streamline repeat purchasing across pharmacy and pet-health categories.
Regional Insights
North America
North America held 40.6% share in 2025, supported by strong companion animal healthcare spending and broad access to veterinary clinics and specialist services. High diagnosis rates and earlier clinical presentation increase the treated population for chronic allergy management. Adoption of targeted therapies is elevated as clinicians prioritize long-term safety and predictable outcomes. Refill continuity is supported by established pharmacy fulfillment options and recurring follow-up patterns. Competitive activity remains intense as companies expand dermatology portfolios and formulation choices.
Europe
Europe represented 25.8% share in 2025, anchored by established veterinary care pathways across major economies and steady owner willingness to pay for prescription management. Structured clinical follow-up supports therapy persistence, particularly for chronic pruritus control. Demand is strengthened by increasing recognition of breed predisposition and recurring flare patterns. Prescription therapy remains central, with adjunct skincare products complementing systemic control. Ongoing product availability and distribution access support consistent category growth.
Asia Pacific
Asia Pacific captured 20.7% share in 2025 and continues to expand as pet ownership increases and veterinary service access improves in large urban markets. Growth is supported by rising awareness of allergy triggers and growing demand for specialist-informed care. Premium therapy adoption is improving, although affordability and uneven specialty coverage still limit penetration in several markets. Expanding clinic networks and modern retail distribution support broader access to prescription treatment. The region is positioned for strong incremental volume growth as care pathways mature.
Latin America
Latin America accounted for 7.6% share in 2025, reflecting a smaller premium therapy base and variability in veterinary access across countries. Urban centers show improving diagnosis rates and increasing demand for long-term itch control as companion care awareness rises. Affordability remains a constraint for biologics and newer targeted therapies, encouraging selective adoption and intermittent use. Retail and online fulfillment channels are gaining relevance for refills where infrastructure is established. Continued service expansion can support gradual improvement in treated population size.
Middle East & Africa
Middle East & Africa held 5.3% share in 2025, shaped by limited specialty dermatology capacity outside select markets and uneven diagnosis intensity. Demand is supported by premium pet care pockets in developed urban areas where veterinary services and pharmacy access are stronger. In many geographies, cost sensitivity and constrained access reduce long-term therapy continuity. Clinic-led dispensing remains important where prescription control is concentrated. Market growth depends on broader veterinary service expansion and improved affordability.
Competitive Landscape
Competition in the Canine Atopic Dermatitis Market centers on efficacy, safety, dosing convenience, and lifecycle management across targeted oral and injectable therapies. Companies compete by expanding product portfolios, improving formulations to support adherence, and strengthening clinic engagement through education and support programs. Differentiation also comes from mechanism-of-action positioning and the ability to serve both maintenance and flare-control needs. Distribution partnerships and refill channel access are becoming increasingly important for long-term therapy persistence.
Zoetis Inc. remains a prominent participant through continued emphasis on targeted therapy options and portfolio refresh strategies in canine dermatology. Product lifecycle initiatives focused on administration convenience and owner adherence support sustained demand in chronic categories. Clinic engagement, veterinary education, and broad distribution access strengthen therapy initiation and refill continuity. Ongoing innovation activity also supports competitive defense against new entrants and expanding targeted oral options. Portfolio depth across companion animal therapeutics helps reinforce a stable market position.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Zoetis Inc.
- Elanco Animal Health
- Merck Animal Health (MSD Animal Health / Merck & Co., Inc.)
- Virbac
- Dechra Pharmaceuticals
- Ceva Santé Animale
- Vetoquinol
- Boehringer Ingelheim Animal Health
- Bioiberica S.A.U.
- Nextmune
- Toray Industries, Inc.
- Bioceltix S.A.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In December 2025, Elanco Animal Health received USDA approval for Befrena (tirnovetmab), a new anti-IL31 monoclonal antibody injection targeting canine allergic and atopic dermatitis, and the company said it expects a U.S. launch in the first half of 2026.
- In September 2025, Elanco also announced that the FDA approved an updated U.S. Zenrelia label removing prior vaccine-induced disease language, which the company said brought the label closer to versions already approved in markets including the European Union, Great Britain, Brazil, and Japan.
- In June 2025, Elanco’s Zenrelia received a positive opinion from the European Medicines Agency’s Committee for Veterinary Medicinal Products, a step that could support marketing authorization in Europe for the canine dermatitis therapy by the end of the third quarter of 2025.
- In September 2024, Elanco Animal Health announced the FDA approval and launch of Zenrelia (ilunocitinib tablets), a once-daily oral JAK inhibitor for the control of itching and inflammation associated with allergic and atopic dermatitis in dogs at least 12 months old.
Report Scope
| REPORT ATTRIBUTE | DETAILS |
| Market size value in 2025 | USD 5352 million |
| Revenue forecast in 2032 | USD 10698.31 million |
| Growth rate (CAGR) | 10.4% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Drug Class Outlook: Antihistamines; Corticosteroids / Glucocorticoids; Calcineurin Inhibitors (Cyclosporine); Janus Kinase (JAK) Inhibitors (Oclacitinib); Monoclonal Antibodies / Interleukin Inhibitors (Lokivetmab) | By Type Outlook: Prescription; OTC | By Mode of Administration Outlook: Oral; Topical; Injectable | By Molecule Type Outlook: Small-Molecule Drugs; Biologics | By Indication Outlook: Ectoparasites; Food Allergy; Allergic Skin Infections; Others | By Dog Breed Outlook: German Shepherd; Terriers; Retrievers; Others | By Distribution Channel Outlook: Veterinary Hospitals / Clinics; Retail Pharmacies; Online Pet Pharmacies |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Zoetis Inc.; Elanco Animal Health; Merck Animal Health (MSD Animal Health / Merck & Co., Inc.); Virbac; Dechra Pharmaceuticals; Ceva Santé Animale; Vetoquinol; Boehringer Ingelheim Animal Health; Bioiberica S.A.U.; Nextmune; Toray Industries, Inc.; Bioceltix S.A. |
| No.of Pages | 340 |
Segmentation
By Drug Class- Antihistamines
- Corticosteroids / Glucocorticoids
- Calcineurin Inhibitors (Cyclosporine)
- Janus Kinase (JAK) Inhibitors (Oclacitinib)
- Monoclonal Antibodies / Interleukin Inhibitors (Lokivetmab)
- Prescription
- OTC
- Oral
- Topical
- Injectable
- Small-Molecule Drugs
- Biologics
- Ectoparasites
- Food Allergy
- Allergic Skin Infections
- Others
- German Shepherd
- Terriers
- Retrievers
- Others
- Veterinary Hospitals / Clinics
- Retail Pharmacies
- Online Pet Pharmacies
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Diagnosis and Long-Term Disease Management
Increased owner awareness and improved veterinary diagnostic workflows are leading to earlier and more frequent diagnosis of canine atopic dermatitis, expanding the treated population and driving sustained demand for prescription therapies and repeat purchasing.
Shift Toward Targeted Immunomodulatory Therapies
Veterinarians and pet owners are increasingly favoring biologics and selective small-molecule drugs for their durable symptom control and improved safety profiles, reducing reliance on broad immunosuppression and supporting premium product uptake.
Premiumization in Companion Animal Healthcare Spending
Higher willingness to pay for advanced dermatology regimens, growth in pet insurance, and subscription-based pharmacy models are enabling broader adoption of premium therapies and consistent refills, fueling overall market expansion.
Expansion of Veterinary Service Access and Specialty Care
Growth in veterinary clinic networks and referral capacity is improving access to dermatology-informed diagnosis and treatment, supporting earlier intervention, structured management plans, and increasing the addressable market.
Distribution Channel Evolution and Refill Convenience
The rise of online pet pharmacies and integrated clinic-to-pharmacy workflows is making it easier for owners to maintain chronic therapy regimens, improving adherence and supporting recurring revenue streams for long-term disease management.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and forecast size of the Canine Atopic Dermatitis Market?
What is the CAGR of the Canine Atopic Dermatitis Market during 2025–2032?
Which segment is the largest in 2025?
What factors are driving growth in this market?
Who are the leading companies operating in the market?
Which region leads the Canine Atopic Dermatitis Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Class
- 1.2.1 Antihistamines
- 1.2.2 Corticosteroids / Glucocorticoids
- 1.2.3 Calcineurin Inhibitors (Cyclosporine)
- 1.2.4 Janus Kinase (JAK) Inhibitors (Oclacitinib)
- 1.2.5 Monoclonal Antibodies / Interleukin Inhibitors (Lokivetmab)
- 1.3 By Molecule Type
- 1.3.1 Small-Molecule Drugs
- 1.3.2 Biologics
- 1.4 By Mode of Administration
- 1.4.1 Oral
- 1.4.2 Topical
- 1.4.3 Injectable
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 5352 million → 2032: USD 10698.31 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Canine Atopic Dermatitis Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Canine Atopic Dermatitis Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Canine Atopic Dermatitis Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Canine Atopic Dermatitis Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Canine Atopic Dermatitis Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Canine Atopic Dermatitis Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Canine Atopic Dermatitis Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Canine Atopic Dermatitis Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 5352 million → 2032: USD 10698.31 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Canine Atopic Dermatitis Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Class - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Antihistamines
- 12.3.7.2 Corticosteroids / Glucocorticoids
- 12.3.7.3 Calcineurin Inhibitors (Cyclosporine)
- 12.3.7.4 Janus Kinase (JAK) Inhibitors (Oclacitinib)
- 12.3.7.5 Monoclonal Antibodies / Interleukin Inhibitors (Lokivetmab)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Molecule Type - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Small-Molecule Drugs
- 12.4.7.2 Biologics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Mode of Administration - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oral
- 12.5.7.2 Topical
- 12.5.7.3 Injectable
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Canine Atopic Dermatitis Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Canine Atopic Dermatitis Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Canine Atopic Dermatitis Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Zoetis Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Elanco Animal Health
- 17.4 Merck Animal Health (MSD Animal Health / Merck & Co., Inc.)
- 17.5 Virbac
- 17.6 Dechra Pharmaceuticals
- 17.7 Ceva Santé Animale
- 17.8 Vetoquinol
- 17.9 Boehringer Ingelheim Animal Health
- 17.10 Bioiberica S.A.U.
- 17.11 Nextmune
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

