
Market Overview:
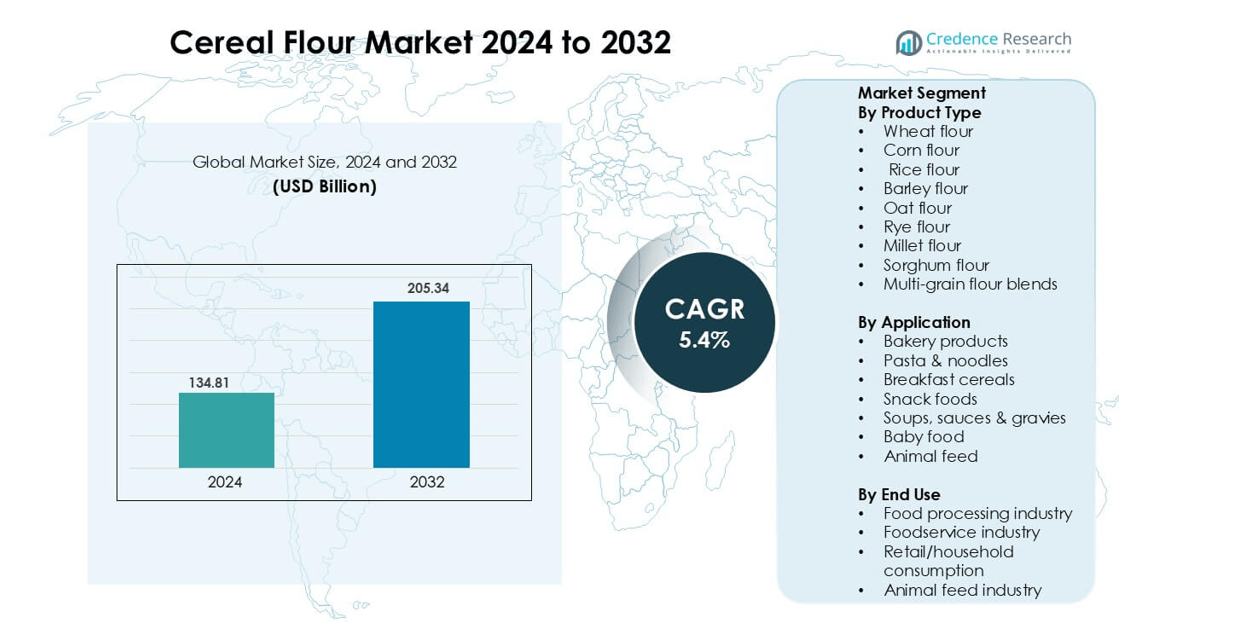
Cereal Flour Market was valued at USD 134.81 billion in 2024 and is anticipated to reach USD 205.34 billion by 2032, growing at a CAGR of 5.4 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cereal Flour Market Size 2024 | USD 134.81 billion |
| Cereal Flour Market, CAGR | 5.4% |
| Cereal Flour Market Size 2032 | USD 205.34 billion |
Leading companies in the Cereal Flour Market include Archer Daniels Midland Company, Ardent Mills LLC, Cargill, Bunge Limited, COFCO Corporation, Bob’s Red Mill Natural Foods, Bay State Milling Company, Conagra Brands Inc., Flour Mills of Nigeria Plc, and Associated British Foods plc. large processors dominate bulk supply to packaged food manufacturers and bakeries, while specialty brands focus on organic, gluten-free, and multi-grain blends. Asia-Pacific is the leading regional market with a 36% share, driven by high consumption of noodles, bread, and traditional cereals, supported by strong milling capacity and rising demand for packaged food products.
Market Insights
- The Cereal Flour Market stands at USD 134.81 billion in 2024 and grows at a CAGR of 5.4 % during the forecast period.
- Rising demand for bakery items, noodles, breakfast cereals, and ready mixes drives large-scale flour procurement from food processors and retail brands.
- Multi-grain blends, gluten-free flour, and fortified products gain strong momentum, supported by clean-label, high-fiber, and health-focused consumer trends across urban markets.
- The competitive landscape features Archer Daniels Midland Company, Ardent Mills LLC, Cargill, Bunge Limited, and COFCO Corporation, while Bob’s Red Mill and Bay State Milling strengthen premium and specialty categories.
- Asia-Pacific holds the largest regional share at 36%, while wheat flour leads the product segment with 46% share, supported by strong bakery and packaged food consumption across fast-growing economies.
Market Segmentation Analysis:
By Product Type
Wheat flour leads the product segment with a market share of 46%, driven by high use in bakery, snacks, and household cooking. Wheat supports strong gluten properties, better dough elasticity, and wide consumer acceptance. Corn and rice flour show stable demand in gluten-free snacks and breakfast items, while barley, rye, oats, millet, and sorghum support the healthy-grain category. Multi-grain flour blends are growing due to fiber, protein, and micronutrient benefits, especially in urban retail. Rising clean-label trends and fortified flour products continue to push demand across packaged food brands and private-label manufacturers.
- For instance, Ardent Mills also confirms that it has doubled its organic wheat supply base in the United States by partnering with its grower network, enabling launch of multi‑grain blends with traceability from seed to shelf.
By Application
Bakery products dominate the application segment with 41% share, owing to strong consumption of bread, biscuits, cookies, cakes, and pastries. Flour offers structure, volume, and texture benefits that make bakery production consistent and scalable. Breakfast cereals and pasta & noodles also show firm growth due to higher convenience food intake in urban regions. Snack foods adopt corn, rice, and multi-grain flour for extruded chips, crackers, and ready-to-eat packs. Soups, sauces, gravies, baby food, and animal feed rely on flour for viscosity, binding, and nutritional enrichment, supporting steady industrial demand.
- For instance, First Milling Company in Saudi Arabia reported that its bakery‑flour product extraction rate reached 80% of the wheat grain at one of its modern mills, optimising yield for bread and pastry applications.
By End Use
The food share as dominant end use, driven by large-scale bakery processing industry holds 57% chains, packaged food manufacturers, and cereal processors. Companies demand uniform particle size, longer shelf stability, and safe additive-free flour grades. The foodservice sector also uses bulk flour in bakeries, restaurants, and quick-service outlets. Retail or household consumption continues to rise with increasing home baking and interest in millet, sorghum, and multi-grain blends. The animal feed industry uses barley, sorghum, and corn flour as energy-rich additives. Growing packaged food penetration and higher disposable income support volume expansion across all channels.
Key Growth Drivers
Rising Consumption of Bakery and Convenience Foods
Demand for packaged bakery goods, ready-to-cook mixes, noodles, and breakfast cereals continues to expand, especially in urban markets. Busy lifestyles and the preference for quick meal options support higher use of wheat, corn, rice, and multi-grain flour across commercial bakeries and food processors. Growing café culture, organized retail, and QSR chains fuel flour consumption for breads, pastries, pizzas, and desserts. Many brands also launch instant mixes and ready-to-heat bakery products for at-home preparation. This steady shift toward convenience food keeps large volumes flowing into industrial production lines. Manufacturers focus on consistent quality, refined milling, and extended shelf life to meet bulk procurement standards from food companies.
- For instance, Ardent Mills operates more than 35 community flour mills and bakery-mix facilities in the U.S. and Canada, supplying large QSR chains with consistent high-protein flour that supports dough strength and stability. The company produces a vast number of specialty blends used in burger buns, tortillas, and pizzas. Their dedicated gluten-free facility in Harvey, North Dakota, processes certified gluten-free oat, quinoa, and amaranth flour that support premium bakery products.
Shift Toward Healthy, High-Fiber and Gluten-Free Alternatives
Demand for specialty flour such as oats, sorghum, millet, rice, and barley rises due to growing interest in natural fibers, whole grains, and clean-label ingredients. Health-conscious buyers prefer flour that supports weight management, digestive wellness, and nutrient-rich diets. Gluten-free bakery and snack launches increase adoption of rice and corn flour, while millet and sorghum attract attention for high mineral and protein content. Governments in several regions promote millet-based products through food programs and awareness campaigns, which encourages wider use in cereals, snacks, and school meals. Brands leverage this shift by developing healthier variants of traditional staples, strengthening product portfolios across retail and e-commerce platforms.
- For instance, Bob’s Red Mill introduced its whole‑grain millet flour product-stone‑ground from hulled millet and positioned for gluten‑free baking.
Expansion of Packaged Food Production and Modern Milling Technologies
Large-scale flour mills invest in high-capacity rollers, advanced grain sorting, and fortified formulations to serve industrial buyers. Improved packaging, moisture control, and hygienic milling help maintain freshness, reduce contamination, and extend storage life during long supply cycles. Food manufacturers prefer premium flour grades that offer uniform particle size, stable dough properties, and predictable baking results. Automation and digital monitoring reduce operational losses and enhance product consistency, making bulk production more cost-efficient. Growing exports of packaged flour and ready-mix bakery products also contribute to industry revenue, supported by international demand for ethnic breads, noodles, and convenience meals.
Key Trend and Opportunity
Growth of Multi-Grain Blends and Nutrient-Fortified Products
Health-focused consumers increasingly select flour blends containing oats, barley, millet, sorghum, or rye for digestive benefits, natural fiber, and better micronutrient intake. Bakery brands reformulate recipes using multi-grain mixes to offer healthier bread, cookies, crackers, and breakfast products. Fortification of flour with iron, vitamins, and minerals becomes common in both retail and industrial supply to address nutritional gaps in developing regions. Companies also market ancient grains and heritage cereals to appeal to premium, organic, and wellness-driven segments. The trend supports value-added pricing and product differentiation across supermarkets and specialty food outlets.
- For instance, ITC Limited under its Aashirvaad Nature s Super Foods brand launched Atta with Millets, Ragi Flour and Multi‑Millet Batter Mix to cater to value‑added, health‑oriented segments across staples, biscuits and noodles.
Rising Adoption in Gluten-Free and Plant-Based Foods
Gluten-free diets drive stronger demand for rice, corn, sorghum, and millet flour in bakery, snacks, and ready meals. Food brands expand their range of biscuits, pizza bases, cakes, and pasta made without wheat. Plant-based and vegan product lines use cereal flour for meat analogs, coatings, and texturing blends. Start-ups enter the market with artisan breads and gourmet health snacks using alternative flour sources. Growing awareness of food intolerances and clean-label eating makes this segment attractive for innovation. Higher retail visibility and online sales create opportunities for both established manufacturers and small niche producers.
- For instance, Rani launched a 1.81 kg (4 lbs) gluten‑free flour blend mixing sorghum, amaranth, chick‑peas, millet, soya and rice labelled vegan, non‑GMO and designed for flatbreads indicating niche product entry leveraging alternative flours.
Key Challenge
Price Fluctuations in Raw Grains
Weather changes, crop disease, geopolitical trade restrictions, and poor storage conditions affect wheat, corn, and rice availability. Price instability impacts flour mill margins and leads to cost pressure on food processors. Small mills struggle to compete when grain prices surge, while multinational players rely on long-term sourcing and large procurement contracts. Any disruption in supply pushes retail flour prices higher, which affects household consumption patterns. Import-dependent regions face currency issues and freight costs, creating uneven pricing across markets. These fluctuations make stable production and forecasting difficult for manufacturers.
Quality Consistency and Food Safety Concerns
Maintaining hygienic processing, pure grain sourcing, and controlled moisture levels is essential for safe flour production. Contamination from pesticides, storage insects, and mycotoxins can lead to product recalls and regulatory action. Traditional mills in developing regions may lack advanced cleaning and detection systems, increasing safety risks. Industrial buyers demand strict compliance with food-grade standards, pushing small producers to upgrade facilities or lose contracts. Shelf stability is another challenge, as temperature and humidity influence flour texture and freshness. These factors force manufacturers to invest in better milling equipment, lab testing, and packaging to protect brand reputation and consumer trust.
Regional Analysis
North America
North America holds a market share of 28%, driven by high consumption of bakery goods, packaged snacks, breakfast cereals, and ready-to-cook mixes. Large milling companies supply premium refined flour, gluten-free blends, and fortified variants to food manufacturers and retail chains. Demand for oat, barley, and multi-grain flour is strong due to clean-label and high-fiber preferences. The U.S. dominates regional use, supported by a mature food processing sector and strong exports of wheat-based products. Growing interest in plant-based and gluten-free bakery items continues to boost rice, sorghum, and corn flour across specialty brands and online sales channels.
Europe
Europe accounts for 31% market share, led by milling advancements, artisanal bakery culture, and long-established wheat consumption. The region uses high-quality refined and whole-grain flour for bread, pastries, biscuits, and confectioneries. Germany, Italy, France, and the U.K. drive large-scale industrial demand. Multi-grain products and rye, barley, and oat flour enjoy wide preference due to health-focused regulations and labeling standards. Foodservice outlets, cafés, and packaged bakery producers create consistent procurement for bulk flour. Strong retail presence of organic, fortified, and clean-label flour also helps sustain premium pricing across supermarkets and specialty bakeries.
Asia-Pacific
Asia-Pacific dominates the market with 36% share, supported by high consumption of noodles, bread, snacks, and traditional foods. Wheat flour demand rises with growth in urban bakeries, fast-food chains, and instant noodle producers. India and China lead large-scale production and consumption, backed by strong milling capacity and government food programs. Rice and corn flour supply gluten-free and baby food segments, while millet and sorghum gain popularity for nutritional benefits. Expanding packaged food industries, rising disposable incomes, and modern retail formats make the region a key growth driver for global flour manufacturers.
Latin America
Latin America holds 8% market share, driven by growing use of wheat and corn flour in bakery, snacks, tortillas, and breakfast items. Brazil, Mexico, and Argentina support large milling operations and processed food output. Corn flour shows strong penetration in traditional foods and snack manufacturing. Health-conscious consumers shift toward whole-grain and multi-grain blends, especially in urban supermarkets. Expanding foodservice chains and investment in packaged food brands contribute to higher flour demand. However, fluctuating grain costs and import dependency in some countries affect pricing and supply consistency.
Middle East & Africa
Middle East & Africa account for 7% market share, supported by wheat-based breads, flatbreads, biscuits, and ready mixes. Gulf countries depend on imports for high-quality milling wheat, while local processors add value through fortified flour and bakery premixes. Expanding retail infrastructure, café culture, and consumer shift toward packaged food promote flour demand. Africa sees rising consumption in noodles, baby food, and biscuits, supported by government nutrition programs. However, supply limitations, high logistics costs, and occasional raw grain shortages challenge market stability, creating opportunities for regional milling expansion and local crop development.
Market Segmentations
By Product Type
- Wheat flour
- Corn flour
- Rice flour
- Barley flour
- Oat flour
- Rye flour
- Millet flour
- Sorghum flour
- Multi-grain flour blends
By Application
- Bakery products
- Pasta & noodles
- Breakfast cereals
- Snack foods
- Soups, sauces & gravies
- Baby food
- Animal feed
By End Use
- Food processing industry
- Foodservice industry
- Retail/household consumption
- Animal feed industry
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Cereal Flour Market features a strong mix of multinational grain processors, regional milling companies, and specialty flour brands competing through product quality, geographic reach, and value-added offerings. Major players such as Archer Daniels Midland Company, Ardent Mills LLC, Cargill, Bunge, and COFCO Corporation operate large milling networks and supply bulk quantities to food manufacturers, bakeries, and foodservice chains. These companies focus on high-capacity production, fortified flour blends, and improved grain sourcing to maintain consistent quality. Specialty producers like Bob’s Red Mill and Bay State Milling expand demand for whole-grain, gluten-free, and organic flour targeting health-conscious consumers and premium retail stores. Many companies invest in modern milling, automated packaging, and grain quality testing to meet strict food safety standards. Partnerships with packaged food brands, rising e-commerce distribution, and premium multi-grain blends help increase market penetration and brand visibility across global and regional markets.
Key Player Analysis
- Bob's Red Mill Natural Foods
- COFCO Corporation
- Conagra Brands, Inc.
- Ardent Mills LLC
- Flour Mills of Nigeria Plc
- Bunge Limited
- Cargill, Incorporated
- Archer Daniels Midland Company
- Bay State Milling Company
- Associated British Foods plc
Recent Developments
- In May 2025, a bulk carrier unloaded 10,600 tons of Canadian durum wheat at a port in Shanghai, purchased by COFCO International, COFCO's international trading arm.
- In March 2025, Bob's Red Mill Natural Foods was named to Fast Company’s annual list of the world’s most innovative companies
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for healthy and whole-grain flour continues to rise in global retail.
- Gluten-free and multi-grain blends gain wider acceptance in bakery and snacks.
- Automation in milling and packaging improves product safety and consistency.
- Specialty flour producers expand into premium and organic product ranges.
- Foodservice chains drive higher consumption of refined and ready-mix flour.
- E-commerce strengthens distribution of retail flour and bakery mixes.
- Fortified flour adoption increases due to nutritional awareness campaigns.
- Emerging markets invest in local milling to reduce import dependency.
- Clean-label and additive-free flour becomes a major product focus.
- Demand from baby food, breakfast cereals, and instant meals keeps rising.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Cereal Flour Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cereal Flour Market projected to grow between 2025 and 2032?
Which Cereal Flour Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cereal Flour Market?
Who are the leading companies in the Cereal Flour Market?
Which region commanded the largest share of the Cereal Flour Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 134.81 billion → 2032: USD 205.34 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cereal Flour Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cereal Flour Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cereal Flour Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cereal Flour Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cereal Flour Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cereal Flour Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cereal Flour Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cereal Flour Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 134.81 billion → 2032: USD 205.34 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cereal Flour Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cereal Flour Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cereal Flour Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cereal Flour Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

