
Market overview
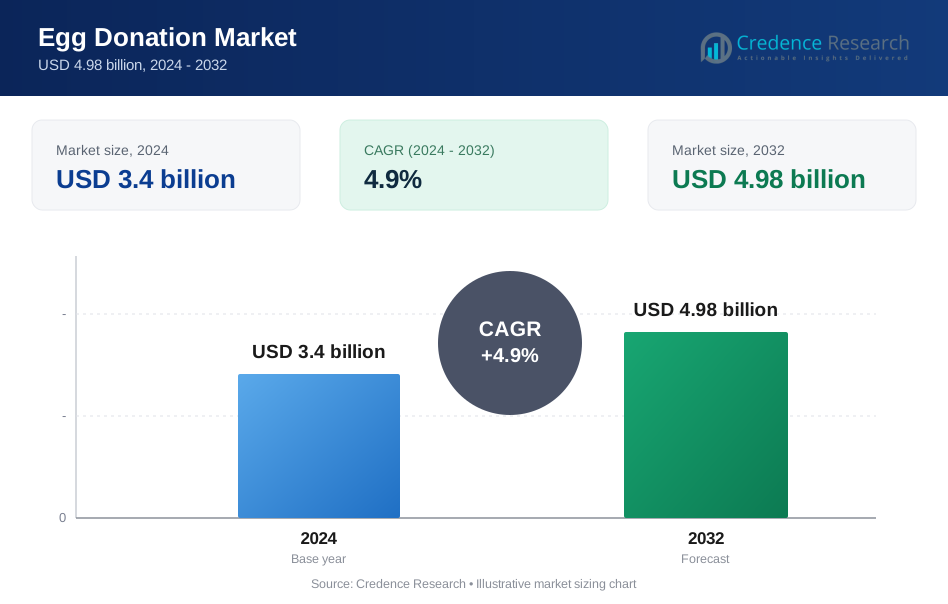
The egg donation market was valued at USD 3.4 billion in 2024 and is anticipated to reach USD 4.98 billion by 2032, at a CAGR of 4.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Egg Donation Market Size 2024 | USD 3.4 billion |
| Egg Donation Market, CAGR | 4.9% |
| Egg Donation Market Size 2032 | USD 4.98 billion |
The egg donation market is highly competitive, with key players driving innovation and service expansion across various regions. Leading companies include Virtus Health, Monash IVF Group, Flinders Reproductive Medicine Pty Ltd, and Morpheus Life Sciences Pvt. Ltd. These organizations are at the forefront of providing comprehensive fertility treatments, including egg donation services. North America holds the largest market share of approximately 31%, driven by the presence of advanced fertility clinics and widespread adoption of assisted reproductive technologies. Europe follows closely, contributing 25% of the market, with strong demand for egg donation services in countries like Spain and the UK. The Asia Pacific region is growing rapidly, expected to reach 20% of the market share by 2032, fueled by increasing infertility rates and expanding healthcare infrastructure. These leading players continue to drive regional growth, benefiting from a combination of regulatory support, technological advancements, and rising awareness.

Market Insights
- The egg donation market was valued at USD 3.4 billion in 2024 and is projected to reach USD 4.98 billion by 2032, growing at a CAGR of 4.9% during the forecast period.
- Key drivers include increasing infertility rates, advancements in reproductive technologies, and growing awareness of fertility preservation, all contributing to the rising demand for egg donation services globally.
- Trends such as fertility tourism, personalized fertility treatments, and genetic screening are driving growth, with a strong emphasis on making services more accessible and affordable.
- The market is highly competitive, with leading players like Virtus Health, Monash IVF Group, and Morpheus Life Sciences Pvt. Ltd. dominating in North America, which holds a 31% market share, followed by Europe at 25%, and Asia Pacific at 20%.
- Regional restraints include regulatory complexities, ethical concerns, and high treatment costs, especially in developing regions, limiting broader access to egg donation services.
Market Segmentation Analysis
By Service Type
The egg donation market is primarily segmented into Fresh Egg Donation, Frozen Egg Donation, Egg Sharing Programs, and Anonymous Donation. Among these, Frozen Egg Donation holds the dominant market share, accounting for approximately 45% of the total market. The increasing preference for frozen eggs is driven by their ability to offer flexibility in fertility treatments, as they can be stored for extended periods. Additionally, the rise in fertility preservation awareness and technological advancements in egg freezing have contributed significantly to the growth of this sub-segment.
- For instance, Cryos International A/S is known for its advanced cryopreservation technologies, setting global standards for safety and donor-recipient matching, which has improved the availability and success of frozen egg donations.
By Application
In the egg donation market, the leading application segments are In Vitro Fertilization (IVF), Fertility Preservation, Genetic Disorder Prevention, and Age-Related Infertility. The IVF segment holds the largest market share, estimated at 55%, due to the growing number of individuals opting for IVF treatments as a solution to infertility. Factors such as improved IVF success rates, advancements in reproductive technologies, and increased accessibility to fertility clinics have accelerated the demand for egg donations in IVF procedures. As IVF continues to be a popular choice, this segment is expected to maintain its strong growth trajectory.
- For instance, companies like Perdigó are innovating in IVF medical devices, using AI-driven technologies and microfluidics to improve egg retrieval and embryo transfer efficiency.
By End User
The End User segment of the egg donation market includes Women Above 35, Couples with Genetic Disorders, Cancer Patients, and the LGBTQ Community. The Women Above 35 segment dominates the market with a share of approximately 40%, driven by the rising trend of delayed pregnancies and the biological challenges associated with age-related infertility. Increased awareness about fertility preservation and the availability of egg donation as a solution for older women are key factors contributing to the growth of this segment. The need for fertility solutions among this demographic remains a significant driver of market expansion.
Key Growth Drivers
Increasing Infertility Rates
One of the key growth drivers in the egg donation market is the rising global infertility rate. Infertility issues, both male and female, are becoming increasingly prevalent due to factors such as lifestyle changes, delayed marriages, and environmental influences. This trend is particularly notable among women over the age of 35, who are experiencing age-related infertility. As these women seek alternative reproductive options, egg donation has emerged as a vital solution. Additionally, the growing awareness about fertility preservation and assisted reproductive technologies (ART), including egg donation, has led to a surge in demand.
- For instance, WHO's data highlights comparable infertility rates across high-, middle-, and low-income countries, reflecting a global health challenge.
Advancements in Reproductive Technologies
Advancements in reproductive technologies are significantly propelling the egg donation market. Innovations such as improved egg freezing techniques, better screening processes for donors, and enhanced IVF protocols have made egg donation a more viable and accessible option for individuals and couples facing infertility. With enhanced success rates in fertility treatments and a better understanding of the egg freezing process, more women are choosing to preserve their fertility at younger ages. Additionally, technological advancements have made it easier to match donors and recipients, ensuring better outcomes for both parties.
- For instance, vitrification an advanced rapid freezing technique has substantially increased egg survival rates by minimizing ice crystal formation and reducing cryoprotectant toxicity, leading to higher fertilization success.
Growing Awareness of Fertility Preservation
The growing awareness of fertility preservation among both men and women is another key driver of the egg donation market. Increasing societal focus on career-building and delaying childbearing, especially among women, has raised awareness about the need for fertility preservation. Women who wish to delay motherhood now have the option to freeze their eggs for later use. Furthermore, there is heightened awareness regarding the benefits of egg donation for individuals facing fertility challenges, such as cancer patients or those with genetic disorders. This increased understanding, coupled with better access to fertility services, has led to an uptick in demand for egg donation as a solution for preserving fertility and achieving successful pregnancies later in life.
Key Trends & Opportunities
Growth of Fertility Tourism
Fertility tourism, or reproductive tourism, is becoming a notable trend in the egg donation market. With the high costs and long waiting times for fertility treatments in certain regions, many individuals and couples are seeking reproductive services abroad. Countries with advanced fertility clinics and less stringent regulations are attracting patients from regions where fertility treatments are more expensive or less accessible. This trend presents a significant opportunity for fertility clinics to expand their services and target international patients. By offering competitive pricing and shorter treatment timelines, these clinics can capitalize on the growing demand for egg donation treatments worldwide, contributing to the global market's growth.
- For instance, Spain has become a leading destination for fertility tourism due to its progressive reproductive laws, high success rates, and world-class medical facilities.
Rise in LGBTQ+ Fertility Treatments
The increasing acceptance and recognition of LGBTQ+ rights and family-building options have opened up new opportunities in the egg donation market. With a growing number of same-sex couples and single individuals in the LGBTQ+ community seeking reproductive assistance, the demand for egg donation services has surged. Fertility clinics are responding by offering tailored services to LGBTQ+ families, such as egg donation combined with IVF or surrogacy services. This trend is expected to continue to grow, driven by the increasing legal and societal acceptance of LGBTQ+ families and the rising number of individuals in this community seeking to have biological children.
- For instance, PureOvum in California is a leading egg donor agency known for its inclusive approach, offering personalized programs specifically supporting LGBTQ+ family building.
Key Challenges
Ethical and Legal Considerations
The egg donation market faces significant ethical and legal challenges that may impact its growth. In many regions, there are legal restrictions surrounding egg donation, such as anonymity for donors, compensation limits, and regulations on the number of donations per donor. Furthermore, ethical concerns regarding the commodification of human eggs, the rights of donors, and the potential exploitation of women in underprivileged circumstances have led to increased scrutiny. Legal frameworks governing egg donation vary by country, and these inconsistencies pose a challenge for global market expansion. Fertility clinics must navigate these ethical and legal complexities to ensure they comply with local laws while maintaining ethical standards.
High Cost of Egg Donation Services
The high cost of egg donation services remains one of the major challenges facing the market. Egg donation, including IVF treatments and associated services, can be prohibitively expensive, especially for individuals seeking multiple cycles or additional services such as genetic screening. The cost of compensating donors, combined with medical fees for the retrieval and storage of eggs, further increases the overall expense. This can limit access to egg donation services, particularly for lower-income individuals or couples. Despite advances in fertility treatment technologies, the financial barrier remains a significant hurdle for market growth.
Regional Analysis
North America
North America holds a dominant share of 31% of the global egg donation market. The United States is the primary contributor, benefiting from advanced infrastructure in assisted reproductive technologies, widespread awareness of fertility options, and supportive regulatory and reimbursement frameworks. These factors drive strong demand for egg donation services. Additionally, the presence of numerous fertility clinics, donor banks, and innovative treatment protocols further solidifies North America’s leadership. The continued expansion of medical tourism and cross-border fertility treatments supports the region’s market dominance.
Europe
Europe represents a significant portion of the egg donation market, contributing 25% of the global market share. The region’s well-established healthcare infrastructure, combined with an aging maternal population, has driven growing demand for egg donation services. Countries like Spain and the Czech Republic are prominent fertility tourism destinations, attracting patients seeking affordable and high-quality fertility treatments. The region benefits from a mix of regulations that support fertility treatments, though differences in donor anonymity laws and reimbursement policies may create some challenges and variations in market dynamics.
Asia Pacific
Asia Pacific (APAC) is the fastest-growing region in the egg donation market, with a projected market share of 20% by 2032. Rising infertility rates, delayed childbearing, and increasing awareness of fertility treatments are key drivers of this growth. The expansion of fertility clinics in India, China, and Southeast Asia, along with the region’s growing medical tourism industry, are accelerating demand. APAC’s cost-effective services, coupled with increasing healthcare access, make it a promising market. However, regulatory and cultural factors may slow progress in certain countries.
Latin America
Latin America accounts for 10% of the global egg donation market. The region is characterized by an increasing adoption of fertility services, rising disposable incomes, and growing acceptance of assisted reproductive technologies. Countries such as Brazil and Mexico are becoming significant players, offering lower-cost fertility treatments compared to North America and Europe, which fuels the region’s market growth. However, varying regulatory frameworks and affordability remain challenges, and the market’s potential is closely tied to expanding fertility clinic networks and medical tourism.
Middle East & Africa (MEA)
The Middle East and Africa (MEA) region currently holds a smaller market share of 5% but is expected to grow steadily over the next decade. Factors such as improving healthcare infrastructure, rising fertility awareness, and increasing demand for fertility treatments from neighboring regions are contributing to growth. However, cultural and religious constraints, as well as varied regulations across countries, present significant challenges. As fertility clinics expand and cross-border treatments become more accepted, MEA is poised to capture a larger share of the global market.
Market Segmentations:
By Service Type
- Fresh Egg Donation
- Frozen Egg Donation
- Egg Sharing Programs
- Anonymous Donation
By Application
- In Vitro Fertilization
- Fertility Preservation
- Genetic Disorder Prevention
- Age-Related Infertility
By End User
- Women Above 35
- Couples with Genetic Disorders
- Cancer Patients
- LGBTQ Community
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape in the global egg donation market is marked by the presence of well‑established fertility clinics and specialist egg‑bank providers that are continually refining their service portfolios to stay ahead. Key players such as Flinders Reproductive Medicine Pty Ltd, Virtus Health and Monash IVF Group lead by leveraging extensive clinic networks and integrated donor‑program platforms. Meanwhile, firms like Morpheus Life Sciences Pvt. Ltd and Chennai Fertility Center are making headway in emerging markets by focusing on cost‑effective solutions and fertility tourism. Other notable players—such as Medfem Fertility Clinic, TRIO Fertility, The Cape Fertility Clinic, Bourn Hall International and Aevitus Fertility Clinic—are distinguishing themselves through niche donor databases, advanced cryopreservation technologies and personalized care pathways. This dynamic competitive scenario pushes service innovation, donor‑pool diversification and geographic expansion as firms race to capture growing demand across different demographic and regional segments.
Key Player Analysis
- Virtus Health
- Medfem Fertility Clinic
- Bourn Hall International
- Monash IVF Group
- Morpheus Life Sciences Pvt. Ltd
- The Cape Fertility Clinic
- Aevitus Fertility Clinic
- Chennai Fertility Center
- TRIO Fertility
- Flinders Reproductive Medicine Pty Ltd
Recent Developments
- In 2025, The World Egg and Sperm Bank proposed a “Client Success Reward Programme” for Australian IVF clinics.
- In October 2025, Sims IVF (Ireland) launched a new in-house donor-egg programme in partnership with Next Fertility (Faro, Portugal).
Report Coverage
The research report offers an in-depth analysis based on Service Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Heightened demand will emerge from increasing numbers of women delaying parenthood due to career or lifestyle choices.
- Technological advancements in cryopreservation methods will boost the viability and availability of donated eggs.
- Fertility clinics will increasingly integrate genetic screening to enhance success rates and attract more clients.
- Cross‑border fertility services will expand as patients seek cost‑effective and accessible egg donation treatments globally.
- Clinics will develop specialized programs tailored to the LGBTQ community and single individuals seeking biological parenthood.
- Growth will accelerate in emerging markets driven by rising fertility awareness, improving healthcare infrastructure, and expanding middle‑class incomes.
- Data analytics and donor‑recipient matching technologies will optimize donor selection and improve treatment outcomes.
- Strategic partnerships and consolidations among fertility service providers will strengthen regional coverage and operational efficiency.
- Transparent pricing models and bundled treatment packages will make egg donation services more accessible and reduce cost barriers.
- Regulatory frameworks will evolve to standardize practices, enhance ethical safeguards, and support market expansion in new jurisdictions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Egg Donation market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Egg Donation market projected to grow between 2025 and 2032?
Which Egg Donation market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Egg Donation market?
Who are the leading companies in the Egg Donation market?
Which region commanded the largest share of the Egg Donation market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Egg Donation Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Egg Donation Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3.4 billion → 2032: USD 4.98 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Egg Donation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Egg Donation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Egg Donation Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Egg Donation Market Drivers
- 3.3 Egg Donation Market Restraints & Challenges
- 3.4 Egg Donation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Egg Donation Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Egg Donation Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Egg Donation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Egg Donation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Egg Donation Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Egg Donation market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Egg Donation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Egg Donation Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Egg Donation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Egg Donation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Egg Donation Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Egg Donation Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Egg Donation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Egg Donation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Egg Donation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Egg Donation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Egg Donation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Egg Donation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Egg Donation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
