
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Chemical Mechanical Planarization Market Size 2024 | USD 5402.5 Million |
| Chemical Mechanical Planarization Market, CAGR | 5.5% |
| Chemical Mechanical Planarization Market Size 2032 | USD 8291.14 Million |
Market Overview:
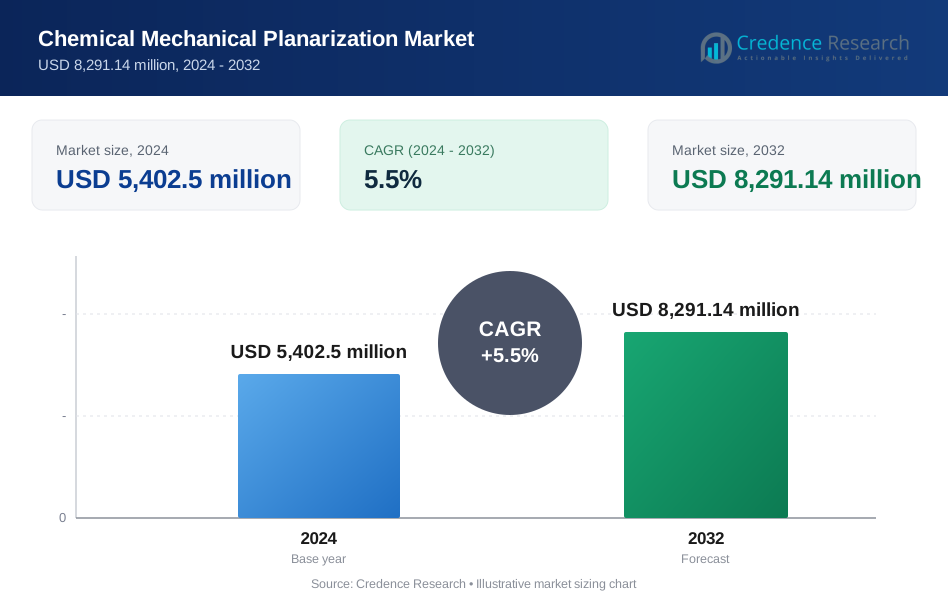
The Chemical Mechanical Planarization Market is projected to grow from USD 5402.5 million in 2024 to an estimated USD 8291.14 million by 2032, with a compound annual growth rate (CAGR) of 5.5% from 2024 to 2032.
Market growth is primarily driven by the rising need for high-performance, smaller, and more efficient semiconductor devices. The demand for planarization techniques is increasing as manufacturers seek to enhance wafer surface quality for advanced node technologies and multi-layered semiconductor structures. CMP plays a critical role in improving chip performance and reducing defects during the manufacturing process. Key drivers also include the growing adoption of CMP in 3D packaging technologies and the production of smaller node sizes such as 7nm and 5nm chips. Furthermore, rising investments in R&D for new CMP slurries, pads, and equipment are fueling innovation to meet the industry's evolving requirements.
Regionally, Asia-Pacific dominates the CMP market, driven by the presence of major semiconductor manufacturing hubs in countries like China, South Korea, Taiwan, and Japan. The region's strong infrastructure, rising demand for consumer electronics, and increasing investments in fabrication facilities (fabs) contribute to its leadership. North America follows closely, fueled by technological advancements, significant investments in semiconductor manufacturing, and the presence of key players. Europe is also emerging as a notable market, with growth in automotive electronics and advancements in industrial automation. Meanwhile, regions like Latin America and the Middle East & Africa show potential for expansion, driven by increasing digitalization and government initiatives to develop local semiconductor industries.
Market Insights:
- The Chemical Mechanical Planarization (CMP) market is projected to grow from USD 5,402.5 million in 2024 to USD 8,291.14 million by 2032, at a steady CAGR of 5%, driven by the increasing demand for advanced semiconductor devices.
- The rise of smaller node technologies like 7nm, 5nm, and sub-3nm is boosting the adoption of CMP to achieve superior wafer surface quality and ensure defect-free semiconductor production.
- Rapid growth in 3D packaging technologies and multi-layered ICs, particularly in 3D NAND memory production, is driving innovation in CMP processes to handle more complex and layered architectures.
- Asia-Pacific dominates the CMP market, accounting for nearly 50-55% of the share, with key players like TSMC, Samsung, and SMIC leading investments in semiconductor manufacturing infrastructure.
- North America contributes 20-25%, supported by the CHIPS Act, which allocates $52 billion for domestic semiconductor production, and initiatives from companies like Intel to expand fab capacities.
- Technological advancements in CMP slurries and polishing pads are fueling market growth, with a focus on improving material removal efficiency, process precision, and minimizing surface defects.
- Challenges such as high equipment costs, environmental concerns, and the complexity of integrating CMP for new materials like cobalt and low-k dielectrics continue to create hurdles, particularly for smaller market entrants.
Market Drivers:
Rising Demand for Advanced Semiconductor Devices
The increasing demand for advanced semiconductor devices is a primary driver of the Chemical Mechanical Planarization (CMP) market. As technology continues to evolve, there is a growing need for smaller, more efficient, and high-performance chips. Devices such as smartphones, tablets, and laptops require integrated circuits (ICs) with smaller node sizes, driving the need for advanced planarization processes. CMP is critical for achieving precise flatness and uniformity during the production of multi-layered semiconductor structures, ensuring superior device performance. For instance, Intel's PowerVia technology, which employs backside power delivery, has demonstrated a 6% frequency boost and 30% reduction in power loss. Additionally, the rapid development of cutting-edge technologies such as 5G, IoT, AI, and high-performance computing has further amplified the demand for advanced node technologies like 7nm, 5nm, and beyond, where CMP is indispensable.
Adoption of 3D Packaging and Multi-Layered ICs
The rising adoption of 3D packaging technologies and multi-layered ICs is another significant factor contributing to the growth of the CMP market. Modern semiconductor designs require increased integration and higher circuit densities to meet the performance demands of today’s applications. To facilitate 3D IC stacking, planarization processes such as CMP are essential for achieving uniform surfaces across layers, minimizing defects, and enabling higher yields. For example, Cu-Cu bumpless hybrid bonding, which combines a dielectric material with embedded metal, allows for interconnect pitches in the single-digit micrometer range and bandwidths up to 1000 GB/s. Furthermore, 3D NAND memory and system-on-chip (SoC) designs rely heavily on CMP techniques to ensure smooth and precise wafer surfaces. This trend toward advanced packaging solutions not only enhances the performance of electronic devices but also fuels continuous innovation in CMP slurries, pads, and consumables.
Technological Advancements in CMP Consumables and Equipment
The CMP market is witnessing considerable growth due to technological advancements in CMP consumables such as slurries and polishing pads, as well as equipment used in planarization processes. Manufacturers are focusing on developing highly specialized slurries tailored for different materials, including copper, aluminum, and dielectric layers, to improve efficiency and reduce material loss during the planarization process. For instance, Applied Materials has introduced a new CMP slurry that reduces defectivity by 30% while maintaining high removal rates. Similarly, the introduction of advanced CMP equipment with automated control systems and enhanced process monitoring capabilities is helping semiconductor manufacturers achieve higher levels of precision and throughput. Continuous R&D efforts to optimize CMP solutions for complex material systems and minimize defects are further boosting the market, ensuring high performance in next-generation semiconductors.
Increasing Investments in Semiconductor Fabrication Facilities
Rising investments in semiconductor fabrication facilities, particularly in Asia-Pacific and North America, are further driving the demand for CMP processes. The growing semiconductor demand has led to an increase in the construction of new fabs and expansion of existing facilities to meet the needs of industries such as consumer electronics, automotive, and telecommunications. For example, TSMC and Sony Semiconductor are building a $7 billion specialty fab in Kumamoto, Japan, to produce 28/22nm chips. Countries like China, South Korea, and Taiwan are heavily investing in semiconductor manufacturing infrastructure to solidify their position in the global market. Simultaneously, government initiatives and private investments in North America and Europe are fostering the establishment of advanced manufacturing facilities. This surge in production capacity highlights the critical role of CMP in ensuring high-quality semiconductor output, solidifying its importance in the manufacturing process as demand continues to grow
Market Trends:
Growing Adoption of Advanced Node Technologies
The increasing adoption of advanced node technologies, such as 5nm, 3nm, and beyond, is shaping the chemical mechanical planarization (CMP) market. Semiconductor manufacturers are pushing the limits of Moore's Law, which demands higher precision and tighter tolerances in wafer fabrication. As nodes become smaller, maintaining uniform surface planarization becomes increasingly complex and critical. CMP techniques are essential for achieving the required surface smoothness and preventing defects during the layering of transistors. Companies are investing in next-generation CMP solutions that can handle ultra-thin films and deliver superior performance at atomic levels. For example, Applied Materials' new CMP system has demonstrated a 20% improvement in planarization efficiency for 3nm nodes. The trend towards smaller nodes is further amplified by demand for advanced electronics, including artificial intelligence (AI) processors, quantum computing devices, and high-performance GPUs.
Expansion of 3D NAND and Logic Devices
The rise of 3D NAND flash memory and logic devices is driving a significant shift in the CMP market. With increasing storage capacity demands in data centers, cloud computing, and consumer electronics, manufacturers are developing multi-layered memory solutions that require complex planarization processes. CMP plays a critical role in ensuring layer uniformity and alignment during the fabrication of stacked memory architectures, which now surpass 176 layers and are expected to grow further. Similarly, advancements in logic devices, such as system-on-chip (SoC) and application processors, demand higher precision CMP processes to enhance reliability and yield. For instance, Samsung's latest 3D NAND technology features 256 layers, significantly increasing storage density and performance. These developments highlight the growing importance of CMP technologies in facilitating the transition to more sophisticated semiconductor architectures.
Advances in CMP Materials and Consumables
Innovation in CMP slurries, pads, and conditioning discs is a notable market trend, driven by the need to improve efficiency and reduce material loss. Manufacturers are developing customized CMP solutions to address challenges posed by new materials, such as low-k dielectrics, advanced metals (e.g., cobalt and ruthenium), and ultra-hard surfaces. For example, DuPont's new CMP slurry for cobalt has achieved a 15% reduction in defectivity while maintaining high removal rates. Additionally, advanced polishing pads are being designed with enhanced durability and performance to accommodate high-volume manufacturing processes. As semiconductor materials diversify, the CMP consumables market is expected to grow significantly to meet the evolving requirements of chipmakers.
Focus on Environmentally Friendly CMP Solutions
Sustainability is becoming a key focus in the CMP market, with manufacturers adopting eco-friendly practices to reduce waste and energy consumption. The semiconductor industry is under increasing pressure to minimize its environmental impact, prompting CMP solution providers to develop low-chemical, recyclable slurries and energy-efficient equipment. Advanced water filtration systems are also being implemented to reduce water consumption in CMP processes, which traditionally require significant amounts of ultrapure water. For example, Fujimi Corporation has introduced a new slurry recycling system that reduces water usage by 40%. These sustainability efforts align with global environmental regulations and semiconductor manufacturers' corporate responsibility goals. As the industry progresses, environmentally conscious CMP solutions are expected to gain traction, balancing performance and ecological responsibility.
Market Challenges Analysis:
High Cost of CMP Equipment and Consumables
One of the significant challenges in the chemical mechanical planarization (CMP) market is the high cost associated with CMP equipment and consumables. CMP requires highly specialized tools, polishing pads, and slurries that contribute significantly to production expenses. Advanced equipment used for precision planarization comes with high upfront investment costs, especially as semiconductor nodes continue to shrink to 5nm and 3nm technologies. Additionally, the consumables, including slurries, pads, and conditioning discs, must be frequently replaced to maintain efficiency, further increasing operational costs. For smaller manufacturers or new market entrants, these high expenses can act as a barrier to adoption, limiting their ability to compete effectively in the market.
Complexity of CMP Process Integration
The increasing complexity of integrating CMP processes into advanced semiconductor manufacturing poses another challenge. As chips become smaller and more layered, achieving uniform planarization with minimal material removal variations becomes increasingly difficult. CMP must be carefully tailored for different materials, including low-k dielectrics, copper, and emerging metals like cobalt and ruthenium, which have unique chemical and mechanical properties. Variations in slurry chemistry, pad performance, and wafer characteristics require meticulous process control to prevent defects, scratches, and erosion. Such complexities demand extensive research and development (R&D) efforts, adding to the cost and time required to perfect the process.
Environmental and Regulatory Pressures
Environmental concerns and stringent regulations are further restraining the growth of the CMP market. The CMP process consumes large amounts of ultrapure water and generates chemical-laden wastewater, which can negatively impact the environment. Regulatory bodies are placing increasing pressure on manufacturers to adopt sustainable practices, such as reducing chemical usage and improving wastewater management. Implementing eco-friendly solutions often requires significant investments in advanced filtration systems and sustainable slurry formulations, which can be challenging for smaller players. Balancing production efficiency with environmental compliance remains a critical restraint for the CMP market.
Market Opportunities:
The growing demand for advanced semiconductor devices and the increasing complexity of chip architectures present substantial opportunities for the Chemical Mechanical Planarization (CMP) market. As industries transition to 5nm, 3nm, and upcoming sub-3nm node technologies, the need for precise planarization becomes critical for achieving high performance and reliability in integrated circuits (ICs). CMP plays an essential role in enabling next-generation chips, including processors, memory devices, and logic components, to meet the demands of advanced applications such as artificial intelligence (AI), 5G networks, autonomous vehicles, and quantum computing. The rise of 3D IC packaging and stacked memory architectures, such as 3D NAND flash exceeding 200 layers, further amplifies the demand for innovative CMP solutions capable of handling complex multi-layered surfaces and diverse material compositions.
Additionally, the emergence of new materials in semiconductor manufacturing, such as cobalt, ruthenium, and low-k dielectrics, offers opportunities for CMP providers to develop specialized slurries, pads, and equipment. Growing investment in semiconductor fabrication facilities (fabs), particularly in Asia-Pacific and North America, supports significant market expansion. Government initiatives to strengthen semiconductor supply chains and reduce reliance on imports are driving the establishment of new fabs, further boosting CMP demand. The shift toward sustainable CMP solutions, including eco-friendly slurries and reduced water consumption systems, also creates opportunities for manufacturers to cater to environmentally conscious chipmakers. By aligning with technological advancements and sustainability goals, the CMP market is poised to capitalize on the growing demands of the global semiconductor industry.
Market Segmentation Analysis:
The Chemical Mechanical Planarization (CMP) market is segmented by type, technology, application, and region, reflecting diverse growth opportunities.
By type, the market is divided into CMP consumables and CMP equipment. CMP consumables, including slurries, pads, and conditioners, dominate the segment due to their recurring need in wafer polishing processes. CMP equipment also holds a significant share, driven by increasing investments in advanced semiconductor manufacturing facilities.
By technology, the market is categorized into Leading Edge, More than Moore’s, and Emerging. The Leading Edge segment, focused on advanced node technologies such as 5nm and 3nm, holds the largest share as semiconductor manufacturers increasingly adopt next-generation planarization techniques. The More than Moore’s segment, targeting mixed-signal ICs and heterogeneous integration, is gaining traction, while the Emerging technology segment shows potential for future growth in innovative applications.
By application, the market includes Integrated Circuits, MEMS and NEMS, Compound Semiconductors, and Optics. Integrated circuits dominate due to their extensive use in electronics and advanced devices, while MEMS (Micro-Electro-Mechanical Systems) and NEMS are expanding rapidly with growing demand for precision devices in automotive and consumer electronics. Compound semiconductors and optics applications also present growth opportunities, particularly in telecommunications and photonics.
Segmentation:
By Type:
- CMP Consumable
- CMP Equipment
By Technology:
- Leading Edge
- More than Moore’s
- Emerging
By Application:
- Integrated Circuits
- MEMS and NEMS
- Compound Semiconductors
- Optics
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific holds the largest share of the global Chemical Mechanical Planarization (CMP) market, accounting for approximately 50-55% of the total market. This dominance is fueled by the region’s position as the global hub for semiconductor manufacturing, with China, South Korea, Taiwan, and Japan leading the way. Taiwan Semiconductor Manufacturing Company (TSMC), the largest semiconductor foundry globally, produces over 60% of the world's chips, further emphasizing the region’s reliance on advanced CMP techniques. Similarly, Samsung Electronics in South Korea continues to invest heavily in advanced fabrication facilities, including its recent $230 billion project for new semiconductor fabs. The Chinese semiconductor industry, bolstered by government initiatives like the Made in China 2025 plan, aims to increase domestic semiconductor production to reduce reliance on imports. Additionally, the rise in consumer electronics, driven by a 14% year-on-year growth in smartphone shipments and increasing adoption of 5G technologies, has amplified the demand for CMP solutions.
North America accounts for approximately 20-25% of the CMP market, supported by its leadership in technological innovation and strategic investments in semiconductor manufacturing. The United States has emerged as a critical player, driven by initiatives like the CHIPS and Science Act, which allocates over $52 billion to revitalize domestic semiconductor production. Companies like Intel are making significant strides, with plans to construct two advanced fabs in Arizona by 2025. Additionally, North America’s focus on high-end technologies, including artificial intelligence (AI), autonomous vehicles, and cloud computing, continues to boost the demand for advanced CMP processes to achieve higher precision and reliability in chips.
Europe holds a market share of around 15-18%, largely driven by advancements in automotive electronics and industrial automation. The European Union’s goal to increase its semiconductor production to 20% of the global market by 2030 under the European Chips Act is a significant driver of CMP demand. Germany, a leader in automotive manufacturing, has seen increasing investments in electric vehicles (EVs), which require advanced semiconductors for battery management and power systems. Additionally, ASML Holding, headquartered in the Netherlands, remains a global leader in photolithography technology, further strengthening Europe’s role in semiconductor innovation and CMP adoption.
Latin America and the Middle East & Africa (MEA) collectively contribute approximately 5-7% to the global CMP market. Brazil, the largest economy in Latin America, is witnessing significant growth in smart technology adoption, creating a rising demand for high-performance semiconductors. Mexico has emerged as a key player in electronics manufacturing, driven by its proximity to North America and trade partnerships like the USMCA agreement. In the MEA region, countries such as Saudi Arabia are investing in smart infrastructure under initiatives like Vision 2030, which emphasize the development of local semiconductor manufacturing capabilities. Similarly, South Africa’s increasing digital transformation efforts are boosting demand for advanced electronics, presenting opportunities for CMP market growth.
Key Player Analysis:
- Air Products and Chemicals, Inc.
- Applied Materials Inc.
- Cabot Microelectronics Corporation
- CMC Materials
- DOW Electronic Materials
- Ebara Corporation
- Fujimi Incorporation
- Hitachi Chemical Company, Ltd.
- LAM Research Corporation
- Lapmaster Wolters GmbH
- Okamoto Machine Tool Works, Ltd.
Competitive Analysis:
The Chemical Mechanical Planarization (CMP) market is characterized by intense competition, with key players focusing on innovation, product development, and strategic partnerships to strengthen their market position. Major companies such as Cabot Microelectronics (CMC Materials), Applied Materials, DuPont, Fujimi Corporation, and Hitachi Chemical dominate the market due to their advanced CMP consumables, equipment, and strong global presence. For instance, Strategic mergers and acquisitions, such as Entegris' acquisition of CMC Materials in 2022 for $6.5 billion, have further consolidated market leadership. These companies continuously invest in R&D to develop next-generation CMP slurries, pads, and conditioning tools that address the evolving needs of smaller node technologies and new materials, such as cobalt and ruthenium.Strategic mergers and acquisitions, such as Entegris' acquisition of CMC Materials in 2022, have further consolidated market leadership. Additionally, regional players in Asia-Pacific, including SKC and Mitsubishi Chemical Corporation, are gaining prominence by catering to the increasing demand for localized solutions. As the semiconductor industry advances, competition will intensify, driven by technological innovation, cost optimization, and sustainability-focused CMP solutions.
Recent Developments:
- In March 2024, Air Products awarded Worley an agreement to provide procurement, fabrication, and modularization services for its Net-Zero Hydrogen Energy Complex in Edmonton, Alberta, Canada.
- In December 2024, Applied Materials launched Vistara, their most significant wafer manufacturing platform innovation in over a decade, featuring enhanced flexibility, intelligence, and sustainability capabilities.
- In September 2024, Ebara Corporation announced the construction of a new equipment testing and development center in Futtsu City, Japan, with an investment of approximately 16 billion yen. The facility will focus on hydrogen infrastructure-related equipment testing and development.
- In April 2024, Hitachi Energy won an order from SP Energy Networks to deliver a power quality solution that will boost renewable energy flow from Scotland to England, enabling up to 280 MW of additional transfer capacity.
- In December 2024, Lam Research Corporation maintained their financial guidance for December 2024 quarter following new export regulations.
- In December 2024, Okamoto Machine Tool Works entered into a capital and business alliance agreement with Mitsui & Co., with Mitsui subscribing to shares amounting to 9.8 billion yen for a 30% ownership stake.
Market Concentration & Characteristics:
The Chemical Mechanical Planarization (CMP) market is moderately concentrated, with a few major players holding a significant share due to their technological expertise, strong global networks, and substantial investments in research and development (R&D). Leading companies such as Applied Materials, Entegris (CMC Materials), DuPont, and Fujimi Corporation dominate the market by offering highly specialized CMP consumables and equipment that cater to advanced semiconductor manufacturing processes. The market is characterized by a high degree of innovation, driven by the need to address the challenges of smaller node sizes (5nm, 3nm, and sub-3nm) and new materials like cobalt, ruthenium, and low-k dielectrics. Companies focus on precision, defect reduction, and process efficiency while developing eco-friendly solutions to comply with environmental regulations. The presence of regional players, particularly in Asia-Pacific, adds to market competitiveness as they offer localized and cost-effective CMP solutions to meet the growing semiconductor demand.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Technology and By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Chemical Mechanical Planarization (CMP) market will experience robust growth driven by the increasing adoption of 3nm and sub-3nm node technologies.
- Rising investments in semiconductor fabrication facilities (fabs), particularly in Asia-Pacific and North America, will create new opportunities for CMP solutions.
- Technological advancements in CMP slurries and pads will focus on improving material removal rates, precision, and minimizing surface defects.
- The growing adoption of 3D packaging and stacked memory architectures, such as 3D NAND flash, will significantly increase the demand for advanced CMP processes.
- New materials, including cobalt, ruthenium, and low-k dielectrics, will drive the development of specialized CMP consumables and tools.
- The market will witness a surge in demand from emerging technologies such as AI, IoT, high-performance computing, and autonomous vehicles.
- Increasing focus on sustainability will encourage the adoption of eco-friendly slurries and water-efficient CMP solutions to align with environmental regulations.
- Strategic collaborations, mergers, and acquisitions among key players will intensify, enhancing innovation and market competitiveness.
- Regional players in Asia-Pacific will expand their presence, offering localized, cost-effective solutions to meet the growing semiconductor demand.
- Government initiatives, such as the CHIPS Act and Europe’s semiconductor strategies, will drive the establishment of domestic fabs, boosting CMP market opportunities globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the CMP market?
What drives the growth of the CMP market?
Which region dominates the CMP market?
What are the challenges faced by the CMP market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Chemical Mechanical Planarization Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Chemical Mechanical Planarization Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,402.5 million → 2032: USD 8,291.14 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Chemical Mechanical Planarization Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Chemical Mechanical Planarization Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Chemical Mechanical Planarization Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Chemical Mechanical Planarization Market Drivers
- 3.3 Chemical Mechanical Planarization Market Restraints & Challenges
- 3.4 Chemical Mechanical Planarization Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Chemical Mechanical Planarization Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Chemical Mechanical Planarization Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Chemical Mechanical Planarization category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Chemical Mechanical Planarization Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Chemical Mechanical Planarization Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Chemical Mechanical Planarization. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Chemical Mechanical Planarization Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Chemical Mechanical Planarization Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Chemical Mechanical Planarization Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Chemical Mechanical Planarization (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Chemical Mechanical Planarization
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Chemical Mechanical Planarization Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Chemical Mechanical Planarization Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Chemical Mechanical Planarization Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Chemical Mechanical Planarization Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Chemical Mechanical Planarization Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Chemical Mechanical Planarization Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Chemical Mechanical Planarization Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Chemical Mechanical Planarization Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
