
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| China AI in Finance Market Size 2023 | USD 3,657 Million |
| China AI in Finance Market, CAGR | 30.6% |
| China AI in Finance Market Size 2032 | USD 40,367 Million |
Market Overview
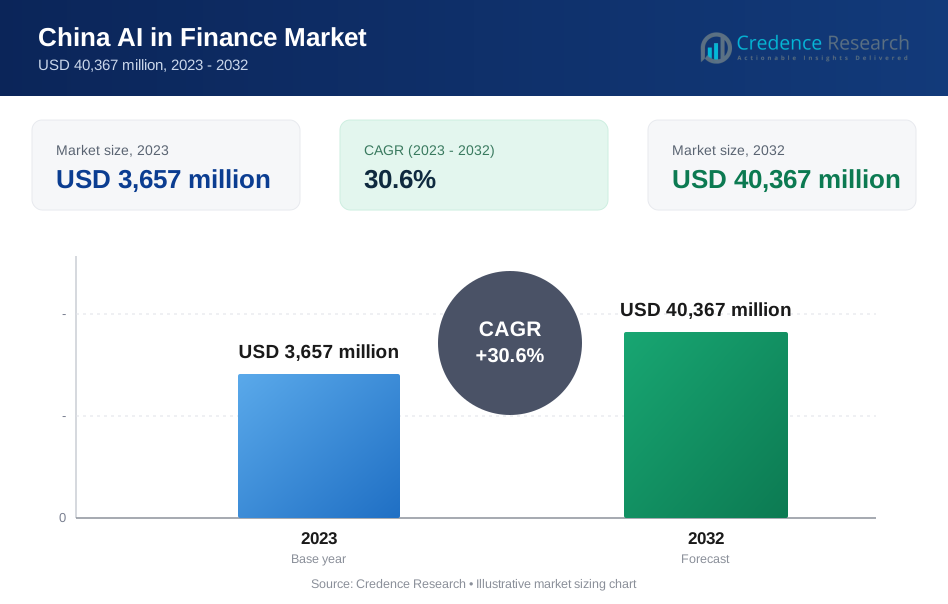
The China AI in Finance Market is projected to grow from USD 3,657 million in 2023 to an estimated USD 40,367 million by 2032, with a compound annual growth rate (CAGR) of 30.6% from 2024 to 2032. This rapid growth reflects the increasing adoption of artificial intelligence technologies across the finance sector in China, driven by the need for enhanced decision-making, cost efficiency, and operational optimization.
Key drivers of the market include the growing demand for AI-powered solutions such as robo-advisors, fraud detection systems, and predictive analytics in financial services. Additionally, advancements in machine learning, natural language processing, and big data analytics are enabling financial institutions to unlock valuable insights, reduce operational risks, and make data-driven decisions. The integration of AI in finance also aligns with China's national strategy to lead in artificial intelligence, fostering innovation and investment in the sector. Trends such as increased regulatory support and the rise of fintech startups are further contributing to the market's growth.
Geographically, China holds a dominant position in the Asia-Pacific region, with major cities like Beijing, Shanghai, and Shenzhen serving as key hubs for AI development and implementation in finance. The Chinese government's supportive policies and investments in AI research and development contribute to the nation's leadership in this market. Key players in the China AI in Finance Market include Baidu, Tencent, Alibaba Group, Ping An Technology, and Ant Financial, which are pioneering AI-driven financial solutions to meet the evolving needs of consumers and businesses.
Market Insights
- The China AI in Finance Market is projected to expand from USD 3,657 million in 2023 to USD 40,367 million by 2032, with a CAGR of 30.6%.
- Increasing demand for AI-powered solutions like robo-advisors, fraud detection, and predictive analytics is driving the market's growth in the financial sector.
- AI enhances decision-making, automates complex tasks, and improves customer experience, contributing to cost savings and higher operational efficiency for financial institutions.
- Government policies and investments in AI research and development are crucial drivers of the market, fostering AI integration in the finance sector.
- Data privacy concerns and the shortage of skilled AI professionals are significant challenges hindering the widespread adoption of AI in finance.
- Eastern China, with key cities like Beijing, Shanghai, and Shenzhen, dominates the market due to its strong financial infrastructure and tech-driven ecosystem.
- Major players such as Baidu, Tencent, Alibaba Group, Ping An Technology, and Ant Financial are leading the charge in AI innovation within China's financial services sector.
Market Drivers
Government Support and Strategic Investments in AI Technology
The Chinese government has been a strong advocate for artificial intelligence, establishing ambitious plans and policies to become a global leader in AI by 2030. This strategic focus has led to substantial investments in AI research and development, particularly in the finance sector. Programs such as "Made in China 2025" and the "Next Generation Artificial Intelligence Development Plan" have provided a conducive environment for the growth of AI technology, including in financial services. The government has recognized AI as a critical tool for transforming China's economy and enhancing the global competitiveness of Chinese companies, including those in the finance industry. Through various funding initiatives, partnerships, and regulatory frameworks, China’s government has created a thriving ecosystem for AI innovation, which is driving the adoption of AI-powered solutions across the financial services industry.For instance, the National Natural Science Foundation of China (NSFC) allocated 4.43 billion yuan in 2022 to support artificial intelligence research projects. This funding has significantly boosted AI development in sectors like finance, enabling advancements in areas such as customer risk assessment and investment management. Additionally, streamlined regulatory processes have allowed financial institutions to experiment with AI-driven solutions more freely, further accelerating innovation. The combination of strategic investments and regulatory flexibility remains a cornerstone of China's leadership in AI adoption.
Increasing Demand for Automation and Operational Efficiency in Financial Services
The rapid adoption of AI in China's finance market is largely driven by the pressing need for increased automation and operational efficiency. Financial institutions such as banks, insurance companies, and investment firms are increasingly seeking ways to streamline their operations and reduce human errors. AI technologies like machine learning and robotic process automation (RPA) enable organizations to automate repetitive tasks such as data entry, transaction processing, and customer service, resulting in faster workflows and improved accuracy.For instance, Ant Financial employs AI to automate insurance claims processing. Customers can file claims by simply taking a photo of the damage, which is then assessed by an AI system that processes the claim without requiring human intervention. This not only reduces processing time but also minimizes errors, highlighting how automation enhances operational efficiency. Moreover, AI allows institutions to optimize resource allocation by freeing up human staff for complex decision-making tasks. As digital transformation accelerates within China’s financial sector, these technologies are becoming indispensable for maintaining competitiveness. The ability of AI to perform an expanding range of tasks continues to reshape workflows across the industry, driving further demand for automation solutions that enhance both speed and cost-effectiveness.
Rising Demand for Personalized Financial Products and Services
Another key driver of the China AI in Finance Market is the growing demand for personalized financial products and services. As consumers become more tech-savvy, they expect higher levels of customization from financial institutions. To meet these expectations, organizations are increasingly turning to AI-powered tools that offer tailored solutions based on individual preferences. Robo-advisors are one such example; they provide personalized wealth management advice by analyzing financial goals, risk profiles, and preferences using machine learning algorithms.For instance, Lichen China Limited has launched an innovative solution called Lichen AI Robot 1.0. This software provides personalized financial and tax advice by generating tailored reports based on user inquiries. Such advancements demonstrate how financial institutions are leveraging AI to improve customer satisfaction and engagement through customized offerings. Additionally, technologies like chatbots and virtual assistants enhance customer service by providing 24/7 support while learning from interactions to deliver more accurate responses over time. As digital platforms grow rapidly alongside mobile banking adoption, consumers can now access personalized services anytime and anywhere. This trend reflects how AI is reshaping customer-centric strategies across China’s financial landscape, enabling institutions to meet evolving consumer demands effectively.
Advancements in Big Data Analytics and Machine Learning
The availability of vast amounts of financial data has been a significant driver of AI adoption in China's financial services industry. With the rise of digital banking, mobile payments, and e-commerce platforms, financial institutions now have access to unprecedented volumes of data on customer behavior, transaction history, market trends, and economic indicators. Advanced AI technologies such as machine learning (ML) and big data analytics enable these organizations to extract valuable insights from this data for better decision-making.For instance, WeBank leverages cloud computing and data analytics technology to build risk models that allow instant credit assessments and approvals. Customers can receive credit decisions within seconds—a process that was previously time-consuming—demonstrating how big data analytics enhances operational efficiency. Similarly, machine learning algorithms are being used to detect fraudulent activities by identifying unusual transaction patterns in real-time. These technologies also play a crucial role in predictive analytics by helping institutions anticipate market trends or optimize trading strategies. As the volume of financial data continues to grow exponentially, advancements in machine learning will further enable smarter decision-making processes while reducing risks across China’s finance market. This integration of big data analytics with AI is transforming how financial services operate at every level.
Market Trends
Expansion of AI-Powered Financial Products and Services
In China, the demand for AI-powered financial products and services is growing rapidly, as financial institutions seek to provide more personalized and tailored solutions to their customers. This trend is most visible in wealth management, where AI-driven robo-advisors are increasingly popular. These platforms utilize machine learning algorithms to offer personalized investment recommendations based on individual financial goals, risk tolerance, and market conditions. For instance, Lu International (Hong Kong) has launched an AI-powered robo-advisory platform named "Lucy," which provides individual asset allocation advice tailored to investors' financial profiles, such as their income, objectives, and risk appetites. With the increasing availability of financial data, these AI systems can continuously improve their recommendations and offer more accurate, real-time advice.Additionally, AI is playing a central role in developing other innovative financial services. Digital lending platforms in China are using AI to assess creditworthiness, enabling quicker and more accurate loan approvals. For example, Ping An Puhui’s “Xingyun” AI-powered smart loan solution has significantly reduced the average loan application time for small and micro customers. Traditional financial institutions and fintech startups are also leveraging AI to create new products like micro-investment opportunities and insurance policies that cater to younger, tech-savvy consumers. This trend aligns with the growing preference for personalized, on-demand financial services.
Increased Integration of AI in Risk Management and Fraud Detection
One of the most notable trends in China’s AI in finance market is the increased integration of artificial intelligence in risk management and fraud detection. Financial institutions are facing an ever-increasing volume of complex transactions, making traditional fraud detection methods insufficient. AI technologies, particularly machine learning algorithms, enable institutions to process large amounts of transactional data and detect anomalies in real time. For instance, the Industrial and Commercial Bank of China (ICBC) implemented a Credit Risk Monitoring System that incorporates AI alongside satellite remote sensing and big data technologies. This system has helped reduce the non-performing loan ratio by 22 basis points in 2023.Machine learning models can identify patterns in user behavior and flag suspicious activities such as unauthorized transactions or identity theft. These systems continuously learn from past fraudulent behaviors, improving their detection capabilities over time. Moreover, AI is increasingly used for credit risk management by analyzing a wide range of financial and non-financial data to assess borrower creditworthiness more accurately than traditional methods. As financial crimes evolve alongside the rapid growth of digital payments in China, integrating AI into risk management has become indispensable for maintaining the integrity of the financial system while enhancing customer trust in digital services.
Rise of AI-Driven Chatbots and Virtual Assistants for Customer Service
The adoption of AI-powered chatbots and virtual assistants is another key trend shaping China’s AI-driven finance market. As financial services become increasingly digitalized, customers expect instant, 24/7 support. Traditional call centers are being replaced or augmented with AI-driven solutions that can handle a growing volume of customer inquiries efficiently. These systems use natural language processing (NLP) to interact with customers via text or voice while answering questions or resolving issues. For instance, Bank of America’s virtual assistant “Erica” has successfully handled over 50 million client requests since its launch in 2018, showcasing how such tools can alleviate human workloads while offering seamless customer support. Financial institutions in China are integrating chatbots into their digital platforms to meet the demand for accessible and personalized customer service. These tools improve with each interaction by learning from user queries to provide more accurate responses over time. Additionally, they enable companies to manage higher inquiry volumes without requiring additional human resources. By improving efficiency and enhancing user experience through conversational interfaces, AI-driven chatbots have become indispensable for banks, insurance companies, and fintech firms alike. This shift toward automated customer service reflects a broader trend toward creating user-friendly digital experiences tailored to modern consumers’ expectations.
Regulatory Support and AI-Driven Compliance Solutions
China’s regulatory environment is increasingly supportive of artificial intelligence adoption in the financial sector as authorities aim to balance innovation with responsible technology deployment. This has paved the way for advanced regulatory technology (RegTech) solutions that automate compliance processes using machine learning and natural language processing (NLP). For instance, these systems can monitor transactions for anti-money laundering (AML) risks or flag potential violations in real time by analyzing vast amounts of data efficiently.AI-driven compliance solutions are helping financial institutions adhere to stringent regulations while improving operational accuracy. As regulatory frameworks evolve alongside technological advancements, these tools are expected to become even more sophisticated. Moreover, China’s regulatory bodies are working toward establishing ethical standards for AI adoption within the sector to ensure consumer protection and market stability.This trend reflects a growing recognition that while artificial intelligence will transform financial services significantly, its deployment must be carefully monitored to avoid misuse or unintended consequences. By leveraging these compliance solutions alongside government support for innovation-friendly policies, financial institutions can better navigate an evolving regulatory landscape while maintaining transparency and trust among stakeholders.
Market Challenges
Data Privacy and Security Concerns
One of the primary challenges facing the AI in Finance Market in China is the issue of data privacy and security. Financial institutions are required to handle vast amounts of sensitive customer data, including financial transactions, personal identification details, and account histories. The integration of AI technologies into these processes introduces risks related to data breaches, unauthorized access, and misuse of personal information. While AI-driven systems, such as fraud detection and credit scoring tools, rely heavily on large datasets to function effectively, ensuring the privacy and security of this data is a significant concern. The Chinese government has implemented various regulations, such as the Personal Information Protection Law (PIPL), to protect citizens’ data, but financial institutions face difficulties in ensuring full compliance while utilizing AI technologies. Additionally, as the complexity of AI models grows, so does the potential for data vulnerabilities. Financial firms need to adopt robust cybersecurity measures and invest in data encryption and anonymization techniques to mitigate these risks. Balancing AI's potential with stringent data protection regulations remains an ongoing challenge that could affect market adoption and consumer trust in AI-driven financial solutions.
Talent Shortage and Skill Gaps in AI and Finance Integration
Another key challenge in the China AI in Finance Market is the shortage of skilled professionals capable of integrating AI technologies effectively into financial systems. While China is a leader in AI research and development, the demand for talent in AI and machine learning far outpaces supply, particularly within the financial sector. Financial institutions need professionals who possess both deep expertise in AI technologies and a strong understanding of the financial services industry. The skill gap creates obstacles in developing, deploying, and maintaining AI-driven financial solutions. The difficulty in finding qualified AI talent hampers the rapid adoption of innovative AI solutions, as firms are forced to either delay projects or rely on external providers for technology integration. This shortage also affects the ability of financial institutions to scale AI initiatives, hindering overall market growth. To address this challenge, financial organizations are increasingly turning to training programs and collaborations with academic institutions to build a pipeline of skilled professionals. However, the need for specialized talent continues to present a significant barrier to the full realization of AI's potential in China’s financial sector.
Market Opportunities
Expansion of Fintech and Digital Banking
The rapid growth of fintech and digital banking in China presents a significant opportunity for AI integration within the financial sector. As more consumers adopt online and mobile banking solutions, financial institutions are increasingly turning to AI technologies to enhance user experience and streamline operations. AI applications such as intelligent chatbots, personalized financial advice through robo-advisors, and automated loan approval systems are gaining traction. The growing demand for digital-first, customer-centric financial services creates opportunities for AI companies to collaborate with banks, insurance companies, and fintech startups to develop cutting-edge solutions. This trend is expected to accelerate as China continues to push for digital financial inclusion and modernization, offering a fertile ground for AI-driven innovations in the financial services industry.
AI-Driven Risk Management and Compliance Solutions
As financial institutions face increasingly complex regulatory environments and higher risks of fraud, the demand for AI-driven risk management and compliance solutions is growing. AI technologies, such as machine learning and predictive analytics, can help financial institutions detect fraud in real-time, optimize credit risk assessments, and ensure compliance with evolving regulatory standards. Given China's focus on improving financial security and compliance with international regulations, there is a significant market opportunity for AI companies that specialize in regulatory technology (RegTech). These AI solutions can streamline compliance processes, reduce operational costs, and enhance overall efficiency, positioning AI as a critical tool in the management of financial risks and regulatory adherence.
Market Segmentation Analysis
By Component
The market is primarily divided into solutions and services. Solutions dominate the market, as financial institutions heavily invest in AI software and tools to streamline operations and enhance decision-making capabilities. These solutions include AI-powered fraud detection systems, robo-advisors, and AI-driven risk management tools. On the other hand, the services segment, which includes consulting, integration, and support services, is witnessing steady growth. Financial institutions require specialized services for the deployment and maintenance of AI systems, driving demand for services such as AI consulting and system integration.
By Deployment Mode
The cloud deployment mode is gaining significant traction due to its scalability, flexibility, and cost-efficiency. Cloud-based AI solutions enable financial institutions to access advanced technologies without the need for significant upfront capital expenditure on infrastructure. The on-premise deployment mode, however, still holds importance for organizations with stringent data privacy and security concerns. The adoption of cloud-based AI is expected to grow rapidly in the coming years as more financial institutions move towards digital transformation.
Segments
Based on component
- Solution
- Services
Based on deployment mode
- On-premise
- Cloud
Based on technology
- Generative AI
- Other AI Technologies
Based on Application
- Virtual Assistant (Chatbots)
- Business Analytics and Reporting
- Fraud Detection
- Quantitative and Asset Management
- Others
Based on region
- Eastern China
- Northern China
- Southern China
Regional Analysis
Eastern China (45%)
Eastern China holds the largest market share in the AI in Finance sector, accounting for approximately 45% of the total market. This region is home to major financial centers such as Beijing, Shanghai, and Shenzhen, which are known for their robust financial infrastructure and high adoption of AI technologies. Shanghai, a global financial hub, serves as a key driver of AI integration in the financial services industry. These cities are home to numerous financial institutions, fintech startups, and AI research and development centers, which fosters a high level of collaboration between financial services and technology firms. The Chinese government's strong focus on AI development, coupled with the significant investments in smart city initiatives and digital finance, further propels growth in this region. Eastern China’s high-tech infrastructure and advanced digital services ecosystem contribute to its dominance in AI adoption in finance.
Northern China (25%)
Northern China, with key cities like Beijing and Tianjin, contributes around 25% to the overall market. Beijing, as the political and technological capital of China, is a major player in AI adoption within the finance sector. The city has a high concentration of tech companies and fintech ventures that are leveraging AI to improve financial offerings such as digital lending, risk management, and customer engagement solutions. Additionally, the government’s initiatives to build an AI-driven economy have helped spur the growth of AI-powered financial products and services in this region. The continued collaboration between universities, research institutions, and financial firms further accelerates innovation in AI technologies.
Key players
- Google LLC
- Microsoft Corporation
- IBM Corporation
- SAP SE
- Intel Corporation
- AWS (Amazon Web Services)
- FIS
- HPE (Hewlett Packard Enterprise)
- Oracle Corporation
- NVIDIA
- Zoho
Competitive Analysis
The AI in Finance Market is highly competitive, with several prominent players dominating the landscape. Google LLC and Microsoft Corporation lead the charge in terms of technological advancements and market share, offering robust AI-powered solutions for fraud detection, risk management, and customer service. IBM Corporation and SAP SE are also significant players, leveraging their deep expertise in enterprise solutions to provide AI-driven tools tailored to the finance sector. AWS, with its cloud infrastructure, offers scalability and flexibility for AI deployment, while Intel Corporation provides the hardware infrastructure necessary for high-performance AI processing. FIS, HPE, and Oracle are key contributors to AI solutions in financial services, focusing on innovation in financial management, analytics, and compliance. NVIDIA, with its GPUs, powers many AI applications, while Zoho offers AI solutions that enhance customer engagement and business analytics. The competitive environment is marked by continuous innovation, strategic partnerships, and an emphasis on providing tailored solutions to meet the specific needs of financial institutions.
Recent Developments
- In late 2024, Google announced the integration of its AI tools into financial applications in China, emphasizing risk management and fraud detection. Its TensorFlow platform is being increasingly adopted by Chinese fintech firms for building predictive models to enhance credit scoring and fraud prevention. Additionally, Google’s AI-powered cloud services are being utilized by financial institutions in China to optimize operational efficiency and customer engagement strategies.
- In January 2025, Microsoft added DeepSeek, a cost-efficient Chinese AI model, to its Azure offerings, aiming to strengthen its position in the Chinese market. Despite a slight dip in Azure's fiscal second-quarter revenue, Microsoft reported that its AI revenue run rate hit $13 billion in late 2024. The company is also working on improving algorithmic efficiency to reduce costs while enhancing performance for financial applications like credit scoring and portfolio optimization.
- In January 2025, SAP’s CFO described DeepSeek’s low-cost AI innovation as beneficial for creating tailored products for Chinese customers. SAP reported that half of its Q4 2024 deals were driven by AI applications, including tools for real-time decision-making and personalized customer experiences in finance.
- In January 2025, Intel expanded its presence in the AI-driven finance market by launching the Intel Core Ultra 200V series, designed to accelerate computing tasks for financial applications such as algorithmic trading and fraud detection. Intel also reported strong growth in its AI PC and edge computing segments, which are being adopted by Chinese banks for real-time data analysis.
- In early 2024, AWS introduced microsecond-accurate hardware clock support for high-frequency trading applications and expanded its infrastructure in China to support generative AI workloads. AWS also provided access to advanced AI models like Anthropic's Claude to Chinese financial institutions for tasks such as credit risk assessment and customer service automation.
- In Q3 2024, HPE reported significant growth due to strong demand for its AI infrastructure solutions. Its edge-to-cloud strategy has enabled Chinese financial institutions to process data at the edge, reducing latency in applications like fraud detection and risk analysis. HPE’s investments in scalable AI systems have positioned it as a key player in supporting China's rapidly growing fintech sector.
- In December 2024, Oracle launched new features that allow Chinese banks to use generative AI for predictive analytics and personalized customer interactions. These tools are aimed at improving operational efficiency while enhancing customer satisfaction.
- In early 2024, NVIDIA published a report highlighting the adoption of generative AI models for portfolio optimization and risk management by over 70% of surveyed financial institutions globally, including those in China. NVIDIA’s GPUs are widely used in high-frequency trading platforms across the country.
- In late 2024, Zoho introduced an update to its finance suite that integrates machine learning capabilities for automating accounting tasks and generating real-time business insights, catering to the needs of China's growing fintech startups.
Market Concentration and Characteristics
The China AI in Finance Market exhibits a moderate to high level of concentration, with several dominant players leading the development and deployment of AI technologies across the financial sector. Large multinational corporations such as Google LLC, Microsoft, IBM, and AWS are significant contributors to the market, offering advanced AI solutions tailored for fraud detection, risk management, customer service, and data analytics. However, domestic companies like Alibaba, Tencent, and Ping An are also playing pivotal roles, driving innovation through AI-powered platforms, fintech applications, and financial management tools. The market is characterized by rapid technological advancements, strong government support for AI integration, and increasing investments in AI research and development. Additionally, the growing number of fintech startups and collaborative efforts between financial institutions and technology providers reflect a dynamic and competitive landscape. The market is also witnessing a shift toward cloud-based AI solutions due to their scalability and cost efficiency, further contributing to its evolving characteristics.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Mode, Technology, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- AI adoption in China's finance sector is expected to accelerate, driven by digital transformation initiatives across financial institutions. This trend will foster innovation in services like wealth management, lending, and fraud detection.
- Fintech companies will increasingly integrate AI technologies to enhance customer experience, offering AI-driven solutions like robo-advisors and personalized investment tools. This will promote financial inclusion and accessibility.
- Cloud-based AI solutions will dominate as more financial institutions migrate to the cloud for greater scalability and cost-efficiency. This will drive AI adoption across smaller financial entities and fintech startups.
- Financial institutions will rely more on AI for big data analytics, enabling better decision-making, predictive insights, and risk assessments. This shift will enhance strategic planning and operational efficiency.
- As AI technology continues to evolve, regulatory frameworks will become more robust to ensure consumer protection, privacy, and financial stability. AI solutions will be developed in compliance with these regulations.
- The demand for AI-powered risk management solutions will rise, especially in areas such as fraud detection, credit scoring, and regulatory compliance. This will help mitigate risks in real-time and improve financial security.
- Machine learning models will become more sophisticated, enabling deeper insights into customer behavior and market trends. This will lead to more precise financial services and predictive models for investments.
- Strategic partnerships between financial institutions, AI developers, and fintech startups will increase, accelerating the development and deployment of cutting-edge AI technologies in the financial sector.
- China will continue to increase its investment in AI research and development, positioning the country as a global leader in AI innovation. This will foster breakthroughs in areas such as AI-powered financial products and automated decision-making.
- AI technologies will increasingly be used to offer personalized financial services, with financial institutions delivering tailored products and services based on customers' individual needs and financial behavior. This will lead to improved customer satisfaction and loyalty.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the China AI in Finance Market in 2023 and 2032?
What are the key drivers of the China AI in Finance Market?
How does AI improve operational efficiency in the finance sector?
Which regions in China are leading in AI adoption within finance?
Who are the key players in the China AI in Finance Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 China AI in Finance Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global China AI in Finance Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 3,657 million → 2032: USD 40,367 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 China AI in Finance Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. China AI in Finance Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 China AI in Finance Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 China AI in Finance Market Drivers
- 3.3 China AI in Finance Market Restraints & Challenges
- 3.4 China AI in Finance Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 China AI in Finance Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 China AI in Finance Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, China AI in Finance category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 China AI in Finance Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. China AI in Finance Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the China AI in Finance market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 China AI in Finance Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 China AI in Finance Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 China AI in Finance Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in China AI in Finance (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New China AI in Finance Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global China AI in Finance Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America China AI in Finance Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe China AI in Finance Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific China AI in Finance Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America China AI in Finance Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East China AI in Finance Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa China AI in Finance Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. China AI in Finance Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
