
Excess weight and online stores widen plus-size demand
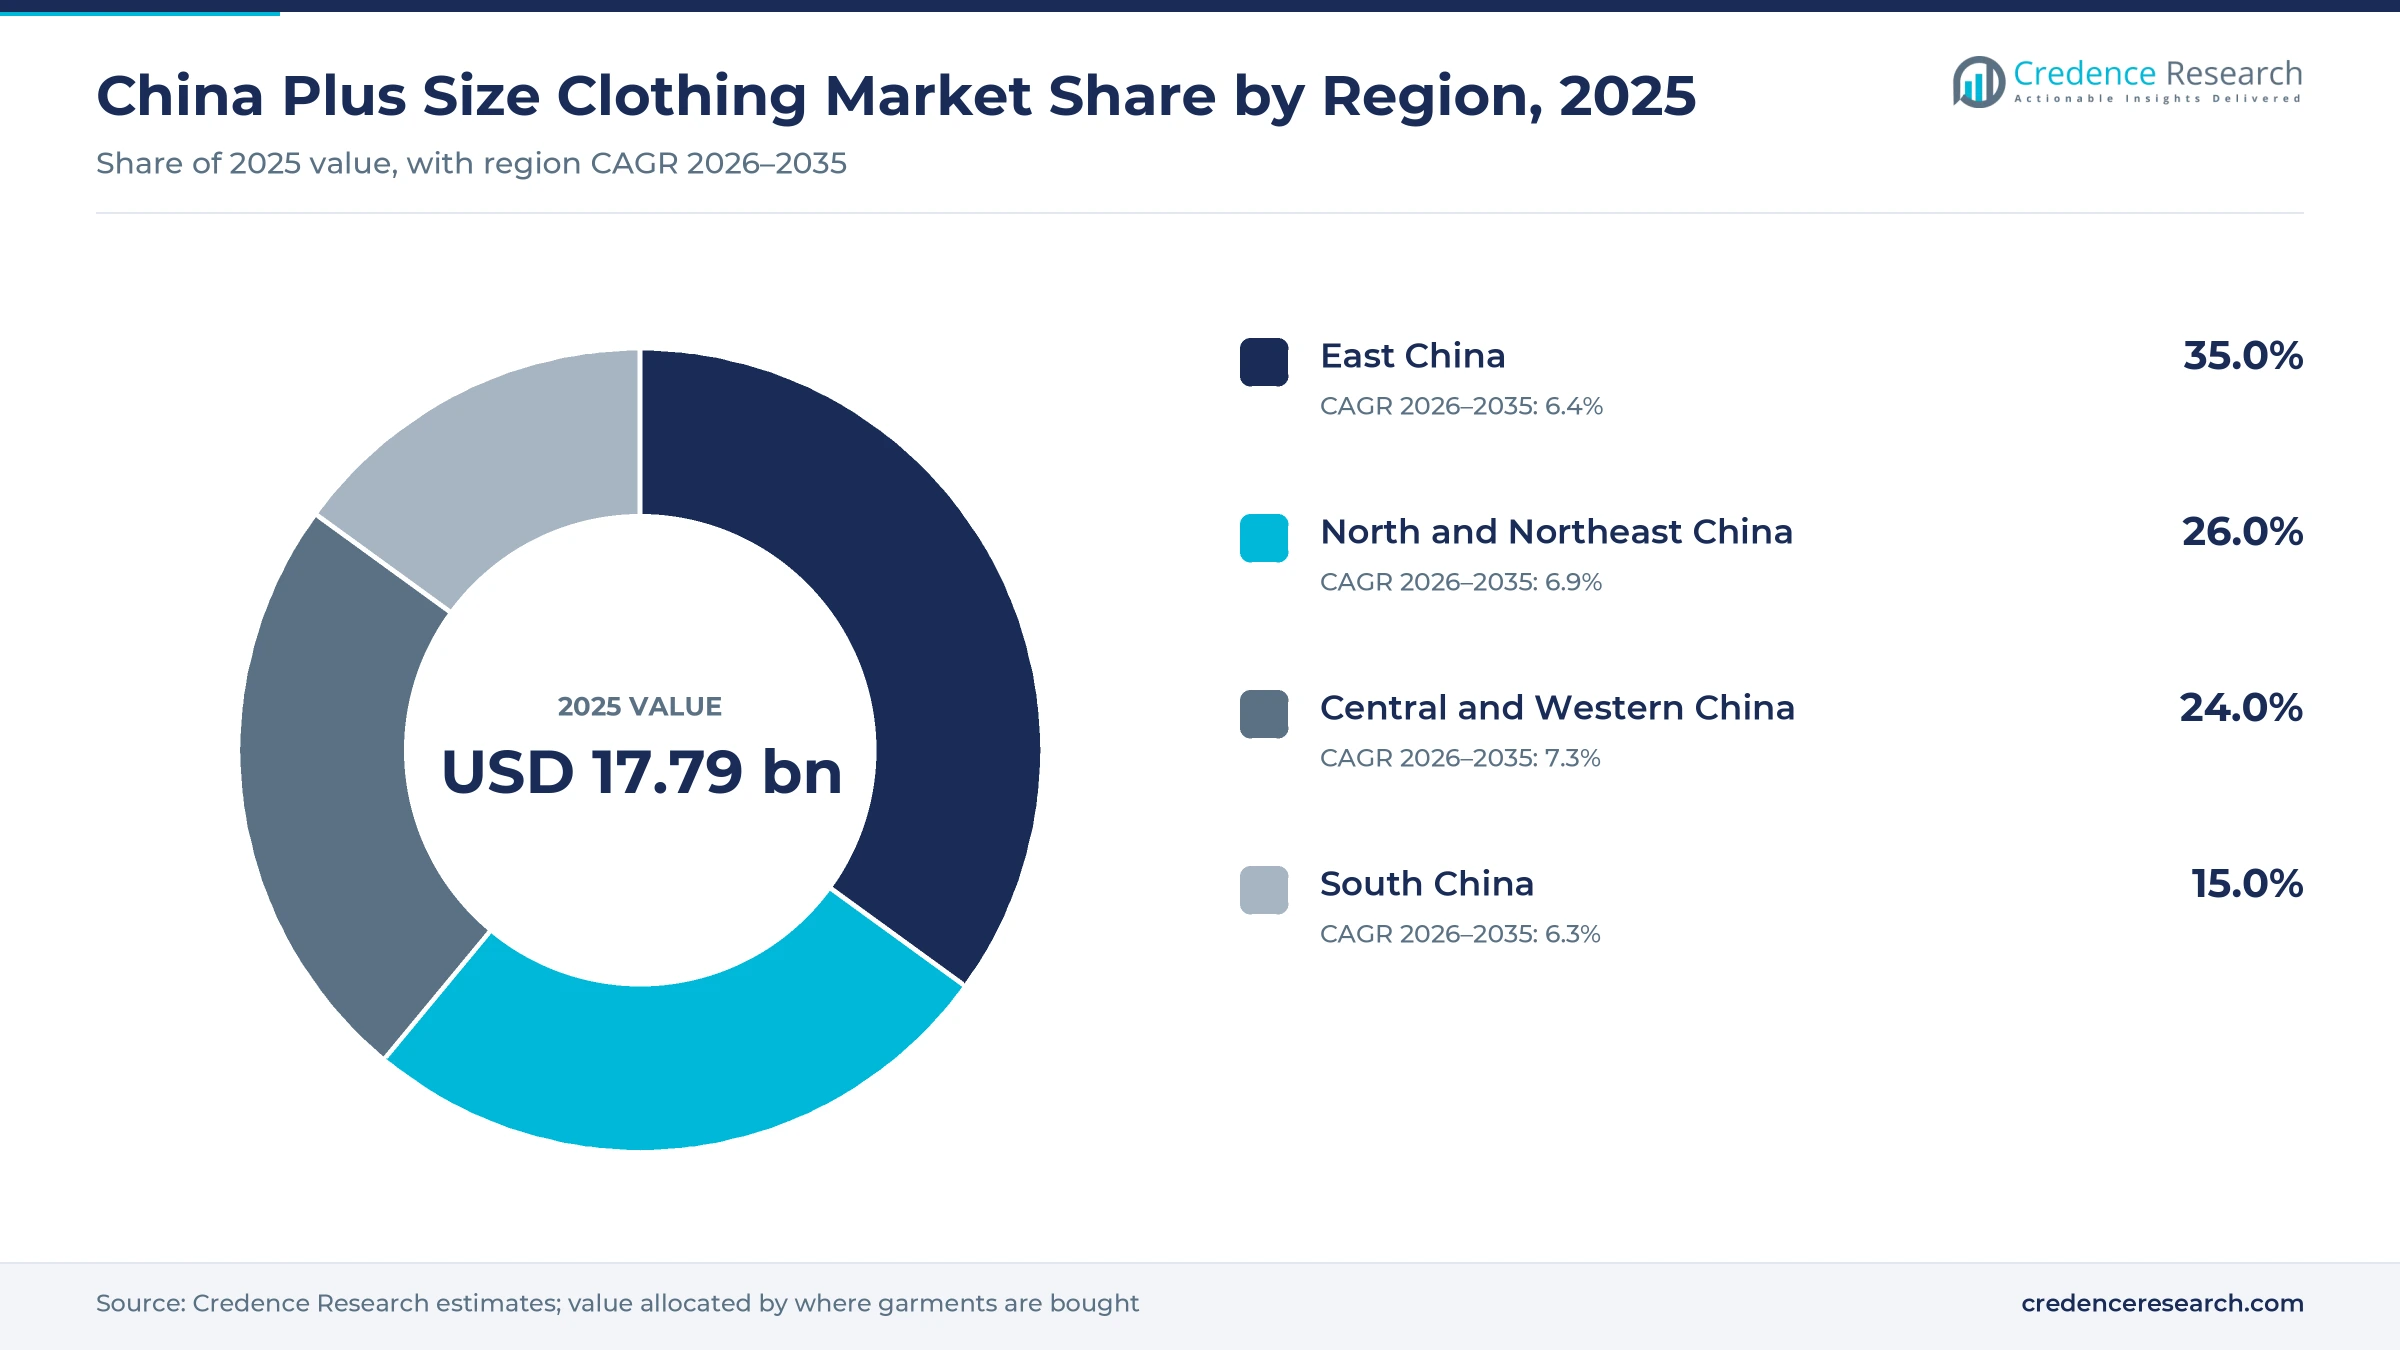
The China plus size clothing market was valued at USD 17.79 billion in 2025 and is projected to increase from USD 18.98 billion in 2026 to USD 34.12 billion by 2035, registering a CAGR of 6.73% during 2026–2035. Demand comes from the roughly half of Chinese adults who are overweight or obese, a group that increasingly needs sizes above a standard L, and most of them buy casual tops, dresses, trousers and innerwear through Taobao, Tmall, Douyin and Kuaishou stores rather than in malls. East China held the largest regional share, 35.0% in 2025, because Shanghai, Jiangsu, Zhejiang and Shandong combine high incomes with dense livestream seller networks. Central and Western China is the fastest-growing region at 7.3% a year, as rural and inland incomes rise faster than coastal ones. The approval of semaglutide for weight management in June 2024, followed by the patent expiry in March 2026, adds a new variable, since cheaper weight-loss drugs could move some buyers back into standard sizes.
Online labels and extended size runs make up the count
The market counts retail spending in mainland China on garments made for larger bodies, which covers dedicated plus-size labels and the extended sizes, usually Chinese XL to 6XL and above, that mainstream brands sell. It covers casual wear, sportswear, innerwear, formal wear and ethnic wear for women, men and children, sold through online stores, livestream channels, department stores and brand outlets.
Footwear, accessories, medical compression garments and exports by Chinese plus-size factories are excluded. The National Bureau of Statistics recorded RMB 1,521.5 billion of retail sales of clothes, shoes, hats and textiles by larger enterprises in 2025, a total that also includes footwear and standard sizes. Value moves from garment clusters and wholesale markets through online specialists, livestream hosts and brand retailers to consumers.
China Plus Size Clothing Market Insights
- The China plus size clothing market rises from USD 17.79 billion in 2025 to USD 34.12 billion by 2035, a 6.73% CAGR during 2026–2035, as online sellers extend size runs for heavier adults.
- East China held 35.0% of 2025 value, because high-income coastal provinces and Shandong, one of the highest-obesity provinces, concentrate buyers and livestream sellers.
- Casual held 46.0% of 2025 value, since livestream catalogs are built around low-priced dresses, tops and trousers in sizes up to 6XL.
- China's National Health Commission and 15 other bodies launched a three-year weight management campaign in June 2024, which shifts demand toward plus-size sportswear.
- Semaglutide lost patent protection in China on March 20, 2026, and cheaper weight-loss drugs are the main downside risk to extended-size demand.
Everyday casual wear and online sales hold most value
Casual wear leads while sportswear grows fastest
Based on type, the market is categorized into casual, sportswear, inner wear, formal and ethnic wear. Casual led with 46.0% of 2025 value because everyday dresses, tops and trousers dominate the catalogs of livestream sellers, which must release at least 20 new styles a day to hold viewers, Sixth Tone reported in October 2021. Sportswear grows fastest at 8.0% a year, because the national weight management campaign described in the trends section pushes larger adults into exercise programs that need training wear in 4XL and above.
Women lead while men grow fastest
Based on gender, the market is categorized into women, men and children. Women led with 53.5% of 2025 value because supply grew first around women's fashion, and the body-positive campaigns described in the drivers section were built around women's lingerie and fashion. Men grow fastest at 7.2% a year, as the study of 15.8 million adults cited in the drivers section found 41.1% of men overweight against 27.7% of women, yet few labels design big-and-tall ranges for Chinese men.
Mass pricing leads while premium labels grow faster
Based on pricing, the market is categorized into mass, premium and luxury. Mass led with 68.0% of 2025 value because livestream channels sell tops at 29 or 39 yuan and set a low price floor for the whole category. Premium grows fastest at 7.5% a year, as labels with better fabric and pattern work command higher baskets, and Taobao brand Garden Lis reported an average order of about 500 yuan within a year of its 2018 launch, Alizila noted.
Online sales lead and keep the faster pace
Based on distribution channel, the market is categorized into online sales channel and offline sales channel. Online Sales Channel led with 61.0% of 2025 value because online search lets shoppers filter by weight and size, which store floors with short size runs cannot match, and online sales of physical goods grew 5.2% in 2025, the National Bureau of Statistics said. Online Sales Channel also grows fastest at 7.2% a year, because weight-based size filters and livestream fit demonstrations work only online, and Douyin's growing share of festival apparel sales noted in the trends section widens that reach.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Casual | 46.0% | Sportswear | 8.0% |
| By Gender | Women | 53.5% | Men | 7.2% |
| By Pricing | Mass | 68.0% | Premium | 7.5% |
| By Distribution Channel | Online Sales Channel | 61.0% | Online Sales Channel | 7.2% |
Livestream prices set the floor for plus-size garments
Plus-size clothing in China is priced per item, and livestream channels set a low floor that store brands must justify against. Livestream sellers buy dresses from wholesale markets for under 50 yuan and sell them for about 60 yuan, while the same items sell for more than 300 yuan in other stores, Sixth Tone found. Fabric weight, pattern grading for larger sizes and return costs move the price, since a 6XL garment uses more cloth and needs separate fit work. Labels that cut returns through better grading keep more of the price gap.
| Offer or channel | Typical price or fee | Basis |
|---|---|---|
| Livestream summer dress, mass tier | About 30 to 60 yuan per item | Sixth Tone, October 2021 |
| Premium online plus-size label | About 500 yuan per order | Alizila, May 2019 (Garden Lis) |
| Branded store extended-size garment | 300 to 900 yuan per item | Credence Research estimate from brand price lists |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Body weight, income and online assortment lift demand
Half of Chinese adults now carry excess weight
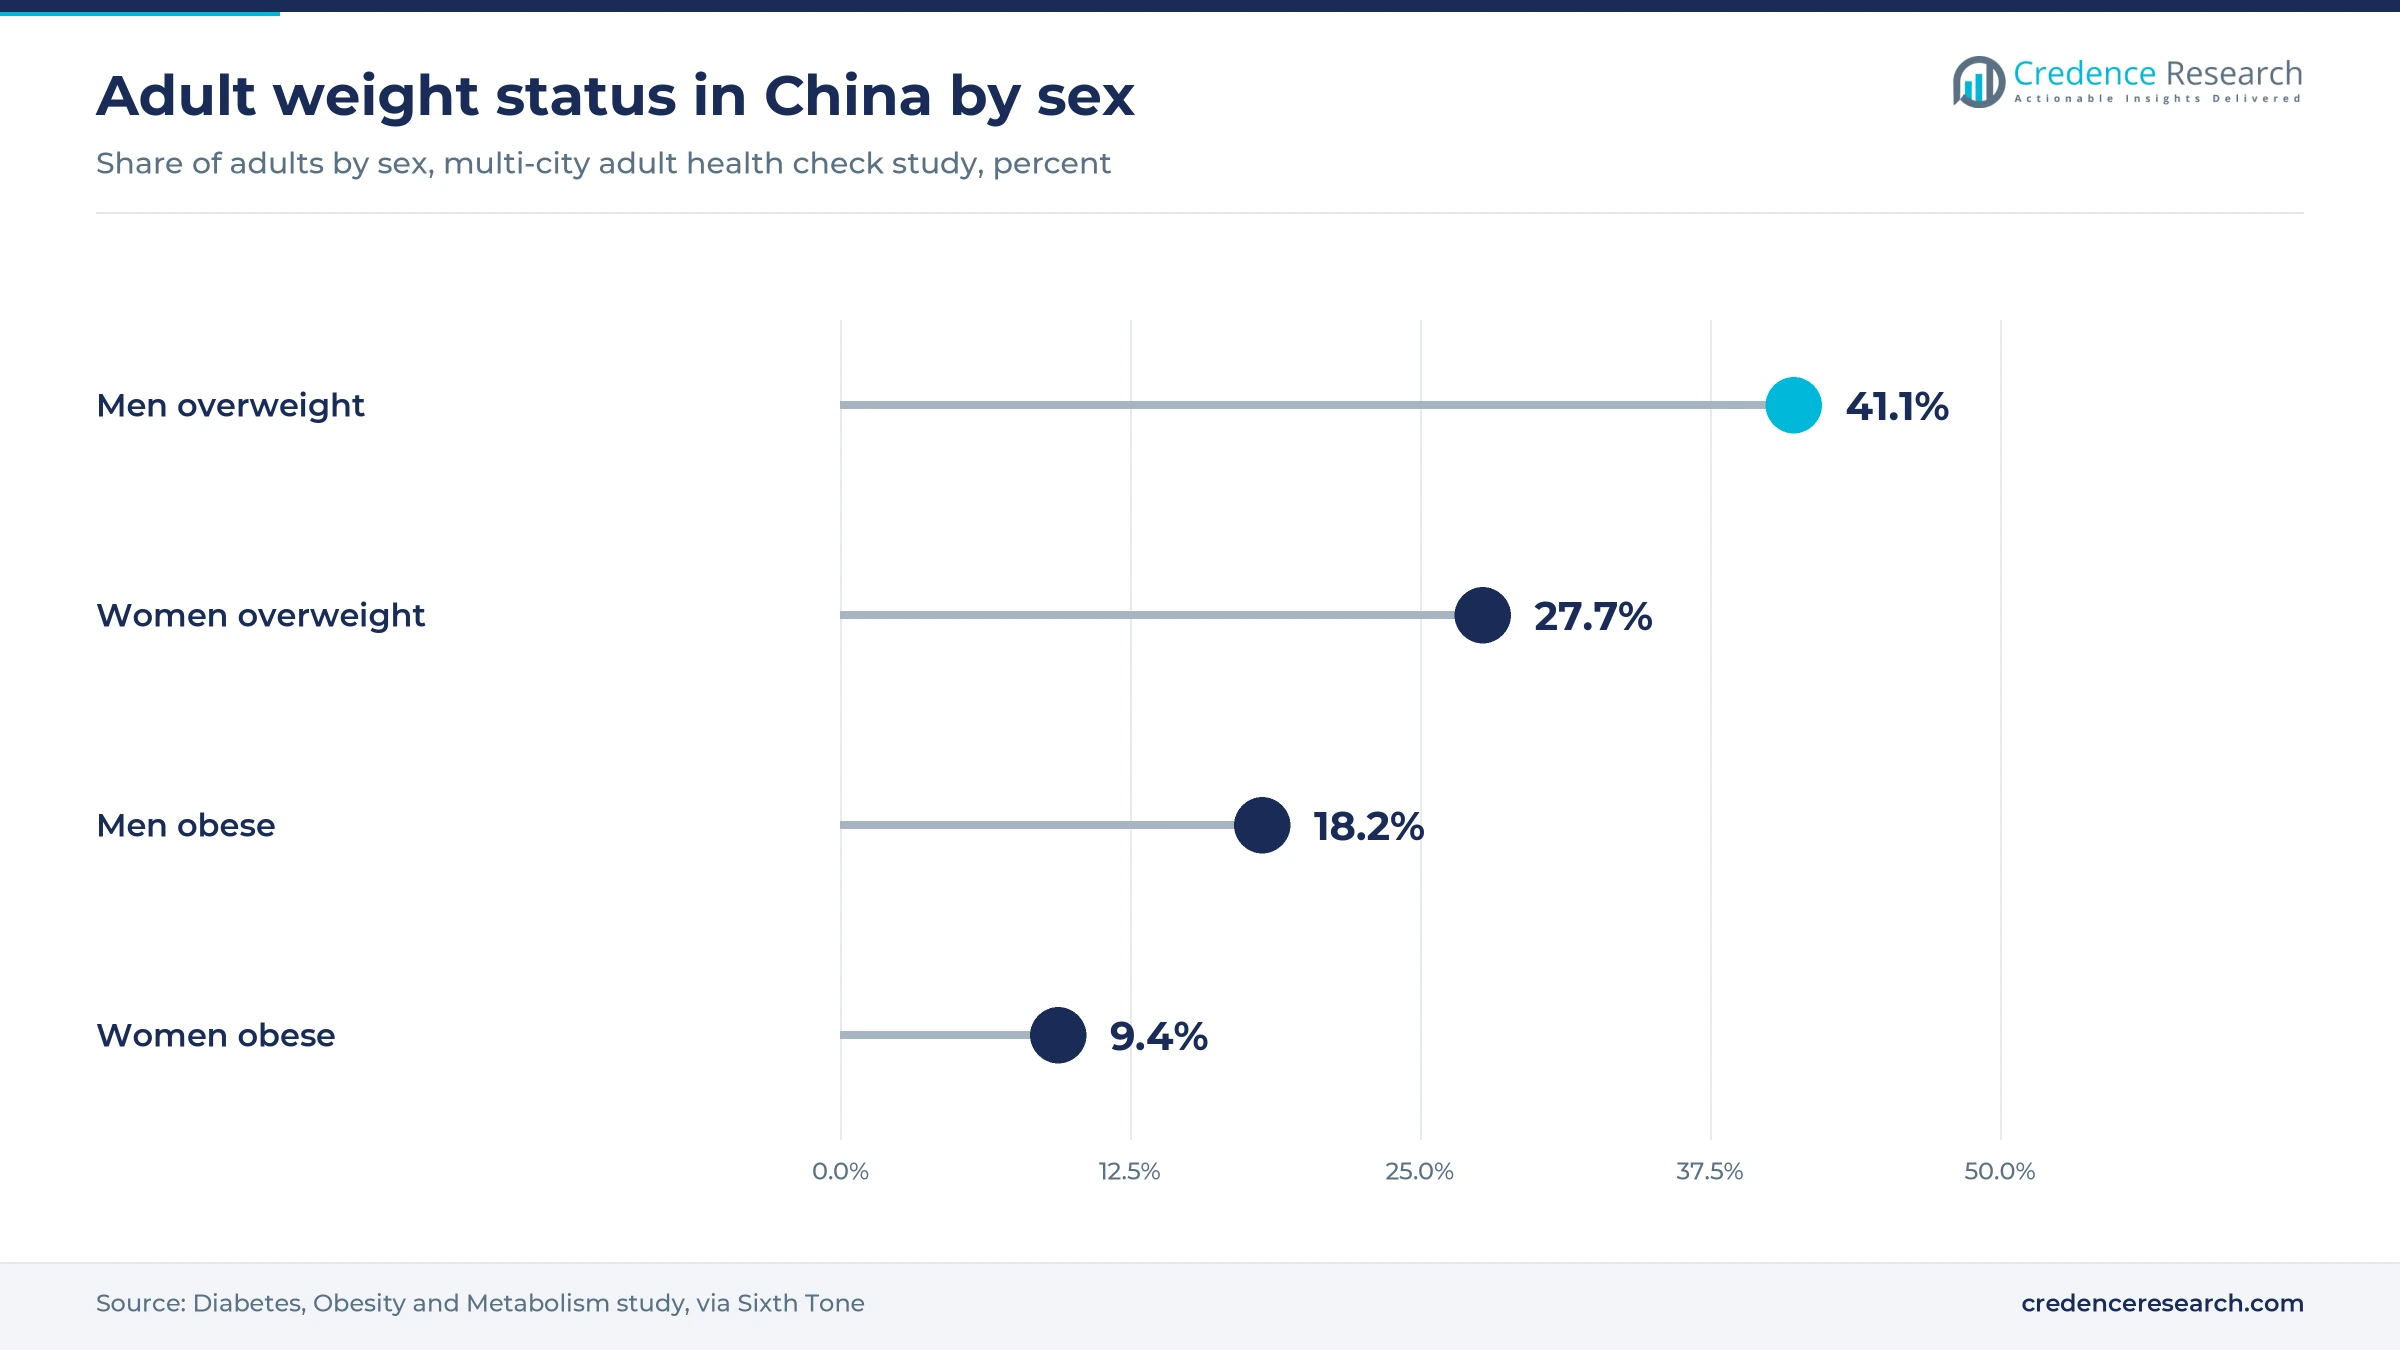
The overweight population sets the size of the addressable market, because every adult who moves beyond a standard L size needs a new wardrobe rather than a replacement item. The National Health Commission reported in December 2020 that 34.3% of adults were overweight and 16.4% obese, Sixth Tone reported, and about 20% of children aged 6 to 17 were overweight or obese. A later study of about 15.8 million adults found men at 41.1% overweight against 27.7% for women. Because these rates rose over two decades, demand for extended sizes builds steadily rather than in seasonal spikes. Brands that hold size runs beyond 4XL gain the most from this base, and men are the fastest-growing gender segment.
Rising incomes let larger shoppers trade up
Income growth supports spending on better-fitting garments, because plus-size buyers who once accepted whatever fit now pay for fabric, cut and style. Per capita disposable income reached 43,377 yuan in 2025, up 5.0%, according to the National Bureau of Statistics. Rural income rose faster, by 5.8% to 24,456 yuan, which widens demand in lower-tier towns where specialist stores are rare. Urban income reached 56,502 yuan, which keeps coastal cities the main base for premium plus-size labels, even though the mass tier holds 68.0% of value. Online specialists that ship to rural counties and carry sizes above 4XL gain most from the faster rural income growth, because few specialist stores operate in those towns.
Online marketplaces widen the plus-size assortment
Online marketplaces solve the assortment problem that kept plus-size shoppers out of malls, because a seller can list sizes up to 6XL without holding them in every store. Online retail sales of physical goods reached 26.1% of all consumer goods sales in 2025, the National Bureau of Statistics said. More than 410,000 Taobao stores now describe themselves as plus-size friendly, digital agency iClick noted, so shoppers can compare far more cuts online than in any mall. Wide online ranges give shoppers more choice than any mall, and they push store retailers to extend their own size runs online first.
Body-positive campaigns bring larger models to fashion
Body-positive campaigns are changing what larger shoppers expect, because brands now show their products on bodies like their customers. The hashtag translated as reject body anxiety appears in nearly 200,000 Xiaohongshu posts, FashionUnited reported in December 2024. Victoria's Secret named plus-size influencer Yang Tianzhen, who runs the PlusMall label, as a partner for a May 2021 campaign in China, Women's Wear Daily reported. Neiwai launched the second installment of its No Body Is Nobody project in March 2021. Kuaishou plus-size host Panpan, who weighs 110 kg, built about 360,000 followers by modeling clothes on her own body, Sixth Tone reported in October 2021. Women, who held 53.5% of 2025 value, respond first, so mainstream lingerie and fashion brands gain new buyers when their campaigns match these expectations.
Livestream sellers and body scan sizing reshape supply
Livestream sellers shift supply toward wholesale clusters
Plus-size retail is shifting toward livestream sellers that source daily from wholesale clusters, because hosts can show fit on a larger body and answer size questions in real time. At Xiliu Market in Haicheng, Liaoning, the number of plus-size vendors rose from about 30 in 2016 to 600 to 700 by 2021, Sixth Tone reported, and sellers there serve customers up to 125 kg, a range few mall brands stock. Douyin also took 26% of first-phase Double 11 apparel volume in 2025, Jing Daily reported, which shows short-video selling now rivals the older marketplaces. Factories near these clusters gain repeat orders, while store chains face sharper price comparison.
Body scan data is reshaping Chinese size charts
Brands are shifting toward size charts built from current body scans, because charts drawn from older measurements leave heavier shoppers between sizes. Humanetics published its SizeWorld China survey in November 2024, with 9,023 people scanned at 15 locations in six regions, and found the population taller, broader and heavier. Ubras, whose one-size bras topped Tmall Singles Day lingerie sales in 2020, shows how stretch designs cut fit risk. Neiwai's Barely Zero collection, tagged your size is the size, fits up to a D-plus cup, Women's Wear Daily reported in September 2021. Pattern makers and lingerie brands that work from current scan data gain lower return rates.
Premium ranges above 70 kg remain an open niche
Women above about 70 kg remain an open niche for premium brands, because most mid-priced labels stop their ranges below that weight. Most items from Neiwai and An Action A Day only cater to women up to 70 kg, FashionUnited reported in December 2024. Guangzhou label Yue Design sells high-end plus-size clothing to fill that gap, FashionUnited reported. Vogue China featured plus-size model Chelsea Zhou in its June 2024 edition, which signals that fashion media now accept larger bodies. Labels that move first can price above the mass tier, because these shoppers have few alternatives today. Premium labels that extend women's apparel fabric quality into sizes above 4XL can win the Premium tier.
Weight programs open demand for larger sportswear
The national weight campaign opens demand for training wear in larger sizes, because people who start exercise programs need sportswear that fits their current body. The National Health Commission and 15 other departments launched a three-year weight management campaign in June 2024, the State Council said. The campaign covers schools, workplaces and communities, so demand for larger training wear reaches children, office workers and older adults across the country. Sportswear is the fastest-growing type in the Credence Research model, and activewear brands that add 4XL and 5XL fits can capture this group. The child overweight rate noted above also makes school programs a large part of this demand.
Weight-loss drugs, returns and soft spending weigh
Cheaper weight-loss drugs could shrink size demand
GLP-1 weight-loss drugs could move some buyers back into standard sizes, which cuts demand for extended ranges. Semaglutide lost patent protection in China on March 20, 2026, and Wegovy fell from about 1,900 yuan a month to below 1,000 yuan in hospitals in Yunnan and Sichuan early in 2026, The Star reported. Brands that hold deep inventory in 5XL and above are most exposed if uptake of these and other anti-obesity drugs accelerates.
High return rates erode online seller margins
Fit uncertainty drives high returns in plus-size clothing, which erodes margins for online sellers. Chinese letter sizes are not standardized across sellers, so an item marked 6XL can fit like a local 4XL and buyers return items that miss by 20 to 25 kg. Taobao, JD.com, Douyin and Kuaishou rolled back refund-only policies in April 2025 after regulators raised the issue during the Two Sessions, TechNode reported, which gives merchants more control in disputes. Small sellers without size guidance or fit tools remain most exposed to returns.
Clothing spending trails overall consumption growth
Clothing takes a shrinking share of household budgets, which limits how fast any apparel category can grow. Per capita clothing spending rose 2.2% to 1,554 yuan in 2025, the National Bureau of Statistics said, against 4.4% for all consumption. Online clothing sales rose just 1.9% that year, which lags the growth of online goods sales overall. Mass-tier sellers that compete only on price are most exposed, while brands with better fit can still win share.
A falling child overweight rate caps children's demand
A falling child overweight rate limits growth in children's plus-size ranges, which already form the smallest gender segment. The overweight and obesity rate among children under 6 fell to 9.7% from 10.4% five years earlier, National Health Commission head Lei Haichao said in September 2025. Children's lines that rely on extended sizes alone are most exposed, while brands that design adjustable fits for growing children face less risk from this decline.
East China spends most as inland zones catch up
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| East China | 6.23 | 35.0% | 6.4% |
| North and Northeast China | 4.62 | 26.0% | 6.9% |
| Central and Western China | 4.27 | 24.0% | 7.3% |
| South China | 2.67 | 15.0% | 6.3% |
East China leads on coastal incomes and seller hubs
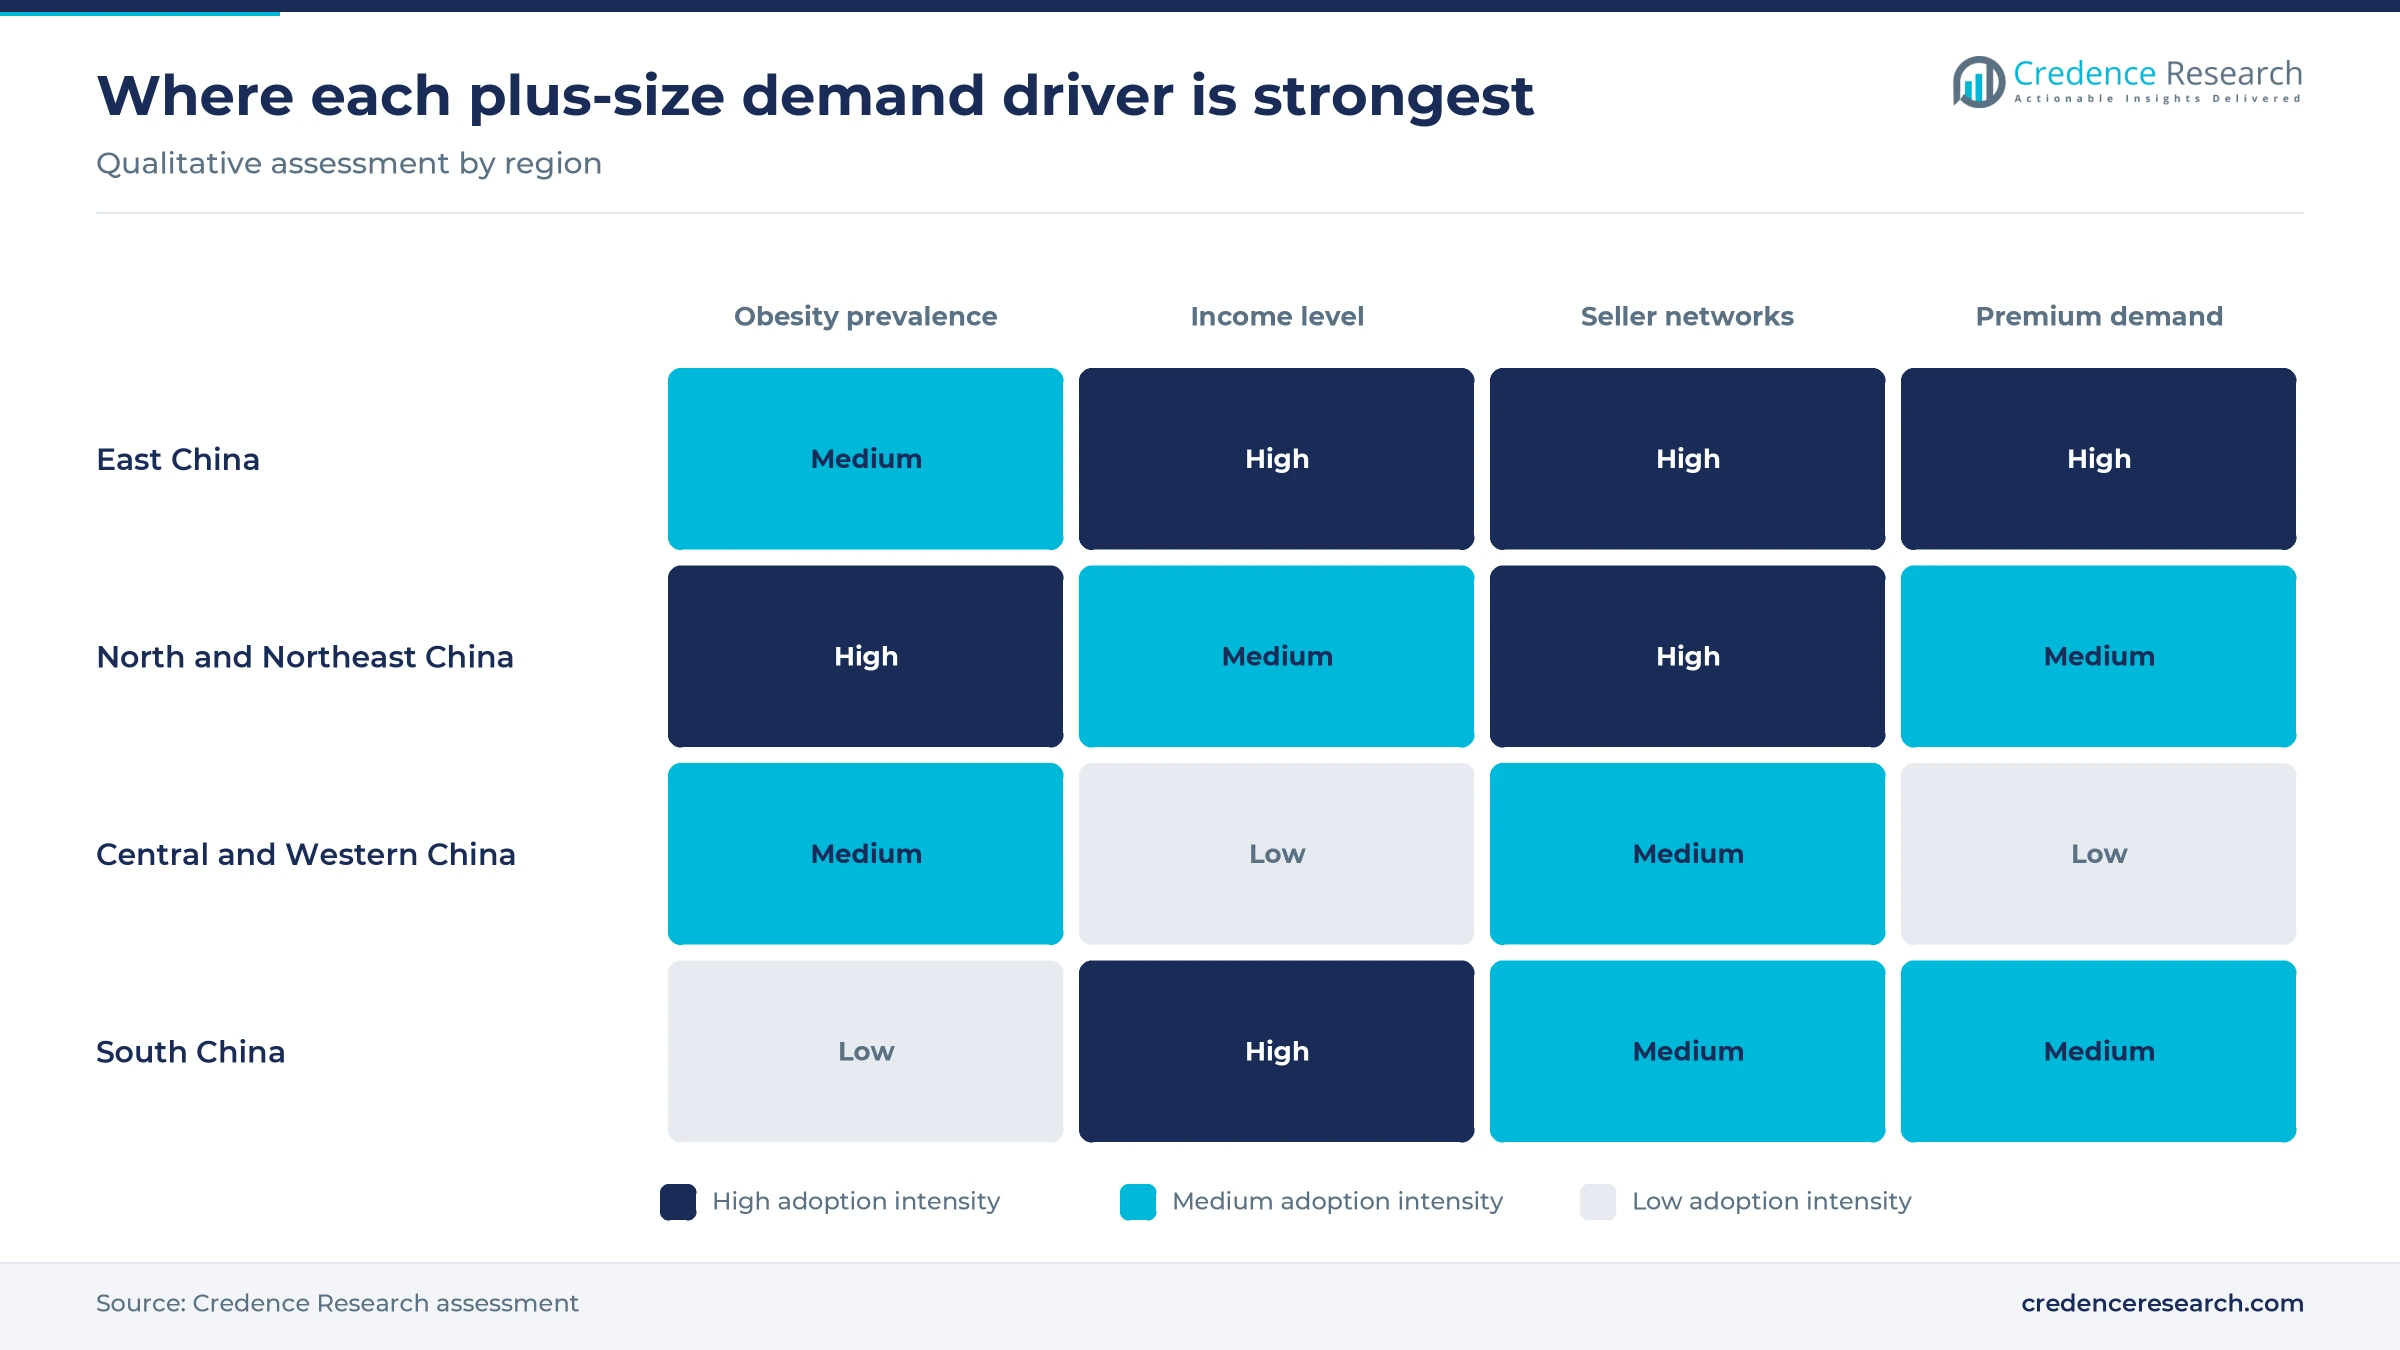
East China held 35.0% of 2025 value and grows at 6.4% a year through 2035. Shandong sits in the highest obesity tier, where roughly one adult in five is obese, according to a map released by the China CDC Chronic Disease Center in September 2025, while Shanghai sits in the middle tier. Hangzhou incubator Dama Wenchuang coached 23 plus-size livestream hosts, Alizila reported in May 2019. Neiwai reopened its Shanghai flagship at Jing An Kerry Centre in September 2025, which keeps premium store demand anchored on the coast.
North and Northeast China hold the heaviest consumers
North and Northeast China held 26.0% of 2025 value and grows at 6.9% a year. Beijing, Tianjin, Hebei, Inner Mongolia and Liaoning all sit in the highest obesity tier on the China CDC map. Kuaishou sellers at Xiliu Market in Haicheng name Liaoning, Hebei, Jilin, Heilongjiang and Inner Mongolia among their priority provinces, Sixth Tone reported. This combination of heavier consumers and a local wholesale hub keeps mass-tier plus-size supply cheap across the north.
Central and Western China grows from inland incomes
Central and Western China held 24.0% of 2025 value and is the fastest-growing region at 7.3% a year. Hubei, Chongqing and Sichuan sit in the middle obesity tier on the China CDC map. Public sources reviewed do not show plus-size retail counts for the region, which is an evidence gap, so growth is assumed to follow the faster rural income growth noted above and wider parcel delivery to inland counties.
South China buys less but hosts plus-size labels
South China held 15.0% of 2025 value and grows at 6.3% a year. Guangdong and Guangxi sit in the lowest obesity tier, where roughly one adult in ten is obese, on the China CDC map. The region still matters on the supply side, because Guangzhou labels such as Yue Design, noted above, sell plus-size clothing to buyers nationwide. Local demand stays smaller than its production role, so regional value grows slowest.
Health campaigns, drug approvals and refund rules
| Development | Status and market relevance |
|---|---|
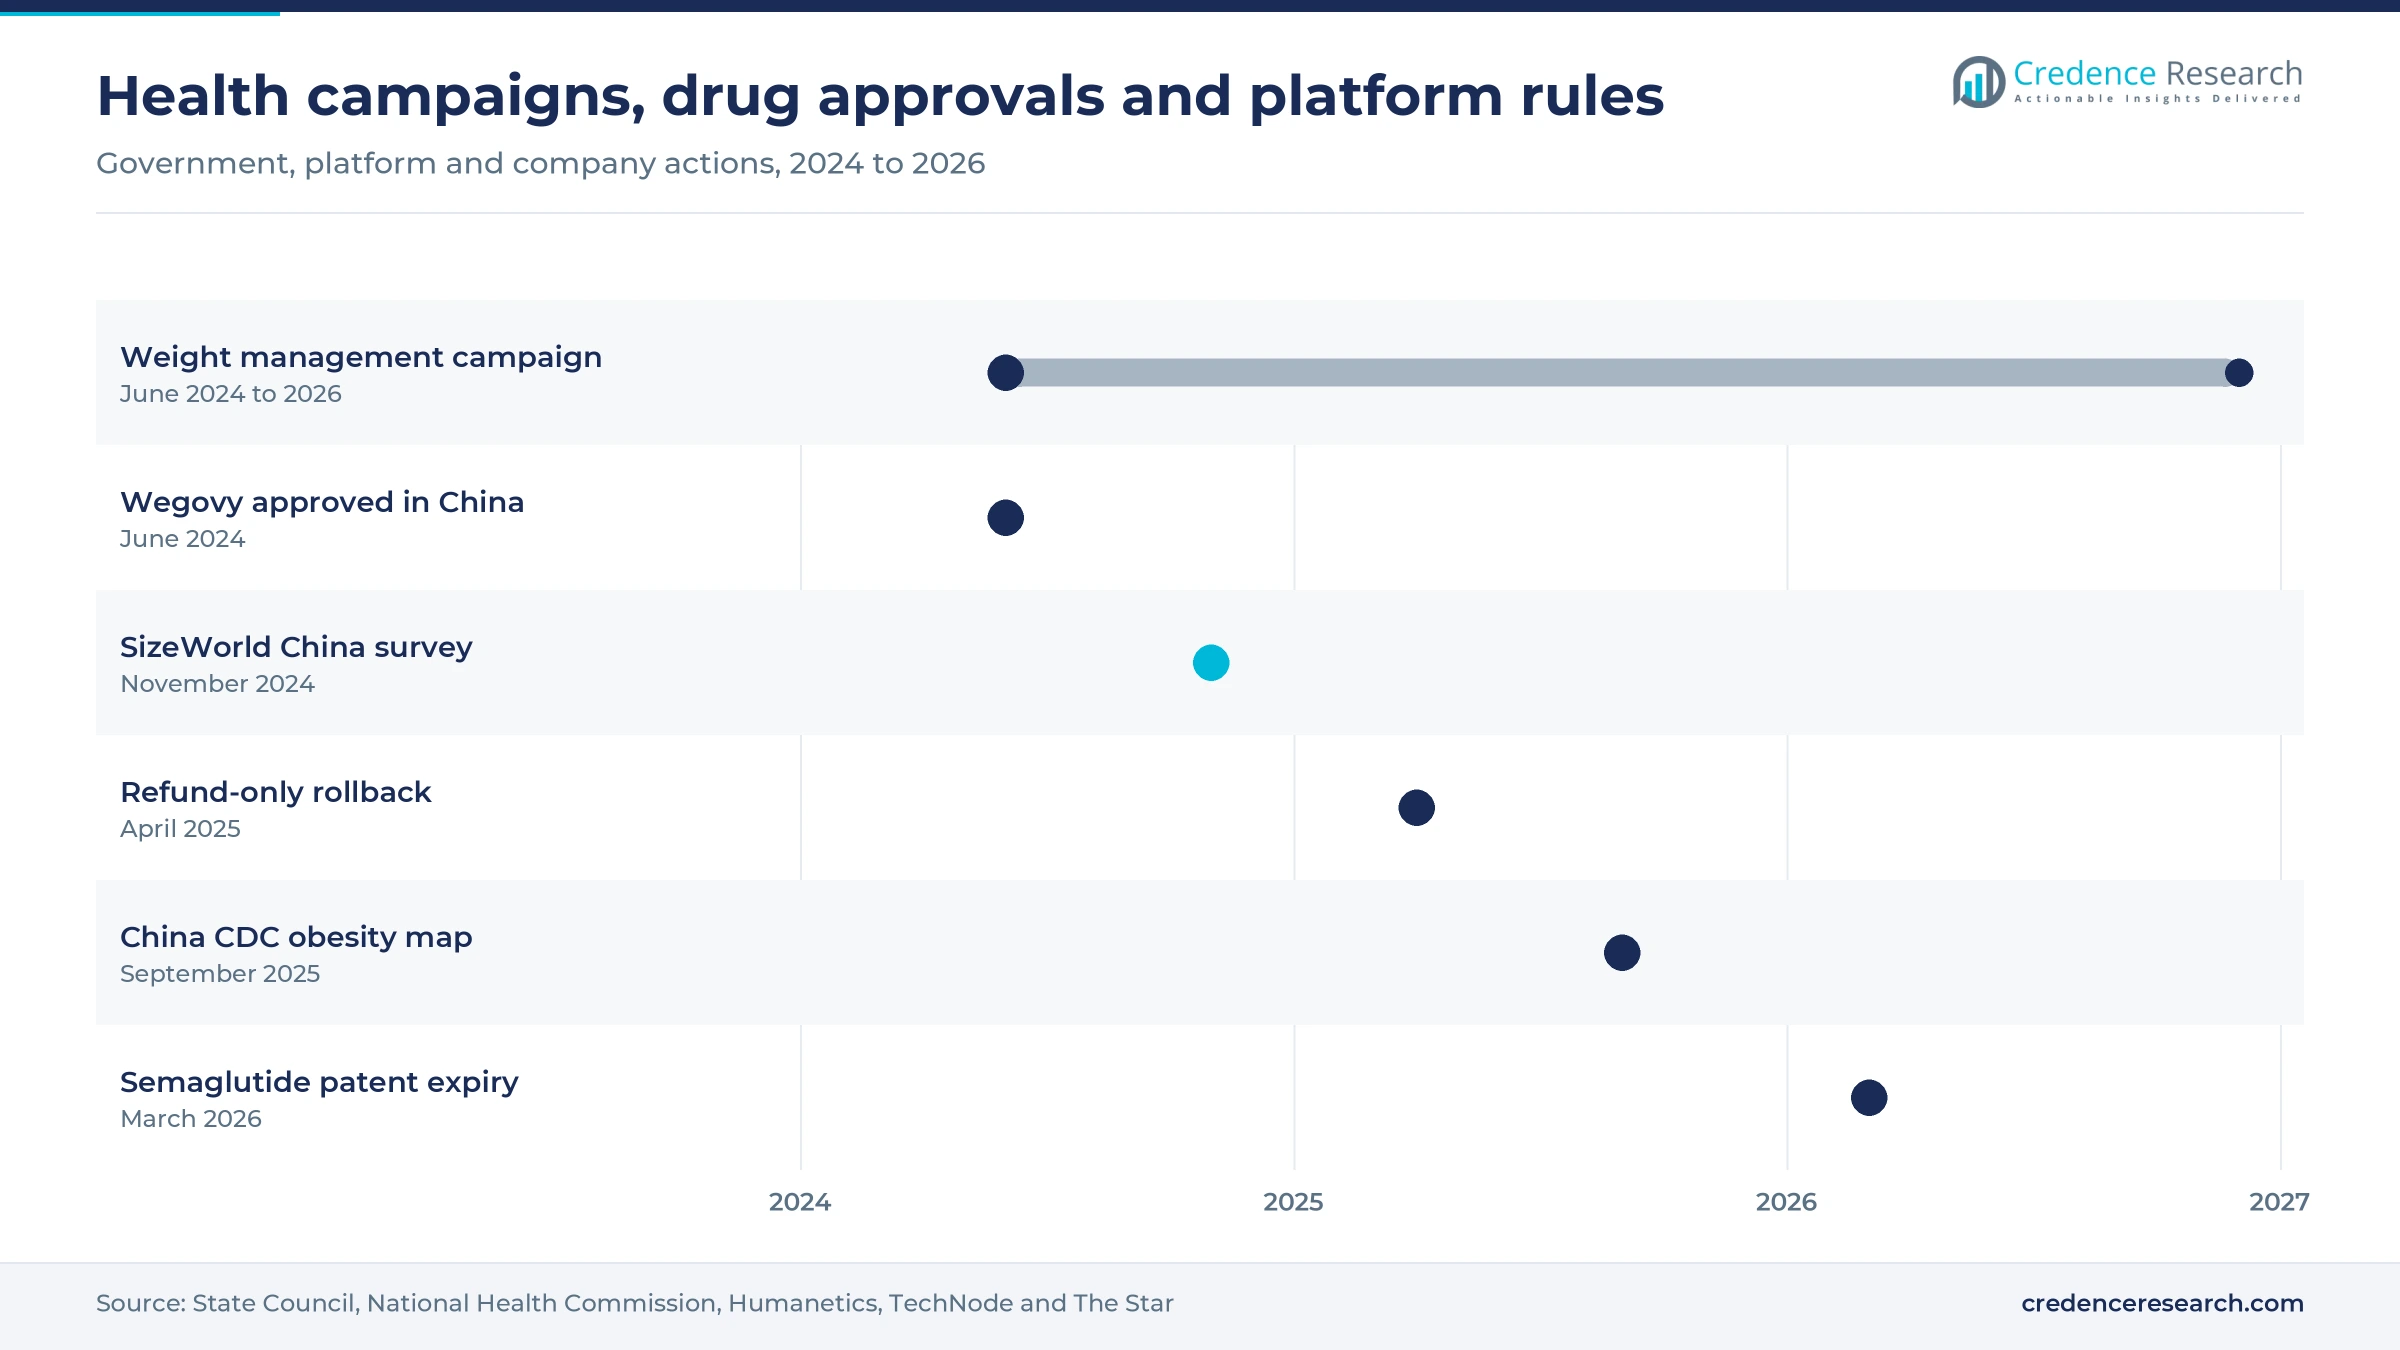
| In June 2024, the National Health Commission and 15 other departments launched a three-year weight management campaign covering schools, workplaces and communities. | Launch; the campaign runs through 2026 and shapes sportswear demand. |
| In June 2024, Novo Nordisk announced approval of Wegovy in China for adults with a BMI of 30 or more and at least one weight-related condition. | Approval; use is initially limited to higher-BMI patients with a related condition. |
| In November 2024, Humanetics published its SizeWorld China survey of 9,023 people scanned at 15 locations in six regions. | Completed; the data are available to brands for size chart revisions. |
| In April 2025, Taobao, JD.com, Douyin and Kuaishou rolled back refund-only policies that let shoppers keep goods after refunds. | Policy change implemented; it gives apparel merchants more control in return disputes. |
| In March 2026, semaglutide lost patent protection in China, with Hangzhou Jiuyuan, Livzon, Qilu and other drugmakers filing generic versions. | Patent expiry completed; generic approvals are pending, which could lower drug prices further. |
Body scan data, stretch fits and size search tools
- 3D body scan data gives pattern makers current measurements of heavier Chinese bodies, which reduces the gap between labeled and actual size.
- Stretch one-size designs let one garment fit a wider weight range, which cuts the number of size units a seller must stock.
- Weight-based size search lets shoppers filter online listings by kilograms and height instead of letter sizes, which lowers fit errors.
- Livestream fit demonstration shows each garment on a host of similar build, which answers fit questions before the order is placed.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Online specialists compete with global basics brands
Competition in the China plus size clothing market splits between online specialists and mainstream brands. Plusmall, founded by influencer Yang Tianzhen, and thousands of Taobao, Douyin and Kuaishou sellers compete on fast style turnover and fit demonstration by hosts of similar build. Fast Retailing's Uniqlo and H&M compete on basics through national store networks and online flagship stores, where wider size runs are easiest to stock. Nike, Adidas, Anta and Li Ning bring sportswear brand strength and compete for buyers starting exercise programs. Neiwai and Ubras compete in innerwear with stretch designs that fit a wider weight range, while Victoria's Secret has used plus-size ambassadors in its China campaigns. Buyers judge suppliers on fit consistency across sizes, return handling and price, so labels that grade patterns well for 4XL and above hold customers longest.
How is the plus-size supply side organized?
Supply runs in three tiers that share the same factories. Thousands of small online and livestream sellers buy from wholesale clusters such as Xiliu Market in Liaoning and compete on price and speed. Specialist labels such as Plusmall build brand loyalty through influencer founders and own design. Global and domestic mass brands such as Uniqlo, H&M, Nike, Adidas, Anta and Li Ning compete for larger shoppers with existing ranges, and size depth varies by brand. Entry barriers are low for sellers but high for brands, and margins sit with labels that control grading and fit.
Brands that plus-size shoppers in China shortlist
| Company | Type | Role in the market |
|---|---|---|
| Fast Retailing Co., Ltd. (Uniqlo) | Global basics brand | Sells casual wear and innerwear in China through stores and online |
| H&M Group | Global fashion retailer | Sells fashion and basics in China through stores and online flagship stores |
| Nike, Inc. | Global sportswear brand | Sells sportswear and training apparel in China through stores and Tmall |
| Adidas AG | Global sportswear brand | Sells sportswear and training apparel in China through stores and online |
| Anta Sports Products Limited | Domestic sportswear leader | Sells sportswear and training apparel through a national store network |
| Li Ning Company Limited | Domestic sportswear brand | Sells sportswear and athleisure apparel through stores and online channels |
| Plusmall | Plus-size specialist | Sells plus-size women's fashion online, founded by influencer Yang Tianzhen |
| Neiwai | Innerwear and loungewear brand | Sells size-inclusive lingerie, loungewear and activewear through stores and online |
| Ubras | Innerwear brand | Sells one-size stretch bras and innerwear mainly through online channels |
| Victoria's Secret & Co. | Global lingerie brand | Sells lingerie in China and has used plus-size ambassadors in campaigns |
Men and premium lines hold the untapped value
Credence Research's view is that men's big-and-tall ranges and premium women's labels hold more untapped value than the crowded mass tier. Mass livestream sellers already serve women at very low prices, so new entrants there compete mainly on cost. Men have higher overweight and obesity rates than women, yet few labels design for them, and women above 70 kg still find few premium options. Brands that grade patterns from current body scan data and keep return rates low should gain share, while weight-loss drugs are the main threat to volume growth after 2027.
Estimates rest on official and company data
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. The 2025 value is a Credence Research estimate built from national household clothing spending, the share of garments sold in extended sizes and typical plus-size prices, and it replaces the earlier estimate, which overstated the plus-size share of garment spending. Market values come from the Credence Research model, and the regional, type, gender, pricing and channel splits are Credence Research estimates informed by public data. Sources include National Bureau of Statistics releases, National Health Commission data, the China CDC obesity map, platform policy reports, company announcements and business publishers. No official statistic tracks plus-size garment sales, and several retail data points date from 2019 to 2021, so the pricing and channel splits carry wider ranges. No interviews or surveys were used to build these estimates.
Assortment depth decides who gains value to 2035
Credence Research expects plus-size clothing value in China to reach USD 34.12 billion by 2035 as heavier adults buy better-fitting garments and brands extend size runs beyond 4XL. Central and Western China should keep the fastest pace, while East China remains the largest source of value. Sportswear grows at 8.0% a year during 2026–2035, ahead of casual wear, as weight programs bring larger adults into exercise. Generic semaglutide approvals are the main downside, because they could reduce the number of buyers needing extended sizes, while men's and premium lines offer the clearest upside.
Weight-loss drug uptake sets the range of outcomes
The range to 2035 depends mainly on how fast cheaper GLP-1 drugs reach mass use after the patent expiry, and on whether men's and premium ranges widen. Overweight prevalence supports every case, but drug uptake decides how many adults move back into standard sizes. Brand investment in men's big-and-tall ranges and sportswear fits adds upside if labels convert the national weight campaign into new apparel purchases.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 4.7% | USD 28.78 billion | Generic semaglutide approvals cut prices and pull many buyers back into standard sizes |
| Base | 6.73% | USD 34.12 billion | Drug uptake stays limited to higher-BMI patients and online assortment keeps widening |
| Upside | 8.2% | USD 38.68 billion | Men's big-and-tall and premium plus-size ranges reach mainstream brands nationwide |
Frequently Asked Questions
How big is the China plus size clothing market?
How common are plus sizes in China?
What does XXXXL mean in Chinese clothing sizes?
Which clothing type leads the market?
How large is plus-size demand for children's sportswear in China?
Which region leads plus-size clothing demand?
What are the main challenges for plus-size clothing sellers?
Who are the main companies in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Casual
- 1.2.2 Sportswear
- 1.2.3 Inner Wear
- 1.2.4 Formal
- 1.2.5 Ethnic Wear
- 1.3 By Gender
- 1.3.1 Women
- 1.3.2 Men
- 1.3.3 Children
- 1.4 By Pricing
- 1.4.1 Mass
- 1.4.2 Premium
- 1.4.3 Luxury
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 17.79 billion → 2035: USD 34.12 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 China Plus Size Clothing Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 China Plus Size Clothing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 China Plus Size Clothing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 China Plus Size Clothing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 China Plus Size Clothing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 China Plus Size Clothing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 China Plus Size Clothing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 China Plus Size Clothing Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 17.79 billion → 2035: USD 34.12 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 China Plus Size Clothing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Casual
- 12.3.7.2 Sportswear
- 12.3.7.3 Inner Wear
- 12.3.7.4 Formal
- 12.3.7.5 Ethnic Wear
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Gender - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Women
- 12.4.7.2 Men
- 12.4.7.3 Children
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Pricing - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Mass
- 12.5.7.2 Premium
- 12.5.7.3 Luxury
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 China Plus Size Clothing Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 China Plus Size Clothing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 China Plus Size Clothing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Fast Retailing Co., Ltd. (Uniqlo)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 H&M Group
- 17.4 Nike, Inc.
- 17.5 Adidas AG
- 17.6 Anta Sports Products Limited
- 17.7 Li Ning Company Limited
- 17.8 Plusmall
- 17.9 Neiwai
- 17.10 Ubras
- 17.11 Victoria's Secret & Co.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

