
Market Overview:
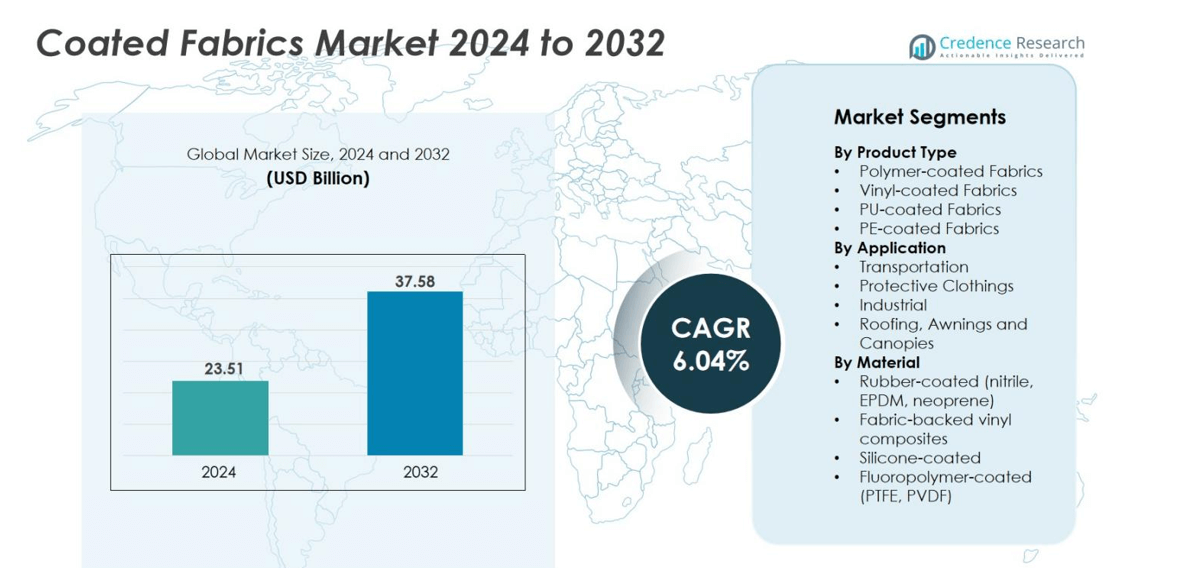
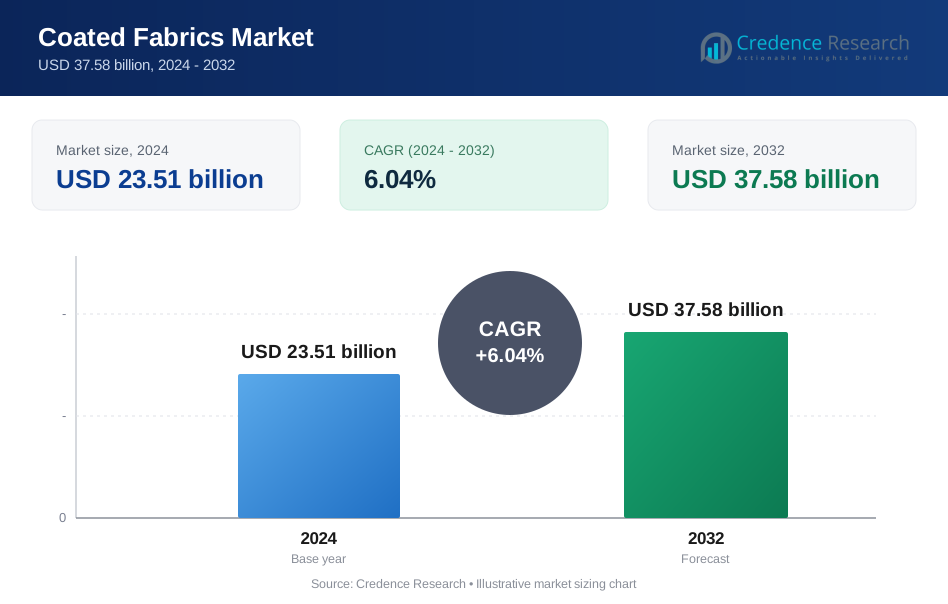
Coated Fabrics market size was valued USD 23.51 Billion in 2024 and is anticipated to reach USD 37.58 Billion by 2032, at a CAGR of 6.04% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Coated Fabrics Market Size 2024 | USD 23.51 Billion |
| Coated Fabrics Market, CAGR | 6.04% |
| Coated Fabrics Market Size 2032 | USD 37.58 Billion |
The coated fabrics market includes major companies such as ContiTech AG, Trelleborg AB, Saint-Gobain S.A., Spradling International Inc., Omnova Solutions, Takata Corporation, Isotex S.p.A, Graniteville Specialty Fabrics, Mauritzon Inc., and Bo-Tex Sales Co. These suppliers compete on durability, flame resistance, UV protection, and advanced polymer technologies for automotive, industrial, and protective clothing applications. Asia Pacific remains the leading region with 39% market share, supported by large-scale manufacturing, strong automotive output, and expanding construction activity. North America follows with 28% share, driven by high standards in worker safety, transportation, and industrial infrastructure.
Market Insights
- The coated fabrics market was valued at USD 23.51 billion in 2024 and is expected to reach USD 37.58 billion by 2032, at a CAGR of 6.04%.
- Strong demand in transportation drives the market, with automotive and commercial vehicles using coated fabrics for airbags, seating, and tarpaulins. Transportation accounts for 37% share, supported by durability, flame resistance, and weather protection.
- Sustainability trends promote low-VOC coatings, recycled composites, and bio-based polymers. Technical textiles with antimicrobial, UV-resistant, and heat-shielding properties gain traction in healthcare, industrial, and defense.
- Leading players include ContiTech AG, Trelleborg AB, Saint-Gobain S.A., Omnova Solutions, and Spradling International Inc., competing on regulatory certifications, coating technology, and long-service-life materials.
- Asia Pacific holds 39% market share, North America 28%, and Europe 24%. Polymer-coated fabrics dominate product type with 42% share, followed by vinyl at 28%, supported by construction, automotive, marine, and industrial applications.
Market Segmentation Analysis:
By Product Type
Polymer-coated fabrics hold the dominant position with close to 42% market share, driven by strong usage in automotive seating, truck tarpaulins, and protective clothing. Vinyl-coated fabrics account for around 28%, supported by indoor and outdoor furniture, marine upholstery, and tent applications due to high abrasion resistance. PU-coated fabrics represent about 19% of demand in premium consumer goods, while PE-coated fabrics capture nearly 11%, mainly in packaging and industrial liners. Long-term growth is supported by durable, UV-resistant, and fire-retardant coatings demanded across transportation and industrial sectors.
- For instance, Covestro supplies durable thermoplastic polyurethane films and flexible PU foam used in automotive seats for armrests and lumbar support, enhancing comfort and durability.
By Application
Transportation leads the market with nearly 37% share, fueled by airbags, seat covers, truck covers, and marine upholstery. Manufacturers prefer coated fabrics for light weight, flame resistance, and long product life. Protective clothing contributes around 24%, driven by workplace safety rules and standards in construction, chemicals, and oil and gas. Industrial applications hold about 22%, covering conveyor belts, tents, and flexible storage tanks. Roofing, awnings, and canopies account for roughly 17%, supported by weather-resistant building materials for commercial spaces and urban infrastructure.
- For instance, Trelleborg’s Dartex END464-E fabric, launched in 2024, is engineered for healthcare seating and provides exceptional durability and resistance against harsh chemical cleaning agents, using advanced polymer technology and 100% recycled yarn certified to the Global Recycled Standard.
By Material
Fabric-backed vinyl composites dominate the material segment with almost 39% market share, due to broad use in automotive interiors, furniture, covers, and heavy-duty industrial applications. Rubber-coated fabrics, including nitrile, EPDM, and neoprene, hold around 27%, supported by oil-resistant and outdoor environments. Silicone-coated materials represent near 18%, used in high-temperature and non-stick applications. Fluoropolymer-coated options such as PTFE and PVDF account for roughly 16%, serving extreme chemical exposure and harsh industrial conditions. Demand rises as industries seek durable and regulatory-compliant coatings.
Key Growth Drivers
Rising Demand from Transportation and Automotive Applications
Transportation remains a major driver for coated fabrics due to strong consumption in airbags, seat covers, truck tarpaulins, and marine upholstery. Automakers prefer coated fabrics for their durability, flame resistance, water resistance, and long service life. The material also supports lightweight vehicle design, which helps improve fuel efficiency and meets global emission regulations. Commercial vehicle manufacturers use coated fabrics for cargo covers and protective interior surfaces that withstand heavy use. Electric vehicles add new demand for heat-resistant and chemical-resistant interiors. Marine and aviation industries adopt coated fabrics for seating, inflatable structures, and protective gear. Urban logistics fleets rely on coated fabrics for tarpaulins and container coverings that resist UV, weather, and abrasion.
- For instance, truck manufacturers use PVC-coated polyester tarpaulins for cargo protection due to their waterproof and UV-resistant properties, with companies such as SATTLER PRO-TEX providing durable tarps suited for long-haul trucking.
Growth in Protective Clothing and Industrial Safety Standards
Protective clothing drives significant demand because coated fabrics offer chemical resistance, puncture resistance, flame retardancy, and waterproofing. Industries such as construction, mining, oil and gas, and chemical processing require protective suits, gloves, boots, and gear that can withstand harsh environments. Governments enforce strict worker safety rules, pushing organizations to replace traditional textiles with coated alternatives. Hospitals and emergency response agencies use coated fabrics for contamination suits, medical gowns, and firefighting gear. The material’s ability to block liquids and toxic particles increases its adoption in hazardous locations. Heavy industrial factories, power plants, and warehouses purchase coated fabrics for conveyor belts, lifting bags, and protective screens.
- For instance, DuPont’s Tychem® QC fabric, which combines Tyvek® with a polyethylene coating, provides chemical protection against more than 40 hazardous chemicals and is widely used in chemical processing and emergency response garments.
Expansion of Building, Construction, and Architectural Projects
Buildings and commercial infrastructure create strong demand for coated fabrics in roofing membranes, canopies, awnings, tarps, and fabric-based architectural structures. These products offer weatherproofing, UV resistance, high tensile strength, and tear resistance, making them ideal for outdoor installations. Urban development and smart city projects increase the need for lightweight, flexible construction materials. Retail malls, airports, sports venues, and transport terminals install coated fabric canopies and tensile structures for both shade and aesthetic appeal. Waterproof industrial shelters and storage facilities also prefer coated materials because they resist corrosion and handle long-term outdoor exposure. The construction industry uses coated fabrics for temporary enclosures, scaffolding covers, and insulation layers.
Key Trends & Opportunities
Growth of Eco-Friendly and Sustainable Coating Technologies
Sustainability reshapes the coated fabrics market as industries move away from traditional solvent-based coatings toward water-based, bio-based, and low-VOC chemical formulations. Manufacturers invest in recyclable substrates and non-toxic additives that reduce environmental impact. Automotive and consumer brands demand greener materials to meet corporate sustainability goals and environmental regulations. Bio-PU and bio-PVC coatings create opportunities for furniture, footwear, and interior design. Recycled polyester and fabric-backed composites reduce waste and carbon emissions. Governments promote eco-certified materials, boosting market adoption. Companies also explore biodegradable fabrics and coating systems that maintain durability without harmful chemicals.
- For instance, Autoliv introduced airbags made from 100% recycled polyester in 2024, demonstrating how safety-critical automotive components can incorporate reclaimed materials without compromising performance.
Rapid Growth of Technical Textiles and Smart Coated Surfaces
Technical textile innovation leads to advanced coated fabrics with antimicrobial, heat-resistant, anti-fungal, reflective, and self-cleaning properties. Smart coatings integrate sensors, conductive layers, and fire-protective finishes for defense, aerospace, and emergency response. Medical facilities adopt antimicrobial and barrier-grade coated fabrics for beds, curtains, and protective clothing. Flame-retardant and UV-stabilized coatings support expanding industrial and outdoor applications. Military and defense agencies demand coated fabrics for tents, inflatable boats, protective gear, and camouflage covers. As industries require specialized performance, high-value technical textiles present strong opportunities for premium product categories.
- For instance, Nobletex Industries supplies medical fabrics with antibacterial coatings that repel body fluids and inhibit pathogen growth, with privacy curtains tested to reduce bacteria by 99%, supporting safer hospital environments.
Key Challenges
Environmental and VOC-Based Regulatory Restrictions
Traditional PVC and solvent-based coatings generate environmental concerns due to high VOC emissions and hazardous chemical content. Governments implement strict rules on plasticizers, wastewater disposal, flue gas treatment, and manufacturing emissions. Companies must redesign production lines and invest in expensive purification technologies. Shifting to eco-friendly materials increases cost and slows production for smaller manufacturers. Compliance challenges raise product pricing and limit market access in developed economies. These regulatory pressures push the industry toward water-based coatings and alternative polymers, but development and scaling remain expensive.
Price Fluctuations in Raw Materials and Supply Chain Disruptions
Coated fabric manufacturing depends on polymers, resins, rubber, and industrial fabrics, all of which face price volatility. Oil-based raw materials such as PVC, PU, neoprene, and nitrile fluctuate based on crude oil markets and global supply disruptions. Transportation delays, trade restrictions, and shortages of chemical additives increase operational costs. Manufacturers face margin pressure because end-users often resist price increases. Small firms struggle to balance procurement cost and production quality. Consistent raw material inflation affects profitability, forcing companies to adopt long-term supply contracts, backward integration, or recycled inputs.
Regional Analysis
North America
North America holds 28% market share, supported by strong demand from automotive interiors, protective clothing, and industrial applications. The U.S. leads consumption due to advanced vehicle manufacturing, construction projects, and strict worker-safety regulations. Coated fabrics are widely used in airbags, seating, tarpaulins, tents, and fire-resistant protective gear. The region invests in high-performance polymers and eco-friendly coating technologies to meet environmental standards. Growth also comes from military tents, aviation seating, and healthcare protective materials. Increased adoption of lightweight and durable fabrics in commercial transport and marine sectors boosts long-term sales across the United States and Canada.
Europe
Europe accounts for 24% market share, driven by strong demand from automotive OEMs, industrial equipment producers, and architectural projects. Germany, France, Italy, and the UK remain major buyers of PU-coated and fluoropolymer-coated fabrics due to premium upholstery and stringent safety standards. Construction companies use coated fabrics for roofing membranes, canopies, and tensile structures. Strict REACH and sustainability regulations encourage the shift to low-VOC and recyclable coatings. Protective clothing demand rises in chemical, mining, and oil and gas operations. The region also exports advanced technical coated textiles for military, medical, and weather-resistant outdoor structures.
Asia Pacific
Asia Pacific dominates with 39% market share, making it the largest regional market. China, India, Japan, and South Korea drive consumption through automotive production, transportation fleets, industrial manufacturing, and infrastructure growth. Large coating facilities, cost-efficient labor, and rising urbanization increase demand for tarpaulins, seat covers, conveyor belts, and protective clothing. Construction projects adopt coated roofing membranes and awning materials for commercial developments. Expanding marine logistics and container transport also boost sales. The presence of major coated fabric producers and flexible export policies support rapid market expansion across regional economies.
Latin America
Latin America captures 6% market share, driven by commercial vehicle fleets, agricultural storage covers, and construction projects. Brazil and Mexico lead demand for PVC-coated fabrics in automotive seating, tarpaulins, and truck covers. Industrial users adopt coated fabrics for conveyor systems and protective workplace gear. The region increases usage of weather-resistant roofing membranes, canopies, and shading structures in urban commercial spaces. Growth in marine transport and mining boosts heavy-duty coated textiles. Although price sensitivity affects premium products, rising safety regulations and expanding logistics networks support long-term demand.
Middle East & Africa
The Middle East & Africa represent 3% market share, but growth remains steady due to oil and gas projects, construction sites, and extreme climate conditions that require weather-resistant coated fabrics. Coated roofing membranes, tents, shade structures, and protective clothing see strong demand in GCC countries. Industrial facilities use coated conveyor belts, storage covers, and chemical-resistant materials. Infrastructure projects in Saudi Arabia, UAE, and Qatar create opportunities for architectural fabrics in stadiums, airports, and retail centers. Limited local manufacturing capacity results in heavy reliance on imports, which supports international suppliers.
Market Segmentations:
By Product Type
- Polymer-coated Fabrics
- Vinyl-coated Fabrics
- PU-coated Fabrics
- PE-coated Fabrics
By Application
- Transportation
- Protective Clothings
- Industrial
- Roofing, Awnings and Canopies
By Material
- Rubber-coated (nitrile, EPDM, neoprene)
- Fabric-backed vinyl composites
- Silicone-coated
- Fluoropolymer-coated (PTFE, PVDF)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The coated fabrics market is moderately fragmented, with global and regional manufacturers competing through product performance, material innovation, and industry certifications. Leading companies focus on durable coatings, flame retardancy, UV resistance, chemical stability, and abrasion strength to serve transportation, industrial, and protective clothing applications. Multinational brands strengthen portfolios with PU, PVC, rubber, silicone, and fluoropolymer-coated products designed for long service life and regulatory compliance. Many firms expand through strategic partnerships with automotive OEMs, construction contractors, and industrial equipment suppliers to secure recurring contracts. Investments in eco-friendly coatings, bio-based polymers, and water-based production processes help producers meet environmental standards and replace solvent-basedsystems. Companies also explore technical textiles with heat shielding, antimicrobial properties, and self-cleaning surfaces for premium markets. Asia Pacific players benefit from large-scale manufacturing and lower production costs, while North American and European manufacturers gain an edge in high-performance and specialty coated fabrics.
Key Player Analysis
- ContiTech AG
- Mauritzon Inc.
- Spradling International Inc.
- Trelleborg AB
- Graniteville Specialty Fabrics
- Takata Corporation
- Saint-Gobain S.A.
- Isotex S.p.A
- Bo-Tex Sales Co.
- Omnova Solutions
Recent Developments
- In December 2024, Trelleborg Engineered Coated Fabrics partnered with Taiwan-based True Source to supply Dartex stretch TPU mattress covers for next-generation alternating-pressure medical beds. The partnership strengthens Trelleborg’s position in the premium healthcare coated fabrics segment.
- In September 2024, Freudenberg Performance Materials expanded its coated technical textiles business by acquiring key assets from the Heytex Group for approximately EUR 100 million. The acquisition includes three production facilities in Germany and China, boosting the company’s global manufacturing presence.
- In August 2024, Carnegie, a provider of sustainable textiles and acoustical management solutions, expanded its Conscious Collection with the addition of Botanic Print and Embellish Print in its silicone hybrid coated upholstery line. Leveraging digital printing technology, the new designs enhance cleanability, durability, and aesthetics inspired by historic embroidery craftsmanship.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Material and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise in transportation and automotive interiors due to safety and durability needs.
- Protective clothing will gain traction as industries enforce stronger worker safety regulations.
- Eco-friendly coatings and recycled substrates will replace solvent-based systems and traditional PVC in many applications.
- Technical textiles with antimicrobial, flame-retardant, and UV-resistant surfaces will see higher adoption in premium markets.
- Construction projects will continue using coated roofing membranes, tensile structures, and awnings for commercial infrastructure.
- Defense and aerospace sectors will expand purchases of weatherproof, chemical-resistant, and heat-shielded coated fabrics.
- Manufacturers will invest in water-based and bio-based polymer coatings to meet environmental compliance.
- Automation and advanced coating lines will improve production speed, product quality, and material uniformity.
- Asia Pacific will strengthen its leadership due to large-scale manufacturing and automotive output.
- Strategic mergers and supply agreements with OEMs will boost long-term contract stability for major producers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Coated Fabrics market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Coated Fabrics market projected to grow between 2025 and 2032?
Which Coated Fabrics market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Coated Fabrics market?
Who are the leading companies in the Coated Fabrics market?
Which region commanded the largest share of the Coated Fabrics market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 23.51 billion → 2032: USD 37.58 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Coated Fabrics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Coated Fabrics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Coated Fabrics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Coated Fabrics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Coated Fabrics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Coated Fabrics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Coated Fabrics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Coated Fabrics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 23.51 billion → 2032: USD 37.58 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Coated Fabrics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Coated Fabrics Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Coated Fabrics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Coated Fabrics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

