
Market Overview
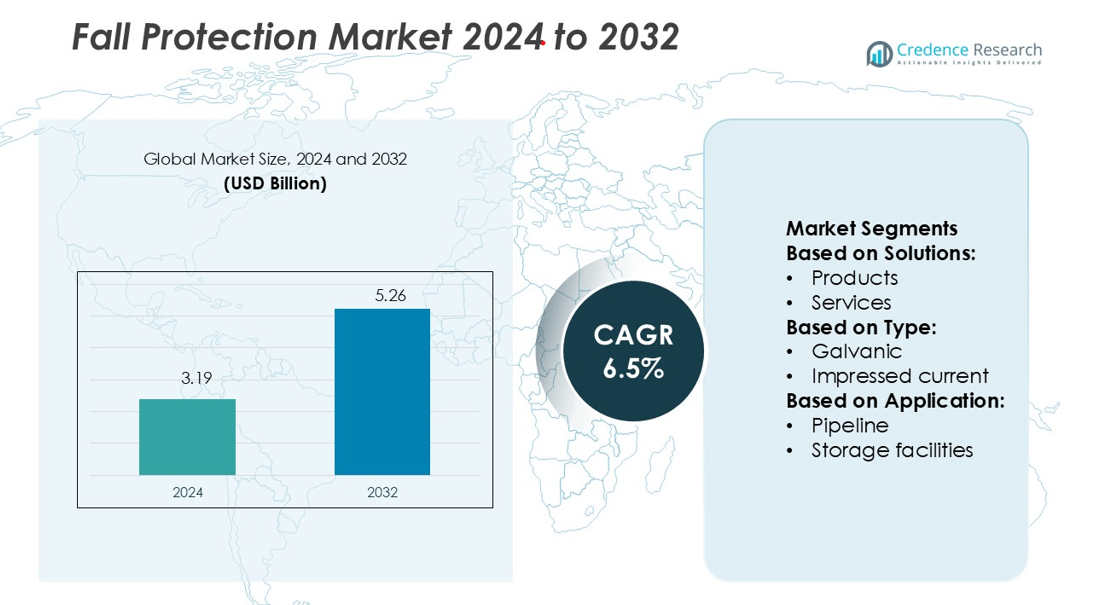
Fall Protection Market size was valued USD 3.19 billion in 2024 and is anticipated to reach USD 5.26 billion by 2032, at a CAGR of 6.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fall Protection Market Size 2024 | USD 3.19 billion |
| Fall Protection Market, CAGR | 6.5% |
| Fall Protection Market Size 2032 | USD 5.26 billion |
The fall protection market is driven by leading players such as Pure Safety Group (PSD), MSA Safety Company, Honeywell Miller, Guardian Industries, Mallcom India Limited, French Creek Production, KARAM, GF Protection Canada, Capital Safety, and 3M. These companies focus on product innovation, regulatory compliance, and global distribution expansion to strengthen their market positions. North America dominates the fall protection market with a 37.6% share, supported by strict safety regulations, rapid infrastructure development, and widespread use of advanced protective equipment. Strong investment in connected safety technologies and worker training further reinforces the region’s leadership, setting high industry standards worldwide.
Market Insights
- The fall protection market was valued at USD 3.19 billion in 2024 and is projected to reach USD 5.26 billion by 2032, growing at a CAGR of 6.5%.
- Strong regulatory frameworks and increased focus on workplace safety drive product demand across construction, manufacturing, and energy sectors.
- Smart wearable technologies and IoT integration are key trends enhancing monitoring, compliance, and operational efficiency.
- The market is competitive with major players focusing on innovation, compliance, and global expansion to strengthen their positions.
- North America leads with a 37.6% market share, while product segments such as harness systems and anchorage solutions account for a significant share of overall revenue growth.
Market Segmentation Analysis:
By Solutions
The products segment holds the dominant share of the Fall Protection Market, accounting for 72.3% in 2024. The segment includes harnesses, lanyards, anchor points, guardrails, and self-retracting lifelines that provide safety across high-risk environments. The demand is driven by strict workplace safety regulations, especially in construction and industrial sectors. Continuous product innovation, such as lightweight harnesses and enhanced energy absorbers, supports widespread adoption. Service offerings like inspection, installation, and training are gaining traction but remain secondary due to higher investments in physical safety equipment.
- For instance, MSA’s V-SHOCK® EDGE Leading Edge Self Retracting Lanyard uses a 0.2165 inch (5.5 mm) galvanized steel cable and supports a user weight capacity of 310 lbs.
By Type
The galvanic segment leads the Fall Protection Market with a 65.8% share in 2024. Galvanic systems offer lower maintenance requirements, reliable corrosion resistance, and cost-effective installation, which make them suitable for long-term safety structures. These systems are widely used in industrial and infrastructure projects to secure platforms, towers, and elevated work areas. Impressed current systems are growing steadily due to advanced monitoring capabilities, but they involve higher installation and operational costs compared to galvanic options.
- For instance, Honeywell Miller H100 full-body harness series supports different maximum working loads depending on the safety standard; for example, the capacity is 400 lbs (181.4 kg) under the OSHA standard but 310 lbs (140.6 kg) under the ANSI standard. The model H11110022 has a confirmed weight of 2.54 lbs (1.15 kg).
By Applications
The pipeline segment dominates the Fall Protection Market with a 31.4% share in 2024. Pipeline infrastructure often involves elevated maintenance zones, demanding reliable fall arrest systems for worker safety. Adoption is driven by strict safety protocols in oil, gas, and chemical industries. Storage facilities and processing plants follow closely, driven by high operational risks in confined spaces and elevated platforms. The water and wastewater, transportation, and building sectors are also increasing investments in safety systems as regulatory frameworks strengthen globally.
Key Growth Drivers
Rising Industrial Safety Regulations
The fall protection market is growing due to stricter safety standards across industries. Regulatory bodies enforce mandatory use of fall protection systems in construction, oil and gas, manufacturing, and utilities. Employers invest in personal protective equipment to reduce workplace accidents and legal liabilities. These regulations support continuous demand for advanced harnesses, guardrails, and anchor systems. Regular inspections and certifications strengthen market adoption. Companies focus on compliance to avoid penalties and enhance worker safety, driving steady growth in product installations and upgrades.
- For instance, Guardian’s B7-Comfort Full-Body Harness is rated for a user capacity of 100 to 420 lb under OSHA rules and 130 to 310 lb under ANSI rules. The weight of the harness varies depending on the model and configuration.
Expansion of Construction and Infrastructure Projects
The surge in infrastructure investments boosts demand for fall protection solutions. Large-scale residential, commercial, and industrial projects increase the need for reliable safety systems. Governments prioritize modernization of transport and energy networks, creating new opportunities for equipment suppliers. High-rise building construction especially requires advanced lifelines, scaffolding systems, and anchorage devices. Contractors adopt durable and easy-to-install systems to meet safety targets and reduce project risks. This expansion enhances market growth across both developed and emerging economies.
- For instance, Mallcom’s HARNESS GLO high-visibility safety harness is equipped with reflective tapes, with some versions featuring 50 mm wide Avery Dennison micro-prismatic tape.
Technological Advancements in Protective Equipment
Innovation in materials and smart safety systems drives market expansion. Manufacturers integrate IoT-enabled devices for real-time monitoring and automated alerts during hazardous conditions. Lightweight harnesses and self-retracting lifelines improve worker mobility without compromising safety. Companies also invest in ergonomic designs that reduce fatigue and enhance comfort. The adoption of predictive analytics and connected wearables further boosts operational efficiency. These technological improvements increase equipment reliability, encourage higher compliance, and strengthen customer trust in advanced fall protection solutions.
Key Trends & Opportunities
Growing Adoption of Smart Wearable Devices
The fall protection market is witnessing rising use of connected safety wearables. Smart helmets, vests, and sensors provide real-time location tracking and fall detection. These devices enable faster emergency response and better incident reporting. Integration with cloud-based monitoring systems helps employers analyze safety data and prevent future accidents. This trend offers significant opportunities for solution providers to deliver integrated platforms combining hardware and software.
- For instance, KARAM’s full-body harness model PN16 (Class A) features a webbing width of 45 mm, a weight of 1.10 kg, and is certified under IS 3521 (Part 1):2021.
Increased Focus on Worker Training and Awareness
Companies are investing more in safety training programs to reduce fall-related accidents. Virtual reality (VR) and simulation tools are becoming popular in worker education. These training platforms help employees understand risks and use fall protection systems correctly. Enhanced training improves compliance with safety standards and reduces equipment misuse. This trend supports long-term adoption of fall protection solutions and opens new service-based revenue opportunities.
- For instance, 3M’s Fundamentals of Fall Protection VR PRO consists of 4 modules with scenarios such as steel beam erection and anchorage connection.The VR simulation supports hardware such as an HTC VIVE headset and a PC with at least 4 GB RAM, Intel Core i5-4590 or AMD FX 8350 processor, and NVIDIA GTX 1060 graphics.
Rising Investments in Retrofit Safety Solutions
Older infrastructure and industrial facilities are increasingly adopting retrofit fall protection systems. Facility owners aim to meet updated safety regulations without major structural changes. Retrofit solutions, such as modular guardrails and non-penetrating anchors, are cost-effective and easy to install. This trend creates growth opportunities for manufacturers specializing in adaptable and customizable systems for aging structures.
Key Challenges
High Installation and Maintenance Costs
The cost of installing and maintaining fall protection systems remains a major barrier for small and medium enterprises. Advanced equipment, regular inspections, and specialized training increase total project costs. Budget constraints often delay upgrades or limit adoption, especially in developing regions. High upfront investment can discourage businesses from implementing comprehensive solutions, affecting overall market growth.
Limited Awareness in Developing Regions
Many companies in emerging markets lack awareness of fall protection standards and safety technologies. This results in low adoption of protective systems despite increasing industrial activity. Insufficient regulatory enforcement further slows market expansion. Manufacturers face challenges in promoting compliance and building trust among cost-sensitive buyers. Overcoming this awareness gap is essential to unlock new market opportunities.
Regional Analysis
North America
North America leads the fall protection market with a 37.6% share. The region benefits from strict workplace safety regulations by OSHA and ANSI. High construction activity, strong oil and gas operations, and rapid industrialization drive adoption of personal protective equipment and lifeline systems. Advanced technologies such as IoT-based safety monitoring enhance worker safety compliance. Companies invest heavily in upgrading equipment to meet evolving standards. The growing presence of major market players also supports innovation and accessibility of high-performance solutions. Government infrastructure funding further strengthens market growth across key industries.
Europe
Europe holds a 28.4% share of the fall protection market. Strong regulatory frameworks, including EU Directives on worker safety, push industries to maintain high protection standards. The region’s mature construction and manufacturing sectors create sustained demand for guardrails, anchorage systems, and full-body harnesses. Emphasis on sustainable infrastructure projects further drives product adoption. Technological integration, including smart wearable systems, enhances compliance and monitoring. High awareness levels among employers and employees accelerate equipment replacement and upgrades, solidifying Europe’s position as a key market for fall protection solutions.
Asia Pacific
Asia Pacific accounts for 24.7% of the fall protection market and shows the fastest growth rate. Rapid urbanization and infrastructure expansion in China, India, and Southeast Asia boost demand for protective systems. Governments are tightening safety laws, increasing adoption in construction and manufacturing sectors. The region also benefits from rising foreign investments in industrial projects. Local manufacturers offer cost-effective equipment, expanding accessibility across small and medium enterprises. Ongoing technology adoption, combined with improving safety culture, strengthens Asia Pacific’s role as a key growth engine for this market.
Latin America
Latin America represents 5.2% of the fall protection market. The region is gradually increasing adoption due to growing construction activity and mining operations. Countries like Brazil and Mexico are enforcing stricter occupational safety standards, driving demand for harnesses and anchorage systems. International companies are expanding their presence to meet rising safety awareness. Limited budget allocation in smaller firms still affects full-scale adoption. However, increasing government initiatives and foreign investments are improving compliance rates, supporting steady market growth in the region.
Middle East & Africa
The Middle East & Africa holds a 4.1% share of the fall protection market. High investments in oil and gas, energy, and infrastructure projects drive demand for protective systems. Countries like Saudi Arabia and the UAE are integrating stricter safety protocols in industrial projects. Modernization initiatives and mega construction programs, including smart city developments, support market expansion. Limited awareness and lower enforcement in parts of Africa remain challenges. However, gradual regulatory reforms and training programs are expected to enhance adoption across the region over time.
Market Segmentations:
By Solutions:
- Products
- Services
By Type:
- Galvanic
- Impressed current
By Application:
- Pipeline
- Storage facilities
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Competitive Landscape
The fall protection market is shaped by key players such as Pure Safety Group (PSD), MSA Safety Company, Honeywell Miller, Guardian Industries, Mallcom India Limited, French Creek Production, KARAM, GF Protection Canada, Capital Safety, and 3M. The fall protection market is becoming increasingly competitive as companies prioritize innovation, safety compliance, and cost efficiency. Rising demand for connected safety solutions and ergonomic designs drives product development. Manufacturers focus on integrating smart sensors, IoT capabilities, and advanced materials to enhance worker protection and mobility. Global expansion strategies, including partnerships and acquisitions, strengthen market reach and supply chain efficiency. Regulatory pressure and growing awareness of workplace safety push companies to adopt continuous product upgrades. This competitive environment encourages consistent technological advancement, faster product launches, and wider availability across industries and regions.
Key Player Analysis
- Pure Safety Group (PSD)
- MSA Safety Company
- Honeywell Miller
- Guardian Industries
- Mallcom India Limited
- French Creek Production
- KARAM
- GF Protection Canada
- Capital Safety
- 3M
Recent Developments
- In March 2025, SureWerx has announced the acquisition of Reliance Fall Protection Equipment to enhance its portfolio of engineered fall safety solutions. This move adds products like Skyloc® II, MicroLoc®, and Enviroshield™ systems to SureWerx’s offerings.
- In July 2024, Gamgee BV has introduced a new fall detection system for seniors that operates through Wi-Fi, without relying on wearable devices or cameras. It instantly alerts caregivers and family members in the event of a fall. The system also tracks daily movement to provide insights into overall well-being.
- In January 2024, WenerCo introduced a groundbreaking fall protection equipment utility lifeline tailored for utility workers and linemen that provides them with an elevated level of climbing security. This innovative offering includes an anchor strap fall arrest system, which is specifically designed to meet the unique safety requirements of professionals working on utility poles or similar structures.
- In September 2023, ADAMA Ltd., one of the leading crop protection companies, announced the launch of its all-new crop protection products in India. These new products are called Cosayr and Lapidos. These are the first-ever insecticides that are said to contain the active ingredient Chlorantraniliprole (CTPR)
Report Coverage
The research report offers an in-depth analysis based on Solutions, Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for advanced fall protection systems will increase with stricter safety regulations.
- Smart wearable technologies will enhance real-time monitoring and safety compliance.
- Construction and infrastructure projects will continue driving market expansion.
- Integration of IoT and AI will improve predictive safety management.
- Retrofit solutions will gain traction in aging industrial facilities.
- Training and awareness programs will boost equipment adoption in developing regions.
- Manufacturers will focus on ergonomic and lightweight designs to improve worker comfort.
- Global partnerships will strengthen supply chains and distribution networks.
- Sustainability goals will drive the development of eco-friendly protective materials.
- Automation and digitalization will enhance overall workplace safety efficiency.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Fall Protection Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Fall Protection Market projected to grow between 2025 and 2032?
Which Fall Protection Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Fall Protection Market?
Who are the leading companies in the Fall Protection Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.19 billion → 2032: USD 5.26 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fall Protection Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fall Protection Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fall Protection Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fall Protection Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fall Protection Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fall Protection Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fall Protection Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fall Protection Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.19 billion → 2032: USD 5.26 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fall Protection Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fall Protection Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Fall Protection Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Fall Protection Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

