
Market Overview
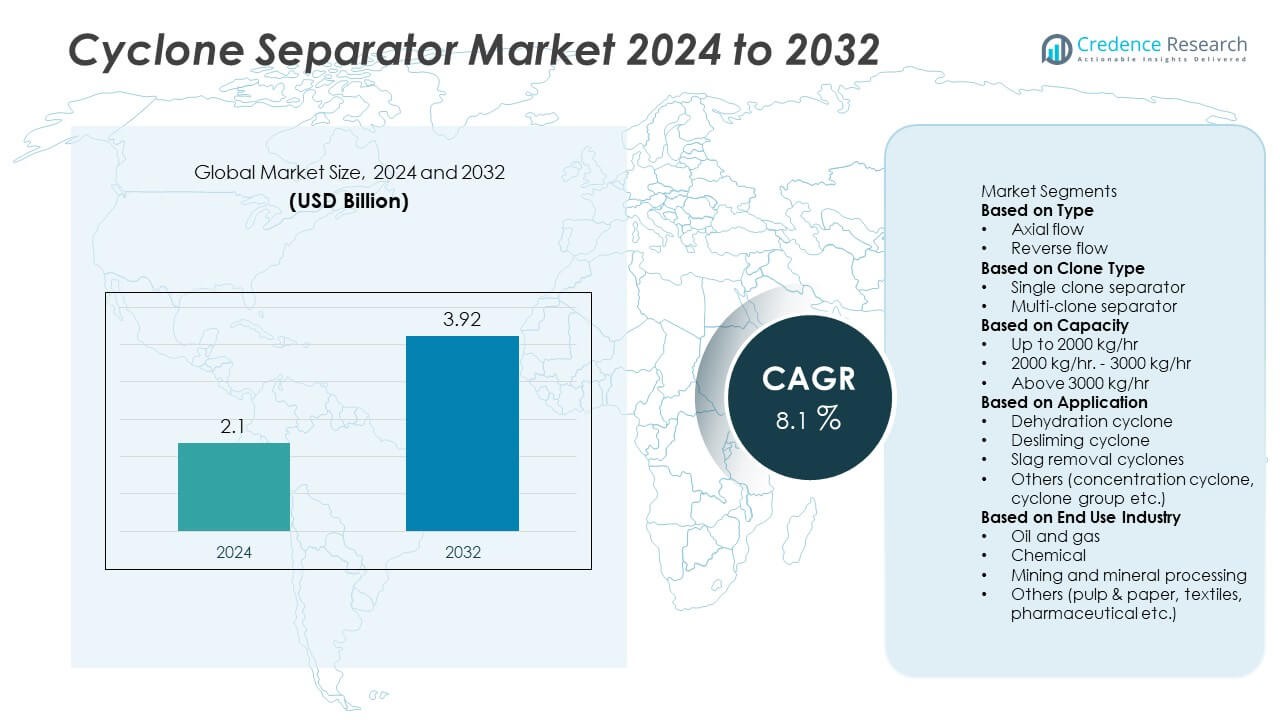
The Cyclone Separator market size was valued at USD 2.1 billion in 2024 and is anticipated to reach USD 3.92 billion by 2032, growing at a CAGR of 8.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cyclone Separator market Size 2024 | USD 2.1 Billion |
| Cyclone Separator market, CAGR | 8.1% |
| Cyclone Separator market Size 2032 | USD 3.92 Billion |
The Cyclone Separator market is led by major players including FLSmidth, Cyclotech, Gulf Coast Air & Hydraulics, Haiwang Hydrocyclone, Elgin Separation Solutions, Cyclone Separator Australia, Air Dynamics, Exterran Corporation, KREBS, and Cyclone Engineering Projects. These companies dominate the market through advancements in separation efficiency, durable construction materials, and integrated dust control systems. North America emerged as the leading region in 2024 with a 34% share, supported by strong adoption in oil, gas, and manufacturing industries. Europe followed with a 28% share, driven by strict emission control regulations and sustainability initiatives, while Asia-Pacific held 27%, fueled by rapid industrial expansion and modernization of process industries.
Market Insights
- The Cyclone Separator market was valued at USD 2.1 billion in 2024 and is projected to reach USD 3.92 billion by 2032, growing at a CAGR of 8.1% during the forecast period.
- Increasing demand from process industries such as cement, chemical, and metal processing is driving market growth, supported by stricter emission regulations and expanding industrial production.
- The market is witnessing trends like advanced material usage, integration of IoT-based monitoring systems, and the growing adoption of multi-clone separators for improved efficiency.
- Key players including FLSmidth, Cyclotech, and KREBS are focusing on technological innovations, product durability, and digital performance monitoring to strengthen their global presence.
- North America leads the market with a 34% share, followed by Europe at 28% and Asia-Pacific at 27%; among product types, reverse flow separators hold a 63% share, while the 2000–3000 kg/hr capacity segment dominates with 46% of total revenue.
Market Segmentation Analysis:
By Type
The reverse flow segment dominated the Cyclone Separator market in 2024, accounting for 63% of total revenue. Reverse flow separators are widely used due to their superior dust separation efficiency, compact design, and adaptability for various industrial processes. Their ability to handle high particulate concentrations makes them preferred in cement, power generation, and metal processing industries. Axial flow separators, while less common, are gaining attention in applications demanding lower pressure drop and compact setups. The consistent performance and lower maintenance needs of reverse flow designs continue to strengthen their market position.
- For instance, FLSmidth's KREBS® gMAX® hydrocyclones utilize a patented inlet geometry to minimize turbulence, delivering finer and sharper particle separation at high capacities in wet processing applications.
By Clone Type
The multi-clone separator segment held a leading share of 58% in 2024, driven by its high efficiency and capacity to manage large dust loads. Multi-clone systems, consisting of several smaller cyclone units, provide enhanced separation with reduced pressure loss, making them ideal for large-scale industrial operations. These separators are widely used in boilers, mining, and chemical processing. Single-clone separators, though simpler in design, are favored in small to medium facilities for their cost-effectiveness. The flexibility and scalability of multi-clone separators make them the preferred choice across heavy-duty applications.
- For instance, Elgin Separation Solutions provides modular systems utilizing hydrocyclone manifolds for mining operations. These systems are designed to remove solids from slurry and can include pressure monitoring and control systems to optimize performance and reduce downtime.
By Capacity
The 2000 kg/hr to 3000 kg/hr capacity range dominated the Cyclone Separator market with a 46% share in 2024. This category offers an ideal balance between throughput and energy efficiency, catering to mid-sized industrial systems in cement, food processing, and chemical sectors. Units below 2000 kg/hr serve smaller plants and laboratory setups, while those above 3000 kg/hr are adopted in heavy-duty industries requiring high dust removal rates. The mid-capacity separators continue to gain traction due to their operational flexibility, moderate cost, and compatibility with a broad range of industrial filtration systems.
Key Growth Drivers
Rising Demand from Process Industries
The growing use of cyclone separators in cement, chemical, and metal processing industries is a major market driver. These industries rely on efficient particulate separation to meet emission standards and improve product quality. Increasing industrialization and tightening air pollution regulations further boost adoption. The ability of cyclone separators to handle high temperatures and abrasive materials makes them ideal for continuous operations. Their low maintenance requirements and cost-effectiveness enhance their appeal in heavy-duty industrial environments.
- For instance, A FLSmidth case study confirms that its KREBS gMAX® cyclones were installed at a gold mine in Ghana. The implementation was intended to improve the classification performance of the operation.
Stringent Environmental and Emission Regulations
Global environmental policies promoting cleaner industrial processes are accelerating cyclone separator demand. Industries are upgrading filtration systems to comply with air quality standards set by environmental authorities. Cyclone separators offer a reliable, mechanical dust separation method without filters, reducing maintenance and operating costs. Governments’ focus on reducing particulate emissions from manufacturing, power generation, and mining industries is fueling equipment modernization. This regulatory push encourages industries to replace conventional filtration systems with advanced cyclone-based technologies.
- For instance, China's Ultra-Low Emission (ULE) standard for coal-fired power plants, implemented in 2014, mandates specific concentration ceilings for pollutants, including particulate matter (PM), which led to a significant overall reduction in emissions across the industry.
Growing Adoption in Energy and Power Generation
The energy sector is increasingly deploying cyclone separators for flue gas cleaning and ash removal in boilers and furnaces. Power plants, especially those using coal or biomass, require efficient dust control systems to meet emission norms. Cyclone separators improve operational reliability by preventing particulate buildup in turbines and heat exchangers. Rising electricity demand and investments in clean energy projects strengthen their integration into power systems. Continuous improvements in separator design are enhancing performance under high-temperature and high-pressure conditions.
Key Trends & Opportunities
Integration of Advanced Materials and Design Optimization
Manufacturers are adopting advanced alloys and ceramic linings to enhance cyclone durability and performance. Design improvements using computational fluid dynamics (CFD) enable optimized vortex flow and higher separation efficiency. Compact, modular separator designs are gaining popularity for easier installation and maintenance. These innovations extend product lifespan and reduce operational downtime. The trend toward customized cyclone designs tailored to specific process needs presents new opportunities for equipment suppliers targeting diverse industrial applications.
- For instance, Haiwang Hydrocyclone manufactures FX Series hydrocyclones with wear-resistant liners made from materials like high-alumina ceramics, composite materials, and polyurethane.
Expansion in Renewable and Waste Management Applications
Cyclone separators are finding new uses in biomass plants, recycling facilities, and waste-to-energy systems. They effectively manage particulate emissions during combustion and material recovery processes. The transition toward sustainable energy generation is increasing equipment demand in biomass and biogas facilities. Emerging waste processing industries in developing regions also present strong growth potential. The focus on circular economy principles and stricter environmental standards further supports cyclone deployment in eco-friendly industrial operations.
- For instance, Cyclone Engineering Projects is a South African company primarily focused on mine tailings deposition, hydraulic and mechanical re-mining, and associated civil works.
Automation and IoT-Based Monitoring
The integration of automation and Internet of Things (IoT) technologies is improving cyclone separator efficiency. Smart monitoring systems provide real-time data on pressure, flow, and dust concentration, enabling predictive maintenance and energy savings. Automated control systems help optimize airflow and reduce operational costs. This trend aligns with the growing adoption of Industry 4.0 technologies across manufacturing and energy sectors. Digitalization enhances system reliability and opens opportunities for value-added service models in industrial air management.
Key Challenges
High Energy Consumption in Operations
Cyclone separators require significant energy input to generate the centrifugal force needed for particle separation. High operating costs can limit adoption, especially in small and medium industries. Maintaining consistent airflow and pressure increases power demand in large-scale systems. Energy-efficient design innovations are being pursued, but widespread implementation remains limited due to cost constraints. Balancing separation efficiency with energy consumption is a key technical challenge for manufacturers aiming to enhance product competitiveness.
Competition from Alternative Filtration Technologies
The availability of advanced filtration methods such as bag filters and electrostatic precipitators poses a competitive challenge. These alternatives often provide higher particle removal efficiency, particularly for fine dust. Industries with strict emission targets sometimes prefer these systems despite higher maintenance needs. To stay competitive, cyclone manufacturers are focusing on hybrid systems combining mechanical and electrostatic mechanisms. However, continuous performance optimization is required to maintain the relevance of cyclone separators in evolving industrial applications.
Regional Analysis
North America
North America held a 34% share of the Cyclone Separator market in 2024, driven by strong demand from oil and gas, chemical, and power generation industries. The region’s strict air quality regulations and growing focus on emission control technologies are major contributors to adoption. The United States leads the market with high investment in industrial automation and retrofitting of dust collection systems. Canada’s mining and energy sectors further support demand for durable separators capable of handling high particulate loads. Ongoing advancements in sustainable industrial operations are expected to reinforce steady regional growth.
Europe
Europe accounted for a 28% share of the Cyclone Separator market in 2024, supported by stringent environmental regulations and a growing emphasis on cleaner manufacturing. Countries such as Germany, France, and the United Kingdom are investing in high-efficiency separation systems to comply with EU emission norms. Industrial applications in cement, metal processing, and food manufacturing continue to drive steady adoption. The region also benefits from advanced engineering capabilities and adoption of smart monitoring systems. Rising demand for energy-efficient equipment and sustainability-driven upgrades across European industries further stimulate market expansion.
Asia-Pacific
Asia-Pacific captured a 27% share of the Cyclone Separator market in 2024, making it one of the fastest-growing regions. Rapid industrialization in China, India, and Japan, coupled with expanding manufacturing and mining activities, drives strong demand. Government initiatives to control industrial pollution and modernize processing plants further boost equipment adoption. Local manufacturers are offering affordable, high-capacity cyclone systems suited for regional needs. Continuous infrastructure investment and the development of new power plants are key growth drivers. The shift toward cleaner technologies and regional emission compliance policies strengthen long-term market prospects.
Latin America
Latin America held an 7% share of the Cyclone Separator market in 2024, supported by expanding mining, cement, and chemical industries. Brazil and Mexico are leading markets with increased industrial activity and environmental awareness. The demand for durable, low-maintenance separators is rising as industries modernize dust collection systems. Regional governments are enforcing stricter pollution norms, encouraging the replacement of traditional filters with cyclone-based solutions. However, limited access to advanced manufacturing technologies and higher equipment costs remain challenges. Growing industrial automation and renewable energy projects are expected to support moderate growth ahead.
Middle East & Africa
The Middle East and Africa accounted for a 4% share of the Cyclone Separator market in 2024. The region’s demand is primarily driven by oil refining, construction materials, and power generation sectors. The Gulf countries are investing in industrial filtration and emission control systems as part of broader sustainability goals. South Africa contributes to growth through its strong mining and metal processing industries. Infrastructure expansion and energy diversification projects are creating new opportunities. Although technology adoption is still developing, rising environmental regulation and industrial modernization efforts are set to enhance future market growth.
Market Segmentations:
By Type
- Axial flow
- Reverse flow
By Clone Type
- Single clone separator
- Multi-clone separator
By Capacity
- Up to 2000 kg/hr
- 2000 kg/hr. - 3000 kg/hr
- Above 3000 kg/hr
By Application
- Dehydration cyclone
- Desliming cyclone
- Slag removal cyclones
- Others (concentration cyclone, cyclone group etc.)
By End Use Industry
- Oil and gas
- Chemical
- Mining and mineral processing
- Others (pulp & paper, textiles, pharmaceutical etc.)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Cyclone Separator market features key players such as FLSmidth, Cyclotech, Gulf Coast Air & Hydraulics, Haiwang Hydrocyclone, Elgin Separation Solutions, Cyclone Separator Australia, Air Dynamics, Exterran Corporation, KREBS, and Cyclone Engineering Projects. These companies compete through innovations in design efficiency, material durability, and system integration to meet industrial air quality and process optimization needs. Manufacturers are focusing on developing compact, energy-efficient separators with enhanced particle removal capabilities for demanding sectors like mining, cement, and chemical processing. Strategic partnerships, mergers, and technology licensing agreements are helping expand global reach and service portfolios. Many players are investing in advanced computational fluid dynamics (CFD) modeling and IoT-enabled performance monitoring to improve reliability and reduce maintenance costs. Continuous R&D efforts, regional expansion, and a shift toward sustainable and automated separation solutions remain central to maintaining competitiveness in this evolving industrial filtration market.
Key Player Analysis
- FLSmidth
- Cyclotech
- Gulf Coast Air & Hydraulics
- Haiwang Hydrocyclone
- Elgin Separation Solutions
- Cyclone Separator Australia
- Air Dynamics
- Exterran Corporation
- KREBS
- Cyclone Engineering Projects
Recent Developments
- In July 2025, Sulzer formed a strategic alliance with Avalon Energy Group to deploy BioFlux technology in sustainable aviation fuel (SAF) production. Auckland Energy Group will initially deploy the technology with biofuel plants in Uruguay with plans to expand to India, Eswatini, and the US.
- In June 2025, Haiwang said its hydrocyclone equipment was operating at Ecuador’s Mirador copper project, supporting plant performance.
- In May 2025, Sulzer Partners with Emirates Biotech. Sulzer signed a contract to bill proprietary equipment for the world’s largest PLA bioplastics production facility in the UAE.
- In February 2025, FLSmidth announced a major iron-ore order that includes KREBS pumps and cyclones as part of a full beneficiation package.
Report Coverage
The research report offers an in-depth analysis based on Type, Clone Type, Capacity, Application, End Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for cyclone separators will rise as industries prioritize cleaner production and emission control.
- Manufacturers will focus on developing energy-efficient designs with reduced pressure loss.
- Integration of IoT and automation will enhance real-time monitoring and maintenance efficiency.
- Advanced materials such as ceramics and composites will improve durability and performance.
- Growing adoption in renewable energy and waste-to-energy plants will create new opportunities.
- Emerging economies will experience strong market growth due to rapid industrialization.
- Custom-built separators for niche applications will gain higher market traction.
- Partnerships between technology providers and industrial operators will expand innovation capacity.
- Environmental regulations will continue to push industries toward modern separation systems.
- Continuous R&D in design optimization and CFD modeling will drive next-generation cyclone technologies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Cyclone Separator market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cyclone Separator market projected to grow between 2025 and 2032?
Which Cyclone Separator market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cyclone Separator market?
Who are the leading companies in the Cyclone Separator market?
Which region commanded the largest share of the Cyclone Separator market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.1 billion → 2032: USD 3.92 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cyclone Separator Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cyclone Separator Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cyclone Separator Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cyclone Separator Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cyclone Separator Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cyclone Separator Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cyclone Separator Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cyclone Separator Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.1 billion → 2032: USD 3.92 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cyclone Separator Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cyclone Separator Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cyclone Separator Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cyclone Separator Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

