
Market Overview:
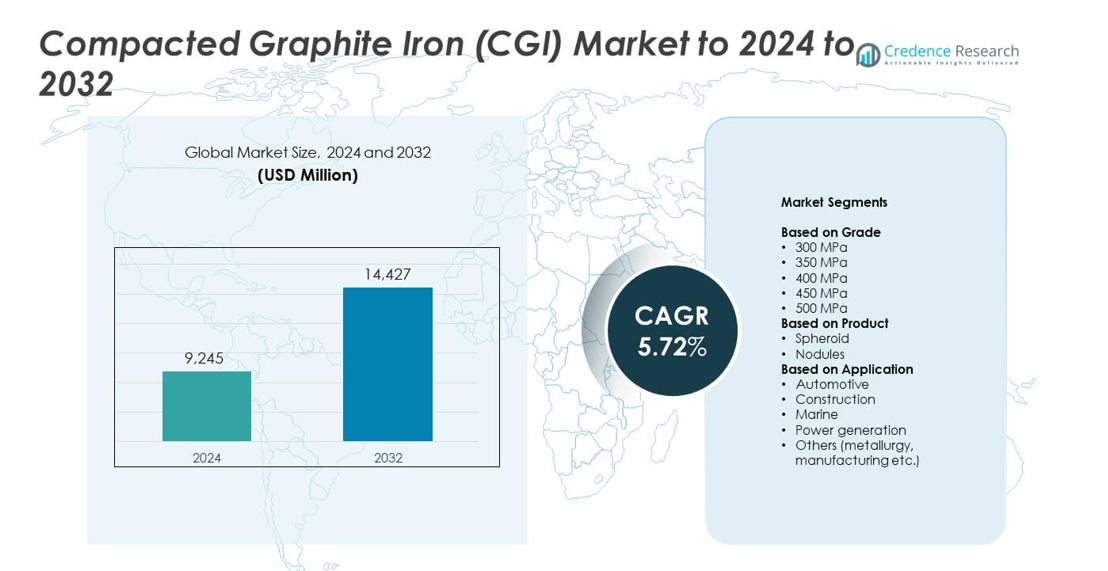
Compacted Graphite Iron (CGI) Market size was valued USD 9,245 million in 2024 and is anticipated to reach USD 14,427 million by 2032, at a CAGR of 5.72% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Compacted Graphite Iron (CGI) Market Size 2024 | USD 9,245 million |
| Compacted Graphite Iron (CGI) Market, CAGR | 5.72% |
| Compacted Graphite Iron (CGI) Market Size 2032 | USD 14,427 million |
The compacted graphite iron (CGI) market is led by major players such as Tupy SA, Fritz Winter Eisenwerk GmbH, Waupaca Foundry, and Sintercast AB, which collectively hold a significant share of global production. These companies focus on advanced casting technologies, sustainability, and strategic collaborations with automotive OEMs to enhance product performance and efficiency. Asia-Pacific emerged as the leading region in 2024, accounting for 34.8% of the total market share, driven by robust automotive manufacturing and expanding power generation industries in China, Japan, and India. Europe followed with a 29.1% share, supported by stringent emission norms and strong adoption of high-strength materials across vehicle and machinery applications.
Market Insights
- The compacted graphite iron market was valued at USD 9,245 million in 2024 and is expected to reach USD 14,427 million by 2032, growing at a CAGR of 5.72%.
- The market is driven by rising demand from the automotive sector, particularly for lightweight and high-strength engine components that improve fuel efficiency and reduce emissions.
- Advancements in metallurgical control and casting technology are enhancing product consistency, leading to wider CGI applications in heavy machinery and power generation.
- The competitive landscape is moderately consolidated, with global manufacturers focusing on R&D, process automation, and sustainable production practices to strengthen market presence.
- Asia-Pacific dominated with a 34.8% share in 2024, followed by Europe at 29.1% and North America at 27.4%, driven by strong automotive, industrial, and energy sector growth.
Market Segmentation Analysis:
By Grade
The 400 MPa segment dominated the compacted graphite iron market with a 34.6% share in 2024. This grade is widely used in automotive engine blocks, cylinder heads, and heavy machinery components due to its balance of tensile strength, thermal conductivity, and machinability. Its durability supports high-performance engines under extreme temperatures and pressure. The rising demand for lightweight yet strong materials in vehicle manufacturing continues to drive the use of 400 MPa CGI. Growing production of commercial vehicles further strengthens the segment’s leadership in global applications.
- For instance, SinterCast reports CGI delivers at least 75% higher tensile strength and 45% higher stiffness than gray iron, supporting ~400 MPa class engine blocks in series production.
By Product
The nodules segment held the largest share of 59.2% in 2024. Its dominance is driven by the superior strength and elasticity that nodular structures provide, enhancing performance under cyclic stress and vibration. Nodular CGI products are preferred in diesel and gasoline engine parts due to better fatigue resistance compared to spheroid forms. Increasing engine downsizing trends and the shift toward higher power densities in automotive design are fueling demand for nodular CGI. This structure also offers improved casting properties, enabling cost-efficient production for mass manufacturing.
- For instance, Impro Precision produces CGI sand-cast components weighing 40–300 kg and consistently achieves over 90% vermicular graphite, matching nodular performance needs.
By Application
The automotive segment led the compacted graphite iron market with a 67.8% share in 2024. CGI’s high stiffness, thermal fatigue resistance, and reduced weight make it ideal for engine blocks, exhaust manifolds, and brake components. The material enables improved fuel efficiency and lower CO₂ emissions, aligning with stringent emission norms in Europe and North America. Rapid electrification and hybrid vehicle manufacturing are further promoting CGI adoption in motor housings and structural parts. Expanding production by global OEMs across China and Germany continues to reinforce automotive sector dominance.
Key Growth Drivers
Rising Adoption in Automotive Engine Manufacturing
The growing use of compacted graphite iron in engine blocks and cylinder heads is a major driver of market growth. Automakers favor CGI for its high strength, thermal resistance, and lightweight properties, improving fuel efficiency and engine durability. Its compatibility with both diesel and gasoline engines supports its integration in hybrid and internal combustion vehicles. Increasing demand for efficient, low-emission engines is further accelerating its adoption across the automotive sector.
- For instance, Ford’s 6.7 L PowerStroke diesel with a CGI block reached 400 hp and 1,085 Nm after a software update, underscoring durability for higher outputs.
Expanding Use in Power Generation Equipment
The power generation industry is increasingly utilizing compacted graphite iron for turbine housings, engine components, and heat exchangers. Its ability to handle high pressure and temperature while maintaining structural integrity enhances operational reliability. As global power demand rises, especially in developing economies, the use of CGI components is expanding in both conventional and renewable power plants. This material’s long service life and low maintenance needs strengthen its role in energy infrastructure.
- For instance, Rolls-Royce Power Systems cast CGI engine frames weighing 9–17 tons, demonstrating thermal-fatigue resistance for heavy-duty power units.
Growth in Heavy Machinery and Construction Equipment
Heavy-duty machinery and construction equipment manufacturers are adopting CGI for components that require enhanced fatigue strength and vibration resistance. Its performance in load-bearing applications such as engine blocks, crankcases, and structural supports ensures longer lifespan and reduced downtime. The ongoing expansion of infrastructure projects and industrialization in Asia-Pacific further drives demand. CGI’s superior mechanical characteristics compared to gray iron make it a preferred choice for high-stress applications in construction machinery.
Key Trends & Opportunities
Shift Toward Lightweight and Sustainable Materials
The global focus on sustainability and fuel efficiency is encouraging manufacturers to use CGI as a substitute for heavier metals. Its lighter weight without compromising strength supports carbon reduction initiatives in transportation and industrial sectors. The combination of recyclability and reduced energy consumption in production enhances its environmental appeal. These factors position CGI as a vital material for future green manufacturing trends across industries.
- For instance, Audi’s CGI diesel blocks achieved about a 10% weight reduction versus conventional cast iron while maintaining strength for efficiency gains.
Integration of Advanced Casting Technologies
The adoption of advanced casting and metallurgical control technologies is improving the consistency and mechanical performance of CGI. Automation and real-time process monitoring are enabling higher precision in production. Manufacturers are investing in digital foundry systems and thermal management techniques to enhance yield and reduce defects. These technological advances are opening new opportunities for high-performance CGI components in automotive and industrial sectors.
- For instance, Tupy has demonstrated the capability to produce Compacted Graphite Iron (CGI) engine blocks with a production cylinder-block nominal wall thickness of 3.5 mm, but has also achieved a minimum wall thickness of 2.5 mm in high-volume series production for specific gasoline V6 engines (e.g., Ford Nano V6 engine program).
Expansion in Electric Vehicle Applications
The transition toward electric vehicles presents new opportunities for CGI in motor housings, battery casings, and structural frames. Its thermal conductivity and strength make it suitable for managing heat and mechanical stress in EV systems. Automakers are exploring CGI to optimize efficiency while maintaining durability. The growing EV production in China, the U.S., and Europe is expected to expand its market scope over the coming years.
Key Challenges
High Production and Processing Costs
Producing compacted graphite iron requires precise metallurgical control and specialized equipment, leading to higher manufacturing costs. The complexity of maintaining graphite morphology adds to process expenses compared to gray iron. Smaller foundries face challenges in scaling CGI production economically. These factors limit widespread adoption, particularly in cost-sensitive industries, affecting market penetration in developing regions.
Limited Awareness and Technical Expertise
The market faces a shortage of technical know-how regarding CGI processing and applications. Many manufacturers lack the specialized training required to maintain production consistency and quality standards. This knowledge gap restricts wider utilization across smaller enterprises. Developing global training programs and industry collaborations remains essential to support the long-term growth and industrial acceptance of CGI materials.
Regional Analysis
North America
North America held a 27.4% share of the compacted graphite iron market in 2024. The region’s dominance is driven by strong automotive production in the United States and Canada, particularly in heavy-duty and light commercial vehicles. Major manufacturers are integrating CGI into high-performance engines to enhance fuel efficiency and reduce emissions. The presence of advanced foundry infrastructure and R&D investments further support market growth. Rising demand for durable materials in power generation and industrial machinery applications also strengthens CGI adoption across North American industries.
Europe
Europe accounted for a 29.1% share of the compacted graphite iron market in 2024. The region benefits from a well-established automotive industry, led by Germany, France, and Italy, focusing on lightweight and high-strength materials. Strict emission regulations are driving manufacturers to adopt CGI for efficient and low-emission engine components. European foundries are investing in advanced metallurgical processes to improve product quality and reduce carbon footprints. The demand for CGI in renewable energy and marine applications continues to expand, supported by technological innovation and sustainability-focused manufacturing initiatives.
Asia-Pacific
Asia-Pacific dominated the compacted graphite iron market with a 34.8% share in 2024. Rapid industrialization and strong automotive production in China, Japan, India, and South Korea drive market expansion. The region’s growing power generation and construction equipment sectors further boost demand for CGI components. Local foundries are increasingly adopting advanced casting technologies to enhance production efficiency and quality. Expanding investments in electric vehicle manufacturing and industrial machinery create additional growth opportunities. Favorable government initiatives supporting manufacturing modernization continue to strengthen Asia-Pacific’s leadership in the global CGI market.
Latin America
Latin America captured a 5.7% share of the compacted graphite iron market in 2024. The region’s growth is supported by rising automotive manufacturing in Brazil and Mexico, along with the expansion of mining and construction sectors. Increasing infrastructure development and industrial activities are driving demand for durable materials like CGI. Although regional production capabilities remain limited, collaborations with international foundries are enhancing local expertise. Growing adoption of lightweight materials for vehicle engines and powertrain components further supports market development across Latin America’s emerging economies.
Middle East & Africa
The Middle East & Africa region held a 3.0% share of the compacted graphite iron market in 2024. The demand is primarily driven by investments in power generation, oil and gas, and construction industries. Rising industrialization in Gulf countries and infrastructure projects across Africa are creating opportunities for CGI applications in heavy machinery and energy systems. Limited local foundry capacity remains a challenge, but regional modernization programs are promoting industrial material innovation. Partnerships with global manufacturers are helping improve technical capabilities and accelerate the adoption of CGI in key sectors.
Market Segmentations:
By Grade
- 300 MPa
- 350 MPa
- 400 MPa
- 450 MPa
- 500 MPa
By Product
- Spheroid
- Nodules
By Application
- Automotive
- Construction
- Marine
- Power generation
- Others (metallurgy, manufacturing etc.)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The compacted graphite iron market features a moderately consolidated competitive landscape, with key participants including Tupy SA, Fritz Winter Eisenwerk GmbH, Saguenay Foundry, Silbitz Group, Durham Foundry, Waupaca Foundry, Sintercast AB, ASI International, Ltd., Teksid Iron, and Eisengiesserei Baumgarte GmbH. The competition is driven by advancements in casting technologies, material innovation, and process automation. Manufacturers are focusing on enhancing mechanical strength, thermal performance, and lightweight properties to meet the growing needs of automotive and industrial sectors. Strategic collaborations with OEMs and foundry expansions are strengthening global production capabilities. Companies are investing in energy-efficient processes and recycling techniques to align with environmental regulations. The integration of digital foundry solutions, such as real-time quality monitoring and predictive analytics, is improving production consistency and cost efficiency. Continuous R&D investment and technological differentiation remain critical to maintaining market share and addressing rising demand for high-performance CGI components.
Key Player Analysis
- Tupy SA
- Fritz Winter Eisenwerk GmbH
- Saguenay Foundry
- Silbitz Group
- Durham Foundry
- Waupaca Foundry
- Sintercast AB
- ASI International, Ltd.
- Teksid Iron
- Eisengiesserei Baumgarte GmbH
Recent Developments
- In February 2025, Saroj Group in India became the first SinterCast licensee in India, planning CGI cylinder head production.
- In 2024, Tupy announced it would expand its Compacted Graphite Iron (CGI) production in Mexico to meet rising demand from the heavy-duty commercial vehicle sectors in Europe and North America.
- In 2024, Fritz Winter Eisenwerk GmbH & Co. KG Continued to leverage advancements in CGI production with enhanced properties, improved production processes, and expanded applications, driving the market through high-performance materials demand.
Report Coverage
The research report offers an in-depth analysis based on Grade, Product, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The global compacted graphite iron market will continue expanding due to increasing automotive and industrial demand.
- Engine downsizing trends will drive wider adoption of CGI for lightweight yet durable components.
- Growth in electric and hybrid vehicles will create new applications for CGI in motor housings and casings.
- Advanced casting and metallurgical innovations will improve manufacturing efficiency and quality consistency.
- Rising infrastructure development will boost the use of CGI in heavy machinery and construction equipment.
- Power generation projects will continue adopting CGI for high-temperature and high-pressure engine components.
- Stringent emission regulations will encourage automakers to integrate CGI in low-emission and efficient engines.
- Expansion of foundry capacities in Asia-Pacific will strengthen regional dominance and supply stability.
- Increased collaboration between manufacturers and research institutions will enhance process optimization and material innovation.
- Sustainability goals and circular economy initiatives will accelerate the transition toward recyclable and energy-efficient CGI products.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Compacted Graphite Iron (CGI) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Compacted Graphite Iron (CGI) Market projected to grow between 2025 and 2032?
hich Compacted Graphite Iron (CGI) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Compacted Graphite Iron (CGI) Market?
Who are the leading companies in the Compacted Graphite Iron (CGI) Market?
Which region commanded the largest share of the Compacted Graphite Iron (CGI) Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Compacted Graphite Iron (CGI) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Compacted Graphite Iron (CGI) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9,245 million → 2032: USD 14,427 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Compacted Graphite Iron (CGI) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Compacted Graphite Iron (CGI) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Compacted Graphite Iron (CGI) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Compacted Graphite Iron (CGI) Market Drivers
- 3.3 Compacted Graphite Iron (CGI) Market Restraints & Challenges
- 3.4 Compacted Graphite Iron (CGI) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Compacted Graphite Iron (CGI) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Compacted Graphite Iron (CGI) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Compacted Graphite Iron (CGI) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Compacted Graphite Iron (CGI) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Compacted Graphite Iron (CGI) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Compacted Graphite Iron (CGI) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Compacted Graphite Iron (CGI) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Compacted Graphite Iron (CGI) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Compacted Graphite Iron (CGI) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Compacted Graphite Iron (CGI) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Compacted Graphite Iron (CGI) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Compacted Graphite Iron (CGI) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Compacted Graphite Iron (CGI) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Compacted Graphite Iron (CGI) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Compacted Graphite Iron (CGI) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Compacted Graphite Iron (CGI) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Compacted Graphite Iron (CGI) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Compacted Graphite Iron (CGI) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Compacted Graphite Iron (CGI) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
