
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Confidential Computing Market Size 2024 | USD 13,305 million |
| Confidential Computing Market, CAGR | 46.20% |
| Confidential Computing Market Size 2032 | USD 277,711.9 million |
Market Overview
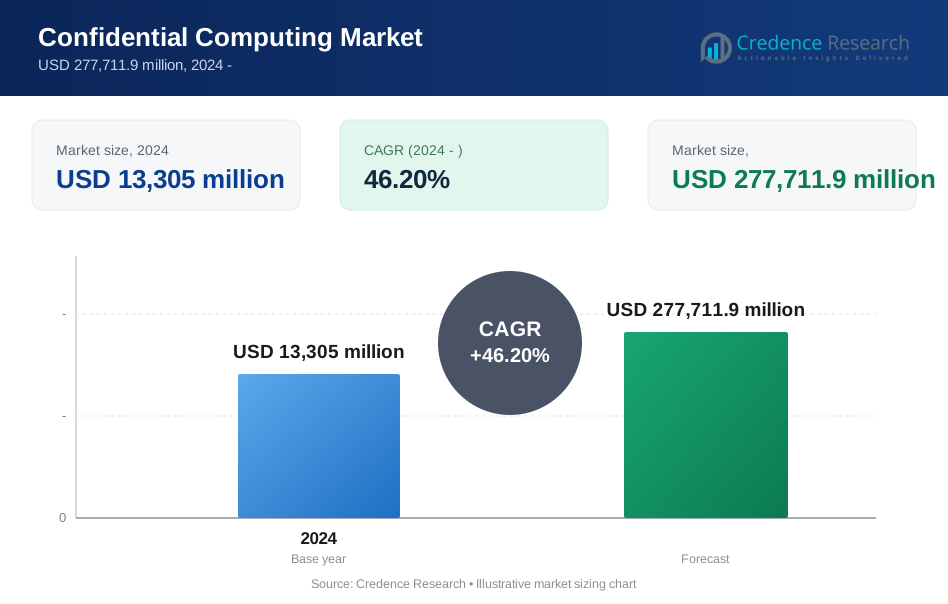
The confidential computing market is projected to grow from USD 13,305 million in 2024 to USD 277,711.9 million by 2032, registering a robust CAGR of 46.20% during the forecast period.
The confidential computing market is witnessing rapid growth driven by escalating concerns over data privacy, increased cyber threats, and stricter regulatory requirements across industries. As enterprises migrate sensitive workloads to cloud environments, the need for secure data processing has surged, prompting the adoption of hardware-based trusted execution environments (TEEs). Organizations in sectors like finance, healthcare, and government are especially prioritizing confidential computing to safeguard sensitive transactions, health records, and intellectual property. The rise of AI, edge computing, and multi-party data collaboration further amplifies the demand for secure data sharing and processing. Key industry players are forming strategic alliances to integrate confidential computing with AI/ML workflows, enabling privacy-preserving analytics. Meanwhile, advancements in processor-level encryption, supported by chipmakers such as Intel, AMD, and ARM, are accelerating mainstream deployment. The market is also benefiting from initiatives by cloud service providers to offer confidential computing services natively, helping businesses ensure compliance, build user trust, and maintain data integrity in real time.
The confidential computing market shows strong geographic diversification, with North America leading at 41% market share due to early technology adoption and robust cloud infrastructure. Europe holds 27%, driven by strict data privacy regulations and sovereign cloud initiatives, while Asia-Pacific commands 22%, fueled by rapid digitalization and expanding data protection laws in countries like China, India, and Japan. North America and Europe benefit from mature enterprise IT ecosystems, whereas Asia-Pacific presents high growth potential. Key players driving global adoption include Intel Corporation, Advanced Micro Devices, Inc., Arm Limited, Microsoft, Google, IBM, Amazon Web Services, Alibaba Cloud, and Fortanix. Specialized security vendors such as Anjuna Security Inc. and DECENTRIQ are expanding their footprint through partnerships and platform innovation. These companies are shaping the market through advancements in hardware-based security, cloud-native services, and confidential AI solutions across multiple industries and regions.
Market Insights
- The confidential computing market is projected to grow from USD 13,305 million in 2024 to USD 277,711.9 million by 2032, registering a strong CAGR of 46.20%.
- Growing concerns over data privacy, regulatory mandates like GDPR and HIPAA, and rising cyber threats are accelerating enterprise adoption across industries.
- The shift to cloud and edge environments is driving demand for secure data-in-use solutions, with providers like Microsoft Azure, AWS, and Google Cloud offering confidential computing services.
- Integration with AI and federated learning is expanding use cases, especially in finance and healthcare, where secure collaboration on sensitive data is essential.
- Key challenges include high integration complexity, legacy system compatibility issues, and limited enterprise awareness, particularly among mid-sized organizations.
- North America leads the market with 41% share, followed by Europe at 27% and Asia-Pacific at 22%, driven by regulatory strength, digitalization, and cloud infrastructure investments.
- Key players include Intel, AMD, Arm, Microsoft, IBM, Google, AWS, Alibaba Cloud, Fortanix, DECENTRIQ, and Anjuna Security, who are shaping the market through innovation and ecosystem expansion.
Market Drivers
Surging Demand for Data Privacy and Regulatory Compliance
The confidential computing market is gaining momentum due to the global rise in data privacy concerns and increasingly stringent regulatory frameworks. Governments and regulatory bodies are enforcing laws like GDPR, HIPAA, and CCPA, which compel organizations to secure sensitive data throughout its lifecycle. Confidential computing enables secure processing of encrypted data in memory, which ensures compliance without sacrificing performance. Enterprises are adopting it to avoid legal repercussions and maintain customer trust. Regulatory pressure is pushing companies to invest in confidential computing technologies across critical infrastructure sectors. This shift is creating strong momentum and widespread awareness among security-conscious industries.
For instance, Intel’s Software Guard Extensions (SGX) technology is used by global banks to run fraud detection algorithms inside hardware-protected enclaves, securing customer financial data during processing and meeting regulatory requirements.
Expansion of Cloud Computing and Edge Infrastructure
The confidential computing market benefits significantly from the growing dependence on cloud and edge computing solutions. Enterprises are shifting from on-premise data centers to public and hybrid cloud models, which increases exposure to security risks during data processing. Confidential computing provides a secure environment that isolates and protects data in use, a critical capability for cloud-native applications. Cloud providers like Microsoft Azure, AWS, and Google Cloud have launched confidential virtual machines to meet enterprise security requirements. The adoption of edge devices in IoT, smart cities, and autonomous systems adds complexity, making secure data processing a priority.
- For instance, Google Cloud’s Confidential VMs, which encrypt data in use and enable enterprises to run sensitive workloads securely in the cloud by keeping the data encrypted throughout the computation process.
Rising Threat of Cyberattacks and Intellectual Property Theft
The confidential computing market is responding to a sharp increase in cyberattacks, ransomware incidents, and state-sponsored hacking. Sensitive business data, trade secrets, and IP assets are frequently targeted, especially in sectors such as finance, defense, and pharmaceuticals. Traditional security approaches focus on data at rest or in transit, leaving data in use vulnerable to breaches. Confidential computing solves this gap by creating hardware-based, isolated execution environments. It enhances endpoint security and defends against insider threats and memory-based attacks. Organizations are prioritizing these capabilities to reduce operational risk and improve incident response strategies.
Accelerated Integration with AI, Machine Learning, and Analytics
The confidential computing market is growing alongside the adoption of AI, machine learning, and big data analytics. Organizations need to process vast volumes of sensitive information for insights while protecting confidentiality. Confidential computing enables privacy-preserving computations, which are essential for secure collaboration and federated learning models. Sectors like healthcare and financial services use it to share encrypted datasets without revealing raw data. This promotes innovation while maintaining privacy and compliance. Technology leaders are integrating confidential computing into AI workflows to support ethical, secure data-driven decision-making at scale.
Market Trends
Growing Adoption by Major Cloud Service Providers
The confidential computing market is seeing strong traction from cloud hyperscalers integrating secure enclaves into their infrastructure. Providers such as Microsoft Azure, Amazon Web Services (AWS), and Google Cloud are offering confidential VMs and containers to enterprise customers. These services allow encrypted data to remain protected while in use, enabling secure multi-tenant cloud environments. Enterprises now expect built-in hardware-level security rather than bolt-on solutions. Cloud-native security offerings are shifting from optional add-ons to standard practice. This trend reinforces confidential computing as a critical feature in modern cloud architecture.
- For instance, AWS, which supports confidential computing with Nitro Enclaves, enabling customers to isolate sensitive data processing in secure, hardware-backed environments, though specific deployment numbers are not publicly disclosed.
Increased Integration with AI and Federated Learning Models
The confidential computing market is advancing through its alignment with AI and machine learning workflows. Organizations use AI to process highly sensitive data sets, including healthcare records, financial transactions, and behavioral analytics. Confidential computing enables secure model training and inference without exposing underlying data, which is essential in privacy-sensitive use cases. Federated learning models particularly benefit from this capability by enabling decentralized data collaboration. Enterprises are turning to privacy-enhancing technologies to balance innovation with data protection. This intersection of AI and security is reshaping expectations for responsible AI development.
Proliferation of Industry-Specific Use Cases
The confidential computing market is diversifying with tailored applications across sectors like finance, healthcare, government, and manufacturing. Financial institutions use secure enclaves to protect transactional data and encryption keys during computation. Healthcare providers apply it to safeguard patient data in diagnostic algorithms. Government agencies deploy confidential computing for intelligence sharing and secure workload isolation. Use cases are expanding to include secure DevOps pipelines, blockchain, and digital identity management. This sector-specific demand reflects a shift toward contextualized security solutions. It encourages vendor specialization and cross-sector innovation.
- For instance, Swiss Re partnered with Decentriq to run confidential analytics in the cloud, protecting sensitive risk models and client data from unauthorized access, even within cloud environments.
Standardization Efforts and Ecosystem Collaboration
The confidential computing market is maturing through industry-wide collaboration and emerging standards. Organizations such as the Confidential Computing Consortium (CCC) are driving interoperability and best practices across vendors and platforms. These initiatives help align hardware providers, software developers, and cloud service operators toward shared security goals. Standards facilitate wider adoption by reducing integration friction and ensuring compatibility. Open-source tools and SDKs are accelerating developer access to confidential computing capabilities. This trend reflects a growing commitment to transparency and security assurance. Collaborative efforts are helping build a scalable and trusted ecosystem.
Market Challenges Analysis
Complexity of Implementation and Integration with Legacy Systems
The confidential computing market faces a significant hurdle in the form of implementation complexity. Many organizations operate legacy systems that are not designed to support trusted execution environments or hardware-based encryption features. Integrating confidential computing requires infrastructure upgrades, specialized hardware, and skilled personnel, which increases deployment time and cost. Compatibility issues with existing applications can delay adoption or limit functionality. Enterprises often lack the internal expertise to re-architect workflows for secure enclaves. This complexity creates barriers for small and mid-sized businesses that lack the resources of large enterprises.
Limited Awareness and Evolving Regulatory Landscape
The confidential computing market must also navigate limited awareness and understanding among decision-makers. Many enterprises are unfamiliar with the concept of protecting data in use or underestimate its necessity. While regulations are evolving to address data privacy more comprehensively, they often lag behind emerging technologies like confidential computing. The lack of explicit regulatory mandates reduces the urgency for adoption, particularly in less-regulated industries. Vendors must invest in education and advocacy to clarify the value proposition. Market growth depends on closing this knowledge gap and aligning technological capabilities with policy evolution.
Market Opportunities
Emerging Demand Across Privacy-Critical Industries
The confidential computing market presents strong opportunities in industries where data privacy and integrity are mission-critical. Healthcare, finance, and defense sectors require advanced protection mechanisms to process sensitive data without exposure. Confidential computing enables these industries to securely collaborate, train AI models, and manage digital assets while meeting regulatory expectations. Startups and enterprises offering specialized solutions for sector-specific use cases can capture early-mover advantages. Governments and critical infrastructure providers also present growth potential due to increasing investment in cyber-resilient technologies. These sectors prioritize secure data handling, making them key opportunity areas for expansion.
Acceleration of Digital Transformation in Emerging Markets
The confidential computing market is well-positioned to benefit from rapid digital transformation in emerging economies. Countries in Asia-Pacific, Latin America, and parts of Africa are investing in cloud infrastructure, digital identity, and smart governance systems. Confidential computing enables these nations to build secure-by-design frameworks from the ground up. It allows organizations to adopt AI and cloud technologies without compromising data privacy. Local governments and enterprises are exploring secure data-sharing models that align with cross-border data protection laws. These developments open new markets for vendors and cloud service providers focused on scalable, secure computing environments.
Market Segmentation Analysis:
By Component
In the confidential computing market, the hardware segment holds a dominant share due to its foundational role in enabling secure enclaves and trusted execution environments (TEEs). Leading semiconductor companies are developing processor-level security features that facilitate isolated data processing. The software segment is growing steadily as it supports orchestration, workload management, and secure application development. Services play a critical role in consulting, integration, and managed security operations, especially for enterprises lacking in-house expertise. Together, these components form a comprehensive ecosystem that drives adoption across sectors.
- For instance, Intel’s Software Guard Extensions (SGX) enables confidential computing solutions by isolating sensitive data and code within secure enclaves on Intel CPUs, allowing users to unlock and process secrets while maintaining hardware-based protection.
By Deployment
The cloud deployment segment leads the confidential computing market as organizations shift toward scalable and flexible IT infrastructures. Cloud service providers are embedding confidential computing into their offerings, allowing businesses to secure data in use without managing hardware themselves. On-premise deployment still appeals to sectors with strict data sovereignty requirements or legacy constraints. Industries such as defense, finance, and healthcare often prefer on-premise control for maximum security assurance. Both deployment models support distinct security and compliance needs across enterprise environments.
By Enterprise Type
Large enterprises represent the primary adopters in the confidential computing market due to their complex workloads, higher risk exposure, and greater compliance obligations. They often have the resources to implement advanced security infrastructure and lead in piloting confidential AI or multi-party data analytics. Small and medium-sized enterprises (SMEs) are gradually entering the market, aided by cloud-based confidential computing solutions. These offerings lower cost barriers and simplify deployment. Growing awareness among SMEs is expected to accelerate market penetration in this segment.
- For instance, Amazon Web Services’ Nitro Enclaves, which enable enterprises to securely process highly confidential workloads-such as those in healthcare and government-by isolating data within dedicated hardware environments.
Segments:
Based on Component
- Hardware
- Software
- Service
Based on Deployment
- On premise
- Cloud
Based on Enterprise Type
- SMEs
- Large Enterprises
Based on Application
- Privacy & Security
- Blockchain
- Multi-party Computing
- IoT & Edge
- Personal Computing Devices
- Other Applications
Based on End Use
- BFSI
- Government & Defense
- Healthcare & Life Sciences
- IT & Telecommunications
- Manufacturing
- Retail & Consumer Goods
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share of the confidential computing market at 41%, driven by early technology adoption and strong regulatory frameworks. The presence of major cloud providers such as Microsoft, Google, and AWS, along with hardware vendors like Intel and AMD, supports rapid innovation and deployment. Enterprises across finance, healthcare, and government sectors prioritize data protection and have the infrastructure to adopt confidential computing at scale. Regulatory acts such as HIPAA and CCPA reinforce demand for in-use data protection. The region also benefits from a mature cybersecurity ecosystem and continuous investment in privacy-enhancing technologies. Strategic collaborations between enterprises and technology providers further accelerate adoption across industries.
Europe
Europe accounts for 27% of the confidential computing market, supported by the region’s stringent data privacy regulations and emphasis on digital sovereignty. The enforcement of GDPR has pushed organizations to adopt secure data practices across storage, transmission, and now, data in use. Countries such as Germany, France, and the Netherlands are leading deployments across finance, healthcare, and public sectors. European enterprises often require localized data processing and security assurances, creating strong demand for on-premise and sovereign cloud solutions. The presence of EU-backed digital initiatives and innovation funding promotes the growth of secure computing technologies. Regional startups and alliances are emerging to build open, privacy-respecting computing environments.
Asia-Pacific
Asia-Pacific holds 22% of the confidential computing market, with rapid growth driven by digital transformation, expanding cloud infrastructure, and rising cybersecurity threats. Countries like China, Japan, South Korea, and India are scaling investments in AI, IoT, and data platforms that demand secure computation. Enterprises and governments across the region are recognizing the need to protect sensitive data in use, especially in finance, telecom, and e-governance projects. National data protection laws are evolving, prompting local cloud providers to integrate confidential computing features. Regional demand is also supported by strategic partnerships between global chipmakers and domestic technology firms. The market shows strong potential as digital economies mature.
Key Player Analysis
- DECENTRIQ
- Microsoft
- Arm Limited
- Fortanix
- Intel Corporation
- Anjuna Security Inc.
- Fortanix Inc.
- IBM
- Amazon Web Services, Inc.
- Alibaba Cloud
- Advanced Micro Devices, Inc.
Competitive Analysis
The confidential computing market features a mix of global technology leaders, cloud service providers, and specialized security firms competing to deliver secure data-in-use solutions. Major players like Intel, AMD, and Arm provide the hardware foundation through processor-level security features such as Trusted Execution Environments (TEEs). Cloud providers including Microsoft, Google, and AWS integrate these capabilities into their services, making confidential virtual machines widely accessible. Security-focused companies like Fortanix, Anjuna Security, and DECENTRIQ offer advanced software platforms that enable secure workload isolation, policy enforcement, and data encryption. The confidential computing market encourages collaboration between hardware and software providers to ensure compatibility and performance. Strategic partnerships and open-source initiatives support ecosystem development and accelerate adoption across sectors. Vendors compete on performance, scalability, and ease of integration, while also differentiating through support for AI, multi-party computation, and compliance capabilities. It remains a rapidly evolving space where innovation and trust define competitive advantage.
Recent Developments
- In April 2024, Cohesity finalized a strategic collaboration with Intel to integrate Intel’s confidential computing capabilities into the Cohesity Data Cloud, enhancing secure data processing.
- On April 28, 2025, Arqit Quantum Inc. launched a quantum‑safe protection solution that integrates Intel Trust Domain Extensions (TDX) with its NetworkSecure™ platform to ensure confidentiality of encryption keys and workloads even in cloud environments
- In November 2023, Anjuna Security, Inc. launched "Anjuna Seaglass," a flexible, cloud-based confidential computing platform compatible with various server chipsets and application architectures.
- In April 2023, Microsoft introduced its D and E Cesv5-series virtual machines in preview, incorporating Intel’s 4th Gen Xeon Scalable processors and Trust Domain Extensions (TDX) for hardware-level confidentiality.
- In July 2023, Fortanix collaborated with the Saudi Information Technology Company (SITE) to deliver a new multi-cloud SaaS data security solution, advancing confidential computing adoption in the Saudi Arabian market.
Market Concentration & Characteristics
The confidential computing market is moderately concentrated, with a mix of established technology giants and emerging security-focused vendors driving innovation. It is characterized by strong vertical integration, where hardware providers, cloud service platforms, and software vendors collaborate to deliver end-to-end secure computing environments. Market leaders such as Intel, AMD, and Arm dominate the hardware layer, while cloud providers like Microsoft, Google, and AWS integrate trusted execution environments into their infrastructure. The market shows high technological intensity, requiring specialized expertise in cryptography, processor architecture, and secure workload management. It also reflects a growing demand for open standards and interoperability, supported by consortiums like the Confidential Computing Consortium. The market continues to evolve rapidly, driven by the convergence of AI, cloud, and cybersecurity. Startups and niche players like Fortanix, DECENTRIQ, and Anjuna Security compete through agile product development and focus on specific industry use cases. The confidential computing market rewards innovation, scalability, and regulatory alignment.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment, Enterprie Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Enterprises will increasingly adopt confidential computing to secure sensitive workloads in cloud and edge environments.
- Adoption will expand beyond finance and healthcare into manufacturing, telecom, and public sector operations.
- AI and machine learning applications will drive demand for privacy-preserving computation at scale.
- Cloud service providers will continue to integrate confidential computing features into mainstream offerings.
- Hardware advancements will improve the efficiency and performance of trusted execution environments.
- Industry-specific regulations will push broader implementation across global markets.
- Partnerships between hardware, software, and cloud vendors will strengthen the technology ecosystem.
- SMEs will gain access through simplified deployment models and managed service offerings.
- Open-source tools and standardization efforts will boost interoperability and developer adoption.
- Market awareness will grow as organizations prioritize data protection strategies for digital transformation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surging Demand for Data Privacy and Regulatory Compliance
Stringent regulations such as GDPR, HIPAA, and CCPA are compelling organizations to secure sensitive data throughout its lifecycle. Confidential computing enables secure processing of encrypted data in memory, ensuring compliance and maintaining customer trust, especially in highly regulated sectors.
Expansion of Cloud Computing and Edge Infrastructure
As enterprises migrate workloads to public and hybrid cloud environments and deploy edge devices, the risk of data exposure during processing increases. Confidential computing provides secure enclaves and trusted execution environments, enabling secure data-in-use protection for cloud-native and edge applications.
Rising Threat of Cyberattacks and Intellectual Property Theft
The increasing frequency and sophistication of cyberattacks, including ransomware and insider threats, are driving organizations to adopt confidential computing. Hardware-based isolation protects sensitive data and intellectual property during computation, closing a critical security gap left by traditional approaches.
Accelerated Integration with AI, Machine Learning, and Analytics
Organizations are leveraging confidential computing to enable privacy-preserving AI and federated learning, allowing secure collaboration on sensitive datasets without exposing raw data. This is particularly vital in sectors like healthcare and finance, where data confidentiality and compliance are paramount.
Industry-Specific Use Cases and Ecosystem Collaboration
Tailored confidential computing solutions are emerging for finance, healthcare, government, and manufacturing, addressing unique security and compliance needs. Industry-wide collaboration and standardization efforts, such as those led by the Confidential Computing Consortium, are accelerating adoption by ensuring interoperability and reducing integration complexity.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Confidential Computing Market?
What are the key segments within the Confidential Computing Market?
What are some challenges faced by the Confidential Computing Market?
Who are the major players in the Confidential Computing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 BFSI
- 1.2.2 Government & Defense
- 1.2.3 Healthcare & Life Sciences
- 1.2.4 IT & Telecommunications
- 1.2.5 Manufacturing
- 1.2.6 Retail & Consumer Goods
- 1.2.7 Others
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Service
- 1.4 By Deployment
- 1.4.1 On premise
- 1.4.2 Cloud
- 1.5 By Application
- 1.5.1 Privacy & Security
- 1.5.2 Blockchain
- 1.5.3 Multi-party Computing
- 1.5.4 IoT & Edge
- 1.5.5 Personal Computing Devices
- 1.5.6 Other Applications
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 13,305 million → 2032: USD 277,711.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Confidential Computing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Confidential Computing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Confidential Computing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Confidential Computing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Confidential Computing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Confidential Computing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Confidential Computing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Confidential Computing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 13,305 million → 2032: USD 277,711.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Confidential Computing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 BFSI
- 12.3.7.2 Government & Defense
- 12.3.7.3 Healthcare & Life Sciences
- 12.3.7.4 IT & Telecommunications
- 12.3.7.5 Manufacturing
- 12.3.7.6 Retail & Consumer Goods
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Service
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On premise
- 12.5.7.2 Cloud
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Privacy & Security
- 12.6.7.2 Blockchain
- 12.6.7.3 Multi-party Computing
- 12.6.7.4 IoT & Edge
- 12.6.7.5 Personal Computing Devices
- 12.6.7.6 Other Applications
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Confidential Computing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Confidential Computing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Confidential Computing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Confidential Computing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Intel Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Advanced Micro Devices, Inc. (AMD)
- 18.4 Arm Limited
- 18.5 Microsoft
- 18.6 Google
- 18.7 IBM
- 18.8 Amazon Web Services (AWS)
- 18.9 Alibaba Cloud
- 18.10 Fortanix
- 18.11 DECENTRIQ
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

