
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Construction Glass Market Size 2024 | USD 111,584.18 million |
| Construction Glass Market, CAGR | 4.87% |
| Construction Glass Market Size 2032 | USD 163,234.81 million |
Market Overview
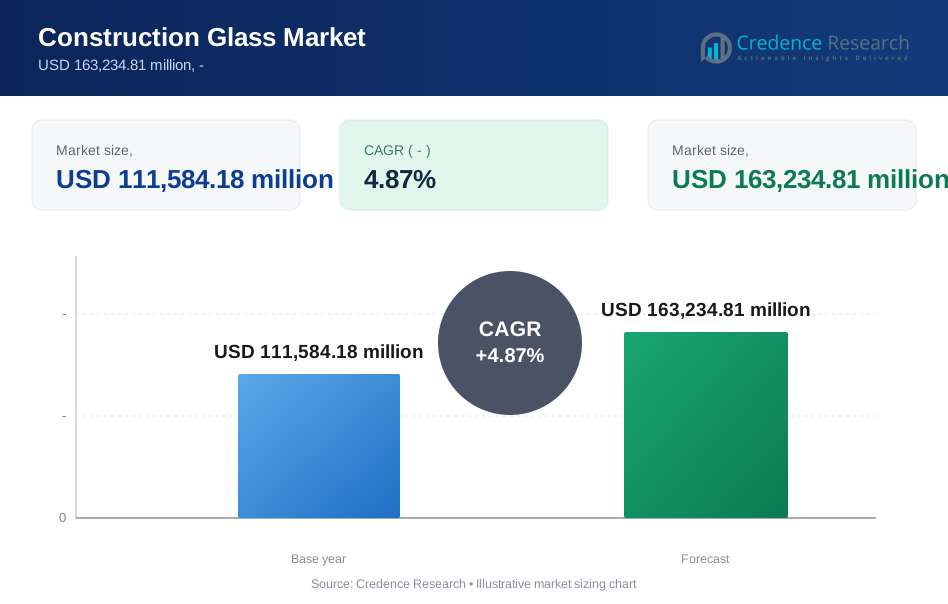
The construction glass market is expected to grow from USD 111,584.18 million in 2024 to USD 163,234.81 million by 2032, with a compound annual growth rate (CAGR) of 4.87%.
The construction glass market is driven by increasing demand for energy-efficient and eco-friendly building materials, particularly in residential, commercial, and industrial sectors. Growing awareness of sustainability has led to the adoption of advanced glass technologies like low-emissivity (Low-E) coatings and solar control glass, which improve thermal insulation and reduce energy consumption. Urbanization, along with a rise in green building projects, further fuels market growth. Additionally, advancements in glass manufacturing, such as the use of recycled materials and renewable energy in production processes, contribute to sustainability efforts. The trend toward smart cities and the integration of smart glass for applications like energy-efficient windows and facades also supports market expansion. Increased government regulations focused on energy conservation and environmental impact are encouraging the use of high-performance glass solutions, making the construction glass market an essential component of modern architecture. As demand for aesthetic and functional glass solutions grows, the market is expected to continue its positive trajectory.
The construction glass market shows diverse growth across various regions. North America holds a significant share, driven by stringent energy efficiency regulations and the adoption of advanced glass technologies. Europe follows closely, with a strong focus on sustainability and green building certifications. The Asia-Pacific region leads the market, supported by rapid urbanization and large-scale infrastructure projects, particularly in China, India, and Japan. Latin America and the Middle East and Africa are experiencing steady growth due to urban development and increasing demand for energy-efficient solutions. Key players such as AGC Glass Company North America, Inc., Guardian Industries Corp Ltd., Saint-Gobain S.A., Nippon Sheet Glass Co., Ltd., and PPG Industries are strategically positioning themselves in these regions, expanding their market reach, and driving technological innovation to cater to regional demands for high-performance construction glass.
Market Insights
- The construction glass market is expected to grow from USD 111,584.18 million in 2024 to USD 163,234.81 million by 2032, with a CAGR of 4.87%.
- Rising demand for energy-efficient and eco-friendly building materials, including low-emissivity coatings and solar control glass, is a major driver of market growth.
- Urbanization and increasing green building projects are contributing to the expanding demand for advanced glass technologies in residential, commercial, and industrial sectors.
- Technological advancements such as the development of smart glass and energy-efficient solutions are fueling innovation in the construction glass market.
- Government regulations aimed at reducing carbon footprints and promoting sustainability are encouraging the adoption of high-performance glass solutions.
- North America holds a significant market share of 28% in 2024, driven by stringent regulations and a high demand for energy-efficient construction materials.
- Asia-Pacific leads with a 35% market share in 2024, supported by rapid urbanization, infrastructure development, and government initiatives in energy-efficient construction practices.
Market Drivers
Rising Demand for Energy-Efficient Solutions
The growing emphasis on sustainability and energy efficiency is a major driver of the construction glass market. Energy-efficient glass products, such as low-emissivity (Low-E) coatings and insulated glass units, help reduce heating and cooling costs in buildings by improving thermal insulation. For instance, Saint-Gobain's PLANITHERM® TOTAL+ is a high-performance, low-emissivity (Low-E) glass developed in the UK, designed to meet British Fenestration Rating Council (BFRC) Window Energy Rating (WER) band B requirements using standard double-glazed units. As governments and regulatory bodies introduce stricter energy efficiency standards, builders and architects are increasingly turning to high-performance glass solutions that comply with green building certifications. These solutions contribute to lowering energy consumption and reducing the overall carbon footprint of buildings, making them highly sought after in both residential and commercial construction projects.
Urbanization and Infrastructure Development
Urbanization continues to be a significant factor propelling the growth of the construction glass market. With more people moving to urban areas, the demand for residential, commercial, and industrial buildings increases. As cities expand, there is a growing need for modern infrastructure that incorporates advanced building materials, including construction glass. For instance, Asahi India Glass Limited (AIS) offers integrated glass solutions to meet the rising demand for energy-efficient buildings in urban areas. This surge in construction activities, particularly in emerging economies, creates opportunities for innovative glass solutions that not only improve the aesthetics of buildings but also enhance their functionality. As urban areas continue to develop, the use of construction glass will become increasingly prevalent.
Technological Advancements in Glass Manufacturing
The evolution of glass manufacturing technology plays a crucial role in driving the construction glass market. Advancements such as the development of smart glass, solar control glass, and self-cleaning glass offer new possibilities for building design and performance. These technologies provide additional benefits, including improved energy efficiency, enhanced privacy, and the ability to harness solar energy. The incorporation of these cutting-edge technologies into construction projects is expected to fuel market demand, as architects and designers seek to create innovative, high-performance buildings that meet modern demands.
Government Regulations and Environmental Concerns
Government regulations aimed at reducing carbon emissions and promoting sustainable building practices are contributing to the increased demand for construction glass. Environmental concerns about the impact of traditional building materials on climate change have led to the adoption of eco-friendly alternatives, such as glass made from recycled materials. These regulatory measures not only incentivize the use of energy-efficient glass products but also support the growth of a more sustainable and environmentally responsible construction industry. As awareness of environmental issues rises, the construction glass market is expected to benefit from heightened demand for green building solutions.
Market Trends
Integration of Smart Glass Technology
One of the prominent trends in the construction glass market is the increasing integration of smart glass technology. Smart glass, which can change its properties in response to external stimuli such as temperature, light, or electricity, is gaining popularity in both residential and commercial buildings. This technology offers benefits like improved energy efficiency, enhanced privacy, and dynamic control over natural light. As cities move toward smart infrastructure, the demand for smart glass in applications such as windows, facades, and partitions is expected to continue growing, as it provides significant advantages in terms of comfort and environmental sustainability.
Sustainability and Eco-Friendly Glass Solutions
Sustainability remains a driving force in the construction glass market. There is a growing trend towards eco-friendly glass products that are manufactured using recycled materials or renewable energy sources. Glass with low carbon emissions and high recyclability is being increasingly incorporated into green building projects. This trend is driven by both consumer demand for environmentally conscious products and government regulations promoting sustainability. For instance, AGC Glass Europe produces low-carbon Planibel Clearlite float glass, which has a carbon footprint of only 5.5 kg CO₂ eq/m² (for 4mm thick glass) and contains over 50% recycled content. As building owners and developers seek to meet stricter environmental standards, the demand for sustainable glass solutions is expected to increase, particularly for high-performance glazing systems that improve energy efficiency.
Customized and Aesthetic Glass Designs
Another key trend is the growing focus on customized and aesthetic glass designs. Modern architecture increasingly emphasizes the visual appeal and versatility of glass as a key building material. Innovations in glass manufacturing allow for a wide range of designs, colors, and textures that can meet both functional and aesthetic needs. From intricate patterns to colored or frosted glass, architects are incorporating more creative glass solutions into building facades, windows, and interiors. This trend reflects the desire for unique and visually striking buildings, which further drives demand for specialized glass products.
Increased Use of Solar Glass and Energy-Harvesting Glass
The use of solar glass and energy-harvesting glass is on the rise in the construction industry. Solar glass, which integrates photovoltaic technology into the glass, enables buildings to generate electricity from sunlight, reducing reliance on external energy sources. For instance, NEXT Energy Technologies has developed an organic thin-film technology that allows daylight to pass through while converting solar energy to electricity. As the demand for sustainable buildings and renewable energy solutions increases, this trend is expected to grow. Energy-harvesting glass technologies not only contribute to energy savings but also align with the broader shift towards sustainable construction practices. This trend is particularly prominent in commercial buildings aiming for LEED certification or other green building accolades.
Market Challenges Analysis
High Production Costs and Material Availability
One of the primary challenges facing the construction glass market is the high production costs associated with advanced glass technologies. High-performance glass products, such as energy-efficient glass and smart glass, require specialized manufacturing processes and raw materials, which can drive up costs. For example, the production of low-emissivity coatings or the integration of photovoltaic cells in glass can significantly increase the price of the final product. These increased costs may limit the adoption of such technologies, especially in budget-conscious markets or smaller-scale projects. Additionally, the availability of key raw materials, such as silica and other specialized components for advanced glass production, can be subject to supply chain disruptions, further complicating pricing, production timelines, and the overall scalability of the industry. This reliance on raw materials from various global markets can also lead to vulnerability in times of geopolitical tensions or supply chain issues, making material availability a persistent challenge for manufacturers.
Regulatory Compliance and Environmental Impact
Another challenge is the need for compliance with stringent building codes and environmental regulations. While these regulations are essential for ensuring the safety and sustainability of buildings, they often require construction glass manufacturers to invest heavily in research, development, and certification processes to meet these standards. This can create financial strain, particularly for smaller companies or those entering new markets where local regulatory requirements differ. Additionally, as governments around the world tighten environmental policies, glass manufacturers are under increasing pressure to reduce the carbon footprint of their products. The environmental impact of glass production, especially in terms of energy consumption and emissions, remains a concern despite advancements in sustainable glass technologies. For instance, In India, BIS certification under IS 2553 (Part 1):2018 sets benchmarks for safety glass used in architectural and general applications, ensuring compliance with quality and safety standards. Companies are faced with the challenge of balancing the demand for eco-friendly products with the high costs and technical challenges associated with producing such materials. Adapting to these evolving regulatory environments while maintaining product affordability is essential for long-term growth and industry sustainability.
Market Opportunities
The construction glass market presents significant opportunities driven by the growing global emphasis on sustainability and energy efficiency. As urbanization continues and green building initiatives gain momentum, there is an increasing demand for advanced glass technologies that contribute to energy savings, such as low-emissivity and solar control glass. This trend is especially prominent in regions focused on reducing carbon emissions and achieving net-zero goals, offering manufacturers a chance to expand their product offerings. Moreover, the integration of smart glass into modern buildings, allowing for real-time adjustments in transparency and energy usage, provides further growth opportunities. These innovations enable construction companies to meet stringent environmental regulations while providing consumers with more sustainable and efficient solutions, thereby creating a lucrative market for both traditional and emerging glass technologies.
The rise of smart cities and the ongoing push for more energy-efficient infrastructures further enhance market prospects for construction glass. As commercial and residential buildings adopt increasingly sophisticated technologies, the need for specialized glass solutions such as solar glass, energy-harvesting glass, and self-cleaning glass is expected to grow. Additionally, as developers and architects continue to prioritize aesthetics and functionality, customized glass designs for façades, windows, and partitions are in high demand. These trends present opportunities for manufacturers to invest in research and development, create cutting-edge products, and cater to a broader range of applications in both residential and commercial sectors. Furthermore, the rising awareness of the importance of sustainable construction materials in emerging markets also opens up new avenues for expansion, particularly in developing regions where urbanization is rapidly increasing.
Market Segmentation Analysis:
By Type
The construction glass market can be segmented by type into float glass, tempered glass, laminated glass, insulated glass, and smart glass. Float glass holds the largest market share due to its versatility and widespread use in windows, facades, and mirrors. However, the demand for smart glass and insulated glass is increasing as they offer energy-efficient solutions, making them popular in modern building designs focused on sustainability and energy conservation.
By Application
In terms of application, the construction glass market is divided into residential, commercial, and industrial sectors. The commercial segment is expected to dominate the market, driven by the increasing demand for energy-efficient solutions in office buildings, shopping centers, and other commercial infrastructures. The residential segment also shows growth potential, particularly with the rising adoption of eco-friendly and aesthetic glass products for homes. The industrial segment, though smaller, contributes significantly due to its use in factories, warehouses, and specialized infrastructure.
Segments:
Based on Type
- Low-E Glass
- Special Glass
Based on Application
- Residential
- Nonresidential
- Commercial
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the construction glass market, estimated at 28% in 2024. The growth in this region is driven by stringent building regulations, a high demand for energy-efficient construction materials, and the adoption of green building practices. The U.S. and Canada are at the forefront of integrating advanced glass technologies such as low-emissivity, solar control, and smart glass into residential, commercial, and industrial projects. The push for sustainable infrastructure, alongside government incentives for energy-efficient buildings, continues to fuel market growth. Additionally, the region's robust construction sector and increasing urbanization are expected to support the steady demand for construction glass in the coming years.
Europe
Europe is another key region in the global construction glass market, holding a market share of 25% in 2024. The European Union’s focus on sustainability and green building certifications like LEED and BREEAM has led to a surge in demand for energy-efficient and eco-friendly glass products. Countries such as Germany, France, and the UK are witnessing significant growth in commercial and residential construction projects that prioritize environmental impact. The region’s emphasis on reducing carbon footprints and meeting strict regulatory standards for energy efficiency plays a crucial role in the adoption of advanced glass technologies. Europe is also a hub for innovation in smart glass solutions, further boosting its market share.
Asia-Pacific
The Asia-Pacific region leads the construction glass market, commanding a market share of 35% in 2024. The rapid pace of urbanization, industrialization, and infrastructure development in countries like China, India, and Japan is driving the demand for construction glass. The region is expected to witness substantial growth due to ongoing construction projects in both residential and commercial sectors. Additionally, governments in these countries are focusing on sustainable building practices, promoting the use of energy-efficient glass products. The increasing adoption of smart cities and green building initiatives in emerging economies further supports the market's expansion in the Asia-Pacific region.
Latin America
Latin America accounts for 7% of the global construction glass market in 2024. While the region is smaller in comparison to others, its market is growing steadily. Countries such as Brazil, Mexico, and Argentina are increasingly adopting energy-efficient glass products due to a rising awareness of environmental concerns and energy conservation. The demand for construction glass is expected to increase as urbanization accelerates and more sustainable construction practices are adopted across the region.
Middle East and Africa
The Middle East and Africa (MEA) region holds a market share of 5% in 2024. Despite being a smaller segment, the region is experiencing significant growth driven by large-scale infrastructure projects, particularly in countries like the UAE, Saudi Arabia, and South Africa. The increasing demand for high-performance glass in commercial buildings, skyscrapers, and government infrastructure projects is driving market expansion. The region’s focus on modernizing urban landscapes and adopting sustainable building materials provides substantial opportunities for growth in the construction glass market.
Key Player Analysis
- AGC Glass Company North America, Inc. (U.S.)
- Guardian Industries Corp Ltd. (U.S.)
- JE Berkowitz, LP (U.S.)
- PPG Industries, Inc. (U.S.)
- Saint-Gobain S.A. (France)
- Nippon Sheet Glass Co., Ltd. (Japan)
- Central Glass Co. Ltd. (Japan)
- Schott AG (Germany)
- AGNORA (U.S.)
- A. Bendheim Ltd. (U.S.)
Competitive Analysis
The construction glass market is highly competitive, with leading players such as AGC Glass Company North America, Inc., Guardian Industries Corp Ltd., JE Berkowitz, LP, PPG Industries, Inc., Saint-Gobain S.A., Nippon Sheet Glass Co., Ltd., Central Glass Co. Ltd., Schott AG, AGNORA, and S.A. Bendheim Ltd. These companies are focused on innovation, sustainability, and expanding their product portfolios to meet the growing demand for energy-efficient and high-performance glass solutions. Their competitive strategies often include the development of advanced glass technologies, such as low-emissivity coatings, smart glass, and solar control glass, which are increasingly being adopted in green building projects. Strategic partnerships, acquisitions, and expansion into emerging markets also help these players maintain their market position. Additionally, manufacturers are investing in R&D to reduce production costs while improving the functionality and aesthetics of their glass products. This intense competition drives continuous improvements in product quality, technological advancements, and customer service.
Recent Developments
- In April 2024, Guardian CrystalClear glass became available in North America, offering architects and designers a highly transparent and cost-effective alternative to standard and low-iron glass. It is suitable for various applications in the building envelope, including education, healthcare, office, residential, and retail.
- In January 2024, Saint-Gobain launched its solution offer for light construction, which is commonly used for both interior solutions (such as plasterboard, insulation, and ceilings) and exterior applications (including siding and roofing).
- In January 2024, AO and Matteson Capital promoted the Boardwalk at Bricktown project, which involves constructing a 1,907-foot skyscraper in downtown Oklahoma City. If built, it will rank as the sixth tallest building in the world, located in the heart of the city’s downtown region.
- In October 2023, NSG Pilkington introduced Pilkington Mirai™, an eco-friendly glass designed to replace conventional float glass while maintaining the same visual quality and performance. This innovation uses alternative fuels, recycled glass, and renewable energy in its production.
- In October 2023, Pilkington United Kingdom Limited, part of the NSG Group, unveiled a new range of glass that cuts its embodied carbon content by 50% compared to ordinary float glass, making it the lowest-carbon option available on the market today.
- In July 2023, HeatCure, a nanotechnology-based coating, began operations in India. This technology aims to prevent solar heat gain on glass doors, windows, and facades, improving energy efficiency.
Market Concentration & Characteristics
The construction glass market is moderately concentrated, with a few key players dominating the global landscape. Leading companies such as AGC Glass Company North America, Inc., Guardian Industries Corp Ltd., Saint-Gobain S.A., and PPG Industries, Inc. hold significant market shares, driving innovation and setting industry standards. These players have established strong supply chains, extensive distribution networks, and well-developed technological capabilities, enabling them to cater to various sectors, including residential, commercial, and industrial construction. Market characteristics include the growing emphasis on sustainability, energy efficiency, and advanced glass technologies like smart glass, solar control, and low-emissivity glass. The market is highly competitive, with firms focusing on product differentiation through innovation in energy-efficient solutions, eco-friendly materials, and smart glass applications. Additionally, regulatory frameworks aimed at reducing carbon footprints are influencing product offerings, leading to a continuous focus on developing high-performance, environmentally responsible construction glass solutions.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing demand for energy-efficient and eco-friendly construction materials will continue to drive market growth.
- Urbanization and rapid infrastructure development in emerging economies will boost the demand for construction glass.
- Technological advancements, such as the rise of smart glass and solar control glass, will lead to innovative applications in buildings.
- Governments will impose stricter energy efficiency and environmental regulations, promoting the use of high-performance glass products.
- The integration of recycled materials and renewable energy sources in glass manufacturing processes will enhance sustainability efforts.
- Growth in green building projects and the adoption of green certifications will further accelerate the use of advanced glass technologies.
- The increasing focus on the development of smart cities will foster demand for energy-efficient windows and facades.
- Continued research and development in glass coatings and glazing technologies will improve the functional capabilities of construction glass.
- The demand for aesthetic and customized glass solutions for both residential and commercial buildings will rise.
- Strategic collaborations and mergers between key players will enhance innovation and market presence across different regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Construction Glass Market?
What factors are driving the growth of the Construction Glass Market?
What are the key segments within the Construction Glass Market?
Who are the major players in the Construction Glass Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Construction Glass Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Construction Glass Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 111,584.18 million → forecast year: USD 163,234.81 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Construction Glass Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Construction Glass Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Construction Glass Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Construction Glass Market Drivers
- 3.3 Construction Glass Market Restraints & Challenges
- 3.4 Construction Glass Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Construction Glass Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Construction Glass Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Construction Glass category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Construction Glass Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Construction Glass Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Construction Glass market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Construction Glass Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Construction Glass Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Construction Glass Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Construction Glass (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Construction Glass Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Construction Glass Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Construction Glass Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Construction Glass Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Construction Glass Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Construction Glass Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Construction Glass Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Construction Glass Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Construction Glass Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
