
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
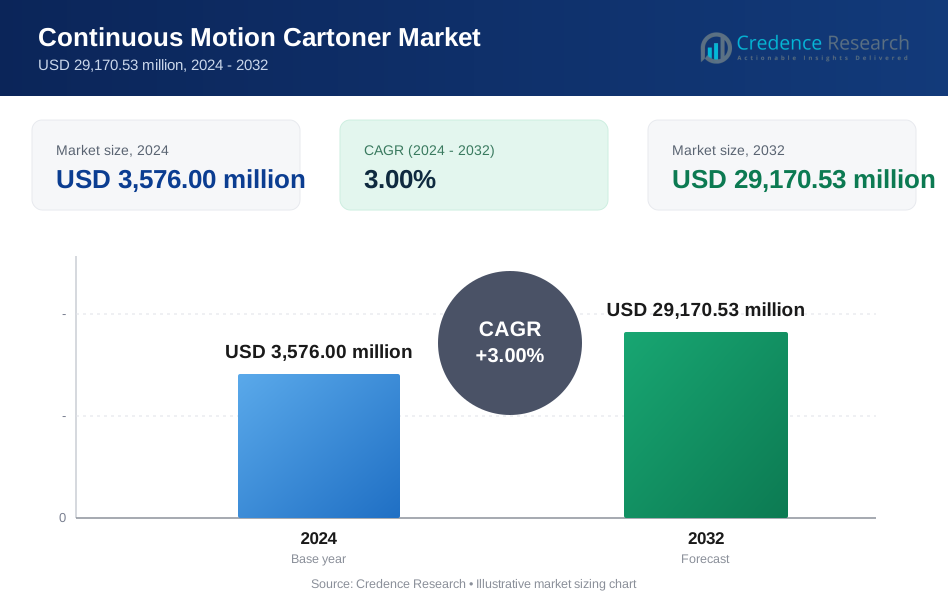
| Continuous Motion Cartoner Market Size 2024 | USD 3,576.00 million |
| Continuous Motion Cartoner Market, CAGR | 3.00% |
| Continuous Motion Cartoner Market Size 2032 | USD 29,170.53 million |
Market Overview
The Continuous Motion Cartoner Market is projected to grow from USD 3,576.00 million in 2024 to USD 29,170.53 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.00%.
The Continuous Motion Cartoner Market is driven by the increasing demand for efficient and high-speed packaging solutions across industries such as pharmaceuticals, food and beverages, and personal care. Technological advancements, including automation and smart technology integration, are enhancing operational efficiency and precision, which boosts market growth. The trend toward sustainability is also influencing the market, as companies seek eco-friendly packaging options. Additionally, the rise in e-commerce and the need for scalable packaging solutions are propelling the adoption of continuous motion cartoners, aligning with broader trends in logistics and supply chain optimization.
The Continuous Motion Cartoner Market exhibits varied dynamics across regions, with North America and Europe leading in adoption due to advanced manufacturing sectors and stringent regulatory requirements. In contrast, Asia Pacific is witnessing rapid growth driven by industrialization and expanding FMCG sectors. Key players in the market include MULTIVAC Sepp Haggenmüller, Bosch Packaging Technology, and TNA (The Nut Factory), which are prominent for their innovative solutions and broad product portfolios. Other notable companies such as ProMach, Omori Machinery Co. Ltd., and KHS GmbH also contribute significantly to the market's competitive landscape.
Market Drivers
Labor Shortages and Cost Reduction
In response to labor shortages and rising operational costs, manufacturers are turning to automation through continuous motion cartoners. For instance, around 16 million working-age Americans (those aged 18 to 65) have long Covid today. Of those, 2 to 4 million are out of work due to long Covid. These advanced machines help reduce dependence on manual labor and lower overall production costs by increasing efficiency and minimizing errors. The integration of automation not only addresses workforce challenges but also optimizes operational expenditures, contributing to more sustainable and cost-effective production processes.
Advancements in Technology and E-commerce Growth
Technological advancements, such as the integration of robotics, automation, and advanced sensors, are significantly enhancing the capabilities of continuous motion cartoners. For instance, data from Digital Commerce 360 indicates a 44% increase in US e-commerce sales, amounting to $861 billion in 2020, up from $598 billion in 2019. These innovations improve precision, efficiency, and adaptability, aligning with the needs of various industries. Additionally, the surge in e-commerce is driving the demand for efficient packaging solutions that can handle diverse product types and volumes, further boosting the adoption of continuous motion cartoners. As online shopping continues to grow, the need for advanced packaging technologies becomes increasingly vital.
Rising Demand for Faster Packaging Solutions
Continuous motion cartoners are increasingly preferred in high-volume production environments due to their superior speed and efficiency compared to intermittent motion cartoners. The need for rapid and seamless packaging solutions is driving this shift, as industries strive to meet the growing demand for quick turnaround times and high productivity. These machines significantly enhance throughput and operational efficiency, making them indispensable in fast-paced manufacturing settings.
Growth of the Fast-Moving Consumer Goods (FMCG) Sector
The booming FMCG sector, characterized by large production volumes and rigorous packaging standards, is a key driver for continuous motion cartoners. As consumer demand for a wide range of packaged goods increases, the need for efficient and reliable packaging solutions becomes more critical. Continuous motion cartoners address this demand by providing the speed and flexibility required to handle diverse FMCG products while maintaining packaging integrity and consistency.
Market Trends
Data Analytics, Compact Designs, and Hygiene
The utilization of data analytics for predictive maintenance and performance optimization is becoming a key trend in the cartoning industry. Leveraging data to monitor machine performance and forecast maintenance needs enhances overall equipment effectiveness (OEE) and reduces downtime. For instance, a survey by the Association for Packaging and Processing Technologies found that 65% of packaging machinery manufacturers are incorporating data analytics capabilities into their equipment. Additionally, compact and modular cartoning designs are gaining traction, particularly in facilities with limited space. These space-saving solutions offer flexibility and efficiency in production environments. Moreover, heightened concerns about hygiene and safety are driving the adoption of cartoning machines with advanced sanitation features and hygienic designs, ensuring compliance with stringent regulations and consumer expectations.
Integration, Industry-Specific Trends, and Remote Monitoring
Seamless integration of continuous motion cartoners with other packaging equipment, such as filling and sealing machines, is essential for optimizing production lines and achieving operational synergy. This integration facilitates smooth and efficient packaging processes. Industry-specific trends further influence cartoner design, with the pharmaceutical sector emphasizing tamper-evident and track-and-trace solutions, the food and beverage industry focusing on sustainable and e-commerce-friendly packaging, and the personal care and cosmetics sector prioritizing premium packaging and efficient production. Additionally, remote monitoring and diagnostics capabilities are enhancing equipment uptime and reducing maintenance costs, reflecting the industry's move towards smarter and more connected production environments.
Market Challenges Analysis
Financial and Operational Challenges
The financial burden associated with purchasing and installing continuous motion cartoners is a notable challenge, particularly for small and medium-sized enterprises (SMEs). The high initial investment can be prohibitive and may deter companies from upgrading their packaging systems. Economic fluctuations also impact investment decisions, potentially leading to reduced demand for new equipment during downturns. Operationally, frequent product changeovers can result in production downtime and decreased efficiency. A study by the Association for Packaging and Processing Technologies found that the average changeover time for packaging equipment is 52 minutes, with some companies reporting times of up to 4 hours. Additionally, the need for skilled operators adds to the complexity of machine maintenance, with 67% of manufacturers reporting difficulty in finding and retaining qualified technicians. These combined challenges necessitate strategic planning and resource allocation to overcome barriers and achieve successful implementation and operation of continuous motion cartoners.
Integration Complexity and Product Variability
Integrating continuous motion cartoners with other packaging equipment, such as fillers and sealers, presents significant challenges due to the need for precise synchronization and seamless operation. The complexity of these integrations demands careful planning and coordination to ensure that all components work together efficiently. Additionally, the variability in product shapes, sizes, and materials further complicates the cartoning process. Machines must be highly flexible and adaptable to accommodate diverse packaging requirements, which can strain operational efficiency and increase setup times. Addressing these challenges requires advanced engineering solutions and meticulous attention to detail to maintain optimal performance across varied product lines.
Market Segmentation Analysis:
By Product:
The continuous motion cartoner market is segmented by product type, including VFFS (Vertical Form-Fill-Seal) cartoners, HFFS (Horizontal Form-Fill-Seal) cartoners, top load cartoners, in-line cartoners, tray and lid cartoners, and other types such as gable top and regular slotted cartoners. VFFS and HFFS cartoners are prominent due to their versatility and efficiency in high-speed packaging environments. Top load and in-line cartoners cater to specific packaging needs, offering flexibility in handling various product types. Tray and lid cartoners are ideal for products requiring additional protection, while gable top and regular slotted options address niche requirements. The diversity in product types ensures that manufacturers can select equipment tailored to their specific production needs and packaging requirements.
By End Use:
In terms of end-use applications, the continuous motion cartoner market serves several key industries, including pharmaceuticals, food & beverages, cosmetics & personal care, tobacco, chemicals, and agriculture. The pharmaceutical industry drives demand due to its need for tamper-evident and compliant packaging solutions. The food & beverages sector, characterized by high production volumes and diverse packaging requirements, also significantly contributes to market growth. Cosmetics & personal care, tobacco, and chemicals industries demand precise and efficient packaging for high-quality products. Additionally, the agriculture sector relies on robust cartoning solutions for bulk and varied products, influencing the market dynamics across these segments.
Segments:
Based on Product
- VFFS Cartoner
- HFFS Cartoner
- Top Load Cartoner
- In-Line Cartoner
- Tray and Lid Cartoner
- Other (Gable Top, Regular Slotted)
Based on End Use
- Pharmaceutical
- Food & Beverages
- Cosmetic & Personal Care
- Tobacco Industry
- Chemical
- Agriculture
Based on Packaging Formats
- Tray Pack
- Shrink-Wrapped Carton
- Rigid Set-Up Boxes
- Window Packs
- Sleeve Packaging
- Blister Packaging
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Europe
Europe leads the market with a substantial 35% share, primarily due to its well-established packaging industry and high adoption of automated packaging solutions. Countries like Germany, Italy, and France dominate this segment, with a strong presence in industries such as food and beverage, pharmaceuticals, and personal care products. The European market is characterized by a high demand for high-speed, flexible cartoning systems that can handle a wide variety of product sizes and shapes. The region's focus on sustainable packaging solutions has also driven innovations in cartoner designs that minimize material waste and energy consumption
North America
North America holds the second-largest market share at 30%, with the United States leading in adoption and innovation. The region's market is driven by a robust pharmaceutical industry and a growing demand for convenient, single-serve packaging in the food sector. For example, Industry 4.0 could enable continuous motion cartoners to interact with other production-line equipment and systems, allowing them to integrate with Industry 4.0. North American manufacturers are at the forefront of developing smart cartoning systems that incorporate IoT technologies for predictive maintenance and real-time performance monitoring.
Key Player Analysis
- MULTIVAC Sepp Haggenmüller
- ProMach
- Bosch Packaging Technology
- Omori Machinery Co. Ltd.
- TNA (The Nut Factory)
- Wipotec-OCS
- Brenton Engineering
- KHS GmbH
- Körber Medipak Systems
Competitive Analysis
In the Continuous Motion Cartoner Market, leading players exhibit a strong competitive edge through technological innovation and comprehensive product offerings. Bosch Packaging Technology stands out with its advanced automation solutions and robust R&D capabilities, enhancing efficiency and flexibility in cartoning processes. MULTIVAC Sepp Haggenmüller excels with its modular designs and adaptability, catering to diverse packaging needs across industries. TNA (The Nut Factory) is recognized for its high-speed, integrated systems that streamline production. ProMach offers a diverse range of cartoners with a focus on reliability and scalability. Omori Machinery Co. Ltd. and KHS GmbH are notable for their strong regional presence and customized solutions. Körber Medipak Systems and Wipotec-OCS leverage their expertise in precision and inspection technologies, addressing stringent quality control requirements. This competitive landscape is characterized by continual innovation and strategic collaborations to meet evolving market demands.
Recent Developments
- In July 2024, ProMach announced the acquisition of Italy-based MBF, a global leader of filling solutions for the wine and spirits industries.
- In June 2022, Omori acquired additional shares of its North American subsidiary, Omori North America.
- In November 2023, KHS GmbH launched a new beer membrane filtration concept, Innopro EcoClear, at the BrauBeviale 2023.
- In January 2022, Wipotec-OCS launched a multi-function metal detection-checkweigher-vision module.
- In January 2022, MULTIVAC completed the acquisition of the complete holdings of TVI in Bruckmühl.
Market Concentration & Characteristics
The Continuous Motion Cartoner Market exhibits moderate to high concentration, driven by key players who dominate with their advanced technology and comprehensive product portfolios. Leading companies such as Bosch Packaging Technology, MULTIVAC, and TNA (The Nut Factory) significantly influence market dynamics through innovation and strategic partnerships. This concentration fosters a competitive environment where differentiation is achieved through technological advancements, such as automation and integration capabilities. The market is characterized by a strong emphasis on efficiency, reliability, and customization to meet diverse industry requirements, including pharmaceuticals, food and beverages, and personal care. As demand for high-speed and flexible packaging solutions grows, market leaders are focused on expanding their offerings and enhancing their technological capabilities to sustain competitive advantage. The industry is also witnessing increased investments in R&D to address evolving packaging needs and regulatory standards.
Report Coverage
The research report offers an in-depth analysis based on Product, End Use, Packaging Formats and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continuous motion cartoners are expected to see growing adoption due to their efficiency in high-speed packaging processes.
- Advancements in automation and robotics will enhance the functionality and versatility of these machines.
- Increased demand from the fast-moving consumer goods (FMCG) sector will drive market growth.
- There will be a rising focus on integrating sustainable and eco-friendly packaging materials.
- The market will benefit from the growth of the e-commerce sector, requiring efficient and adaptable packaging solutions.
- Technological innovations in data analytics and predictive maintenance will improve machine performance and reduce downtime.
- The pharmaceutical industry will continue to drive demand due to stringent packaging requirements and need for tamper-evident solutions.
- Emerging economies will contribute significantly to market expansion as industrialization and consumer bases grow.
- Enhanced regulatory compliance and product safety standards will push for advanced cartoning technologies.
- Competitive pressure will encourage continuous improvement and innovation among key market players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Continuous Motion Cartoner Market?
What factors are driving the growth of the Continuous Motion Cartoner Market?
What are the key segments within the Continuous Motion Cartoner Market?
Who are the major players in the Continuous Motion Cartoner Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Continuous Motion Cartoner Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Continuous Motion Cartoner Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,576.00 million → 2032: USD 29,170.53 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Continuous Motion Cartoner Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Continuous Motion Cartoner Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Continuous Motion Cartoner Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Continuous Motion Cartoner Market Drivers
- 3.3 Continuous Motion Cartoner Market Restraints & Challenges
- 3.4 Continuous Motion Cartoner Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Continuous Motion Cartoner Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Continuous Motion Cartoner Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Continuous Motion Cartoner category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Continuous Motion Cartoner Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Continuous Motion Cartoner Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Continuous Motion Cartoner market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Continuous Motion Cartoner Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Continuous Motion Cartoner Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Continuous Motion Cartoner Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Continuous Motion Cartoner (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Continuous Motion Cartoner Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Continuous Motion Cartoner Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Continuous Motion Cartoner Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Continuous Motion Cartoner Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Continuous Motion Cartoner Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Continuous Motion Cartoner Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Continuous Motion Cartoner Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Continuous Motion Cartoner Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Continuous Motion Cartoner Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
