
Market Overview
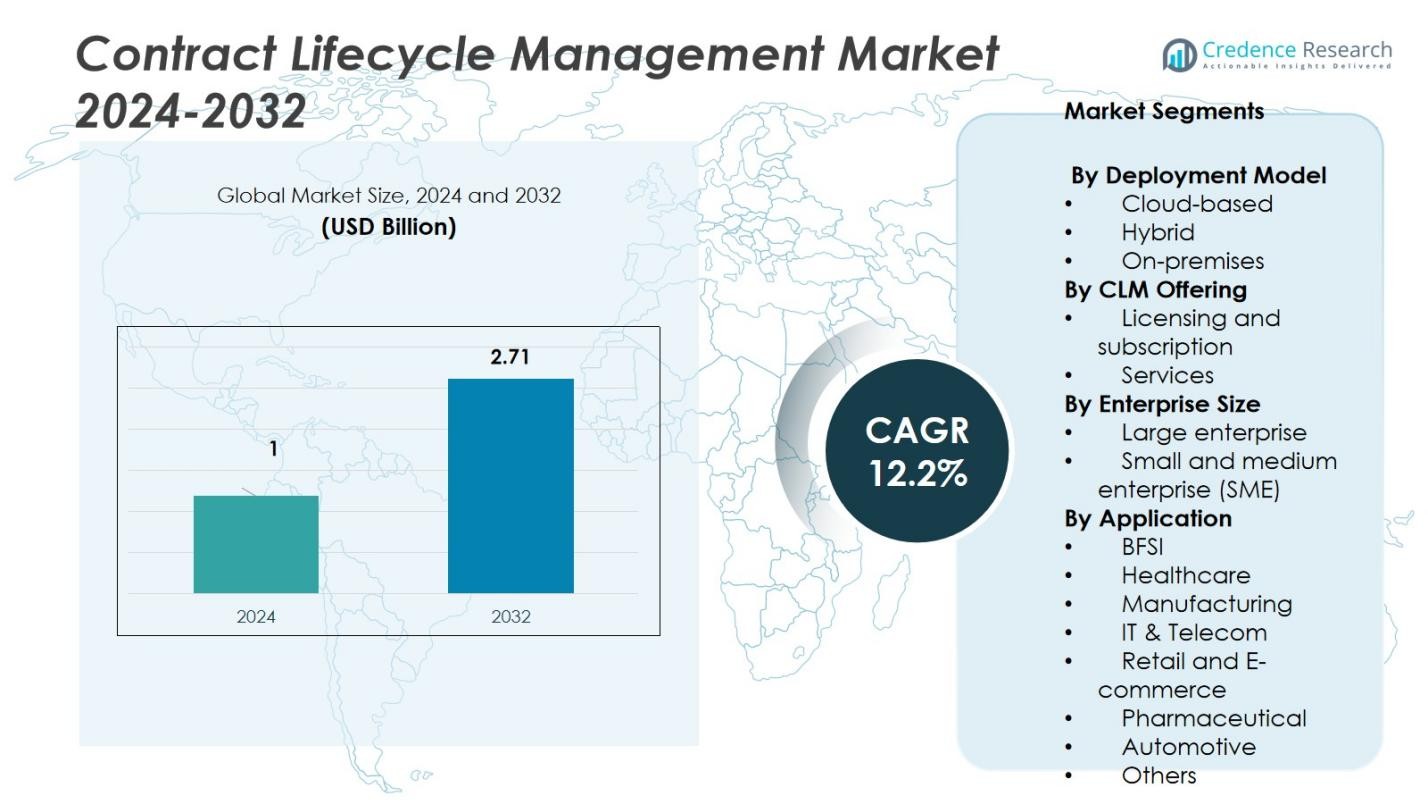
The Contract Lifecycle Management (CLM) Market was valued at USD 1 billion in 2024 and is projected to reach USD 2.71 billion by 2032, growing at a compound annual growth rate (CAGR) of 12.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Contract Lifecycle Management (CLM) Market Size 2024 | USD 1 Billion |
| Contract Lifecycle Management (CLM) Market, CAGR | 12.2% |
| Contract Lifecycle Management (CLM) Market Size 2032 | USD 2.71 Billion |
The contract lifecycle management (CLM) market is highly competitive, with key players such as DocuSign, Icertis, Oracle, Agiloft, and Conga shaping the industry. These companies offer advanced solutions that streamline contract creation, management, and compliance. DocuSign is renowned for its eSignature capabilities, complementing its CLM platform to help businesses automate contract workflows. Icertis stands out with its cloud-based solution, integrating AI to enhance contract visibility and compliance. Oracle, Agiloft, and Conga cater primarily to large enterprises, offering features such as automated contract generation, workflow automation, and ERP integration. North America leads the global CLM market, capturing around 40% of the market share in 2024. This region's dominance is driven by the presence of key vendors, high adoption rates of cloud solutions, and significant demand for automation, compliance, and data security in sectors like finance, healthcare, and manufacturing. The region is also benefiting from the ongoing digital transformation in businesses across various industries.
Market Insights
- The contract lifecycle management market reached USD 1 billion in 2024 and is projected to hit USD 2.71 billion by 2032, growing at a CAGR of 12.2 %.
- The market is driven by digital transformation initiatives, regulatory compliance needs, and increasing adoption of cloud‑based deployment models-which held over 70% share in 2024.
- Key trends include the rise of AI‑enabled contract intelligence, shift toward subscription/licensing offerings (around 60% share in 2024), and growing demand from SMEs in emerging markets.
- Competitive analysis shows leading players such as DocuSign, Icertis, Oracle, Agiloft, and Conga actively innovating and partnering to expand cloud and AI‑based CLM services while market fragmentation remains moderate.
- Regional analysis reveals North America leading with a 40% market share, followed by Europe at 30%, Asia‑Pacific at 20%, and Latin America and Middle East & Africa combined at 10%, signalling strong growth potential outside mature markets.
Market Segmentation Analysis:
By Deployment Model
In the deployment‑model segmentation of the contract lifecycle management (CLM) market, the cloud‑based sub‑segment dominates, with over 70% market share in 2024. This dominance is driven by the scalability, remote‑access capability and lower upfront investment that cloud models offer compared to on‑premises setups. Hybrid deployments are gaining traction due to enterprises’ need to balance legacy systems with modern solutions, while the on‑premises model retains a minor share because many organisations still require full control of data and infrastructure.
- For instance, SAP's cloud-based Contract and Lease Management solution in SAP S/4HANA Public Cloud seamlessly integrates lease contracts into core business processes with centralized online repositories, reducing manual data entry across finance and asset accounting systems.
By CLM Offering
Within the CLM market’s offerings, the licensing and subscription segment holds the largest share approximately 60% in 2024 reflecting broad adoption of software‑as‑a‑service (SaaS) models and flexible spending by organisations. This strong position is fueled by the growing preference for subscription‑based access, rapid deployment and continuous updates. The services sub‑segment (including consulting, integration and maintenance) is expanding steadily, driven by the complexity of integrations and need for customisation, but remains secondary in revenue.
- For instance, Conga CLM, deployed on AWS and priced through subscription models, allows organizations to manage contract lifecycles through cloud-native SaaS architecture, with customers reporting 25% reductions in contract processing time through their templated, self-service licensing approach.
By Enterprise Size
For the enterprise‑size segmentation, large enterprises lead the market, accounting for roughly 59% of revenue in 2024. They dominate because they handle complex, high‑volume contract workflows, require advanced features and possess the budget for enterprise‑grade CLM tools. Small and medium enterprises (SMEs) represent the remainder of the market; their growth is accelerating thanks to more affordable cloud options and rising regulatory pressures, but they currently trail large enterprises in terms of absolute market share.
Key Growth Drivers
Digital Transformation and Operational Efficiency
The increasing adoption of CLM solutions is largely driven by the need for digital transformation. Businesses are moving away from manual processes to automated systems that streamline contract workflows. This shift significantly enhances operational efficiency by reducing processing time, improving accuracy, and lowering human errors. As organizations prioritize greater productivity and better governance, CLM solutions are becoming a central tool in transforming contract management and boosting business operations across industries.
- For instance, bioMérieux, a global diagnostics leader, modernized its contract operations through Icertis CLM (branded internally as "myContract") to enhance structure and compliance across over 12,000 contracts, shifting from reliance on live trainings and manual support to real-time, in-app user enablement that reduced friction and support overhead.
Regulatory Compliance and Risk Mitigation
Rising regulatory pressures and the need for stricter compliance are key factors driving the demand for CLM solutions. As organizations face complex regulations and heightened scrutiny, the ability to manage contracts effectively becomes critical. CLM tools help businesses ensure they meet regulatory requirements, track obligations, and prepare for audits. The demand for systems that facilitate compliance, minimize risks, and provide transparency in contract management is accelerating, making CLM an essential part of corporate governance.
- For instance, Wipro helped a leading healthcare services company centralize contracts from multiple acquired entities onto a single CLM platform. This move ensured compliance, eliminated fake and irrelevant documents, and delivered 99% quality in contract abstraction, significantly improving productivity and audit readiness.
Cloud Adoption and Technology Integration
The shift toward cloud‑based platforms and advanced technologies is a significant growth driver in the CLM market. Cloud‑based deployment offers scalability, flexibility, and lower costs, which appeals to a wide range of businesses. Additionally, the integration of artificial intelligence and machine learning with CLM solutions allows for enhanced contract analysis, smarter decision‑making, and predictive insights. These technological advancements are making CLM solutions more efficient, driving greater adoption across various sectors.
Key Trends & Opportunities
AI‑Enabled Contract Intelligence
AI is revolutionizing the contract lifecycle management process by enabling smarter contract analysis, automation, and risk assessment. AI‑powered CLM systems are becoming increasingly adept at reviewing contracts, suggesting terms, and automatically identifying discrepancies. This trend is opening up new opportunities for companies to leverage advanced technologies for more efficient and accurate contract management, reducing manual effort while ensuring compliance and risk mitigation. The rise of AI in CLM is paving the way for faster, more accurate contract decision‑making.
- For instance, Icertis implemented an AI-powered centralized CLM platform for a European automation company, reducing contract cycle times from 72 days to just 4 days while eliminating manual errors through automated processes.
Expansion into SME and Emerging Markets
While large enterprises have traditionally led the adoption of CLM solutions, small and medium enterprises (SMEs) are increasingly adopting these technologies due to the availability of affordable, scalable cloud models. Emerging markets also present untapped potential, as digital readiness improves globally. CLM vendors have a significant opportunity to expand their reach by offering tailored solutions that address the unique needs of SMEs and organizations in developing regions, driving growth in previously underserved markets.
- For instance, Johnson & Johnson implemented a CLM system to centralize contract management across its 175 operating companies worldwide, improving contract visibility, compliance, and speeding execution with data-driven insights.
Key Challenges
High Implementation and Integration Costs
Implementing CLM systems often involves significant initial costs, including software licensing, integration with existing systems, and change management efforts. These expenses can be prohibitive, particularly for small and medium enterprises (SMEs) with limited budgets or complex IT environments. While the long‑term benefits of CLM solutions are substantial, the upfront financial and resource commitments required for implementation and integration remain a significant barrier to widespread adoption.
Data Security and Change Resistance
Data security is a primary concern when adopting CLM systems, as they handle sensitive contract information. Ensuring the confidentiality, integrity, and accessibility of this data is crucial. Additionally, resistance to change from traditional, manual contract processes can slow the adoption of CLM solutions. Employees and organizations accustomed to legacy methods may be hesitant to transition to digital systems, presenting a challenge for businesses seeking to modernize their contract management processes and gain the full benefits of CLM technology.
Regional Analysis
North America
North America leads the contract lifecycle management (CLM) market, holding the largest market share of 40% in 2024. The region’s dominance is driven by the presence of key market players like DocuSign, Oracle, and Icertis, alongside a high adoption rate of cloud‑based CLM solutions. The increasing demand for automation, compliance, and data security in contract management across industries like finance, healthcare, and manufacturing fuels this growth. Additionally, North America benefits from the rapid digital transformation across enterprises, further driving CLM adoption and innovation in the region.
Europe
Europe holds a significant share in the contract lifecycle management market, accounting for 30% of the global market. The region’s growth is driven by the increasing need for regulatory compliance, especially in industries such as healthcare, manufacturing, and energy. The adoption of digital contract management solutions has been accelerated by stringent data protection regulations like GDPR. European businesses are increasingly adopting cloud‑based and hybrid CLM models to streamline their contract processes, reduce risks, and improve compliance with evolving legal requirements.
Asia-Pacific
Asia-Pacific (APAC) is a rapidly growing market for CLM, contributing 20% of the global market share. The growth in this region is primarily driven by the region’s booming economies, increasing digitalization, and rising adoption of cloud technologies. Countries like India, China, and Japan are leading the charge in adopting CLM solutions across various sectors, including manufacturing, IT, and retail. The rise of small and medium enterprises (SMEs) in the region also plays a key role in accelerating the adoption of affordable and scalable CLM solutions, further fueling the market growth.
Latin America
Latin America holds a smaller but growing share of the global contract lifecycle management market, contributing 5% of the overall market. The adoption of CLM solutions in the region is being driven by the need for greater efficiency, transparency, and compliance, especially in industries like energy, finance, and retail. Brazil and Mexico are the key markets within Latin America, with a rising number of enterprises in these countries transitioning to digital contract management systems. The increasing availability of cloud‑based solutions is making CLM more accessible to businesses of all sizes.
Middle East & Africa
The Middle East & Africa (MEA) region, though still in the early stages of CLM adoption, holds a share of 5% of the global market. The growth in this region is driven by the region's ongoing digital transformation, particularly in sectors like oil and gas, construction, and healthcare. Governments and enterprises are increasingly recognizing the need for effective contract management systems to reduce risks and improve compliance with local and international regulations. The market is expected to expand rapidly as more businesses in the region adopt digital and cloud‑based CLM solutions.
Market Segmentations:
By Deployment Model
- Cloud-based
- Hybrid
- On-premises
By CLM Offering
- Licensing and subscription
- Services
By Enterprise Size
- Large enterprise
- Small and medium enterprise (SME)
By Application
- BFSI
- Healthcare
- Manufacturing
- IT & Telecom
- Retail and E-commerce
- Pharmaceutical
- Automotive
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The contract lifecycle management (CLM) market is highly competitive, with leading players such as DocuSign, Icertis, Oracle, Agiloft, and Conga shaping the industry landscape. These companies offer a range of solutions designed to streamline contract creation, management, and compliance. DocuSign, for instance, is renowned for its eSignature solutions, which complement its CLM platform, helping businesses to manage and automate contract workflows. Icertis, on the other hand, has established a strong presence with its cloud‑based CLM solution, which offers advanced analytics and AI capabilities to improve contract visibility and compliance. Oracle, Agiloft, and Conga provide robust CLM systems that cater to large enterprises, offering features such as automated contract generation, workflow automation, and integration with existing enterprise resource planning (ERP) systems. The market is also seeing increased adoption by small and medium enterprises (SMEs), driving innovation as vendors introduce more affordable and scalable solutions. As the market evolves, these key players continue to focus on enhancing their offerings with AI, cloud computing, and data analytics to stay competitive.
Key Player Analysis
- JAGGAER (U.S.)
- GEP (U.S.)
- Icertis (U.S.)
- DocuSign, Inc. (U.S.)
- Oracle (U.S.)
- Agiloft Inc. (U.S.)
- Ironclad, Inc. (U.S.)
- CobbleStone Software (U.S.)
- SirionLabs (U.S.)
- Conga (U.S.)
Recent Developments
- In April 2025, Summize unveiled its next-generation Contract Lifecycle Management (CLM) platform, integrating agentic AI through Summize Intelligent Agents (SIA). This multi-agent system enhances contract reviews by automating redlines, providing AI-driven summaries, and facilitating contract Q&A directly within Microsoft Word.
- In April 2025, Ironclad introduced new capabilities to help enterprises recapture millions in lost contract value. The platform's Obligation Management feature enables users to systematically track critical contract obligations, ensuring compliance and minimizing revenue leakage.
- In May 2024, Icertis and Evisort announced a strategic partnership to enhance contract intelligence capabilities. By integrating Evisort’s AI engine with the Icertis Contract Intelligence platform, the collaboration aims to accelerate the ingestion and analysis of both legacy and new contracts.
- In February 2024, PwC India formed a strategic alliance with Sirion, an AI-powered Contract Lifecycle Management (CLM) platform, to transform enterprise contract management. This collaboration combines PwC India's consulting expertise with Sirion's advanced CLM technology to enhance contract efficiency, reduce risks, and drive innovation.
Report Coverage
The research report offers an in-depth analysis based on Deployment Model, CLM Offering, Enterprise Size, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of AI‑powered analytics will accelerate, enabling organizations to extract insights from large volumes of contracts and support decision‑making.
- Cloud‑native deployment will increase as companies seek flexible, scalable contract lifecycle management platforms that support remote and hybrid workforces.
- SMEs will drive future growth as vendors launch cost‑effective, modular CLM solutions tailored to smaller businesses with limited budgets.
- Integration of CLM platforms with enterprise systems such as procurement, sales, and legal will deepen to offer end‑to‑end contract workflow automation.
- Demand for industry‑specific CLM configurations will rise, especially in sectors like healthcare, manufacturing, and government, to address unique regulatory needs.
- Expansion across emerging geographic markets including Asia‑Pacific and Latin America will open new revenue opportunities as digital transformation accelerates.
- Automation of renewal, obligation tracking, and compliance will reduce contract cycle times and operational risk, enhancing business agility.
- Vendors will increasingly embed sustainability and ESG clauses within CLM platforms, reflecting growing corporate responsibility and regulatory pressure.
- Strategic partnerships, mergers, and acquisitions among CLM software providers will increase as companies seek to consolidate capabilities and market share.
- User focus will shift from basic contract management to proactive contract intelligence-enabling organizations to treat contracts as strategic assets.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Digital Transformation and Operational Efficiency
Organizations are increasingly adopting CLM solutions to automate and streamline contract workflows, replacing manual processes. This shift enhances operational efficiency, reduces processing time, and minimizes human error, making CLM a core component of business process modernization.
Regulatory Compliance and Risk Mitigation
Growing regulatory complexity and the need for strict compliance are pushing businesses to implement CLM systems. These solutions help organizations track obligations, ensure audit readiness, and minimize risks by providing transparency and control over contract management.
Cloud Adoption and Technology Integration
The scalability, flexibility, and cost-effectiveness of cloud-based CLM platforms are driving widespread adoption, especially among SMEs. Integration of AI and machine learning further enhances contract analysis, decision-making, and predictive insights, making CLM solutions more attractive.
AI-Enabled Contract Intelligence
The integration of AI into CLM platforms enables automated contract review, risk assessment, and intelligent recommendations. This trend is accelerating adoption as businesses seek to leverage advanced analytics for faster, more accurate contract management and compliance.
Expansion into SME and Emerging Markets
Affordable, scalable cloud CLM solutions are making it feasible for SMEs and organizations in emerging markets to adopt contract management technology. As digital readiness improves globally, vendors are targeting these segments to drive future market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the contract lifecycle management market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the contract lifecycle management market projected to grow between 2025 and 2032?
Which contract lifecycle management market segment held the largest share in 2024?
What are the primary factors fueling the growth of the contract lifecycle management market?
Who are the leading companies in the contract lifecycle management market?
Which region commanded the largest share of the contract lifecycle management market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 BFSI
- 1.2.2 Healthcare
- 1.2.3 Manufacturing
- 1.2.4 IT & Telecom
- 1.2.5 Retail and E-commerce
- 1.2.6 Pharmaceutical
- 1.2.7 Automotive
- 1.2.8 Others
- 1.3 By CLM Offering
- 1.3.1 Licensing and subscription
- 1.3.2 Services
- 1.4 By Enterprise Size
- 1.4.1 Large enterprise
- 1.4.2 Small and medium enterprise (SME)
- 1.5 By Deployment Model
- 1.5.1 Cloud-based
- 1.5.2 Hybrid
- 1.5.3 On-premises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1 billion → 2032: USD 2.71 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Contract Lifecycle Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Contract Lifecycle Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Contract Lifecycle Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Contract Lifecycle Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Contract Lifecycle Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Contract Lifecycle Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Contract Lifecycle Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Contract Lifecycle Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1 billion → 2032: USD 2.71 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Contract Lifecycle Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 BFSI
- 12.3.7.2 Healthcare
- 12.3.7.3 Manufacturing
- 12.3.7.4 IT & Telecom
- 12.3.7.5 Retail and E-commerce
- 12.3.7.6 Pharmaceutical
- 12.3.7.7 Automotive
- 12.3.7.8 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By CLM Offering - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Licensing and subscription
- 12.4.7.2 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Enterprise Size - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Large enterprise
- 12.5.7.2 Small and medium enterprise (SME)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Deployment Model - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Cloud-based
- 12.6.7.2 Hybrid
- 12.6.7.3 On-premises
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Contract Lifecycle Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Contract Lifecycle Management Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Contract Lifecycle Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Contract Lifecycle Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DocuSign
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Icertis
- 18.4 Oracle
- 18.5 Agiloft
- 18.6 Conga
- 18.7 JAGGAER
- 18.8 GEP
- 18.9 Ironclad
- 18.10 CobbleStone Software
- 18.11 SirionLabs
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

