
Market Overview:
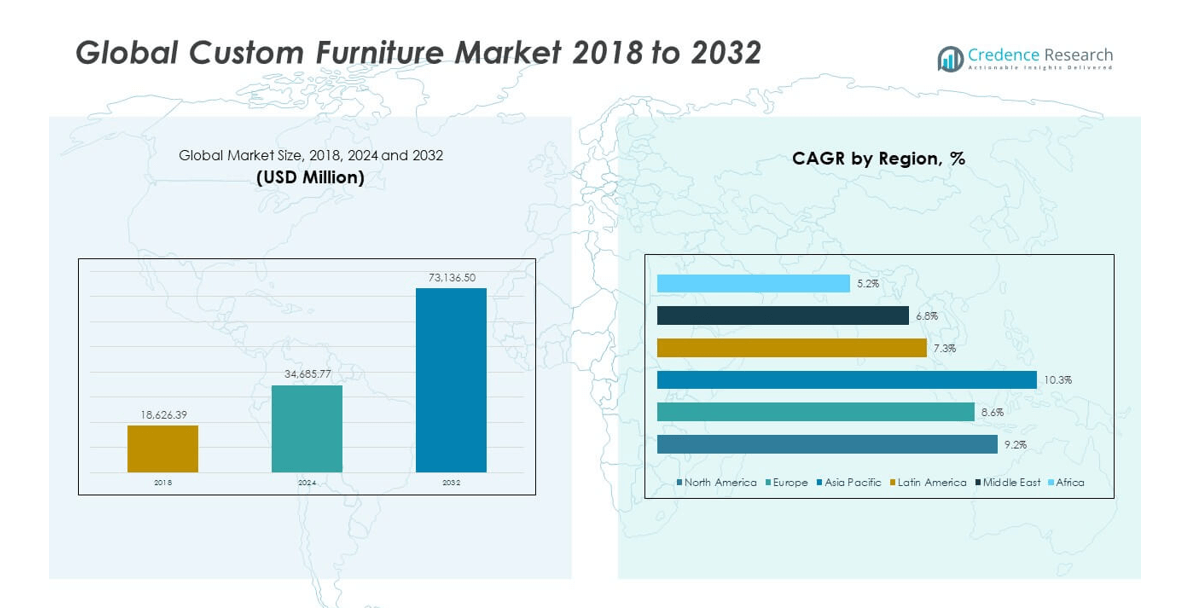
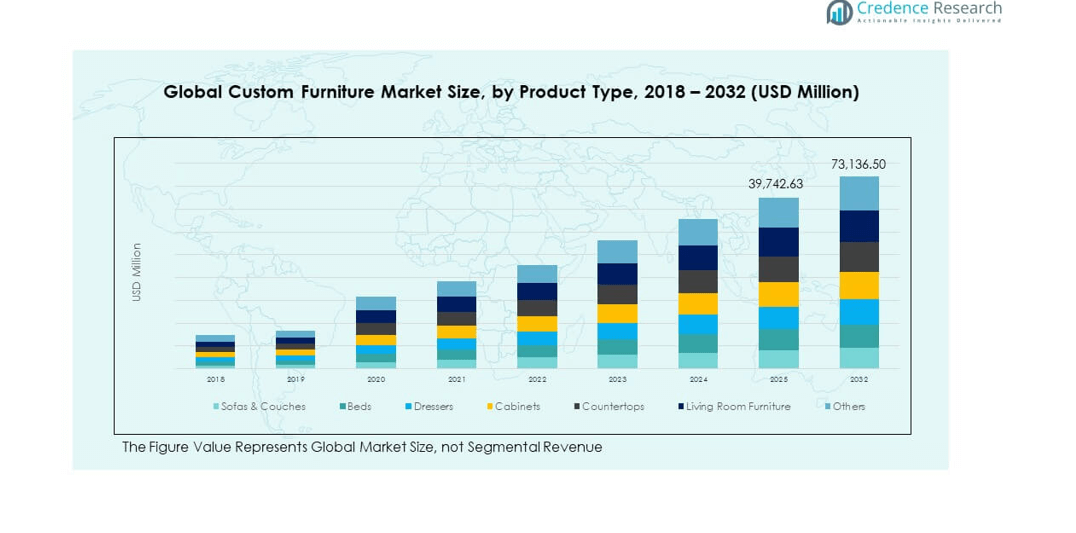
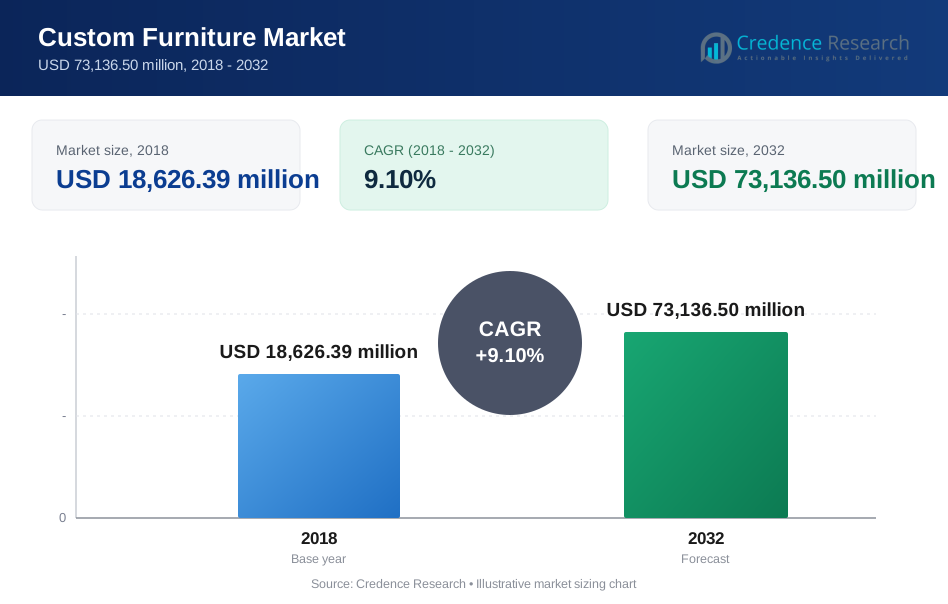
The Global Custom Furniture Market size was valued at USD 18,626.39 million in 2018 to USD 34,685.77 million in 2024 and is anticipated to reach USD 73,136.50 million by 2032, at a CAGR of 9.10% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Custom Furniture Market Size 2024 | USD 34,685.77 million |
| Custom Furniture Market, CAGR | 9.10% |
| Custom Furniture Market Size 2032 | USD 73,136.50 million |
Growing consumer preference for personalized designs, premium aesthetics, and multifunctional furniture is driving expansion. Urban housing projects and office spaces demand versatile layouts that maximize space utility. Increasing adoption of sustainable materials aligns with consumer awareness of eco-friendly living. Rising e-commerce platforms enhance accessibility to custom options and expand reach to diverse demographics. Demand for customized luxury furniture among high-income consumers strengthens market penetration. The hospitality industry further accelerates adoption due to its focus on tailored guest experiences. Increasing technological integration in design and manufacturing enhances both speed and precision of delivery.
Regional Analysis, The Global Custom Furniture Market witnesses’ notable regional variations driven by lifestyle, culture, and economic development. Europe leads due to its strong tradition of craftsmanship and rising demand for luxury interiors. North America follows with high adoption of premium customized furniture, fueled by modern housing developments and lifestyle-focused consumers. Asia Pacific emerges as the fastest-growing market, supported by urbanization and rising middle-class purchasing power. Latin America shows gradual growth through expanding residential and commercial projects. The Middle East demonstrates demand in luxury and hospitality segments, while Africa remains at an early stage but shows promise with increasing urbanization.
Market Insights:
- The Global Custom Furniture Market size was USD 18,626.39 million in 2018, reaching USD 34,685.77 million in 2024, and is projected to hit USD 73,136.50 million by 2032, at a CAGR of 9.10%.
- Europe held the largest share in 2024 at 42.7%, driven by strong craftsmanship traditions and luxury furniture demand; Asia Pacific followed with 30.9% due to urbanization and income growth; North America ranked third with 18.2%, supported by premium lifestyle spending.
- Asia Pacific, the fastest-growing region, captured 30.9% share in 2024, led by rising middle-class demand, urban housing projects, and rapid e-commerce adoption.
- Sofas & couches represented the largest product segment at 27% share in 2024, driven by their central role in residential and commercial interiors.
- Living room furniture accounted for the second-largest share at 22% in 2024, supported by rising urban housing developments and growing demand for multifunctional designs.
Market Drivers:
Rising Demand for Personalization in Interior Spaces:
Consumers are increasingly seeking personalized solutions that reflect individual identity and lifestyle preferences. The Global Custom Furniture Market benefits from this shift as buyers prioritize unique furniture that fits specific dimensions and styles. Higher disposable incomes allow greater spending on tailored solutions for both homes and offices. Urbanization intensifies this trend as compact living spaces demand customized, multifunctional designs. The hospitality sector also seeks unique pieces to create distinctive guest experiences. E-commerce platforms enhance access by offering user-friendly customization options. Integration of digital design tools makes customer participation more engaging. Growing awareness of design-led living continues to fuel adoption.
- For instance, IKEA's Kreativ app enables customers to customize furniture and room designs in a 3D replica of their own space. This app leverages AI to tailor design suggestions based on user preferences, resulting in a higher likelihood of purchase when customers interact with 3D models and higher likelihood with AR visualization.
Influence of Premiumization and Lifestyle Shifts:
The market expands through a rising focus on premiumization, where consumers demand quality and luxury appeal. Customized furniture serves as a symbol of modern lifestyle choices and sophistication. Rising middle-class aspirations push demand for stylish yet functional designs. The Global Custom Furniture Market gains momentum as buyers value durability along with exclusivity. Globalization of lifestyle trends encourages cross-border adoption of premium furniture. Hospitality and corporate sectors are enhancing spaces with high-end customized furniture. Online visualization platforms simplify premium buying decisions. Shifts in consumer psychology emphasize ownership of distinctive, long-lasting pieces. These factors drive strong value creation.
- For instance, Herman Miller exemplifies this with its Live OS system, integrating a digital platform that connects furniture with workplace strategy via sensors. Their sit-to-stand desks have increased employee posture changes sixfold, enhancing well-being and luxury appeal in office environments.
Expansion of Real Estate and Urban Housing Projects:
Urban development projects play a critical role in shaping demand for custom furniture. Residential and commercial expansions drive need for tailored solutions suited to specific layouts. The Global Custom Furniture Market benefits from rising construction activity in both developed and emerging nations. High-rise apartments demand multifunctional designs that optimize space. Corporates require flexible, ergonomic furniture to meet evolving work patterns. Real estate developers increasingly collaborate with designers for integrated furniture offerings. Rising rental spaces further demand customized modular furniture. This synergy between construction and furniture industries creates long-term growth momentum.
Sustainability and Eco-Friendly Material Adoption:
The adoption of sustainable practices is a major driver for the market. Consumers are increasingly choosing furniture made from eco-friendly materials like bamboo, reclaimed wood, and recycled metal. The Global Custom Furniture Market aligns with these shifts by promoting sustainable sourcing and manufacturing. Governments and organizations encourage green certifications for furniture products. Brands highlight transparency in material usage to attract eco-conscious buyers. Sustainable furniture also supports durability, enhancing value over time. Corporate buyers emphasize eco-friendly interiors to align with ESG commitments. Technology aids efficient material use and waste reduction. This driver strengthens long-term environmental and commercial appeal.
Market Trends:
Integration of Digital Tools for Enhanced Customer Experience:
The Global Custom Furniture Market witnesses a strong trend of digital engagement. Augmented reality and 3D modeling tools help customers visualize furniture in their living spaces. E-commerce platforms integrate these technologies to improve buying confidence. AI-driven design suggestions allow quick personalization based on user preferences. Online platforms also simplify material and color selection. Digital consultations with designers reduce the gap between concept and delivery. This seamless experience boosts consumer confidence in online purchases. Rapid adoption of virtual showrooms indicates a long-term trend. It transforms customer interaction and sets new industry standards.
- For instance, Wayfair and other retailers use AR-powered 'View in Room' features that, according to industry studies, have been linked to significant improvements in customer metrics. This technology allows shoppers to visualize true-to-scale 3D models of furniture in their own homes. General data from e-commerce platforms like Shopify suggests that products with AR content can see conversion rates increase by over 90% and returns can be reduced by as much as 40%.
Growth of Modular and Multifunctional Furniture Designs:
The demand for modular solutions continues to increase with urban compact living. Consumers value furniture that adapts to limited spaces and changing lifestyles. The Global Custom Furniture Market benefits from designs that integrate storage and multi-use functions. Foldable beds, expandable tables, and convertible sofas gain traction among urban households. Offices also adopt modular designs to create flexible work environments. Manufacturers emphasize quick assembly and portability to meet evolving consumer needs. This trend reflects growing emphasis on efficiency and smart use of space. Innovation in modular formats drives competitive differentiation.
- For instance, Resource Furniture, a leader in multifunctional designs, reported increasing sales of foldable beds and expandable tables, which appeal to urban consumers requiring adaptable, space-saving solutions.
Increasing Popularity of Premium and Luxury Furniture:
Rising affluence fuels demand for luxury furniture with custom craftsmanship. The Global Custom Furniture Market reflects this trend with growing adoption in both residential and commercial spaces. Wealthy consumers prioritize exclusivity and high-quality materials. Luxury hotels and corporate offices invest in distinctive designs to create unique brand impressions. Art-inspired furniture also gains traction among collectors. Premium brands expand by offering curated customization services. Online luxury furniture portals enhance accessibility to affluent buyers. This trend highlights the growing role of lifestyle aspirations in driving market expansion.
Expansion of Online Customization Platforms:
Digital platforms offering personalized furniture options are rapidly expanding. The Global Custom Furniture Market leverages e-commerce growth to reach wider audiences. Online retailers provide user-friendly tools to select dimensions, materials, and colors. Virtual design assistance ensures accuracy and satisfaction. Competitive pricing and doorstep delivery add value to the online segment. Cross-border sales are growing as logistics networks improve. The shift toward online shopping fuels both mainstream and premium furniture categories. This trend continues to reshape distribution strategies for key players.
Market Challenges Analysis:
High Cost of Production and Pricing Pressures:
The Global Custom Furniture Market faces challenges due to high production costs. Customization requires skilled labor, advanced machinery, and premium materials. These factors increase unit costs compared to mass-produced furniture. Consumers often perceive custom furniture as expensive, limiting affordability in price-sensitive regions. Manufacturers also face pricing pressures in competitive markets. Online platforms offering cheaper alternatives intensify the challenge. Scaling production without losing exclusivity remains difficult. High logistics costs add to overall expense, especially in international markets. Managing cost while maintaining quality is a key industry obstacle.
Supply Chain Constraints and Lead Time Issues:
Another challenge lies in extended supply chains and long lead times. Custom furniture often requires sourcing specific materials not always readily available. The Global Custom Furniture Market experiences delays due to this dependency. Skilled artisanship adds to production time, slowing order fulfillment. Disruptions in raw material supply or logistics can further delay deliveries. Consumers, accustomed to quick e-commerce shipments, sometimes hesitate due to long wait periods. Balancing customization with timely delivery is a persistent issue. Companies that fail to optimize supply chains risk losing market share. Effective management of operations is crucial to overcome these hurdles.
Market Opportunities:
Expansion into Emerging Economies and Middle-Class Markets:
The Global Custom Furniture Market offers strong opportunities in emerging economies. Rising disposable income among middle-class consumers fuels demand for affordable customization. Urbanization in Asia, Latin America, and Africa creates large untapped markets. Consumers seek functional, stylish furniture tailored to compact housing layouts. Local manufacturers gain opportunities by offering cost-effective, region-specific designs. Online retail expansion further supports accessibility. This opportunity strengthens future market penetration.
Collaboration with Real Estate and Hospitality Sectors:
Strategic collaborations create significant growth avenues. The Global Custom Furniture Market benefits when manufacturers partner with real estate developers and hospitality brands. Integrated furniture solutions enhance project value and customer appeal. Hotels seek tailored furniture for brand distinction. Real estate projects with pre-installed customized options attract premium buyers. Such partnerships ensure consistent demand flow. These alliances also improve visibility for custom furniture brands. This opportunity drives stable long-term growth.
Market Segmentation Analysis:
By Product Type
The product type segment highlights sofas & couches as the leading category, driven by strong demand in both residential and commercial spaces. Beds also represent a significant portion, supported by growth in urban housing and hospitality projects. Cabinets, dressers, and countertops continue to expand as multifunctional designs gain popularity. Living room furniture remains vital in shaping interior aesthetics, while other categories include customized niche solutions. This diversity ensures that the market caters to a wide range of customer needs.
- For instance, Living room furniture remains vital in shaping interior aesthetics, while other categories include customized niche solutions such as bespoke office desks and accent chairs, ensuring that the market caters to a wide range of customer needs.
By Material
Fabric dominates the material segment due to its comfort, flexibility in design, and suitability for different interiors. Metal is gaining popularity in modern and industrial-themed furniture, while glass is used for premium aesthetics and contemporary designs. Other materials such as composites and wood alternatives provide sustainability-focused options. The balance between durability, cost, and aesthetics drives consumer choices across these material segments.
- For instance, some composites and wood alternatives offer sustainability-focused options that attract environmentally conscious buyers. The level of sustainability varies based on factors like recycled content, bio-based materials, and the manufacturing process. These products often balance durability, cost, and aesthetics, though specific trade-offs exist within each material segment, such as differences in heat retention or recyclability.
By End User
Residential customers hold the largest share, supported by rising urbanization and the growth of personalized home interiors. Commercial demand continues to expand through offices, retail outlets, and hospitality projects that prioritize brand-specific furniture. Institutional use remains steady, especially in educational and healthcare facilities seeking durable, functional furniture. Each segment reflects unique customization needs, fueling market diversity.
By Distribution Channel
Offline distribution channels dominate due to consumer preference for in-store experience and customization. Physical stores allow buyers to engage directly with materials and designs before making a purchase. Online channels, however, are growing rapidly as digital tools enable visualization and design selection. E-commerce platforms offer broader reach, competitive pricing, and doorstep delivery, strengthening the segment’s influence. Together, both channels complement the evolving sales ecosystem.
Segmentation:
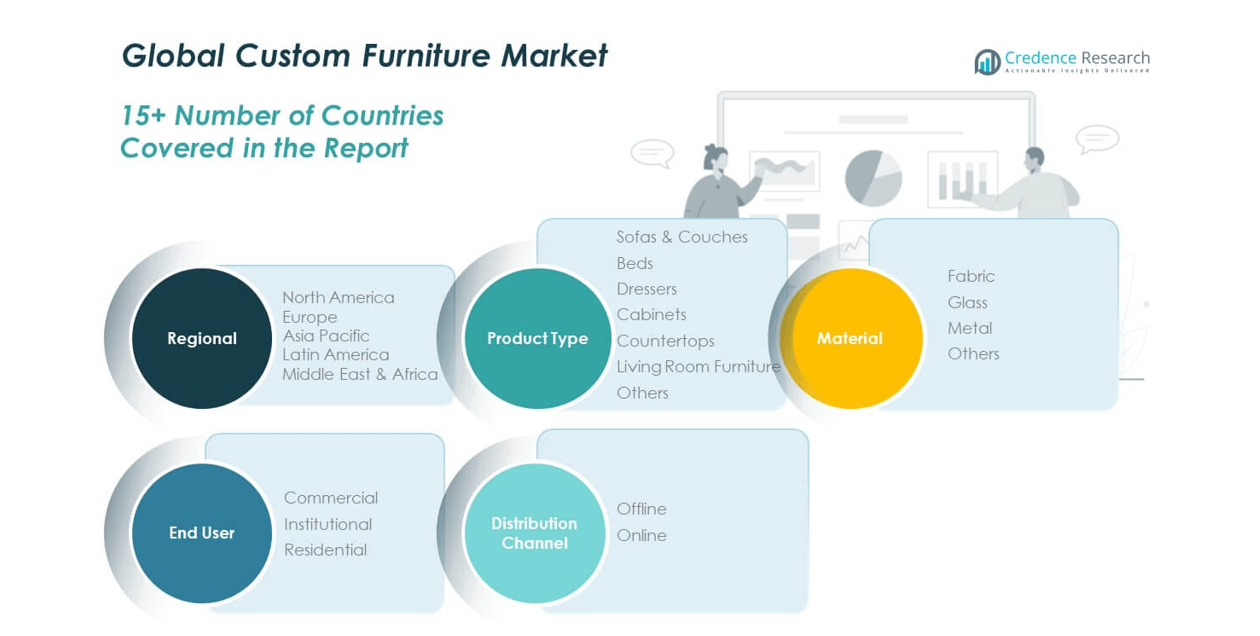
- By Product Type
- Sofas & Couches
- Beds
- Dressers
- Cabinets
- Countertops
- Living Room Furniture
- Others
- By Material
- Fabric
- Glass
- Metal
- Others
- By End User
- Commercial
- Institutional
- Residential
- By Distribution Channel
- Offline
- Online
- By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
- North America
Regional Analysis:
North America
The North America Global Custom Furniture Market size was valued at USD 3,468.87 million in 2018 to USD 6,302.37 million in 2024 and is anticipated to reach USD 13,376.59 million by 2032, at a CAGR of 9.2% during the forecast period. North America accounted for 18.2% share in 2024. The region benefits from strong demand for premium home décor, modern urban housing, and workplace renovation projects. The U.S. drives most sales with rising consumer preference for high-quality custom furniture in both residential and commercial sectors. Canada contributes through sustainable designs and eco-friendly material adoption, while Mexico shows growth from expanding middle-class consumption. High digital adoption supports online customization, while retail outlets remain influential in driving customer trust. Strong purchasing power and lifestyle-driven spending make North America a stable and expanding market.
Europe
The Europe Global Custom Furniture Market size was valued at USD 8,146.16 million in 2018 to USD 14,814.91 million in 2024 and is anticipated to reach USD 30,067.71 million by 2032, at a CAGR of 8.6% during the forecast period. Europe commanded the 42.7% share in 2024, the largest among all regions. The market thrives on a tradition of craftsmanship, luxury interiors, and growing focus on sustainability. Countries such as Germany, France, Italy, and the UK dominate due to advanced design capabilities and strong consumer spending. Demand for eco-friendly and luxury furniture strengthens the segment, supported by strict EU regulations on sustainable sourcing. Cultural emphasis on home aesthetics and premium living rooms sustains growth. Strong export activity also contributes to market stability. Europe remains the global leader in custom furniture innovation and luxury consumption.
Asia Pacific
The Asia Pacific Global Custom Furniture Market size was valued at USD 5,445.24 million in 2018 to USD 10,699.69 million in 2024 and is anticipated to reach USD 24,582.27 million by 2032, at a CAGR of 10.3% during the forecast period. Asia Pacific held a 30.9% share in 2024, making it the fastest-growing region. Rising urbanization and the rapid growth of middle-class households drive strong residential demand. China leads with large-scale adoption across metropolitan cities, while India demonstrates growth through urban housing expansion and premium lifestyle adoption. Japan and South Korea emphasize modern and compact furniture designs suited for limited living spaces. Southeast Asia adds potential through increasing disposable income and digital retail adoption. The region’s manufacturing base also provides cost advantages, making it both a consumer and production hub for custom furniture.
Latin America
The Latin America Global Custom Furniture Market size was valued at USD 809.32 million in 2018 to USD 1,486.73 million in 2024 and is anticipated to reach USD 2,742.82 million by 2032, at a CAGR of 7.3% during the forecast period. Latin America accounted for 4.3% share in 2024. Brazil dominates the market due to its growing construction industry and rising urban middle class. Mexico and Argentina follow, with demand supported by expanding retail and hospitality sectors. Rising interest in premium lifestyle furniture among higher-income groups contributes to steady market growth. However, economic fluctuations remain a limiting factor in some countries. Expansion of online distribution channels helps overcome supply chain gaps. Latin America represents a developing market with consistent opportunities for customized, space-efficient designs.
Middle East
The Middle East Global Custom Furniture Market size was valued at USD 525.82 million in 2018 to USD 895.71 million in 2024 and is anticipated to reach USD 1,596.09 million by 2032, at a CAGR of 6.8% during the forecast period. The Middle East accounted for 2.6% share in 2024. The region’s growth is concentrated in luxury and hospitality projects, especially in GCC countries. High investments in commercial spaces, premium hotels, and residential complexes drive demand for unique furniture solutions. Consumers value exclusivity and high-end craftsmanship, fueling demand for bespoke designs. Turkey and Israel contribute additional demand through urban housing and design-oriented buyers. Government-backed infrastructure projects also support the segment. However, limited affordability among mass consumers restricts wider adoption. The market remains a niche but premium-driven segment.
Africa
The Africa Global Custom Furniture Market size was valued at USD 230.99 million in 2018 to USD 486.37 million in 2024 and is anticipated to reach USD 771.01 million by 2032, at a CAGR of 5.2% during the forecast period. Africa held a 1.4% share in 2024. The region remains in its early stages of adoption but shows promise with ongoing urbanization and growing middle-class consumption. South Africa leads demand, supported by construction and lifestyle-focused spending. Egypt follows with growth in real estate and retail projects. Affordability challenges and weaker distribution networks limit rapid expansion in other African nations. However, rising e-commerce penetration is improving accessibility. With steady infrastructure development, Africa represents a long-term growth opportunity for custom furniture makers targeting cost-effective designs.
Key Player Analysis:
- IKEA
- Herman Miller
- Ashley Furniture Industries
- Williams-Sonoma
- Steelcase
- Ethan Allen
- La-Z-Boy
- MillerKnoll (formerly Herman Miller/Knoll)
- Godrej Interio
- Kimball International
Competitive Analysis:
The Global Custom Furniture Market is highly competitive, with established players and emerging regional firms vying for share. Companies such as IKEA, Herman Miller, Ashley Furniture Industries, and Williams-Sonoma dominate with strong global presence and innovation-driven portfolios. These leaders invest heavily in design technology, sustainable sourcing, and online platforms to expand reach. Mid-sized firms like Godrej Interio and Kimball International strengthen regional footprints by offering cost-effective and culturally relevant designs. Niche luxury brands also play a role by catering to affluent consumers seeking exclusivity. Competitive strategies include mergers, acquisitions, new product launches, and expansion into high-growth regions. The market’s fragmented nature allows smaller players to thrive through customization, digital engagement, and local design influence. It reflects a balanced mix of global giants, regional specialists, and boutique firms competing to capture rising demand.
Recent Developments:
- In December 2024, Inter IKEA Group completed the acquisition of IKEA retail operations in Estonia, Latvia, and Lithuania, including three full-size stores, smaller customer meeting points, and e-commerce platforms. This move supports IKEA's vision to create a better everyday life and enables sharing learnings across the value chain to strengthen their global operations.
- Ashley Furniture Industries launched a high-performance furniture collection in April 2024 featuring family and pet-friendly durable fabrics under the Next-Gen Nuvella® technology. They also acquired Resident Home Inc., a digital retailer of mattresses and bedding accessories, to expand their home furnishings assortment and global footprint.
Report Coverage:
The research report offers an in-depth analysis based on product type, material, end user, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growth will be driven by rising demand for personalized interior solutions.
- Eco-friendly furniture will gain traction as consumers demand sustainable options.
- Digital customization platforms will reshape customer engagement strategies.
- Premium and luxury custom furniture will see stronger adoption among affluent buyers.
- Modular and multifunctional designs will expand with urban housing trends.
- Online distribution will capture larger share as e-commerce adoption rises.
- Asia Pacific will remain the fastest-growing region due to urbanization and income growth.
- Strategic partnerships with real estate and hospitality will boost market expansion.
- Technology integration such as AR/VR will enhance buyer experience.
- Smaller regional players will thrive through localized customization offerings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Custom Furniture Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Custom Furniture Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Global Custom Furniture Market?
Who are the leading companies in the Global Custom Furniture Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Custom Furniture Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Custom Furniture Market Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2032) (2018: USD 18,626.39 million → 2032: USD 73,136.50 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Custom Furniture Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2018 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Custom Furniture Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Custom Furniture Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Custom Furniture Market Drivers
- 3.3 Custom Furniture Market Restraints & Challenges
- 3.4 Custom Furniture Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Custom Furniture Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Custom Furniture Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Custom Furniture category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Custom Furniture Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Custom Furniture Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2018)
- 5.1.2 Global Export Volume by Country (2018)
- 5.1.3 Global Import Value by Country (2018)
- 5.1.4 Global Import Volume by Country (2018)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Custom Furniture market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Custom Furniture Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2018
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Custom Furniture Market Share Analysis – 2018
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2018)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Custom Furniture Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Custom Furniture (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Custom Furniture Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Custom Furniture Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2032)
- 7.1.2 Channel Mix Evolution (2018-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Custom Furniture Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Custom Furniture Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Custom Furniture Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Custom Furniture Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Custom Furniture Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Custom Furniture Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Custom Furniture Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
