
Market Overview:
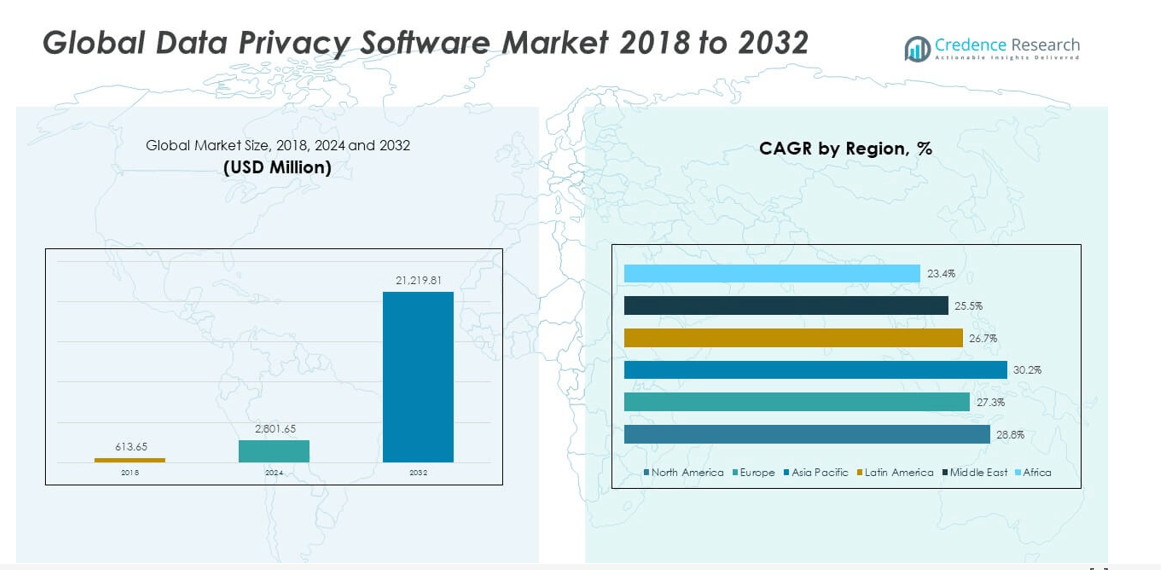
The Global Data Privacy Software Market size was valued at USD 613.65 million in 2018 to USD 2,801.65 million in 2024 and is anticipated to reach USD 21,219.81 million by 2032, at a CAGR of 28.80% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Data Privacy Software Market Size 2024 | USD 2,801.65 million |
| Data Privacy Software Market, CAGR | 28.80% |
| Data Privacy Software Market Size 2032 | USD 21,219.81 million |
The market is growing as organizations face increasing pressure to comply with stringent data protection regulations worldwide. Rising consumer awareness about personal data rights, combined with high-profile data breaches, has accelerated adoption of privacy software solutions. Enterprises are investing in advanced tools to monitor data access, manage consent, automate compliance, and reduce risks of financial penalties. Growth in cloud adoption and digital transformation initiatives further strengthens the demand for scalable privacy management solutions across industries.
Regionally, North America leads due to strong regulatory frameworks such as CCPA and extensive enterprise adoption of compliance solutions. Europe follows closely, driven by GDPR enforcement and widespread consumer data protection initiatives. Asia Pacific is emerging as the fastest-growing region, with countries like India, China, and Japan adopting privacy software in response to expanding digital economies and evolving data security laws. Meanwhile, Latin America and the Middle East are gradually embracing data privacy software, spurred by increasing digitalization, cross-border trade, and rising cyber threats that necessitate compliance and protection frameworks.
Market Insights:
- The Global Data Privacy Software Market was valued at USD 613.65 million in 2018, reached USD 2,801.65 million in 2024, and is projected to hit USD 21,219.81 million by 2032, growing at a CAGR of 28.80%.
- North America led with 43.9% share in 2024 due to strong regulatory enforcement and early enterprise adoption, followed by Asia Pacific with 30.7% share supported by rapid digital transformation, and Europe with 17.7% share backed by strict GDPR compliance.
- Asia Pacific is the fastest-growing region with 30.7% share, driven by expanding e-commerce, fintech growth, and rising consumer data protection laws in China, India, and Japan.
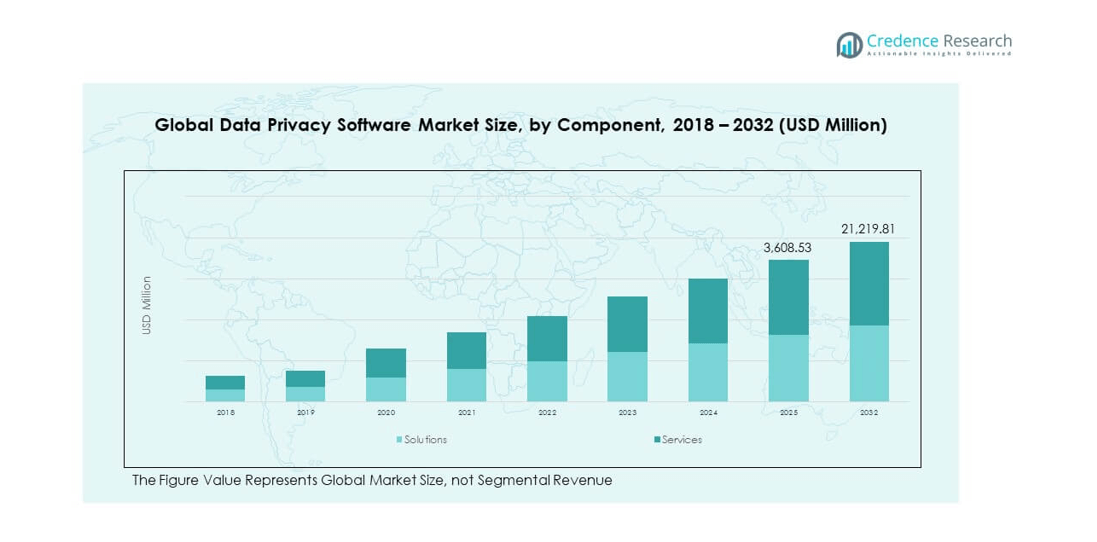
- By component, solutions dominated with 70% share in 2024 as enterprises adopted automated compliance and data governance platforms.
- Services accounted for 30% share in 2024, reflecting steady demand for consulting, integration, and training support to strengthen compliance strategies.
Market Drivers
Increasing Enforcement of Data Protection Regulations Across Multiple Jurisdictions is Fueling Market Growth
The growing complexity of global data protection laws is a primary driver for the Global Data Privacy Software Market. Organizations across sectors are under pressure to comply with frameworks such as GDPR in Europe, CCPA in the United States, and evolving laws in Asia and Latin America. Enterprises face heavy fines and reputational risks when failing to comply with these strict regulations. It creates sustained demand for advanced privacy management platforms that automate compliance processes. Businesses seek solutions that can adapt to frequent changes in regulatory frameworks. Privacy software ensures data mapping, consent management, and monitoring are efficiently handled. Demand rises sharply as organizations expand across borders and manage multiple legal environments. This compliance necessity reinforces the rapid adoption of privacy-focused solutions across industries.
- For instance, OneTrustreported supporting over thousands of organizations in automating compliance with regulations like GDPR and CCPA, processing more than 1.5 billion consent preferences annually to help enterprises maintain regulatory conformity across jurisdictions.
Rising Incidents of Cyber Threats and Data Breaches are Driving the Adoption of Privacy Software
High-profile cyberattacks and frequent data breaches have become a significant concern for global enterprises. Businesses are realizing the financial and reputational damage associated with data theft and misuse. It strengthens the role of privacy software as an essential safeguard. Tools that monitor access, detect vulnerabilities, and secure sensitive customer data are gaining rapid deployment. The Global Data Privacy Software Market is expanding as organizations shift from reactive security measures to proactive data protection. Enterprises are allocating larger budgets for cybersecurity and compliance solutions. Demand is particularly strong in sectors handling sensitive data such as healthcare, BFSI, and retail. This trend underscores the critical role of privacy solutions in modern business strategies.
Growing Consumer Awareness About Data Protection and Rights is Influencing Enterprise Adoption
Consumers today are more informed about their rights concerning data usage and privacy. This shift in consumer expectations forces businesses to adopt transparency in data handling practices. Organizations are under pressure to offer consent management tools and provide visibility into how data is collected and stored. It increases the reliance on data privacy software to build trust and enhance customer loyalty. The Global Data Privacy Software Market benefits from this heightened awareness, as companies prioritize ethical data use. Failure to meet these expectations often leads to consumer distrust and loss of market credibility. Businesses now integrate privacy software into their customer experience strategies. This integration ensures compliance and strengthens brand reputation in competitive industries.
Expanding Digital Transformation and Cloud Adoption are Driving Demand for Scalable Privacy Solutions
The accelerated pace of digital transformation across industries has multiplied the amount of sensitive data being processed. Cloud computing, big data analytics, and remote work models expose businesses to higher privacy risks. Enterprises require scalable and flexible privacy solutions that can operate across hybrid and multi-cloud environments. It drives strong adoption of cloud-native privacy management tools. The Global Data Privacy Software Market is witnessing demand from companies modernizing their IT infrastructure while maintaining compliance. Privacy tools are now embedded into digital transformation roadmaps. Sectors such as e-commerce, fintech, and telecom lead adoption due to high volumes of customer data. This alignment between transformation and privacy underscores the software’s strategic importance.
- For instance, Microsoft Azure provides a comprehensive data privacy framework that leverages services like Microsoft Purview for classification, Azure Policy for restrictions, and Dynamic Data Masking for data obfuscation.
Market Trends
Integration of Artificial Intelligence and Automation is Transforming Privacy Software Capabilities
Vendors are embedding artificial intelligence and machine learning into privacy solutions to improve accuracy and efficiency. Automated tools enable faster identification of sensitive data across diverse systems. It supports predictive risk assessment and enhances real-time compliance management. The Global Data Privacy Software Market is experiencing a shift toward AI-driven governance frameworks. Organizations value automation that reduces manual efforts in data mapping and auditing. AI-enabled analytics also allow for continuous monitoring of compliance across multiple jurisdictions. These capabilities help businesses scale data protection efforts in dynamic digital environments. The trend positions AI as a core driver of innovation in the privacy domain.
- For instance, TrustArc launched its AI Autofill capability in June 2024, and company data confirms it has been used more than 13,500 times by enterprise clients to streamline compliance record creation and privacy process mapping.
Increasing Adoption of Privacy Software as a Service Model Among Enterprises
Cloud-delivered privacy solutions are becoming the preferred choice for many businesses. Organizations seek cost-effective, flexible, and quickly deployable platforms to manage compliance. It drives demand for privacy software offered through subscription-based models. The Global Data Privacy Software Market benefits as vendors focus on SaaS offerings with scalable functionalities. Enterprises appreciate the reduced need for in-house IT resources and simplified updates. SaaS platforms also allow small and medium enterprises to access advanced compliance tools. The growing hybrid work culture further reinforces this trend. It highlights the industry’s shift toward delivering privacy as an accessible, service-oriented solution.
Consolidation and Strategic Collaborations Among Vendors are Shaping Market Dynamics
The competitive landscape is witnessing increased mergers, acquisitions, and partnerships. Companies aim to expand their product portfolios and geographic reach through strategic alliances. It strengthens the ability to provide integrated and comprehensive privacy management platforms. The Global Data Privacy Software Market shows momentum as vendors collaborate with cybersecurity firms and cloud service providers. Consolidation also fosters innovation by combining complementary expertise. Enterprises prefer vendors that can deliver end-to-end compliance solutions. This trend indicates a maturing industry moving toward larger ecosystems of privacy and security integration. Partnerships ensure that software remains relevant in complex digital landscapes.
- For instance, BigID was selected as a launch partner for AWS’s Data & AI Governance and Security initiative, which was announced at AWS re:Invent 2024. BigID officially announced its partnership via a press release in May 2025, confirming the development of its connector for Amazon SageMaker AI to enhance data governance and security in AI workloads.
Industry-Specific Customization of Privacy Software is Becoming a Growing Trend
Enterprises in different sectors require tailored privacy solutions aligned with their operational needs. Healthcare organizations prioritize patient data security, while financial institutions demand regulatory-driven compliance. It has led to vendors offering industry-focused modules and customizable features. The Global Data Privacy Software Market is evolving toward solutions designed for specific verticals. Businesses prefer software that aligns with sectoral compliance frameworks. Vendors differentiate themselves by addressing niche requirements in industries like education, retail, and government. This trend highlights the movement toward specialized offerings rather than generic tools. Industry-focused solutions enhance trust and efficiency for businesses navigating unique challenges.
Market Challenges Analysis
Rising Complexity of Multi-Jurisdictional Compliance is Creating Barriers for Enterprises
Organizations face significant challenges in aligning with the varying requirements of multiple regulatory frameworks. Laws such as GDPR, HIPAA, and regional privacy rules differ widely in scope and enforcement. It forces businesses to invest heavily in software customization and legal expertise. The Global Data Privacy Software Market experiences slower adoption in small enterprises due to high compliance costs. Companies also struggle to keep pace with frequent updates in privacy legislation. Lack of uniform global standards adds another layer of difficulty for multinational firms. Enterprises risk financial penalties and reputational harm when compliance gaps occur. These hurdles create friction for businesses aiming to scale privacy efforts effectively.
Limited Awareness and Integration Challenges are Restricting the Adoption of Privacy Software
Many organizations still lack comprehensive awareness of modern privacy risks and the solutions available to address them. It restricts the widespread adoption of advanced privacy tools. The Global Data Privacy Software Market encounters challenges where businesses depend on outdated manual processes. Integrating privacy software with existing IT infrastructure is often complex and resource-intensive. Enterprises may face resistance from employees unaccustomed to new systems. Budget constraints in smaller organizations further limit adoption rates. Inadequate training and shortage of skilled privacy professionals compound these challenges. These barriers delay the realization of full benefits that modern privacy software can deliver.
Market Opportunities
Expansion of Data Protection Regulations in Emerging Economies is Creating Strong Market Potential
Emerging economies are introducing robust data protection frameworks to align with global standards. Countries in Asia, Latin America, and the Middle East are implementing stricter compliance mandates. It creates new opportunities for vendors offering scalable and cost-effective privacy solutions. The Global Data Privacy Software Market stands to benefit as businesses in these regions seek compliance support. Enterprises in developing markets require localized software with regional language and legal compatibility. Vendors can capture growth by tailoring offerings for these fast-developing economies. The introduction of new laws ensures a long-term demand base for compliance-driven privacy tools.
Rising Demand for Privacy-Centric Digital Transformation Strategies is Opening New Avenues
Organizations worldwide are embedding data privacy into their digital transformation initiatives. It aligns compliance with broader modernization objectives. The Global Data Privacy Software Market gains traction as businesses integrate privacy into customer experience strategies. Enterprises see data protection as a competitive differentiator that enhances trust and brand value. Vendors providing software with seamless integration across digital platforms capture significant growth. Industries with high consumer engagement, such as e-commerce and fintech, highlight demand for privacy tools. This creates opportunities for vendors to design privacy-first digital ecosystems. The growing synergy between digital innovation and compliance broadens the market’s expansion pathway.
Market Segmentation Analysis:
The Global Data Privacy Software Market is structured
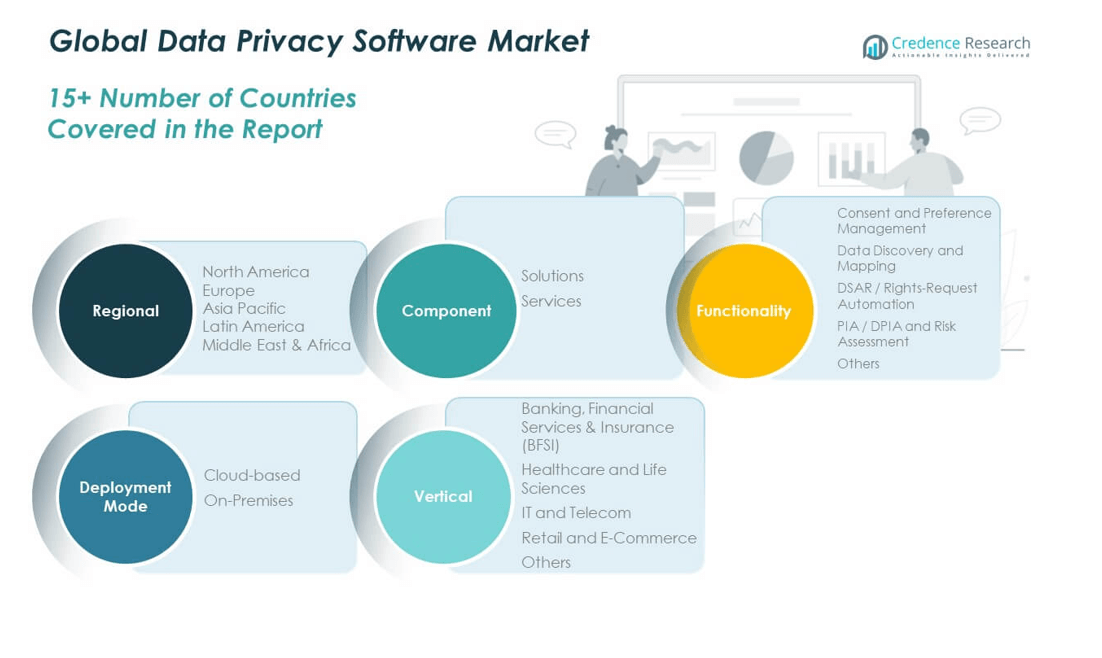
By component into solutions and services. Solutions dominate as organizations prioritize automated compliance platforms and data protection frameworks. Services support these deployments through consulting, integration, and training, enabling enterprises to maximize efficiency.
- For instance, OneTrust’s Compliance Automation Platform supports over 50 out-of-the-box regulatory frameworks, such as GDPR and ISO 27001, and utilizes AI for project management, automated evidence collection, and reporting.
By functionality, the market covers consent and preference management, data discovery and mapping, DSAR automation, PIA/DPIA risk assessments, and other specialized modules. Each function addresses specific regulatory and operational requirements, ensuring comprehensive privacy management.
By deployment mode divides the market into cloud-based and on-premises segments. Cloud-based models hold strong appeal due to scalability, flexibility, and compatibility with hybrid environments. On-premises solutions remain relevant in industries with stricter control needs, such as government and defense.
By vertical, BFSI represents a leading adopter due to heavy regulatory oversight and high sensitivity of financial data. Healthcare and life sciences follow, driven by the protection of patient records and HIPAA compliance. IT and telecom embrace privacy tools to secure vast data flows and maintain service trust. Retail and e-commerce sectors emphasize consent management to safeguard customer interactions. Other industries, including education and government, continue to strengthen demand through broad digitalization initiatives. This segmentation highlights a balanced yet diverse adoption landscape across industries and technologies.
- For instance, the BFSI sector accounted for 23.0% of the privacy management software market share in 2023. This dominance is driven by the industry's need to protect sensitive customer data and comply with stringent regulatory requirements, such as GDPR, CCPA, and GLBA.
Segmentation:
By Component
- Solutions
- Services
By Functionality
- Consent and Preference Management
- Data Discovery and Mapping
- DSAR / Rights-Request Automation
- PIA / DPIA and Risk Assessment
- Others
By Deployment Mode
- Cloud-based
- On-Premises
By Vertical
- Banking, Financial Services & Insurance (BFSI)
- Healthcare and Life Sciences
- IT and Telecom
- Retail and E-Commerce
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Global Data Privacy Software Market size was valued at USD 271.44 million in 2018 to USD 1,226.59 million in 2024 and is anticipated to reach USD 9,315.71 million by 2032, at a CAGR of 28.8% during the forecast period. North America holds the largest share of the Global Data Privacy Software Market, accounting for 43.9% of global revenue in 2024. Strong regulatory enforcement, including frameworks such as CCPA and HIPAA, drives enterprise adoption. It benefits from high technology maturity and strong investment in data protection tools. Financial institutions, healthcare providers, and e-commerce platforms lead implementation across industries. Vendors in the region emphasize AI-enabled platforms and integrated compliance solutions. The widespread use of cloud computing further boosts demand for scalable privacy management tools. Continuous innovation and strong government oversight sustain North America’s dominant role in shaping market expansion.
Europe
The Europe Global Data Privacy Software Market size was valued at USD 114.96 million in 2018 to USD 496.22 million in 2024 and is anticipated to reach USD 3,418.89 million by 2032, at a CAGR of 27.3% during the forecast period. Europe commands 17.7% of global market share in 2024, supported by strict enforcement of GDPR. The region maintains strong consumer awareness of data rights, influencing enterprise adoption. It emphasizes transparency and accountability in data management across verticals such as BFSI and healthcare. Multinational companies deploy privacy software to align with multi-country compliance requirements. Vendors develop industry-specific solutions to address complex regional regulations. The expansion of e-commerce and digital platforms sustains steady adoption. Europe remains a critical hub for regulatory innovation and compliance-driven growth.
Asia Pacific
The Asia Pacific Global Data Privacy Software Market size was valued at USD 178.78 million in 2018 to USD 861.44 million in 2024 and is anticipated to reach USD 7,111.08 million by 2032, at a CAGR of 30.2% during the forecast period. Asia Pacific represents 30.7% of the global market in 2024, making it the fastest-growing region. Countries like China, India, and Japan lead adoption, supported by expanding digital economies and evolving data protection laws. It benefits from the rapid growth of e-commerce, fintech, and telecom industries. Regional governments are enacting stricter privacy frameworks, accelerating demand for compliance tools. Enterprises invest in cloud-based platforms to handle cross-border data flows. Growing consumer awareness strengthens enterprise investments in transparency and trust. Asia Pacific’s scale and pace of digital transformation position it as a growth engine for global expansion.
Latin America
The Latin America Global Data Privacy Software Market size was valued at USD 27.14 million in 2018 to USD 122.27 million in 2024 and is anticipated to reach USD 812.35 million by 2032, at a CAGR of 26.7% during the forecast period. Latin America accounts for 4.4% of the global market share in 2024. Regulatory frameworks such as Brazil’s LGPD influence enterprise investment in privacy tools. It records growing adoption in financial services, retail, and healthcare. Cloud deployments gain traction as businesses modernize IT infrastructure. Rising cyber threats drive demand for advanced compliance solutions. Regional enterprises face challenges of limited awareness but continue to expand investments. Latin America’s regulatory developments and increasing digital penetration provide growth momentum.
Middle East
The Middle East Global Data Privacy Software Market size was valued at USD 14.87 million in 2018 to USD 61.15 million in 2024 and is anticipated to reach USD 378.30 million by 2032, at a CAGR of 25.5% during the forecast period. The region contributes 2.2% of global revenue in 2024. Countries such as the UAE, Israel, and Saudi Arabia lead adoption, driven by national cybersecurity initiatives. It benefits from government focus on digital economy expansion and data protection. Banking, telecom, and government sectors prioritize advanced privacy frameworks. Cloud adoption grows with investments in smart city projects. Vendors expand regional presence through partnerships and localized compliance solutions. Rising data-driven services create demand for scalable privacy platforms. Middle East adoption is strengthening through regulatory alignment and economic diversification strategies.
Africa
The Africa Global Data Privacy Software Market size was valued at USD 6.45 million in 2018 to USD 33.98 million in 2024 and is anticipated to reach USD 183.49 million by 2032, at a CAGR of 23.4% during the forecast period. Africa holds 1.2% of the global market in 2024. South Africa and Egypt lead adoption with early regulatory frameworks. It faces slower growth due to limited resources and low awareness of privacy risks. Expanding internet penetration and mobile-driven economies create opportunities for adoption. Cloud-based platforms attract interest due to affordability and scalability. Regional governments are strengthening data protection laws to align with global practices. BFSI and telecom sectors remain primary adopters. Africa presents long-term potential as awareness and regulatory maturity improve.
Key Player Analysis:
- OneTrust
- AvePoint
- TrustArc
- IBM Corporation
- RSA Security
- Informatica
- Cisco
- Microsoft
- Oracle
- Symantec
- Egnyte
- Box Zones
Competitive Analysis:
The Global Data Privacy Software Market is highly competitive, with established technology firms and specialized vendors driving innovation. Leading players such as OneTrust, TrustArc, AvePoint, IBM, Microsoft, and Cisco focus on delivering comprehensive compliance platforms that integrate automation, risk assessment, and consent management. It is shaped by continuous product launches, mergers, and strategic collaborations aimed at expanding portfolios and global reach. Companies emphasize AI-driven tools, cloud-native solutions, and industry-specific modules to differentiate offerings. Market share is concentrated among top vendors, but regional firms are emerging with localized compliance expertise. Demand from regulated sectors like BFSI, healthcare, and telecom drives vendor partnerships with enterprises seeking scalable solutions. Intense competition pushes providers to strengthen value propositions around transparency, adaptability, and regulatory alignment. This dynamic competitive landscape ensures continuous innovation and a focus on long-term customer trust.
Recent Developments:
- In August 2025, Cloud Software Group moved to acquire Arctera, a data management and protection provider born from the Veritas–Cohesity merger. The deal, set to close in Q4 2025, aims to strengthen data resilience, compliance, and protection offerings.
- In June 2025, OneTrust expanded its integration with Databricks to launch a new Data Policy Enforcement product integration. This update enables governance teams to automate data policy enforcement using Unity Catalog within AI‑driven systems.
- In April 2025, OneTrust unveiled new AI innovations designed to help teams scale operations, boost efficiency, and respond faster while maintaining privacy governance and control
Report Coverage:
The research report offers an in-depth analysis based on Component, Functionality, Deployment Mode and Vertical. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Data Privacy Software Market will expand as regulatory complexity increases across developed and emerging economies.
- Enterprises will prioritize cloud-native privacy platforms to support hybrid and multi-cloud environments.
- AI and automation will become central to data discovery, mapping, and risk management.
- Industry-specific privacy solutions will gain traction in sectors such as healthcare, BFSI, and retail.
- Vendors will strengthen global footprints through mergers, acquisitions, and regional partnerships.
- Small and medium enterprises will adopt scalable SaaS-based models to meet compliance needs.
- Consumer demand for transparency will push companies to integrate privacy into customer engagement strategies.
- Privacy software will evolve into a core element of digital transformation roadmaps.
- Cybersecurity integration with privacy tools will enhance enterprise resilience against breaches.
- Regional markets in Asia Pacific and Latin America will emerge as high-growth frontiers for adoption.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Enforcement of Data Protection Regulations
The proliferation of stringent data protection laws such as GDPR, CCPA, and regional frameworks in Asia and Latin America is compelling organizations to adopt privacy software to automate compliance and avoid heavy penalties.
Rising Incidents of Cyber Threats and Data Breaches
Frequent high-profile data breaches and cyberattacks have heightened the need for robust privacy software that can monitor, detect, and secure sensitive data, driving adoption across sectors handling critical information.
Growing Consumer Awareness About Data Rights
Consumers are increasingly aware of their data privacy rights, pressuring enterprises to implement transparent data handling and consent management solutions, which boosts demand for privacy software.
Expanding Digital Transformation and Cloud Adoption
The shift to cloud computing, big data analytics, and remote work has increased the volume and complexity of data, necessitating scalable privacy management tools that can operate across hybrid and multi-cloud environments.
Integration of AI and Automation in Privacy Management
Vendors are embedding AI and automation into privacy software to enhance data discovery, risk assessment, and compliance monitoring, enabling enterprises to efficiently manage privacy across dynamic digital landscapes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Data Privacy Software Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Data Privacy Software Market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the Global Data Privacy Software Market?
Who are the leading companies in the Global Data Privacy Software Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vertical
- 1.2.1 Banking, Financial Services & Insurance (BFSI)
- 1.2.2 Healthcare and Life Sciences
- 1.2.3 IT and Telecom
- 1.2.4 Retail and E-Commerce
- 1.2.5 Others
- 1.3 By Component
- 1.3.1 Solutions
- 1.3.2 Services
- 1.4 By Functionality
- 1.4.1 Consent and Preference Management
- 1.4.2 Data Discovery and Mapping
- 1.4.3 DSAR / Rights-Request Automation
- 1.4.4 PIA / DPIA and Risk Assessment
- 1.4.5 Others
- 1.5 By Deployment Mode
- 1.5.1 Cloud-based
- 1.5.2 On-Premises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,801.65 million → 2032: USD 21,219.81 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Data Privacy Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Data Privacy Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Data Privacy Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Data Privacy Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Data Privacy Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Data Privacy Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Data Privacy Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Data Privacy Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,801.65 million → 2032: USD 21,219.81 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Data Privacy Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vertical - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Banking, Financial Services & Insurance (BFSI)
- 12.3.6.2 Healthcare and Life Sciences
- 12.3.6.3 IT and Telecom
- 12.3.6.4 Retail and E-Commerce
- 12.3.6.5 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Solutions
- 12.4.6.2 Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Functionality - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Consent and Preference Management
- 12.5.6.2 Data Discovery and Mapping
- 12.5.6.3 DSAR / Rights-Request Automation
- 12.5.6.4 PIA / DPIA and Risk Assessment
- 12.5.6.5 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Cloud-based
- 12.6.6.2 On-Premises
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Data Privacy Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Data Privacy Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Data Privacy Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Data Privacy Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 OneTrust
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 AvePoint
- 18.4 TrustArc
- 18.5 IBM Corporation
- 18.6 RSA Security
- 18.7 Informatica
- 18.8 Cisco
- 18.9 Microsoft
- 18.10 Oracle
- 18.11 Symantec
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

