
Market Overview:
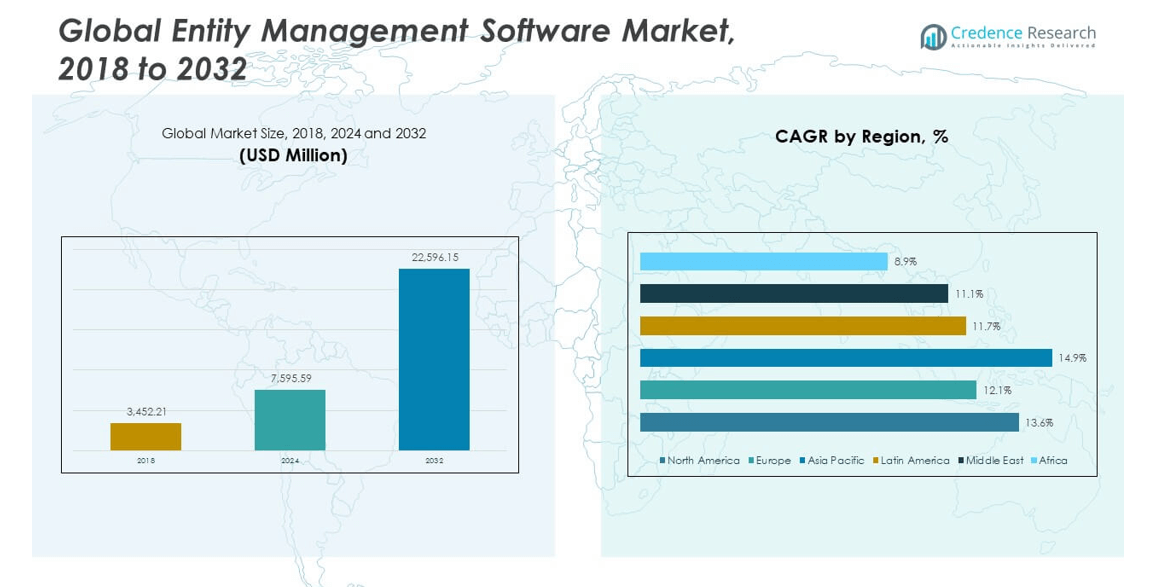
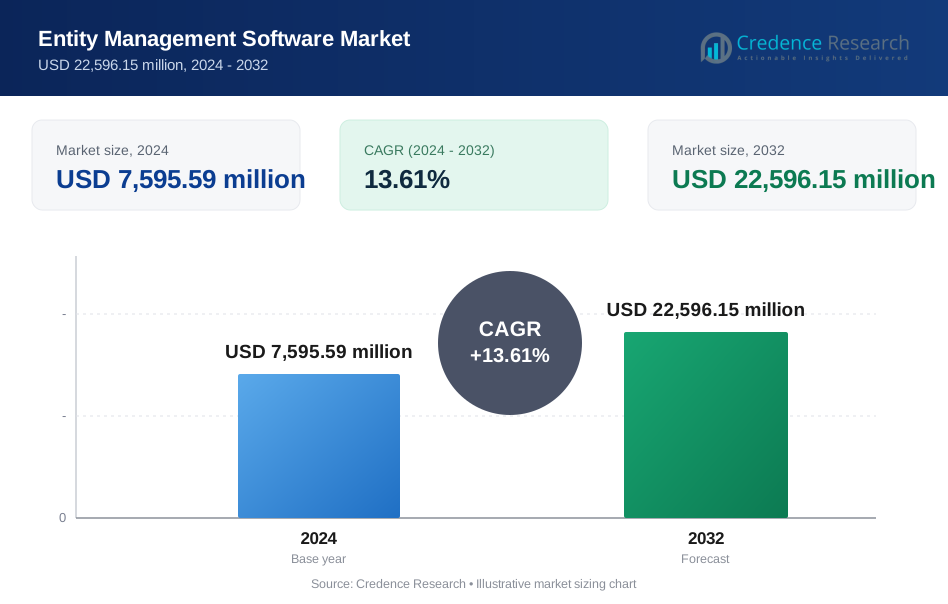
The Global Entity Management Software Market size was valued at USD 3,452.21 million in 2018 to USD 7,595.59 million in 2024 and is anticipated to reach USD 22,596.15 million by 2032, at a CAGR of 13.61% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Entity Management Software Market Size 2024 | USD 7,595.59 million |
| Entity Management Software Market, CAGR | 13.61% |
| Entity Management Software Market Size 2032 | USD 22,596.15 million |
Market growth is driven by rising regulatory complexity, rapid digital transformation, and increased adoption of compliance automation platforms. Companies are focusing on improving governance structures, automating entity lifecycle management, and ensuring transparency across jurisdictions. Cloud-based deployment and AI-powered features are accelerating adoption. It supports legal and compliance teams in managing large entity portfolios while improving operational efficiency, accuracy, and risk management in regulated industries.
North America leads the market due to strong legal technology infrastructure, advanced regulatory frameworks, and early cloud adoption. Europe holds a significant share, supported by strict compliance standards. Asia Pacific is an emerging region, driven by rising foreign investments and growing business expansion. Latin America, the Middle East, and Africa show steady adoption, supported by ongoing modernization of governance and compliance systems
Market Insights:
- The Global Entity Management Software Market size was valued at USD 3,452.21 million in 2018, reached USD 7,595.59 million in 2024, and is projected to hit USD 22,596.15 million by 2032 at a CAGR of 13.61%.
- North America leads with 45.8% market share, supported by advanced legal infrastructure and early cloud adoption. Europe follows with 19.8% due to strict compliance frameworks, while Asia Pacific holds 33% with strong enterprise expansion and regulatory modernization.
- Asia Pacific is the fastest-growing region, driven by rapid digital transformation, foreign investment, and expanding multinational operations across China, India, and Japan.
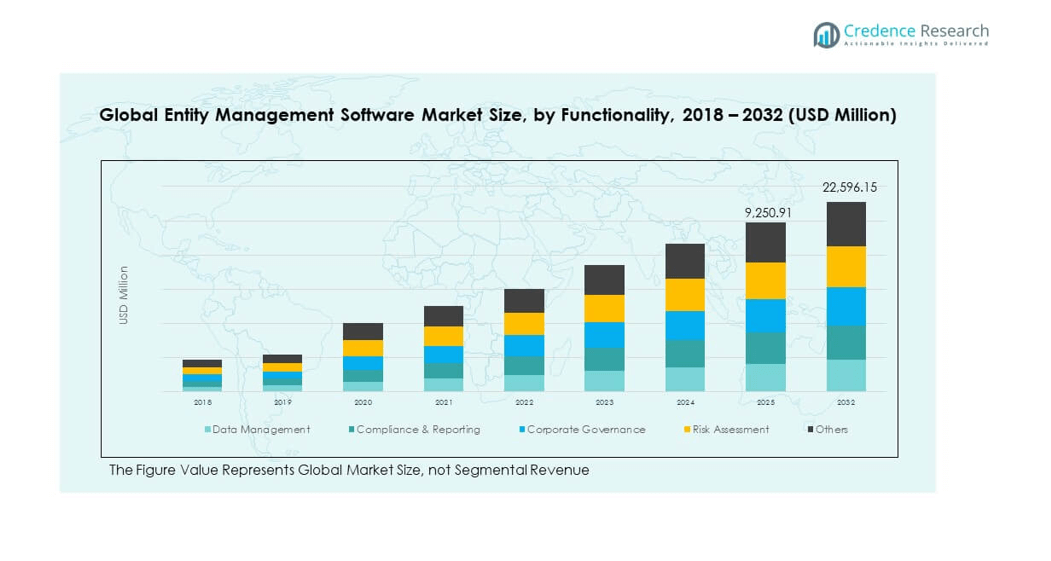
- Data management dominates the functionality segment with 32% share, reflecting its role in centralizing legal records and improving governance.
- Compliance & reporting accounts for 26%, followed by corporate governance and risk assessment, supported by rising regulatory requirements and cross-border business expansion.
Market Drivers
Rising Regulatory Complexity and Expanding Corporate Structures Driving Demand for Advanced Compliance Solutions
The Global Entity Management Software Market is witnessing rapid growth due to increasing regulatory complexity across jurisdictions. Companies face frequent changes in tax, corporate, and data governance regulations, which drive the need for centralized compliance solutions. It enables enterprises to maintain legal accuracy, reduce compliance risks, and manage entity lifecycles more efficiently. The rise in multinational operations makes traditional manual methods unsustainable. Automated reporting and governance systems enhance transparency and control. Legal teams benefit from real-time updates and streamlined documentation workflows. Industries with high compliance burdens adopt these platforms at a faster pace. Growing cross-border trade and investment further strengthen this driver.
Increasing Digital Transformation and Shift Toward Automated Legal Operations Across Enterprises
Enterprises are investing heavily in digital transformation initiatives to improve operational efficiency and governance transparency. The Global Entity Management Software Market benefits from this shift as organizations modernize legal and compliance systems. It supports automation of reporting tasks, reducing manual intervention and errors. Companies gain better visibility over complex entity networks through integrated dashboards. Cloud infrastructure enables secure access and collaboration across multiple geographies. Automated workflows also accelerate document approvals and legal sign-offs. Legal and compliance teams reduce administrative overhead, improving strategic decision-making. Strong emphasis on efficiency and data accuracy pushes adoption further.
Adoption of Cloud and AI Technologies Enhancing Real-Time Visibility and Governance Control
The integration of AI and cloud computing is reshaping the legal technology landscape. The Global Entity Management Software Market leverages these technologies to deliver intelligent automation and faster compliance processing. It allows enterprises to gain real-time visibility over their legal entities and governance structures. Cloud-based deployment improves accessibility, scalability, and system reliability. AI-powered features strengthen risk management and predictive analysis. Companies achieve better regulatory alignment through automated alerts and data validation. This driver creates opportunities for agile and efficient compliance operations. Organizations in regulated industries are leading adopters of these advanced technologies.
- For example, in 2025, Athennian expanded its automation capabilities to enhance entity creation and legal document processing, aiming to improve efficiency and compliance workflows for enterprise users.
Strategic Emphasis on Risk Mitigation and Data Accuracy Across Multinational Enterprises
Risk management is a key priority for enterprises operating across multiple jurisdictions. The Global Entity Management Software Market addresses this by providing structured data governance frameworks. It minimizes legal exposure and financial penalties by ensuring timely compliance. Integrated reporting tools enhance data accuracy, reducing operational inefficiencies. Legal departments can monitor changes in entity structures more effectively. Real-time audit trails support regulatory inspections and governance reviews. Risk mitigation also improves investor confidence and board accountability. The growing complexity of international business drives companies toward automated governance systems. This factor continues to be a strong catalyst for sustained market growth.
- For example, in 2025, Mitratech continued to enhance its Governance, Risk & Compliance platform with AI-driven capabilities. The company focuses on improving evidence validation, predictive modeling, and risk assessment to support faster compliance and stronger audit controls for enterprises.
Market Trends
Expansion of AI-Driven Automation to Streamline Compliance and Governance Functions
AI capabilities are advancing across enterprise governance platforms. The Global Entity Management Software Market is seeing wider integration of AI-driven automation for compliance, reporting, and workflow orchestration. It supports predictive analytics to detect potential risks early. Companies use natural language processing and intelligent bots to accelerate data handling. Automated reporting improves regulatory accuracy and audit preparedness. Predictive governance models reduce reliance on manual legal tasks. AI also enables dynamic risk scoring, enhancing operational security. The focus on automation aligns with broader enterprise technology strategies across industries.
Increased Integration of Entity Management Platforms with Enterprise Resource Planning Systems
Organizations are integrating entity management platforms with ERP solutions to create unified operational ecosystems. The Global Entity Management Software Market benefits from this trend, which enhances data consistency and regulatory visibility. It connects legal, finance, and compliance data into a single source of truth. Such integration improves decision-making through shared analytics. Enterprises eliminate data silos and streamline reporting processes. Real-time synchronization improves accuracy across legal and financial records. This trend supports more transparent governance frameworks. Seamless integration strengthens strategic planning and compliance agility.
- For instance, in September 2025, PwC and SAP successfully implemented one of the largest global ERP transformations, connecting more than 100,000 PwC professionals across 19 countries through SAP Cloud ERP, SAP Business Technology Platform, and SAP Analytics Cloud.
Rising Demand for Cloud-Native Solutions Supporting Global Expansion Strategies
Cloud-native entity management platforms are gaining prominence among multinational enterprises. The Global Entity Management Software Market is experiencing a surge in demand for scalable, location-agnostic solutions. It enables organizations to support expansion into new markets with minimal infrastructure investment. Cloud deployment accelerates onboarding and compliance configuration. Enterprises achieve better cross-border collaboration and system resilience. Security enhancements make cloud adoption more acceptable to regulated industries. This trend reflects a clear move toward flexibility and cost efficiency. Global firms are increasingly prioritizing cloud-first strategies in governance functions.
Increasing Focus on Data Security, Privacy, and Advanced Access Control Features
Data protection has become a critical trend shaping the legal technology landscape. The Global Entity Management Software Market is incorporating stronger encryption, access control, and compliance with evolving privacy regulations. It ensures secure handling of sensitive legal and financial data. Enterprises adopt role-based access systems to strengthen governance structures. Integration of blockchain and digital signatures enhances document authenticity. Compliance teams are prioritizing zero-trust architectures. Strong security measures increase trust among stakeholders and regulators. This trend reflects rising pressure from global cybersecurity frameworks.
- For example, the Cloud Signature Consortium (CSC) has developed API specifications, including version 2.0, designed to support compliance with the EU’s eIDAS regulation. The CSC standard enables interoperability between remote signing services and digital applications, strengthening the legal validity of electronic signatures in the European Union.
Market Challenges Analysis
Regulatory Fragmentation and Constantly Evolving Compliance Landscape Across Jurisdictions
The Global Entity Management Software Market faces regulatory fragmentation as a key challenge. Jurisdictions vary widely in their compliance structures, making standardization difficult. It forces enterprises to invest in frequent system updates and legal adaptation. Diverging tax, corporate, and data laws increase operational complexity. Software providers must offer customizable solutions to address varying legal frameworks. Constant regulatory change requires continuous monitoring and integration. Legal teams face difficulties in aligning global operations with local requirements. The lack of uniform compliance structures delays deployment timelines and raises costs.
Integration Barriers, Skill Gaps, and High Implementation Costs in Traditional Enterprise Environments
Adoption challenges remain significant across industries with limited digital maturity. The Global Entity Management Software Market encounters integration issues when aligning with legacy systems. It increases project complexity and delays return on investment. Many organizations lack the internal expertise required to deploy and manage these solutions effectively. Training and change management become additional cost burdens. Limited IT budgets in some regions restrict access to advanced tools. Integration gaps can affect data consistency and reporting accuracy. These obstacles make it harder for smaller firms to adopt sophisticated platforms at scale.
Market Opportunities
Expansion of AI-Enabled Legal Tech Ecosystems Across Emerging Economies
The Global Entity Management Software Market has significant growth opportunities in emerging economies. It benefits from rapid digital transformation and increasing foreign investments. Governments are strengthening compliance frameworks, driving demand for governance platforms. AI integration creates opportunities for localized solutions tailored to regulatory environments. Legal tech providers can scale faster through partnerships and cloud deployments. Expanding SME adoption further supports market penetration. This creates strong potential for long-term growth and market diversification.
Development of Sector-Specific Solutions and Advanced Automation Capabilities
Sector-focused solutions present major opportunities for vendors targeting industries with complex regulatory landscapes. The Global Entity Management Software Market can leverage this by offering specialized platforms for BFSI, healthcare, and telecommunications. It allows enterprises to align compliance features with industry-specific needs. Automation capabilities reduce operational costs and increase system adaptability. Vendors focusing on interoperability and data security will gain strong competitive advantages. This opportunity enhances platform adoption and market depth across regions.
Market Segmentation Analysis:
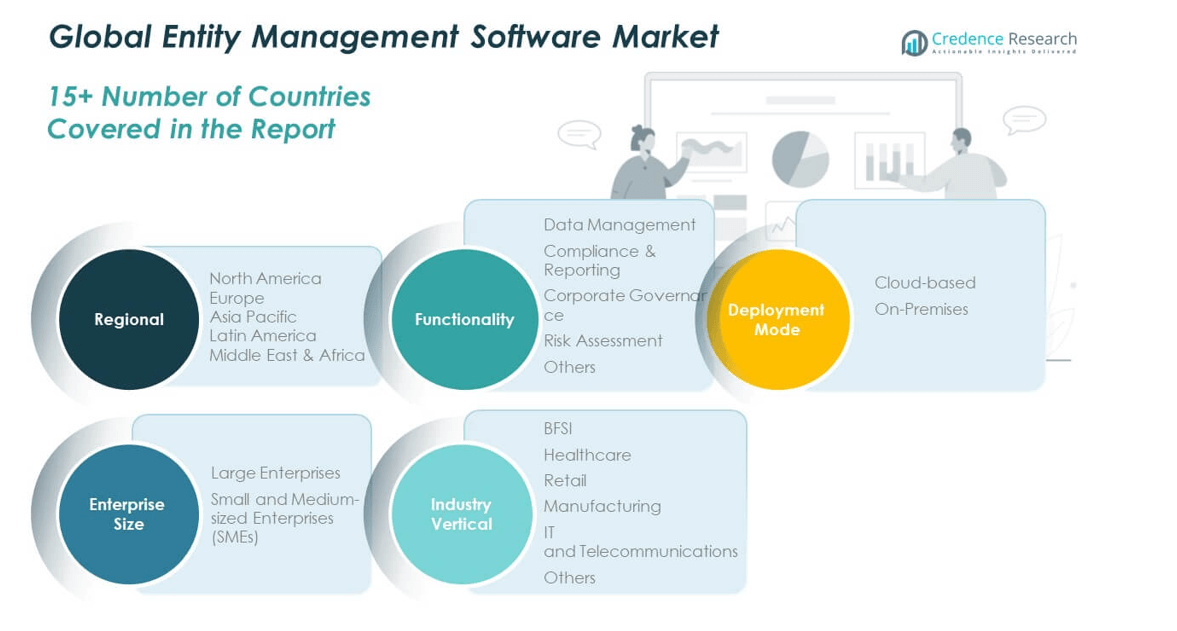
By functionality, data management plays a critical role in centralizing legal structures and enabling efficient entity tracking. Organizations rely on these tools to store corporate records, manage lifecycle data, and ensure structured reporting. Compliance and reporting solutions support alignment with regulatory frameworks and reduce legal risks. Corporate governance modules strengthen oversight and enhance decision-making. Risk assessment tools improve visibility into operational vulnerabilities, while other niche features expand adaptability and address specific compliance scenarios.
- For example, in June 2025, Diligent Corporation introduced AI-driven enhancements to its Diligent Entities platform, including Microsoft Teams integration, AI Report Generator, and automated document summarization. The company stated that its platform supports over 700,000 board members and 1 million users worldwide.
By deployment mode, cloud-based solutions hold the leading position. Companies prefer them for lower infrastructure costs, quick scalability, and remote accessibility. It enables seamless collaboration across multiple jurisdictions and departments. On-premises deployment remains significant among organizations prioritizing data sovereignty, internal control, and strict compliance. Both models serve distinct organizational needs, supporting a wide range of legal and operational frameworks.
- For example, Deloitte’s Cloud Transformation Services supported Heidelberger Druckmaschinen AG in digitalizing its global HR data across nearly 40 countries within 11 months. The transformation used Workday HCM to enhance agility and scalability in managing its international workforce.
By enterprise size, large enterprises dominate the market. Their complex global structures require advanced entity management capabilities and automated workflows. SMEs increasingly turn to affordable and flexible platforms to streamline compliance and governance. It reflects a steady shift toward cloud adoption, improving efficiency and reducing manual administrative work.
By industry vertical, BFSI accounts for a major share due to stringent compliance and reporting regulations. IT and telecommunications follow, driven by cross-border operations and dynamic legal frameworks. Healthcare, retail, and manufacturing show growing adoption, aiming for enhanced governance and operational visibility. Other industries adopt entity management solutions to strengthen oversight, reduce compliance risks, and improve corporate transparency.
Segmentation:
By Functionality
- Data Management
- Compliance & Reporting
- Corporate Governance
- Risk Assessment
- Others
By Deployment Mode
- Cloud-based
- On-Premises
By Enterprise Size
- Large Enterprises
- Small and Medium-sized Enterprises (SMEs)
By Industry Vertical
- BFSI
- Healthcare
- Retail
- Manufacturing
- IT and Telecommunications
- Others
By Regio
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
The North America Global Entity Management Software Market size was valued at USD 1,592.66 million in 2018 to USD 3,469.74 million in 2024 and is anticipated to reach USD 10,349.26 million by 2032, at a CAGR of 13.6% during the forecast period. North America holds a 45.8% market share. The region leads due to strong adoption of legal tech platforms and strict regulatory requirements. It benefits from advanced infrastructure, mature enterprise ecosystems, and early digital transformation. Organizations in the U.S. and Canada emphasize automated compliance to meet complex reporting standards. It is supported by well-established cloud infrastructure, driving faster implementation across industries. The presence of major technology providers further boosts growth. Companies integrate AI, data analytics, and governance solutions to enhance operational control. Regulatory pressures across sectors such as BFSI and healthcare continue to drive platform expansion.
Europe
The Europe Global Entity Management Software Market size was valued at USD 591.14 million in 2018 to USD 1,222.94 million in 2024 and is anticipated to reach USD 3,276.59 million by 2032, at a CAGR of 12.1% during the forecast period. Europe accounts for a 19.8% market share. The region’s growth is influenced by strong compliance standards and evolving corporate governance frameworks. It has a well-regulated business environment, supporting higher adoption rates across mid and large enterprises. Countries like the UK, Germany, and France lead demand due to structured legal reporting systems. Integration with existing enterprise applications is a key growth enabler. It benefits from a strong push toward digital legal transformation. Companies adopt these platforms to align with GDPR and cross-border reporting requirements. Legal complexity across EU markets creates consistent demand for entity management solutions.
Asia Pacific
The Asia Pacific Global Entity Management Software Market size was valued at USD 985.07 million in 2018 to USD 2,289.92 million in 2024 and is anticipated to reach USD 7,436.84 million by 2032, at a CAGR of 14.9% during the forecast period. Asia Pacific holds a 33% market share. The region is expanding rapidly due to rising foreign investments, complex entity structures, and digital adoption. Enterprises in China, India, Japan, and Australia prioritize compliance modernization to manage cross-border transactions. It benefits from strong growth in IT and manufacturing industries, driving governance technology use. Growing SME participation strengthens market reach. Governments encourage digital compliance frameworks, accelerating software adoption. Cloud-based solutions remain dominant due to cost efficiency and scalability. Strategic investments from global legal tech providers support platform localization and regional expansion.
Latin America
The Latin America Global Entity Management Software Market size was valued at USD 152.32 million in 2018 to USD 330.68 million in 2024 and is anticipated to reach USD 862.63 million by 2032, at a CAGR of 11.7% during the forecast period. Latin America represents a 3.8% market share. The region shows steady growth supported by compliance modernization and corporate digitalization efforts. Brazil leads the market, followed by Argentina, with rising interest from regional enterprises. It is influenced by increasing awareness of regulatory governance tools. Local firms and multinationals adopt cloud platforms to streamline reporting processes. Limited legal infrastructure in some economies creates demand for standardized digital tools. Regulatory modernization and trade liberalization are expected to sustain adoption. Legal tech startups and global vendors are expanding their regional footprint.
Middle East
The Middle East Global Entity Management Software Market size was valued at USD 94.02 million in 2018 to USD 188.58 million in 2024 and is anticipated to reach USD 470.62 million by 2032, at a CAGR of 11.1% during the forecast period. The Middle East accounts for a 2.1% market share. The market is driven by increasing investment in compliance infrastructure and economic diversification initiatives. GCC countries dominate demand, supported by modernization of regulatory frameworks. It benefits from growing adoption in sectors such as BFSI and energy. Enterprises prioritize risk management and corporate governance integration. Governments push for transparency and legal alignment with international standards. Cloud adoption strengthens accessibility and scalability. Strategic alliances with international legal tech vendors support faster deployment and skill development.
Africa
The Africa Global Entity Management Software Market size was valued at USD 37.00 million in 2018 to USD 93.73 million in 2024 and is anticipated to reach USD 200.19 million by 2032, at a CAGR of 8.9% during the forecast period. Africa holds a 0.9% market share. The region is at an early adoption stage, with growth driven by economic reforms and corporate structuring needs. South Africa leads the market, supported by a maturing legal technology ecosystem. It benefits from government initiatives encouraging digital compliance. Regulatory modernization and trade partnerships boost awareness of governance platforms. SMEs are exploring cloud-based solutions for cost efficiency. Infrastructure limitations pose short-term challenges, but regional investments continue to grow. International vendors are expanding partnerships to address emerging legal technology demand.
Key Player Analysis:
- IBM Corporation
- Oracle Corporation
- SAP SE
- Microsoft Corporation
- Salesforce, Inc.
- ServiceNow, Inc.
- AppFolio, Inc.
- Zoho Corporation
- Diligent Corporation
- Wolters Kluwer N.V.
Competitive Analysis:
The Global Entity Management Software Market is highly competitive with a strong presence of global and regional players. It is driven by rapid adoption of cloud solutions, digital governance tools, and compliance automation platforms. Companies such as IBM, Oracle, SAP, Microsoft, Salesforce, ServiceNow, AppFolio, Zoho Corporation, Diligent Corporation, and Wolters Kluwer lead the market through strategic product development and technology innovation. Vendors focus on integrating AI, workflow automation, and analytics to strengthen compliance visibility. Mergers, acquisitions, and regional expansion remain key strategies to capture emerging markets. Strong emphasis on security, scalability, and interoperability enhances competitive positioning. Growing demand for multi-jurisdiction entity management is pushing providers to deliver more advanced and adaptive solutions.
Recent Developments:
- In October 2025, IBM Corporation entered a major collaboration with the National University of Singapore (NUS) to launch the NUS-IBM Research and Innovation Centre on October 23, 2025. This center aims to advance breakthroughs in artificial intelligence and quantum computing applications. The strategic partnership integrates academic research with IBM’s technological expertise to accelerate cross-disciplinary development in AI, cloud, and data sciences across Asia.
- In October 2025, Oracle Corporation introduced the Fusion Applications AI Agent Marketplace on October 15, 2025. This platform integrates embedded AI agents into Oracle’s Fusion Cloud Applications Suite to automate multi-step business tasks across finance, HR, supply chain, and customer experience functions.
- In October 2025, Salesforce, Inc. deepened its collaboration with OpenAI through an expanded strategic partnership announced on October 14, 2025. This integration connects Salesforce’s Agentforce 360 with OpenAI’s frontier models, including GPT-5, allowing businesses to access Salesforce tools within ChatGPT.
- In September 2025, ServiceNow, Inc. introduced its new “AI Experience,” the interface for enterprise AI announced on September 30, 2025. This innovation provides integrated access to voice, text, and image-based AI agents across workflows. The same month, ServiceNow also released the “AI Platform Zurich” update, which strengthens enterprise-wide AI security, multi-agentic development environments, and accelerated AI deployment within corporate infrastructures.
Report Coverage:
The research report offers an in-depth analysis based on Functionality, Deployment Mode, Enterprise Size and Industry Vertical. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising regulatory complexity will push enterprises to expand entity management capabilities across multiple jurisdictions.
- Integration of AI and advanced analytics will enhance predictive compliance and governance.
- Cloud-based platforms will dominate new deployments due to scalability and cost advantages.
- Global expansion of multinational firms will increase demand for centralized legal and compliance visibility.
- Automation of reporting processes will reduce manual workloads and improve operational efficiency.
- Strategic alliances between legal tech vendors and enterprise software providers will strengthen ecosystem maturity.
- Rapid adoption in emerging economies will reshape competitive dynamics in the legal technology space.
- Sector-specific solutions for BFSI, healthcare, and IT will drive platform diversification.
- Enhanced cybersecurity features will become critical to address evolving compliance and privacy standards.
- Continuous investment in digital legal infrastructure will sustain long-term market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Entity Management Software Market, and what is its projected size in 2032?
The Global Entity Management Software Market size was valued at USD 7,595.59 million in 2024 and is projected to reach USD 22,596.15 million by 2032.
Which Global Entity Management Software Market segment held the largest sharein 2024?
What are the primary factors fueling the growth of the Global Entity Management Software Market?
Who are the leading companies in the Global Entity Management Software Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,595.59 million → 2032: USD 22,596.15 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Entity Management Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Entity Management Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Entity Management Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Entity Management Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Entity Management Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Entity Management Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Entity Management Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Entity Management Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,595.59 million → 2032: USD 22,596.15 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Entity Management Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Entity Management Software Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Entity Management Software Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Entity Management Software Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

