
Market Overview:
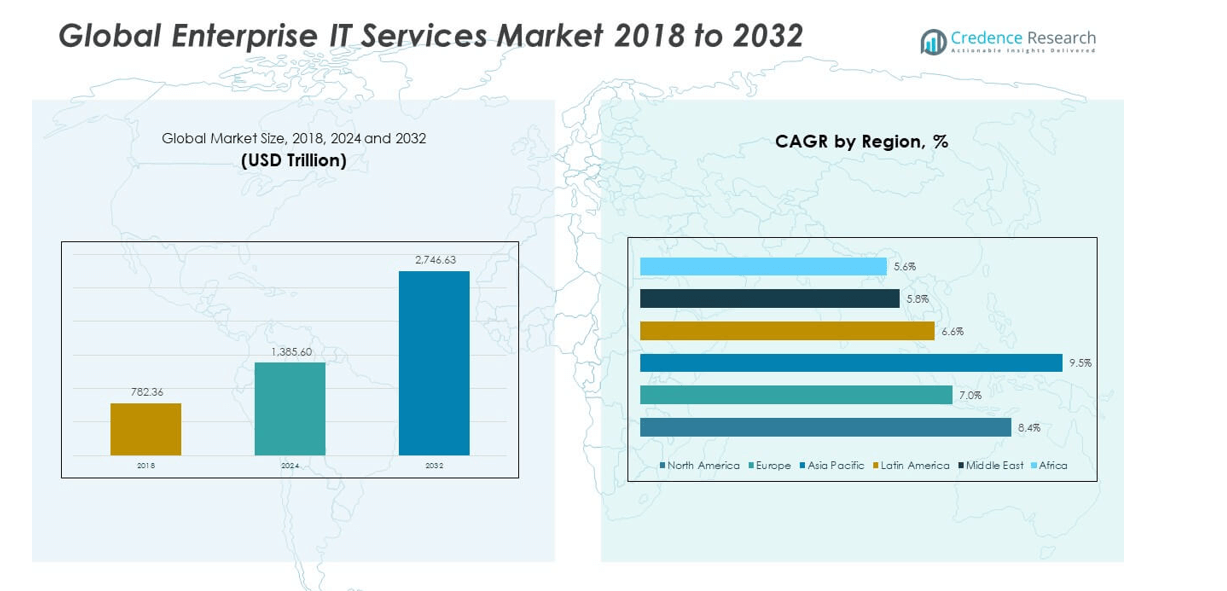
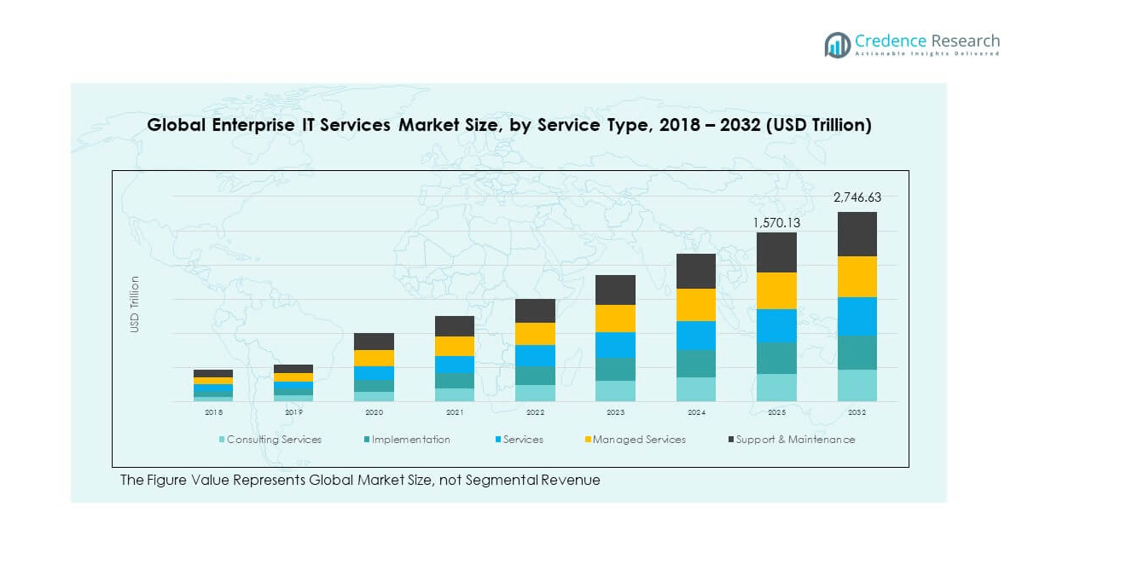
The Global Enterprise IT Services Market size was valued at USD 782.36 trillion in 2018 to USD 1,385.60 trillion in 2024 and is anticipated to reach USD 2,746.63 trillion by 2032, at a CAGR of 8.32% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Enterprise IT Services Market Size 2024 | USD 1,385.60 trillion |
| Enterprise IT Services Market, CAGR | 8.32% |
| Enterprise IT Services Market Size 2032 | USD 2,746.63 trillion |
Rising digital transformation initiatives, rapid cloud adoption, and growing automation drive strong market growth. Enterprises across industries are modernizing their IT infrastructure to improve efficiency and resilience. Demand for managed services and hybrid cloud solutions is increasing due to their cost-effectiveness and scalability. Cybersecurity, data modernization, and AI integration remain central priorities for organizations aiming to enhance competitiveness. These factors create favorable conditions for sustained market expansion and technological innovation.
North America leads the market with advanced digital infrastructure, strong enterprise IT investment, and high adoption of AI-driven solutions. Europe shows steady growth supported by regulatory compliance and hybrid cloud adoption. Asia Pacific is emerging rapidly, driven by digital initiatives in manufacturing, healthcare, and financial services. Latin America, the Middle East, and Africa are expanding gradually through modernization efforts and growing interest in IT outsourcing.
Market Insights:
- The Global Enterprise IT Services Market was valued at USD 782.36 trillion in 2018, reached USD 1,385.60 trillion in 2024, and is projected to attain USD 2,746.63 trillion by 2032, growing at a CAGR of 8.32%.
- North America leads with a 34.3% share, followed by Asia Pacific at 23.9% and Europe at 14.0%. Their dominance is driven by strong IT infrastructure, mature enterprise adoption, and high cloud investments.
- Asia Pacific is the fastest-growing region with a 23.9% share, supported by rapid digitalization, government-led initiatives, and increasing demand from large enterprises and SMEs.
- Managed services account for the largest segment share at 32%, reflecting rising demand for scalable IT support and cost optimization.
- Consulting services hold the second-largest share at 27%, driven by enterprise modernization strategies and strong adoption of digital transformation programs.
Market Drivers
Rising Digital Transformation Across Core Industries Enhances Technology Adoption
Enterprises across multiple industries are rapidly shifting toward digital-first strategies to modernize processes and improve customer engagement. This shift creates strong demand for managed IT services, cloud platforms, and infrastructure modernization. The Global Enterprise IT Services Market benefits from expanding investments in smart technologies, including AI, IoT, and blockchain. Companies aim to enhance agility, speed up product cycles, and improve security layers. It drives automation initiatives across manufacturing, retail, healthcare, and BFSI sectors. Legacy systems are being replaced by scalable, integrated platforms that reduce operational complexities. This digital wave strengthens vendor relationships and supports long-term contracts. The momentum reflects a decisive move toward technology-led competitiveness.
- For example, Siemens AG has implemented digital twin and IoT solutions at its Electronics Works Amberg facility in Germany. The site uses NavVis mobile mapping technology to create high-precision digital replicas of the factory, supporting real-time monitoring and operational optimization. This initiative reflects Siemens’ focus on smart manufacturing and advanced industrial automation.
Expanding Cloud Adoption and Hybrid Infrastructure Accelerate Market Expansion
Cloud adoption continues to rise as enterprises seek flexibility, cost efficiency, and reliable service delivery. Hybrid and multi-cloud models allow businesses to balance security with scalability. The Global Enterprise IT Services Market benefits from rising enterprise cloud budgets and stronger integration frameworks. Cloud migration services, managed infrastructure, and security layers form core priorities. Organizations are shifting workloads to cloud platforms for faster deployment and improved data resilience. It creates demand for cloud-native solutions that align with business continuity goals. This push increases collaborations between service providers and large enterprises. Broader adoption supports global competitiveness in complex digital environments.
- For example, Unilever partnered with Microsoft, Accenture, and Avanade to complete one of the largest cloud migrations in the consumer goods industry. The 18-month program transitioned the company to a fully cloud-only infrastructure on Microsoft Azure. This migration enhanced operational agility, strengthened innovation capabilities, and reduced the environmental impact of its IT operations.
Strong Cybersecurity Focus Fuels Investments in Advanced IT Solutions
Enterprises face growing cybersecurity threats that demand resilient and adaptive IT infrastructures. Rising attacks on enterprise networks accelerate spending on managed security services. The Global Enterprise IT Services Market grows through increased demand for endpoint protection, data encryption, and identity management. Advanced security solutions integrate with existing IT systems to ensure compliance with global standards. It pushes companies to enhance risk management strategies and adopt proactive defense systems. Continuous monitoring frameworks help reduce downtime and improve operational reliability. Regulatory mandates strengthen the need for advanced security architecture. These factors make cybersecurity a central growth pillar for IT service vendors.
Automation and AI Integration Boost Operational Agility and Scalability
Automation, AI, and analytics reshape enterprise operations by improving accuracy and decision-making speed. AI-driven platforms support predictive maintenance, workflow optimization, and cost control. The Global Enterprise IT Services Market gains momentum through intelligent automation tools that reduce manual tasks. AI chatbots and virtual assistants enhance enterprise service delivery. It enables real-time process tracking and rapid issue resolution. Automation also improves workforce productivity and strategic planning. Enterprises rely on intelligent systems to scale quickly without raising infrastructure costs. This trend accelerates service innovation and enhances digital maturity across industries.
Market Trends
Rising Demand for Industry-Specific IT Solutions Enhances Customization Capabilities
Industries increasingly seek IT solutions tailored to their unique operational needs. Custom platforms deliver stronger efficiency and integrate seamlessly with core systems. The Global Enterprise IT Services Market is witnessing rapid growth in vertical-specific offerings for healthcare, finance, manufacturing, and retail. Service providers develop domain-focused solutions that improve compliance and data security. It supports faster deployment and ensures better alignment with business goals. Industry-focused IT solutions help reduce integration gaps and improve ROI. This shift positions vendors as strategic partners rather than simple service providers. The trend accelerates adoption of niche IT services globally.
- For example, SuperAGI is an open-source autonomous AI framework designed to help enterprises build and deploy AI agents for decision-making and process automation. The platform focuses on enhancing operational efficiency through intelligent automation and advanced analytics. It is gaining attention for its flexibility and enterprise-focused AI capabilities.
Rapid Shift Toward Platform-Based Service Models Transforms Delivery Structure
Platform-based services enable enterprises to unify diverse functions into a single digital environment. These models support faster implementation and easier upgrades. The Global Enterprise IT Services Market is moving toward flexible subscription and platform ecosystems. Service providers offer integrated tools that reduce complexity and improve real-time visibility. It allows companies to adopt modular solutions that scale with business growth. Platform ecosystems foster stronger vendor-client collaborations and shorten deployment timelines. This structure improves cost predictability and enhances service reliability. Platform-based models are becoming a defining trend in global enterprise IT strategies.
- For example, ServiceNow offers an enterprise SaaS platform that delivers modular workflow automation across functions like finance, HR, and operations. The company is recognized for its strong global enterprise customer base and focus on high service availability through reliable uptime performance. Its platform plays a key role in driving digital transformation for large organizations.
Adoption of Edge Computing and 5G Infrastructure Reshapes Service Delivery
Edge computing is gaining momentum for its ability to lower latency and enhance real-time decision-making. Integration with 5G networks boosts speed and performance across industries. The Global Enterprise IT Services Market experiences rising interest in edge infrastructure deployment. Enterprises use edge solutions to process data closer to the source and reduce network congestion. It supports new use cases in manufacturing, logistics, and healthcare. Service providers are building specialized offerings around edge-optimized platforms. These developments align with the need for high-speed and low-latency operations. The trend improves operational continuity and service responsiveness.
Sustainability and Green IT Initiatives Gain Strategic Importance
Enterprises focus on reducing their carbon footprint and improving energy efficiency in IT infrastructure. Green data centers and energy-efficient cloud platforms are becoming a priority. The Global Enterprise IT Services Market sees increasing investments in sustainable IT operations. Service providers promote solutions that optimize energy use and reduce hardware waste. It aligns with global ESG and regulatory frameworks, enhancing corporate reputation. Sustainability initiatives also lower operational costs and boost long-term resilience. Companies are integrating eco-friendly technologies into their IT strategies. The trend strengthens responsible innovation across the enterprise technology landscape.
Market Challenges Analysis
Complex Integration of Legacy Systems with Modern Platforms Limits Transformation Speed
Many enterprises rely on outdated legacy systems that are difficult to integrate with modern technologies. This complexity slows digital transformation and increases operational risks. The Global Enterprise IT Services Market faces integration challenges that delay project timelines and raise costs. It requires specialized expertise to manage hybrid environments effectively. Incompatibility issues between legacy systems and advanced platforms limit automation potential. Security vulnerabilities in older infrastructure increase exposure to threats. Limited interoperability often forces businesses to invest in expensive middleware solutions. These factors create barriers to seamless IT modernization and impact scalability efforts.
High Skill Shortage and Rising Operational Costs Constrain Service Expansion
The industry faces a shortage of skilled professionals capable of managing advanced IT environments. Demand for cloud, AI, cybersecurity, and automation skills exceeds available talent. The Global Enterprise IT Services Market experiences pressure on cost structures due to rising wages and training needs. It pushes enterprises to rely more on third-party providers, creating dependency risks. Maintaining a balance between cost efficiency and service quality remains difficult. High operational costs also impact pricing strategies, especially for small and mid-sized firms. Talent gaps limit innovation speed and reduce flexibility in service delivery. These constraints make scaling operations more complex.
Market Opportunities
Rising IT Outsourcing Demand in Emerging Economies Creates Strong Growth Potential
Emerging economies are rapidly adopting digital transformation strategies across industries. Enterprises seek outsourcing partners to optimize costs and gain access to advanced technologies. The Global Enterprise IT Services Market benefits from this shift through expanded service contracts. It allows vendors to strengthen their presence in fast-growing regions. Outsourcing demand drives new partnerships, infrastructure investments, and service diversification. This trend creates opportunities for local and global players to expand capabilities. Growing digitalization in SMEs accelerates outsourcing momentum and strengthens global IT networks.
Expansion of AI and Cloud-Native Solutions Unlocks New Innovation Streams
AI-driven automation and cloud-native architectures are opening new service opportunities. Enterprises demand scalable, secure, and intelligent solutions to support complex workloads. The Global Enterprise IT Services Market gains opportunities through integration of AI into IT infrastructure. It enables vendors to offer predictive analytics, self-healing systems, and adaptive security models. Cloud-native solutions enhance speed, resilience, and flexibility in service delivery. This expansion supports advanced innovation and new business models. Vendors leveraging these technologies can establish strong competitive advantages and long-term customer relationships.
Market Segmentation Analysis:
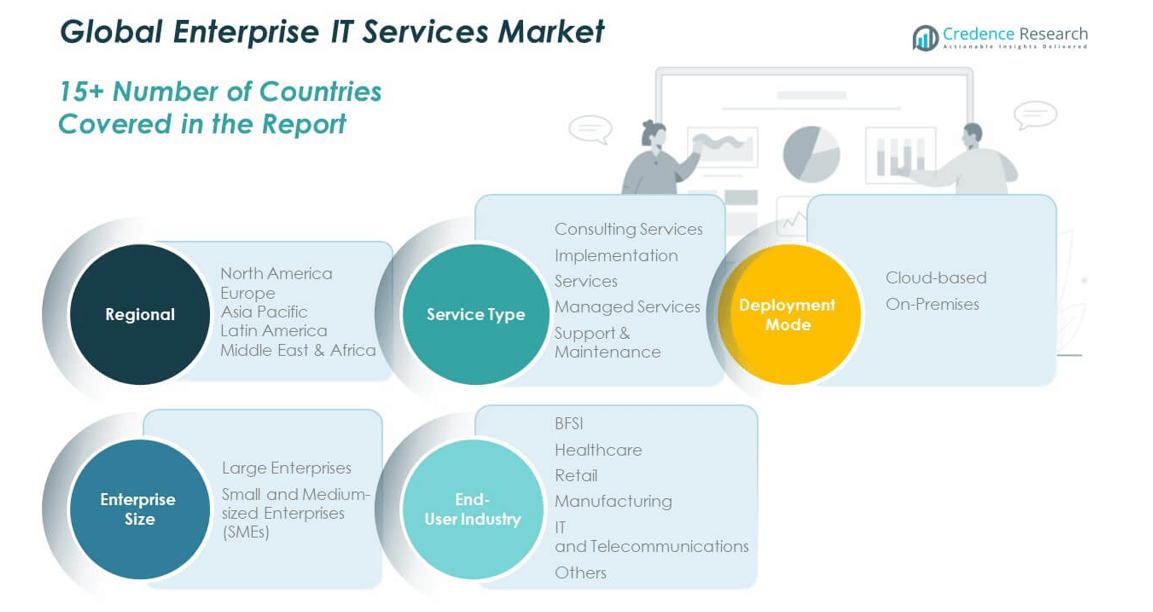
By Service Type, consulting services hold a strong position due to rising enterprise demand for strategic IT planning and modernization. Implementation services grow rapidly as companies integrate advanced technologies across operations. Managed services gain traction with rising outsourcing to reduce costs and enhance operational efficiency. Support and maintenance services remain vital for ensuring business continuity and system reliability.
- For instance, Deloitte promotes the Build–Operate–Transfer (BOTT) model as a structured approach to scale and transition enterprise operations efficiently. The model helps organizations optimize processes, strengthen digital integration, and ensure smooth operational continuity during transformation phases. It is widely applied to streamline global business services and improve performance without disrupting existing operations.
By Deployment Mode, cloud-based solutions dominate due to flexibility, scalability, and faster deployment capabilities. On-premises solutions retain demand among industries requiring tighter security control and regulatory compliance.
- For instance, IBM’s RISE with SAP deployment on Power Virtual Server in 2025 reduced migration time by 15–25% compared to heterogeneous x86 transitions, lowering operational risk through architectural continuity.
By Enterprise Size, large enterprises lead due to strong investment capacity, advanced infrastructure, and complex IT needs. Small and medium-sized enterprises show strong adoption momentum with growing focus on cost-efficient IT service models.
By End-User Industry, BFSI leads due to high reliance on secure and integrated IT systems. Healthcare shows significant growth supported by electronic health records and telemedicine platforms. Retail expands with e-commerce and omnichannel strategies. Manufacturing focuses on automation and operational optimization. IT and telecommunications drive adoption through network modernization. Others contribute steadily through sector-specific digital transformation efforts. The Global Enterprise IT Services Market benefits from broad adoption across industries with strong service diversification.
Segmentation:
By Service Type
- Consulting Services
- Implementation Services
- Managed Services
- Support & Maintenance
By Deployment Mode
- Cloud-based
- On-Premises
By Enterprise Size
- Large Enterprises
- Small and Medium-sized Enterprises (SMEs)
By End-User Industry
- BFSI
- Healthcare
- Retail
- Manufacturing
- IT and Telecommunications
- Others
By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
The North America Global Enterprise IT Services Market size was valued at USD 342.16 trillion in 2018 to USD 599.70 trillion in 2024 and is anticipated to reach USD 1,192.07 trillion by 2032, at a CAGR of 8.4% during the forecast period. North America holds the largest market share of 34.3%. Strong cloud adoption, advanced digital infrastructure, and early technology investments drive regional dominance. Enterprises prioritize AI integration, hybrid cloud, and cybersecurity modernization to maintain operational efficiency. The U.S. leads the region due to its mature IT ecosystem and large-scale enterprise investments. It benefits from a high concentration of key service providers and strong enterprise technology spending. Canada and Mexico contribute through rising digital transformation initiatives and expanding managed service contracts. Government modernization programs and strong private sector demand support consistent market growth. This leadership is reinforced by a robust innovation ecosystem and enterprise-scale cloud infrastructure.
Europe
The Europe Global Enterprise IT Services Market size was valued at USD 146.57 trillion in 2018 to USD 245.41 trillion in 2024 and is anticipated to reach USD 442.53 trillion by 2032, at a CAGR of 7.0% during the forecast period. Europe accounts for a market share of 14.0%. The region focuses on data sovereignty, regulatory compliance, and sustainable IT infrastructure. Enterprises invest heavily in hybrid cloud and cybersecurity to meet EU data protection standards. Germany, the UK, and France lead with strong enterprise IT adoption and digital innovation strategies. It benefits from industry-specific digital transformation in manufacturing, healthcare, and financial services. Cloud migration and managed services demand continue to expand. Regional vendors and global service providers strengthen partnerships to deliver secure and efficient solutions. This growth is supported by regulatory frameworks that encourage digital resilience.
Asia Pacific
The Asia Pacific Global Enterprise IT Services Market size was valued at USD 223.24 trillion in 2018 to USD 417.73 trillion in 2024 and is anticipated to reach USD 903.97 trillion by 2032, at a CAGR of 9.5% during the forecast period. Asia Pacific holds a market share of 23.9%. Rapid digital transformation, growing enterprise investments, and expanding cloud infrastructure fuel growth. China, Japan, and India drive strong demand for IT modernization and managed services. It benefits from rising adoption of automation, AI, and edge computing across industries. Government digital initiatives and favorable investment environments support market expansion. SMEs are increasing IT spending to compete globally. Large service providers and hyperscalers continue to scale their regional presence. This growth is reinforced by a fast-evolving technology landscape and a competitive service ecosystem.
Latin America
The Latin America Global Enterprise IT Services Market size was valued at USD 36.26 trillion in 2018 to USD 63.40 trillion in 2024 and is anticipated to reach USD 110.96 trillion by 2032, at a CAGR of 6.6% during the forecast period. Latin America holds a market share of 6.5%. The region is seeing stronger digital adoption in financial services, retail, and manufacturing. Brazil leads the market through expanding cloud infrastructure and growing enterprise modernization projects. It benefits from increasing managed service adoption among mid-sized businesses. Regional governments encourage digitalization and smart infrastructure investments. Service providers are entering new partnerships to strengthen local delivery capabilities. Data security, compliance, and cost optimization remain key priorities. This growth reflects a gradual shift toward modern IT models and broader enterprise adoption.
Middle East
The Middle East Global Enterprise IT Services Market size was valued at USD 20.61 trillion in 2018 to USD 33.17 trillion in 2024 and is anticipated to reach USD 54.76 trillion by 2032, at a CAGR of 5.8% during the forecast period. The region accounts for a market share of 3.4%. Governments are pushing strong digital transformation agendas, creating a favorable environment for enterprise IT expansion. Saudi Arabia and the UAE lead through smart city programs, cybersecurity investments, and large-scale cloud adoption. It benefits from increased infrastructure spending and public-private technology collaborations. Financial services, energy, and government sectors drive strong IT demand. Vendors expand their presence to deliver customized regional solutions. Regulatory reforms improve confidence in adopting cloud services. This upward trend reflects a structured shift toward modern digital frameworks.
Africa
The Africa Global Enterprise IT Services Market size was valued at USD 13.51 trillion in 2018 to USD 26.18 trillion in 2024 and is anticipated to reach USD 42.34 trillion by 2032, at a CAGR of 5.6% during the forecast period. Africa holds a market share of 2.9%. The region is witnessing steady digital adoption supported by mobile connectivity expansion and cloud-based solutions. South Africa leads the market with rising demand for managed services and infrastructure modernization. It benefits from increased foreign investments and regional startup ecosystems. Governments promote digital transformation through strategic ICT programs. The healthcare, telecom, and financial sectors show growing IT service needs. Infrastructure gaps and skill shortages remain key challenges, but investment momentum is increasing. This growth reflects a transition toward stronger enterprise digital capabilities and service adoption.
Key Player Analysis:
- Accenture
- Deloitte
- IBM
- Tata Consultancy Services (TCS)
- Cognizant
- Infosys
- Wipro
- Capgemini
- HCL Technologies
- Cisco Systems
Competitive Analysis:
The Global Enterprise IT Services Market is shaped by intense competition among established global service providers. Leading companies include Accenture, Deloitte, IBM, Tata Consultancy Services (TCS), Cognizant, Infosys, Wipro, Capgemini, HCL Technologies, and Cisco Systems. These firms focus on expanding service portfolios, strengthening cloud capabilities, and integrating AI-driven solutions to enhance enterprise transformation. It relies on strategic acquisitions, alliances, and innovation to maintain leadership. Vendors emphasize scalable cloud infrastructure, advanced cybersecurity, and industry-specific service models to differentiate offerings. Emerging players are entering niche segments with specialized services, increasing competitive pressure. Global coverage, technological depth, and strategic partnerships remain key factors shaping market positioning and customer loyalty.
Recent Developments:
- In October 2025, Accenture announced a significant acquisition to strengthen its footprint in the generative AI and Palantir integration ecosystem. On October 14, 2025, the company acquired Decho, a UK-based AI consultancy that specializes in designing and deploying Palantir-based AI solutions. This move aims to bolster Accenture’s capabilities in helping public sector and healthcare clients scale AI-driven transformation with advanced data modeling, application engineering, and training services, reinforcing its leadership in enterprise AI innovation.
- In October 2025, Deloitte deepened its engagement in data modernization initiatives through an expanded alliance with Databricks. Announced on October 8, 2025, this collaboration focuses on modernizing data management within tax operations by leveraging Databricks’ data and AI platform.
- In July 2025, Hewlett Packard Enterprise (HPE) completed its $13.4 billion acquisition of Juniper Networks, marking a pivotal moment in the enterprise IT services market and establishing a new competitive force in AI networking.
Report Coverage:
The research report offers an in-depth analysis based on Service Type, Deployment Mode, Enterprise Size and End-User Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing integration of AI and automation will transform enterprise workflows and service delivery models.
- Increased cloud adoption will drive demand for hybrid and multi-cloud service offerings.
- Rising cybersecurity investments will strengthen managed security services across industries.
- Industry-specific digital solutions will expand, creating niche opportunities for service providers.
- Strategic acquisitions and partnerships will accelerate global expansion and service diversification.
- Demand for data modernization and analytics services will intensify across large enterprises and SMEs.
- Edge computing and 5G deployments will reshape infrastructure strategies for critical industries.
- Green IT and sustainability initiatives will influence enterprise procurement decisions.
- Public sector digitalization programs will increase enterprise IT service penetration in emerging markets.
- Evolving regulatory frameworks will drive higher demand for compliance-focused service solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Enterprise IT Services Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Enterprise IT Services Market projected to grow between 2024 and 2032?
Which Global Enterprise IT Services Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Enterprise IT Services Market?
Who are the leading companies in the Global Enterprise IT Services Market?
Which region commanded the largest share of the Global Enterprise IT Services Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 1,385.60 trillion → 2032: USD 2,746.63 trillion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Enterprise IT Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Enterprise IT Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Enterprise IT Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Enterprise IT Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Enterprise IT Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Enterprise IT Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Enterprise IT Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Enterprise IT Services Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 1,385.60 trillion → 2032: USD 2,746.63 trillion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Enterprise IT Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Enterprise IT Services Geographic Market Outlook, 2018-2032
- 13.1 Regional Market Size and Share, 2018
- 13.2 Regional Market Forecast, 2018-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Enterprise IT Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2018-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Enterprise IT Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2018
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2018-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

