
Market Overview
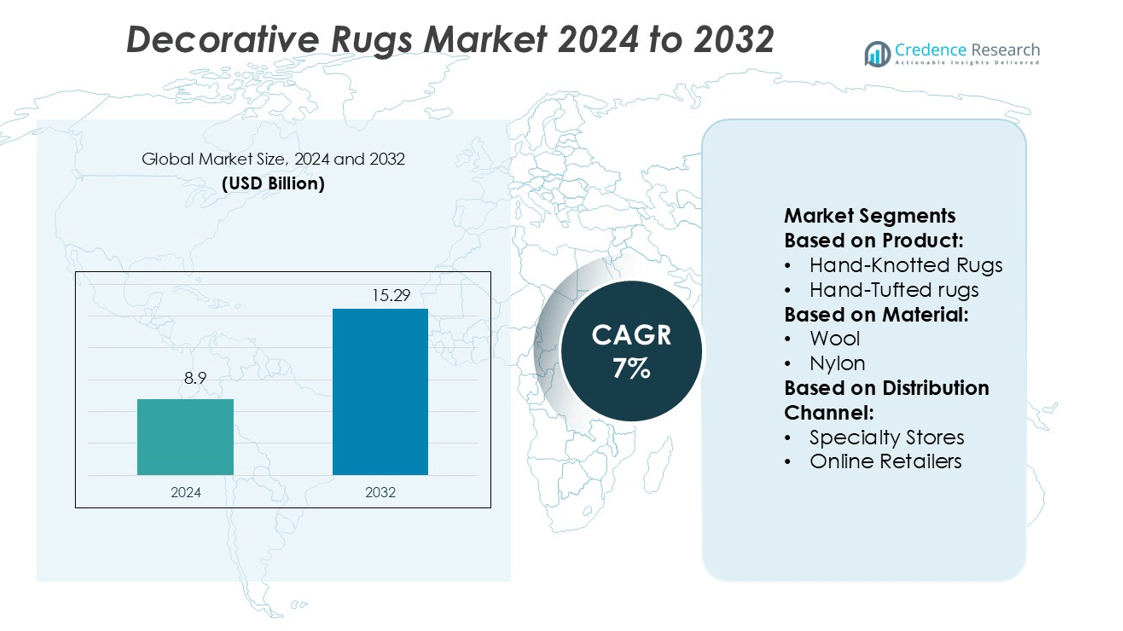
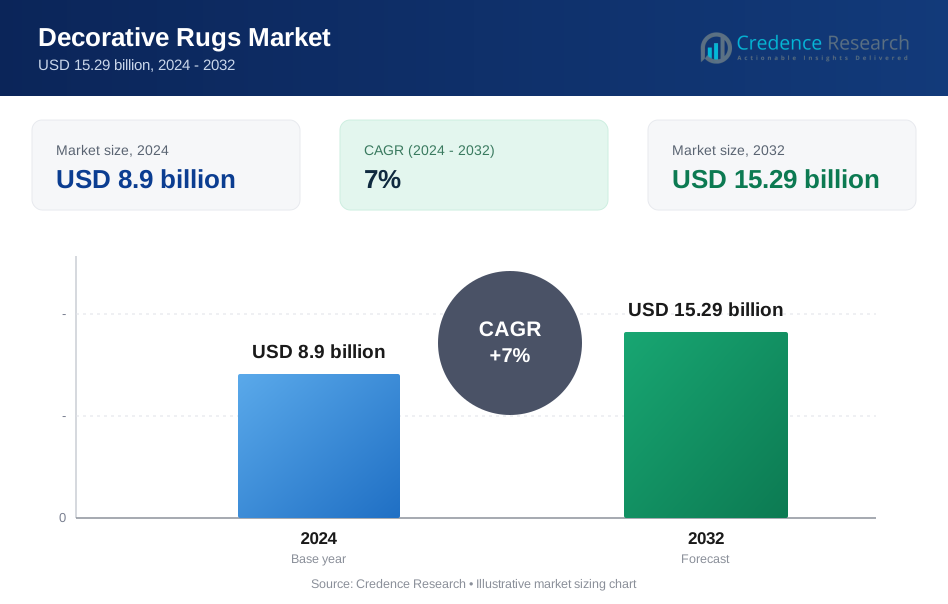
Decorative Rugs Market size was valued USD 8.9 billion in 2024 and is anticipated to reach USD 15.29 billion by 2032, at a CAGR of 7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Decorative Rugs Market Size 2024 | USD 8.9 billion |
| Decorative Rugs Market, CAGR | 7% |
| Decorative Rugs Market Size 2032 | USD 15.29 billion |
The decorative rugs market is shaped by major players including Kalaty Rug Corp, Balta Group, Momeni Inc., Harounian Rugs International, Agnella, Loloi Inc., Milliken and Co, Mohawk Industries Inc, Capel Rugs, and Bukhara Oriental Rugs. These companies focus on premium product development, advanced weaving technologies, and sustainable materials to strengthen their market presence. Strategic partnerships with designers and online retail expansion enhance their global reach. North America leads the decorative rugs market with a 31.6% share, driven by strong consumer demand for luxury and eco-friendly home décor. High spending on home improvement, rapid e-commerce growth, and preference for artisanal craftsmanship further solidify the region’s leadership position.
Market Insights
- The Decorative Rugs Market was valued at USD 8.9 billion in 2024 and is expected to reach USD 15.29 billion by 2032, growing at a CAGR of 7%.
- Rising demand for premium and sustainable rugs is driving market growth, supported by increased consumer spending on home décor.
- Key players focus on advanced weaving technologies, eco-friendly materials, and strategic partnerships to strengthen their global position.
- High production costs and strong price competition among manufacturers remain major restraints for market expansion.
- North America leads with a 31.6% share, followed by Europe with 27.8%, while hand-knotted rugs hold the largest product segment share due to their premium quality and design appeal.
Market Segmentation Analysis:
By Product
Hand-knotted rugs dominate the Decorative Rugs Market, holding a 32.7% share in 2024. These rugs are valued for their craftsmanship, durability, and luxury appeal. High demand comes from premium residential spaces, boutique hotels, and designer showrooms. Hand-tufted rugs follow closely, driven by lower prices and faster production cycles. Machine-made and flatweave rugs cater to mass consumers seeking affordable décor options. Growth in this segment is fueled by rising disposable incomes, evolving home décor trends, and growing demand for sustainable, artisan-made interior products.
- For instance, Momeni Inc. offers a New Moroccan line of hand-woven shag rugs made entirely of 100% New Zealand wool.The Momeni website has a product page dedicated to the "New Moroccan" collection.
By Material
Wool leads the market with a 29.8% share due to its softness, resilience, and eco-friendly properties. The material is popular for premium and mid-range rugs, especially in Europe and North America. Nylon and polyester follow, supported by their stain resistance and affordability. Cotton and jute are gaining traction among eco-conscious consumers for their natural look and sustainable sourcing. Increasing interior design investments, preference for organic materials, and rising interest in sustainable manufacturing practices are key growth drivers for wool-based rugs.
- For instance, Brintons, the parent company of Agnella, developed high-definition weaving technology that enables looms to use up to 32 colors per pass. This represents a significant advancement over earlier technology, which typically supported only 12 to 16 colors.
By Distribution Channel
Specialty stores dominate the segment with a 34.2% market share, driven by personalized service and a curated product mix. These stores offer design consultation and quality assurance, attracting mid- to high-income consumers. Online retail channels are growing rapidly due to improved logistics, wide product availability, and competitive pricing. Hypermarkets and wholesalers support bulk sales for commercial projects and exports. E-commerce expansion, enhanced digital visualization tools, and home delivery convenience are strengthening the market presence of online and specialty channels.
Key Growth Drivers
Rising Demand for Premium Home Décor Products
Consumers are increasingly investing in high-quality interior furnishings, boosting demand for decorative rugs. Premium rugs enhance aesthetics and offer durability, making them a preferred choice for modern homes and luxury spaces. Growing urbanization and rising disposable incomes further support this shift. The hospitality sector also contributes significantly, using premium rugs to elevate interior appeal. Hand-knotted and hand-tufted rugs are gaining popularity among design-conscious buyers. This preference for luxury and artisanal craftsmanship continues to drive market expansion across developed and emerging regions.
- For instance, Loloi Inc. offers the Magnolia Home x Loloi collection, which included new rug designs and matching throw pillows launched in 2024. The Charlie line within this collection is hand-loomed from 100% recycled post-consumer polyester, using repurposed plastic bottles.
Expansion of E-Commerce and Digital Retail Channels
E-commerce platforms have simplified rug selection, pricing comparison, and delivery, driving strong market growth. Consumers can access a wider product range online, including custom and imported designs, without visiting physical stores. Advanced visualization tools, AR applications, and improved logistics enhance the online shopping experience. Retailers are investing in digital platforms to reach a larger audience and expand sales. This rapid digitalization strengthens the distribution network, boosts cross-border trade, and enables small manufacturers to access global buyers efficiently.
- For instance, Capel Rugs now offers over 5,000 braided rug style-size-color combinations, making it the largest braided rug producer in the U.S. The company also manufactures flat-woven, machine-made, and custom fabric-bordered rugs at their North Carolina facility.
Rising Focus on Sustainable and Eco-Friendly Materials
Growing environmental awareness is pushing manufacturers to adopt eco-friendly materials such as wool, jute, and organic cotton. Consumers increasingly prefer rugs made using sustainable and ethically sourced fibers. Government regulations supporting green products further strengthen this demand. Manufacturers are investing in low-impact dyeing and energy-efficient production methods to meet sustainability goals. Premium segments are witnessing higher adoption of natural materials for their durability and aesthetics. This trend is boosting innovation in product design and supporting long-term market growth.
Key Trends & Opportunities
Technological Integration in Manufacturing
Rug manufacturers are adopting advanced weaving technologies to increase efficiency and precision. Automation and digital printing enable faster production while maintaining intricate designs. These technologies help reduce costs, minimize defects, and meet rising customization demand. Many companies are integrating 3D modeling and AR tools to offer virtual product previews. The trend supports both traditional craftsmanship and modern design flexibility. This balance between innovation and heritage is opening new opportunities in global premium and mass-market segments.
- For instance, Rug News reported that Momeni had officially opened a new 300,000-square-foot facility in Adairsville, Georgia, effectively doubling its previous warehouse space.
Growing Popularity of Artisanal and Handcrafted Rugs
Consumers increasingly value craftsmanship and uniqueness, fueling demand for artisanal rugs. Hand-knotted and hand-tufted designs are associated with quality, cultural heritage, and aesthetic appeal. Global luxury buyers seek exclusive, limited-edition pieces that reflect local artistry. Manufacturers are partnering with artisans to preserve traditional weaving techniques while expanding production capacity. This trend aligns with premium interior design movements and rising interest in sustainable, authentic home décor. The growing emphasis on storytelling through design is creating strong brand differentiation opportunities.
- For instance, Ruggable LLC utilizes a patented 2-piece rug system where the rug cover is fully machine-washable, detachable from the non-slip pad via their Cling Effect™ mechanism.
Rising Demand in Commercial Spaces
Hotels, offices, and retail outlets are using decorative rugs to create premium interiors and improve acoustic comfort. Custom-designed rugs are increasingly integrated into modern commercial architecture to enhance ambiance. Developers and interior designers are prioritizing durable, low-maintenance options suitable for high-traffic areas. This demand is driving large-scale installations of machine-made and hand-tufted rugs. As commercial construction projects expand globally, especially in Asia-Pacific and the Middle East, this segment presents significant growth potential for manufacturers and suppliers.
Key Challenges
High Production Costs and Pricing Pressure
The manufacturing of premium decorative rugs, especially hand-knotted varieties, involves high labor and material costs. Artisanal craftsmanship requires skilled weavers, making production slower and more expensive. At the same time, growing competition from machine-made alternatives creates pricing pressure. Many consumers prioritize affordability over heritage value, limiting premium market penetration. Rising raw material prices further intensify cost challenges. Balancing quality and competitive pricing remains a key challenge for manufacturers targeting both high-end and mid-range segments.
Intense Competition and Market Fragmentation
The decorative rugs market is highly fragmented, with numerous local and international brands competing for market share. Large manufacturers focus on automation and scale, while smaller players emphasize craftsmanship and niche designs. This fragmented structure creates pricing pressure and limits brand differentiation. Rapid expansion of online retail platforms intensifies competition, making customer retention more challenging. Companies must continuously innovate in design, sustainability, and service offerings to stay competitive in an evolving and crowded market landscape.
Regional Analysis
North America
North America holds a 31.6% share of the decorative rugs market, driven by strong demand for premium and sustainable home décor. The U.S. dominates the region due to high consumer spending on interior design and renovation projects. Rising popularity of artisanal and hand-knotted rugs supports the luxury segment, while machine-made rugs cater to mass consumers. E-commerce platforms such as Amazon and Wayfair play a key role in expanding product reach. Sustainable materials like wool and jute are gaining traction, aligning with eco-conscious preferences. Hospitality and commercial sectors further boost demand for durable, high-quality decorative rugs.
Europe
Europe accounts for a 27.8% share of the decorative rugs market, supported by strong design traditions and demand for high-quality craftsmanship. Countries such as Germany, France, and the UK lead in premium rug consumption. Consumers favor wool and flatweave rugs for their durability and timeless appeal. Strict environmental regulations also push manufacturers toward sustainable production methods. Online retail channels are expanding, enhancing access to artisanal and luxury rugs. The hospitality sector and residential remodeling trends continue to drive sales, with growing interest in culturally inspired and eco-friendly designs strengthening the region’s position in the global market.
Asia Pacific
Asia Pacific captures a 24.5% market share, emerging as a major production hub and a rapidly growing consumer base. India and China are leading exporters of hand-knotted and machine-made rugs, supplying to North America and Europe. Rising disposable incomes and urbanization are fueling strong domestic demand. E-commerce expansion and a growing middle-class population drive sales of affordable and mid-range rugs. Manufacturers in the region also benefit from lower production costs and skilled artisans. The shift toward sustainable materials and modern design trends supports further growth. Increasing investments in infrastructure and commercial spaces boost market penetration.
Latin America
Latin America holds a 9.2% share of the decorative rugs market, supported by growing interest in interior décor among urban consumers. Brazil and Mexico lead regional sales, driven by increasing housing development and rising disposable incomes. Demand is concentrated in affordable machine-made and flatweave rugs, though premium segments are slowly gaining traction. Online retail is expanding, improving product accessibility in emerging urban markets. Consumers increasingly prefer rugs with vibrant colors and cultural patterns. Local manufacturing and import activity are growing steadily, positioning the region as a rising market with significant long-term potential for international brands.
Middle East & Africa
The Middle East & Africa region accounts for a 6.9% market share, with growth driven by strong construction activity and luxury interior demand. Countries such as the UAE, Saudi Arabia, and South Africa are major contributors. High-end hand-knotted and hand-tufted rugs are popular in luxury residences, hotels, and cultural spaces. Urbanization and infrastructure development boost commercial installations. Consumers show increasing interest in Persian and artisanal designs that reflect heritage and exclusivity. Expanding retail networks and rising online shopping trends support wider product adoption, positioning the region as a promising market for premium decorative rug manufacturers.
Market Segmentations:
By Product:
- Hand-Knotted Rugs
- Hand-Tufted rugs
By Material:
- Wool
- Nylon
By Distribution Channel:
- Specialty Stores
- Online Retailers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The decorative rugs market features prominent players such as Kalaty Rug Corp, Balta Group, Momeni Inc., Harounian Rugs International, Agnella, Loloi Inc., Milliken and Co, Mohawk Industries Inc, Capel Rugs, and Bukhara Oriental Rugs. The decorative rugs market is characterized by intense competition, with companies focusing on innovation, design, and sustainable production to strengthen their position. Manufacturers are investing in advanced weaving technologies and automation to improve efficiency, quality, and product variety. Strong emphasis is placed on eco-friendly materials and artisanal craftsmanship to meet growing consumer demand for premium home décor. E-commerce platforms are expanding market reach, allowing brands to connect directly with global customers. Strategic collaborations with designers and retailers help create exclusive collections and enhance brand identity. Customization, storytelling, and sustainable practices are emerging as key differentiators in this competitive landscape.
Key Player Analysis
- Kalaty Rug Corp
- Balta Group
- Momeni Inc.
- Harounian Rugs International
- Agnella
- Loloi Inc.
- Milliken and Co
- Mohawk Industries Inc
- Capel Rugs
- Bukhara Oriental Rugs
Recent Developments
- In July 2025, Mohawk Industries launched Products reflecting Mohawk's sustainable leadership include SolidTech® R, a high performance waterproof, PVC-free flooring. Designed for unconditioned spaces like three-season rooms, this sustainable flooring solution combines durability, water resistance, and eco-friendliness to meet growing demand for versatile, renewable options.
- In December 2024, Benuta, Europe’s largest online rug retailer, adopted Constructor's AI-powered e-commerce platform to enhance and personalize shopping experiences. With over 20,000 products, the platform streamlines product discovery, saving time for both shoppers and merchandisers. It operates across European domains, offering localized, seamless, and engaging searches.
- In May 2024, FLOR announced the launch of new area rug styles designed to welcome the summer season. This release features a vibrant collection of customizable rugs that reflect the latest design trends while maintaining the brand's commitment to sustainability.
- In November 2023, Oriental Weavers Group collaborated with a leading solar energy solutions provider, Amarenco Solarize, to power its factory in the Tenth of Ramadan area using solar energy. The goal of the 1.3 MWp solar power plant is to supply 80% of the factory's energy needs, which will result in a yearly decrease of 2,300 tons of carbon emissions.
Report Coverage
The research reIn May 2024, FLOR announced the launch of new area rug styles designed to welcome the summer season. This release features a vibrant collection of customizable rugs that reflect the latest design trends while maintaining the brand's commitment to sustainability.port offers an in-depth analysis based on Product, Material, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for sustainable and eco-friendly rugs will continue to rise across major markets.
- Manufacturers will increasingly adopt automation and digital weaving technologies.
- Online retail platforms will become a dominant distribution channel for decorative rugs.
- Premium and artisanal rug segments will experience steady expansion.
- Customization and limited-edition designs will gain higher consumer preference.
- Strategic collaborations with designers will strengthen brand positioning.
- Commercial and hospitality sectors will drive large-scale rug installations.
- Regional production hubs will expand to support global supply chains.
- Smart visualization tools will enhance customer buying experiences online.
- Companies will focus on building strong sustainability and circular economy strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Decorative Rugs Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Decorative Rugs Market projected to grow between 2025 and 2032?
Which Decorative Rugs Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Decorative Rugs Market?
Who are the leading companies in the Decorative Rugs Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8.9 billion → 2032: USD 15.29 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Decorative Rugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Decorative Rugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Decorative Rugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Decorative Rugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Decorative Rugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Decorative Rugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Decorative Rugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Decorative Rugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8.9 billion → 2032: USD 15.29 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Decorative Rugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Decorative Rugs Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Decorative Rugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Decorative Rugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

