
Market Overview
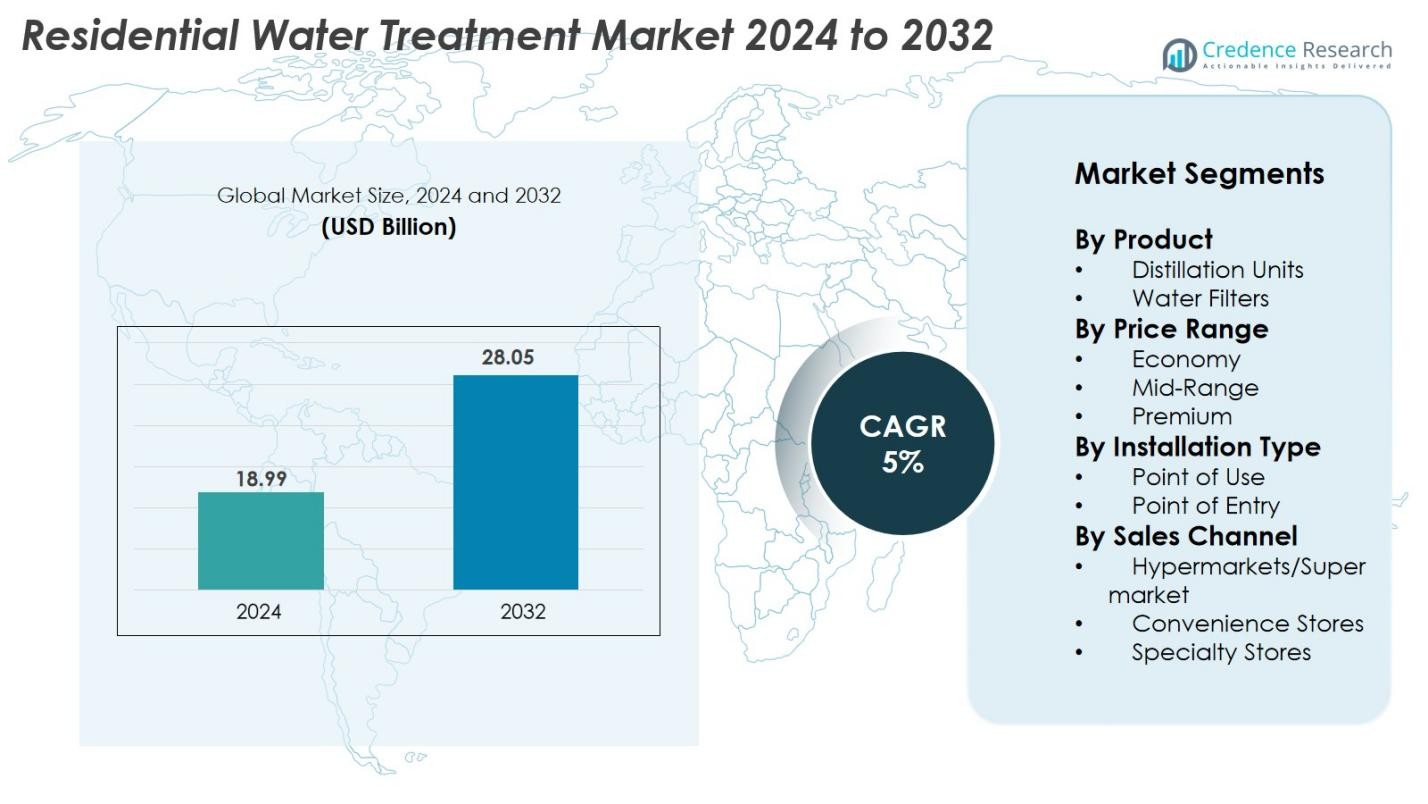
Residential Water Treatment Market size was valued at USD 18.99 Billion in 2024 and is anticipated to reach USD 28.05 Billion by 2032, at a CAGR of 5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Residential Water Treatment Market Size 2024 | USD 18.99 Billion |
| Residential Water Treatment Market, CAGR | 5% |
| Residential Water Treatment Market Size 2032 | USD 28.05 Billion |
Residential Water Treatment Market is driven by strong participation from leading players such as A.O. Smith Corporation, Kent Supreme, Eureka Forbes, Panasonic, Aquasana, GE Appliances, 3M, Waterwise Inc., Everpure, and Aqua Care. These companies focus on advanced RO, UV, and multi-stage filtration technologies, supported by expanding product portfolios and strong distribution networks. North America leads the market with a 34.2% share in 2024, followed by Asia-Pacific with 29.8%, reflecting rapid urbanization and rising health awareness. Europe holds a 27.6% share, driven by strict water-quality standards and growing adoption of eco-friendly purification solutions across households.
Market Insights
- The Residential Water Treatment Market was valued at USD 18.99 Billion in 2024 and is projected to reach USD 28.05 Billion by 2032, registering a CAGR of 5%.
- Growing consumer awareness of contaminants, aging municipal pipelines, and rising health concerns are driving strong adoption of RO, UV, and multi-stage filtration systems across residential households.
- Key trends include the rising demand for smart, connected purifiers, water-efficient RO systems, and compact, space-saving filtration units tailored for urban living environments.
- Leading players such as A.O. Smith Corporation, Eureka Forbes, Panasonic, Kent Supreme, GE Appliances, and 3M strengthen market growth through product innovation, expanded retail networks, and service-focused strategies.
- Regionally, North America leads with a 34.2% share, followed by Asia-Pacific at 29.8% and Europe at 27.6%, while water filters dominate product segmentation with a 62.4% share in 2024.
Market Segmentation Analysis
By Product
The Residential Water Treatment Market by product is dominated by water filters, accounting for 62.4% of the market share in 2024. Their wide adoption is driven by increasing consumer awareness of contaminants such as chlorine, lead, and microbial impurities. Households prefer filtration systems for their affordability, ease of installation, and compatibility with various water sources. Distillation units hold a smaller share but continue to attract users seeking high-purity output for specific health needs. The growing emphasis on safe drinking water and rising urban water quality concerns accelerate demand for advanced multi-stage filtration technologies.
- For instance, A. O. Smith’s X8 Green RO system integrates an 8-stage purification process and features a mineralizer cartridge rated for 6,000 liters, ensuring extended filtration life.
By Price Range
In the price range segment, mid-range solutions lead the Residential Water Treatment Market with a 48.7% market share in 2024, supported by strong consumer preference for balanced affordability and performance. Mid-range products offer enhanced purification technologies, better durability, and wider brand availability, making them the most attractive choice for middle-income households. Economy systems remain popular in emerging markets, while premium products gain traction among high-income consumers seeking smart, connected, and high-efficiency purification systems. Rising disposable incomes and growing adoption of household water safety solutions continue to drive mid-range segment dominance.
- For instance, Kent RO’s Grand Plus model incorporates an RO+UV+UF purification framework with a storage capacity of 8 liters and a purification rate of 20 liters per hour, ensuring continuous supply for family households.
By Installation Type
By installation type, point-of-use (POU) systems dominate the Residential Water Treatment Market with a 67.1% market share in 2024, driven by their convenience, lower cost, and targeted purification at consumption points such as kitchen sinks. POU systems, including countertop, under-sink, and faucet-mounted units, are preferred for daily drinking and cooking requirements. Point-of-entry (POE) systems are gaining momentum among larger households seeking whole-home filtration for bathing, laundry, and appliance protection. Increasing water contamination levels, rising household awareness, and expanding urban populations reinforce the strong demand for POU solutions.
Key Growth Drivers
Rising Concerns Over Drinking Water Quality
Growing concerns about deteriorating water quality remain one of the strongest drivers of the Residential Water Treatment market. Increasing contamination from industrial discharge, aging municipal pipelines, agricultural runoff, and high TDS levels in groundwater has made households more dependent on home-based purification systems. Consumers are increasingly aware of risks related to microbial pathogens, heavy metals, chlorine, and emerging contaminants, strengthening the need for advanced systems such as RO, UV, and multi-stage filtration units. Government testing reports and rising media coverage of water quality incidents further influence consumer behavior. In rapidly urbanizing regions, water scarcity and the reliance on tanker or borewell supplies also heighten demand for purification units. The growing preference for convenient, point-of-use systems and the shift toward regular filter-replacement cycles contribute to market expansion. As health consciousness rises globally, reliable home water treatment solutions are becoming essential, supporting long-term market growth.
- For instance, Culligan’s Aquasential Reverse Osmosis system uses a five-stage purification module and delivers up to 189 liters of purified water per day, suitable for households with high consumption.
Increasing Adoption of Smart and Connected Water Purification Technologies
The adoption of smart water purification systems is accelerating as consumers shift toward technologically advanced home appliances. Modern residential water treatment devices now integrate IoT-based monitoring, app-controlled operations, digital indicators, and automated filter replacement alerts, improving user convenience and system reliability. These features ensure optimal performance while reducing maintenance uncertainty for households. Smart RO and UV systems, supported by Wi-Fi connectivity and AI-driven diagnostics, are becoming popular in premium and mid-range segments. Manufacturers are investing in innovation to offer energy-efficient purification, water recovery optimization, and enhanced real-time tracking of water quality parameters. Growing consumer preference for smart home ecosystems further strengthens this trend. As brands expand product portfolios with intelligent purification tools, the market benefits from rising demand for high-tech, feature-rich, and user-friendly water treatment solutions, particularly in urban households with busy lifestyles and higher disposable incomes.
- For instance, A.O. Smith Intelli UV+ water purifier features an Advanced Digital Display and Advance Alert Technology to inform users when the UV lamp and filters need replacement.
Rising Urbanization and Expansion of Middle-Class Households
Rapid urbanization and the expansion of middle-income households significantly drive the Residential Water Treatment market. Urban regions often face inconsistent water supply quality due to infrastructure limitations, compelling households to rely on purification systems as a necessity rather than a lifestyle choice. The growing number of nuclear families and rising residential construction activity create strong replacement and first-time installation opportunities. Increasing disposable incomes enable households to upgrade from basic filtration units to more advanced RO, UV, and multi-stage systems. Additionally, the rise of packaged drinking water costs encourages consumers to switch to home purification solutions. The market also benefits from rising homeownership, improved living standards, and government-led initiatives promoting access to safe drinking water. As urban populations grow globally, the adoption of reliable household water treatment systems is expected to increase steadily, supporting sustained market expansion.
Key Trends & Opportunities
Growing Shift Toward Eco-Friendly and High-Efficiency Purification Systems
A major trend shaping the Residential Water Treatment market is the rising demand for eco-friendly purification systems designed to reduce water wastage, energy consumption, and plastic dependency. Consumers are becoming increasingly environmentally conscious, driving interest in RO systems with water recovery mechanisms, zero-water-waste technologies, and advanced filtration media made from biodegradable or long-lasting materials. Manufacturers are responding by introducing water-efficient models and filters with extended lifespans, minimizing replacement frequency. The shift toward sustainable purification aligns with broader global initiatives promoting water conservation and green household appliances. Opportunities emerge for brands offering recyclable filter cartridges, solar-powered purification, and systems designed to reduce operational footprints. As environmental regulations tighten and consumers prioritize sustainability, companies innovating eco-friendly purification technologies will gain a competitive advantage in premium and mid-range residential segments.
- For instance, Coway's CHP-18 series water purifiers (e.g., Villaem II) utilize an RO membrane with a lifespan of approximately 24 months (or 18–24 months for some compatible filters) rather than a specific total liter capacity for the filter itself.
Rising Demand for Portable, Modular, and Compact Water Treatment Solutions
The increasing popularity of compact and portable water treatment solutions presents a strong opportunity within the residential market. As more households move into smaller urban apartments, demand grows for lightweight, space-saving devices such as faucet filters, countertop purifiers, gravity-based units, and modular under-sink systems. These solutions appeal to renters, frequent movers, and students due to their ease of installation and affordability. The trend is further strengthened by lifestyle mobility, the rising prevalence of shared living spaces, and the need for convenient purification options without permanent plumbing changes. Manufacturers are focusing on modular designs that allow users to customize filtration levels, portability, and water flow configurations. The surge in online retail has also expanded access to compact purification products. This trend offers significant growth opportunities in emerging markets and urban centers where space limitations and mobility influence consumer purchasing behavior.
- For instance, Brita’s basic faucet filtration system processes up to 378 liters before cartridge replacement and requires no tools for installation, making it ideal for mobile and rental households.
Key Challenges
High Maintenance Costs and Frequent Filter Replacements
One of the major challenges affecting the Residential Water Treatment market is the high maintenance cost associated with advanced purification systems, particularly RO and UV units. Frequent filter replacements, servicing requirements, and membrane cleaning add to the total cost of ownership, discouraging budget-conscious consumers. In many regions, lack of standardized service networks and dependence on third-party technicians further complicate maintenance reliability. Households often delay servicing due to cost concerns, reducing system efficiency and lifespan. Additionally, low-cost counterfeit filters available in unorganized markets pose safety and durability risks. For manufacturers, maintaining consistent after-sales service quality remains difficult across diverse geographies. Addressing this challenge requires affordable subscription-based maintenance models, long-life filters, and improved service infrastructure.
Variability in Water Quality and Lack of Consumer Awareness
The Residential Water Treatment market also faces challenges due to highly variable water quality across regions, making it difficult for consumers to select the most suitable purification technology. Many households lack awareness of specific contaminants in their water supply, leading to improper product choices or underutilization of system features. Misconceptions about RO wastage, UV effectiveness, and general maintenance further hinder adoption. In rural or price-sensitive markets, reliance on traditional boiling or basic filters reduces the uptake of advanced systems. Additionally, inconsistent municipal water testing and lack of standardization in water quality reporting limit consumer understanding. To overcome this challenge, manufacturers must invest in awareness campaigns, water testing services, and educational tools that guide consumers toward appropriate purification technologies.
Regional Analysis
North America North America leads the Residential Water Treatment Market with a 34.2% market share in 2024, driven by heightened awareness of water contamination issues, aging pipeline infrastructure, and widespread adoption of advanced purification technologies. Consumers prefer RO, UV, and multi-stage systems supported by strong product availability and high disposable incomes. The U.S. dominates regional demand due to stringent water safety regulations and frequent municipal quality concerns. Growth is further fueled by the rising adoption of smart, connected purifiers and subscription-based filter replacement models. Canada follows with increasing uptake of energy-efficient and eco-friendly home filtration solutions.
Europe
Europe accounts for 27.6% of the Residential Water Treatment Market in 2024, supported by strict water-quality regulations and a strong environmental focus. Households in Western Europe, particularly Germany, France, and the U.K., increasingly adopt filtration systems to address hardness, microplastics, and chemical contaminants. Demand for eco-friendly purification technologies, including water-saving RO systems and recyclable filters, is growing steadily. Southern and Eastern Europe are witnessing rising adoption due to improving urban infrastructure and consumer awareness. The region’s emphasis on sustainability and premium home appliances continues to support the expansion of residential water purification systems.
Asia-Pacific
Asia-Pacific holds the largest growth momentum and captures 29.8% of the Residential Water Treatment Market in 2024, driven by rapid urbanization, varying water quality, and dependence on tanker and borewell sources. Countries such as India, China, and Indonesia show strong demand for RO and ultraviolet systems due to high TDS levels and microbial contamination. Expanding middle-class households and rising health consciousness further accelerate adoption. The region benefits from local manufacturing, competitive pricing, and wide retail distribution. Increasing government initiatives promoting safe drinking water and rising awareness of daily health risks continue to make Asia-Pacific the fastest-expanding market.
Latin America
Latin America holds a 5.8% market share in 2024, with demand driven by inconsistent municipal water supply and increasing household reliance on purification systems. Brazil and Mexico lead the region as urban populations grow and consumer awareness of waterborne illnesses rises. Households increasingly adopt POU systems such as countertop and under-sink filters for drinking and cooking needs. Economic constraints support steady demand for affordable and mid-range filtration solutions. Improvements in retail penetration and expansion of water quality testing services are further encouraging the uptake of household purification technologies across the region.
Middle East & Africa
The Middle East & Africa region accounts for 2.6% of the Residential Water Treatment Market in 2024, primarily driven by water scarcity, desalinated water use, and rising concerns over microbial impurities. Gulf nations such as the UAE and Saudi Arabia show strong adoption of advanced RO and activated carbon systems to improve taste and reduce salinity. In Africa, urban centers increasingly rely on filtration due to unreliable municipal supply and contamination risks. Affordability challenges slow adoption, but rising urbanization, growing awareness, and expanding access to retail distribution channels are gradually supporting market growth.
Market Segmentations
By Product
- Distillation Units
- Water Filters
By Price Range
- Economy
- Mid-Range
- Premium
By Installation Type
- Point of Use
- Point of Entry
By Sales Channel
- Hypermarkets/Supermarket
- Convenience Stores
- Specialty Stores
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Residential Water Treatment Market is shaped by a mix of global brands and regional specialists focusing on advanced purification technologies, product reliability, and expanding distribution networks. Key players such as A.O. Smith Corporation, Kent Supreme, Eureka Forbes, Panasonic, Aquasana, GE Appliances, 3M, Waterwise Inc., Everpure, and Aqua Care concentrate on offering RO, UV, activated carbon, and multi-stage filtration systems tailored to diverse household needs. Companies increasingly invest in smart purification features, improved water recovery systems, and long-life filters to strengthen their market position. Strategic initiatives, including product innovation, partnerships with retail and online channels, and expansion into emerging markets, help brands broaden their consumer reach. Growing emphasis on eco-friendly materials and energy-efficient purification technologies also drives competitive differentiation. As consumer awareness rises and regulatory standards tighten, leading manufacturers continue to refine product quality, affordability, and after-sales service to maintain long-term market leadership.
Key Player Analysis
- Aquasana
- Panasonic
- Everpure
- Waterwise Inc.
- A.O. Smith Corporation
- GE Appliances
- Kent Supreme
- 3M
- Aqua Care
- Eureka Forbes
Recent Developments
- In July 2025, Eureka Forbes Ltd launched a new range of Aquaguard water purifiers featuring Longlife Nanopore Filter technology that provides a filter-life of up to 2 years for Indian homes.
- In 2024, Unilever announced the sale of its water-purification business Pureit to A. O. Smith Corporation, marking a significant portfolio shift in the residential purification segment.
Report Coverage
The research report offers an in-depth analysis based on Product, Price Range, Installation Type, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth as households increasingly prioritize safe and reliable drinking water solutions.
- Adoption of smart and connected purification systems will accelerate, driven by rising demand for real-time monitoring and automated maintenance.
- Eco-friendly and water-efficient purification technologies will gain prominence as sustainability becomes a major consumer focus.
- Point-of-use systems will remain the preferred installation type due to convenience, affordability, and targeted purification benefits.
- Advanced RO and multi-stage filtration technologies will see wider usage in regions with high TDS and variable water quality.
- The rise of compact and modular purifiers will support adoption in urban apartments with limited space.
- Manufacturers will expand service subscription models, improving maintenance accessibility and long-term system performance.
- Growth opportunities will strengthen in emerging markets as awareness of water contamination and health risks increases.
- Digital retail channels will play a larger role, enhancing consumer reach and product availability.
- Innovations in long-life filters and low-maintenance designs will help reduce ownership costs and boost adoption.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Concerns Over Drinking Water Quality
Increasing contamination from industrial discharge, aging municipal pipelines, and agricultural runoff has heightened consumer awareness of waterborne risks, driving households to adopt advanced purification systems such as RO, UV, and multi-stage filters.
Increasing Adoption of Smart and Connected Water Purification Technologies
Consumers are shifting toward technologically advanced water treatment devices with IoT monitoring, app controls, and automated maintenance alerts, which enhance convenience and reliability, especially in urban households with higher disposable incomes.
Rising Urbanization and Expansion of Middle-Class Households
Rapid urbanization and the growth of middle-income populations are increasing the need for reliable home water treatment, as urban infrastructure struggles to provide consistent water quality and more families seek advanced purification solutions.
Growing Shift Toward Eco-Friendly and High-Efficiency Purification Systems
Environmental consciousness is driving demand for water-efficient RO systems, recyclable filters, and purification technologies that reduce water and energy waste, aligning with global sustainability trends and regulatory pressures.
Rising Demand for Portable, Modular, and Compact Water Treatment Solutions
Urbanization and smaller living spaces are boosting the popularity of compact, portable, and modular water purifiers, which appeal to renters, students, and mobile households seeking affordable and easy-to-install solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Residential Water Treatment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Residential Water Treatment Market projected to grow between 2025 and 2032?
Which Residential Water Treatment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Residential Water Treatment Market?
Who are the leading companies in the Residential Water Treatment Market?
Which region commanded the largest share of the Residential Water Treatment Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Distillation Units
- 1.2.2 Water Filters
- 1.3 By Price Range
- 1.3.1 Economy
- 1.3.2 Mid-Range
- 1.3.3 Premium
- 1.4 By Sales Channel
- 1.4.1 Hypermarkets/Supermarket
- 1.4.2 Convenience Stores
- 1.4.3 Specialty Stores
- 1.5 By Installation Type
- 1.5.1 Point of Use
- 1.5.2 Point of Entry
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 18.99 Billion → 2032: USD 28.05 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Residential Water Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Residential Water Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Residential Water Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Residential Water Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Residential Water Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Residential Water Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Residential Water Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Residential Water Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 18.99 Billion → 2032: USD 28.05 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Residential Water Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Distillation Units
- 12.3.7.2 Water Filters
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Price Range - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Economy
- 12.4.7.2 Mid-Range
- 12.4.7.3 Premium
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hypermarkets/Supermarket
- 12.5.7.2 Convenience Stores
- 12.5.7.3 Specialty Stores
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Installation Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Point of Use
- 12.6.7.2 Point of Entry
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Residential Water Treatment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Residential Water Treatment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Residential Water Treatment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 A.O. Smith Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Kent Supreme
- 17.4 Eureka Forbes
- 17.5 Panasonic
- 17.6 Aquasana
- 17.7 GE Appliances
- 17.8 3M
- 17.9 Waterwise Inc.
- 17.10 Everpure
- 17.11 Aqua Care
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

