
Market Overview:
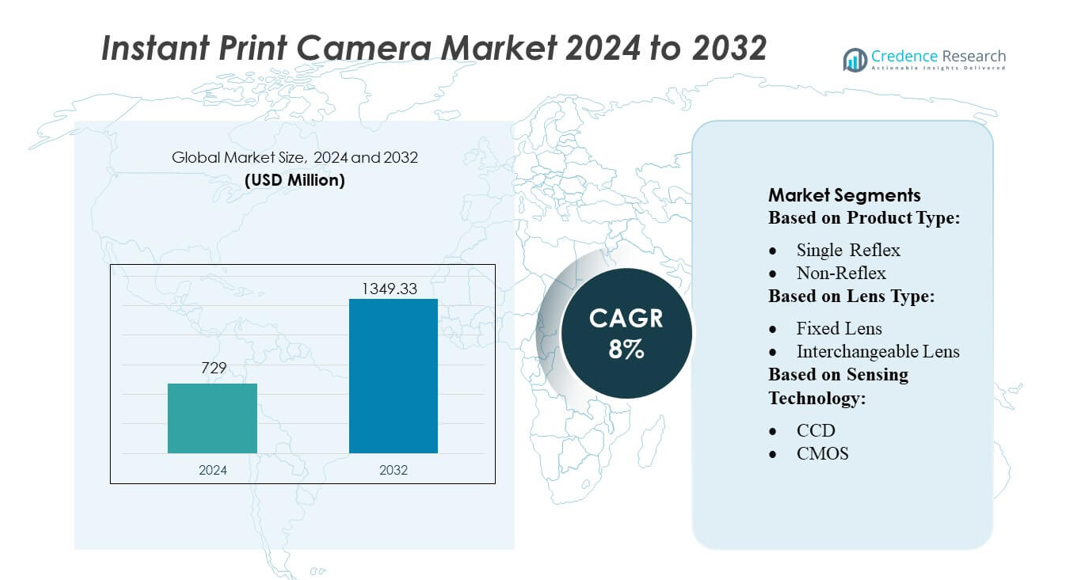
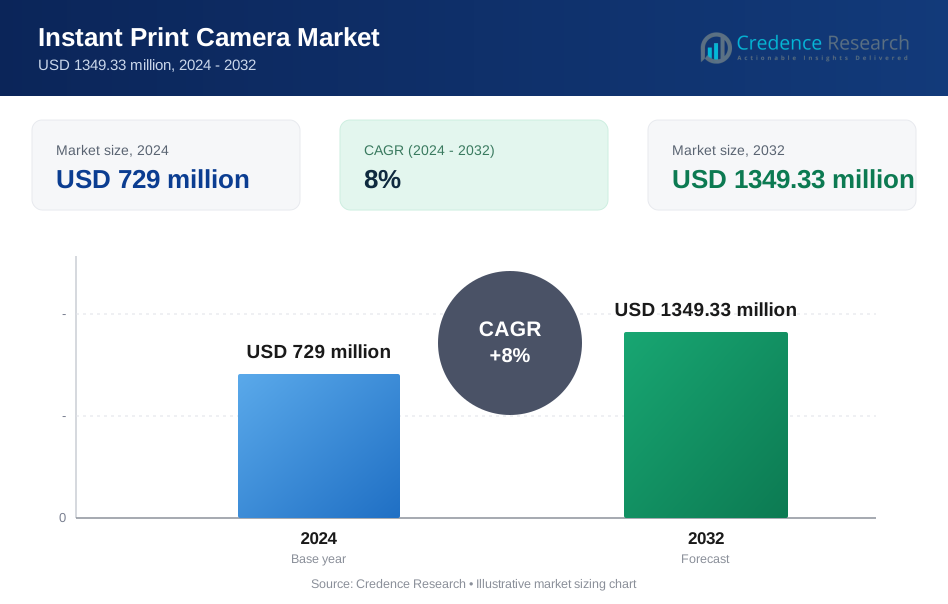
Instant Print Camera Market size was valued USD 729 million in 2024 and is anticipated to reach USD 1349.33 million by 2032, at a CAGR of 8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Instant Print Camera Market Size 2024 | USD 729 million |
| Instant Print Camera Market, CAGR | 8% |
| Instant Print Camera Market Size 2032 | USD 1349.33 million |
The Instant Print Camera Market is highly competitive, with leading players such as Olympus Corporation, Canon Inc., Leica Camera AG, FUJIFILM Holdings Corporation, OM Digital Solutions Corporation, Nikon Corporation, SIGMA CORPORATION, RICOH IMAGING COMPANY, LTD., Eastman Kodak Company, and Panasonic Corporation driving innovation and market growth. These companies focus on developing compact, user-friendly cameras with advanced printing technology, smart connectivity, and stylish designs to cater to lifestyle-oriented consumers. Product launches, regional expansion, and targeted marketing strengthen their market presence and consumer engagement. North America remains the leading region, capturing approximately 35% of the global market share, driven by high disposable income, strong social media engagement, and the popularity of instant photography among millennials and Gen Z consumers. Technological advancements and experiential marketing continue to reinforce the region’s dominance and attract broader adoption.
Market Insights
- The Instant Print Camera Market size was valued at USD 729 million in 2024 and is projected to reach USD 1349.33 million by 2032, growing at a CAGR of 8% during the forecast period.
- Growth is driven by rising consumer demand for instant photography, technological advancements in sensors and printing, and the popularity of compact, portable, and user-friendly cameras.
- Trends include integration of smart features, mobile connectivity, and lifestyle-oriented designs, as well as increased adoption through e-commerce and omnichannel retail platforms.
- The market is highly competitive, with key players focusing on product innovation, targeted marketing, and regional expansion to enhance consumer engagement and maintain market share.
- North America leads with approximately 35% market share, followed by Europe and Asia-Pacific, while fixed-lens and CMOS sensor cameras dominate their respective segments due to ease of use and affordability.
Market Segmentation Analysis:
By Product Type
In the Instant Print Camera Market, the non-reflex segment dominates, accounting for approximately 62% of the market share. Non-reflex cameras are favored for their compact design, ease of use, and immediate photo-printing capability, appealing to casual photographers and social media enthusiasts. Growth is driven by rising demand for portable imaging solutions and the trend of instant gratification in personal photography. Single reflex cameras, while offering higher image quality and advanced features, witness slower adoption due to their bulkier form factor and higher price points.
- For instance, Canon’s IVY CLIQ+ Instant Camera Printer employs an 8‑megapixel sensor and delivers peel‑and‑stick 2″×3″ ZINK™ photos in 50 seconds or less per print, combining digital capture and immediate print output in a compact device.
By Lens Type
Fixed lens cameras lead the lens type segment, capturing nearly 70% of the market share. Their popularity stems from simplicity, affordability, and reliable performance for casual and recreational users. Fixed lens instant cameras meet the demand for lightweight, ready-to-use devices without requiring technical knowledge of interchangeable lens systems. Interchangeable lens cameras, while attractive to professional users seeking creative flexibility, experience limited growth due to higher costs and complexity, positioning fixed lens models as the primary driver of market expansion.
- For instance, SOFORT 2 supports printing of Instax‑Mini format photo paper via a simple manual print lever, offers a macro mode capable of close‑focus down to 10 cm, and provides 10 lens and 10 film‑effect options - highlighting how a fixed‑lens design can deliver both simplicity and creative flexibility.
By Sensing Technology
CMOS-based instant print cameras dominate the sensing technology segment with a market share of approximately 65%. CMOS sensors offer lower power consumption, faster image processing, and better performance in compact, portable camera designs, aligning with consumer preferences for instant photography. CCD sensors, although providing higher image fidelity in certain lighting conditions, see slower adoption due to higher production costs and larger module size. The increasing integration of CMOS technology in user-friendly, budget-friendly instant cameras fuels overall market growth and strengthens its leadership in the segment.
Key Growth Drivers
Rising Consumer Preference for Instant Photography
The growing demand for instant photography among millennials and Gen Z is a primary growth driver. Consumers increasingly seek devices that provide immediate tangible prints for social sharing, scrapbooking, and personal keepsakes. The trend toward experiential and creative content consumption fuels purchases of instant print cameras. Ease of use, compact design, and social media compatibility enhance appeal. This shift in consumer behavior toward instant, shareable content significantly drives market expansion, encouraging manufacturers to innovate and launch more user-friendly, portable camera models.
- For instance, FUJIFILM’s recently launched hybrid model, instax WIDE Evo, offers a wide-format lens with wide-angle capability, a 3.5‑inch LCD for framing and preview, and supports combining multiple film and lens effects for creative output - directly catering to younger users wanting instant tangible prints plus modern creative control.
Technological Advancements in Camera Features
Innovations in camera sensors, printing mechanisms, and smart connectivity are accelerating market growth. Integration of CMOS sensors, high-speed printing, and mobile app compatibility improves image quality, efficiency, and user experience. Features like filters, stickers, and augmented reality overlays enhance creative expression and engagement. These technological enhancements attract both casual and professional users seeking multifunctional instant cameras. Continuous investment in R&D and the adoption of advanced electronics and compact design innovations position the market for sustained growth over the forecast period.
- For instance, OM SYSTEM OM-5 Mark II delivers in‑body 5‑axis image stabilization providing up to 6.5 stops of shutter speed compensation at center and, when paired with compatible lenses, up to 7.5 stops via 5‑axis sync IS - enabling sharp handheld shots even under challenging conditions.
Rising Popularity of DIY and Personalized Photography Products
The DIY culture and demand for personalized, tangible products drive adoption of instant print cameras. Consumers increasingly value creating custom photo albums, gifts, and decorative items, which instant cameras enable effortlessly. Social media trends and influencer-driven campaigns further fuel interest in personalized photography. This trend also supports cross-industry collaborations with stationery and lifestyle brands, expanding the market’s reach. As personalization becomes a key purchasing factor, instant print camera manufacturers capitalize on consumer desire for unique, interactive experiences, boosting overall sales and market penetration.
Key Trends & Opportunities
Integration of Smart Features and Mobile Connectivity
Smart instant print cameras with Bluetooth, Wi-Fi, and app-based controls are gaining traction. These features allow seamless printing from smartphones, editing photos digitally before printing, and sharing content on social media platforms. The opportunity lies in combining instant physical prints with digital convenience, appealing to tech-savvy users. Manufacturers can leverage this trend by introducing companion apps, cloud storage options, and AI-based enhancements, creating a hybrid experience that bridges traditional photography with modern digital demands, expanding market reach.
- For instance, SIGMA Corporation recently launched the Sigma BF in 2025, a full‑frame mirrorless camera distinguished by a radically simplified design and robust technical specs.
Growing Popularity of Compact and Portable Designs
Compact, lightweight, and stylish camera designs are increasingly favored, providing convenience for travel, events, and social gatherings. The trend toward portability aligns with consumer lifestyles, where mobility and aesthetics are key purchasing factors. There is significant opportunity for manufacturers to innovate in ergonomics, battery efficiency, and design customization. By offering visually appealing, easy-to-carry cameras, companies can capture younger demographics and casual users, driving both adoption and repeat purchases in the instant print camera market.
- For instance, RICOH IMAGING demonstrates its commitment to portability through models such as the Ricoh GR III and the recently released Ricoh GR IV. The GR III weighs approximately 257 g (with battery and SD card) and measures 109.4 mm × 61.9 mm × 33.2 mm, making it pocket-sized and ideal for travel or street photography.
Expanding E-commerce and Omnichannel Distribution
The growth of e-commerce platforms and omnichannel retail strategies provides opportunities for broader market penetration. Online platforms allow consumers to compare features, access product reviews, and make informed purchases conveniently. Manufacturers can leverage direct-to-consumer sales, targeted promotions, and exclusive online editions to reach tech-savvy buyers. Omnichannel strategies, combining online and offline presence, enhance visibility and brand loyalty. This distribution evolution supports increased sales volumes, especially in regions with limited physical retail presence, fueling overall market growth.
Key Challenges
High Cost of Advanced Instant Cameras
The premium pricing of advanced instant print cameras with smart features, interchangeable lenses, and high-resolution sensors restricts adoption among price-sensitive consumers. Cost barriers can slow market penetration in emerging regions where disposable income for luxury or niche photography products is limited. Manufacturers must balance innovation with affordability to maintain competitiveness. Without cost-effective options, mass-market adoption may remain constrained, limiting growth potential and slowing the transition from casual cameras to technologically advanced instant print solutions.
Limited Print Media Durability and Ongoing Consumable Costs
Instant print cameras rely on specialized photo paper, which adds recurring costs and may affect long-term consumer satisfaction. Additionally, print durability can vary, leading to fading or smudging over time. These factors can discourage frequent use and influence purchase decisions, especially among budget-conscious users. The dependence on proprietary consumables also restricts user flexibility and increases overall ownership costs, posing a notable challenge to market expansion and long-term adoption of instant print camera systems.
Regional Analysis
North America:
North America leads the Instant Print Camera Market, accounting for approximately 35% of the global share. High consumer disposable income, strong social media engagement, and growing popularity of lifestyle and DIY photography drive market growth. The U.S. and Canada witness high adoption of compact and technologically advanced cameras, including models with smart connectivity and mobile integration. Retail penetration through e-commerce and electronics stores enhances accessibility. Additionally, influencer marketing and experiential campaigns amplify demand among millennials and Gen Z consumers. North America remains a key innovation hub, encouraging product launches and R&D investments that sustain market dominance.
Europe:
Europe holds around 28% of the Instant Print Camera Market, driven by growing interest in personalized photography and creative expression. Countries like Germany, the U.K., and France show strong adoption of instant cameras for lifestyle, travel, and gifting purposes. High smartphone penetration combined with a preference for hybrid devices that integrate mobile apps and instant printing fuels growth. Additionally, fashion-conscious and experience-driven consumer segments propel demand for stylish, compact models. The region’s focus on sustainability also encourages innovations in eco-friendly printing materials, offering new opportunities for camera manufacturers to expand market presence and maintain steady growth.
Asia-Pacific:
Asia-Pacific accounts for nearly 25% of the market share, with China, Japan, and South Korea emerging as key contributors. Rising disposable income, increasing youth population, and high social media usage drive instant camera adoption. The region benefits from rapid urbanization and a growing interest in experiential and DIY photography. Affordable, compact, and trendy camera models gain traction among millennials and Gen Z. E-commerce platforms play a crucial role in distribution, making devices accessible to wider demographics. Continuous technological innovations and collaborations with lifestyle brands offer opportunities to capture further market share in this fast-growing region.
Latin America:
Latin America represents approximately 7% of the Instant Print Camera Market. Growth is fueled by increasing smartphone integration, rising interest in social and experiential photography, and expanding e-commerce access. Countries like Brazil and Mexico show adoption of portable and affordable instant cameras, especially among younger consumers. Limited consumer awareness and economic fluctuations pose adoption challenges, but marketing initiatives highlighting personalization, DIY projects, and social sharing create growth opportunities. Collaborations with local retailers and online platforms enhance accessibility and brand visibility, positioning Latin America for gradual market expansion in both urban and semi-urban regions.
Middle East & Africa:
The Middle East & Africa (MEA) region holds roughly 5% of the global instant print camera market. Growth is driven by rising urbanization, increased disposable income in GCC countries, and growing social media engagement. Lifestyle and gifting trends, especially during festivals and events, encourage adoption. However, limited retail infrastructure and higher import costs can constrain market penetration. E-commerce expansion and targeted promotional campaigns provide opportunities to improve accessibility. Manufacturers focusing on compact, portable, and stylish cameras tailored to regional preferences can leverage these trends to strengthen presence and gradually increase the market share across MEA.
Market Segmentations:
By Product Type:
- Single Reflex
- Non-Reflex
By Lens Type:
- Fixed Lens
- Interchangeable Lens
By Sensing Technology:
- CCD
- CMOS
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Instant Print Camera Market include Olympus Corporation, Canon Inc., Leica Camera AG, FUJIFILM Holdings Corporation, OM Digital Solutions Corporation, Nikon Corporation, SIGMA CORPORATION, RICOH IMAGING COMPANY, LTD., Eastman Kodak Company, and Panasonic Corporation. The Instant Print Camera Market is highly competitive, driven by rapid technological advancements and evolving consumer preferences. Companies focus on differentiating products through features such as compact designs, high-resolution sensors, fast printing mechanisms, and smart connectivity with mobile devices. Innovation in user-friendly interfaces, customization options, and lifestyle-oriented designs strengthens brand positioning. Strategic initiatives, including product launches, regional expansions, and targeted marketing campaigns, enhance market presence and consumer engagement. Additionally, pricing strategies and omnichannel distribution play a critical role in capturing diverse consumer segments, balancing affordability with premium features to sustain growth in both mature and emerging markets.
Key Player Analysis
- Olympus Corporation
- Canon Inc.
- Leica Camera AG
- FUJIFILM Holdings Corporation
- OM Digital Solutions Corporation
- Nikon Corporation
- SIGMA CORPORATION
- RICOH IMAGING COMPANY, LTD.
- Eastman Kodak Company
- Panasonic Corporation
Recent Developments
- In April 2025, Genetec partnered with Axis Communications and Convergint to present integrated security solutions at The Security Event 2025. This collaboration shows a unified approach to advanced security technologies, combining expertise in video surveillance, access control, and system integration.
- In March 2025, Konica Minolta announced the sale of all shares and loans receivable by its subsidiary, MOBOTIX AG, to Certina Software Investments AG. MOBOTIX, known for its decentralized processing IP camera systems, will transition to new ownership as part of this deal. The divestiture aligns with Konica Minolta’s strategic restructuring efforts.
- In February 2025, Alarm.com acquired a majority stake in CHeKT, a Louisiana-based cloud platform specializing in remote video monitoring. This acquisition strengthens Alarm.com’s proactive video surveillance capabilities, offering improved security solutions for businesses and consumers.
- In February 2025, Hikvision introduced its latest Pro Series Network Cameras featuring ColorVu 3.0 technology, significantly improving low-light imaging performance. This advancement enhances visibility in dark environments, making the cameras ideal for round-the-clock surveillance
Report Coverage
The research report offers an in-depth analysis based on Product Type, Lens Type, Sensing Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to grow steadily due to rising demand for instant and personalized photography.
- Technological advancements in sensors, printing mechanisms, and connectivity will drive product innovation.
- Compact and portable camera designs will continue to attract younger consumers and casual photographers.
- Integration with mobile apps and smart devices will enhance user experience and market adoption.
- Expansion of e-commerce and omnichannel retail will improve accessibility and sales reach globally.
- Increasing social media engagement will boost demand for instant cameras for content creation and sharing.
- Customizable and lifestyle-oriented products will drive consumer preference and repeat purchases.
- Growth opportunities will emerge in emerging markets with rising disposable income and urbanization.
- Continuous R&D investment will enable higher-quality prints and faster printing speeds.
- Collaborations with lifestyle and stationery brands will strengthen market presence and consumer engagement.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Consumer Preference for Instant Photography
Millennials and Gen Z are increasingly seeking devices that provide immediate tangible prints for social sharing, scrapbooking, and personal keepsakes. This trend toward experiential and creative content consumption is fueling purchases of instant print cameras, especially those that are compact and easy to use.
Technological Advancements in Camera Features
Innovations such as CMOS sensors, high-speed printing, and mobile app compatibility are improving image quality and user experience. Enhanced features like filters, stickers, and augmented reality overlays are attracting both casual and professional users, driving market growth.
Popularity of DIY and Personalized Photography Products
The growing DIY culture and demand for personalized, tangible products are encouraging consumers to create custom photo albums, gifts, and decorative items with instant cameras. Social media trends and influencer-driven campaigns further boost interest in personalized photography.
Integration of Smart Features and Mobile Connectivity
Smart instant print cameras with Bluetooth, Wi-Fi, and app-based controls are gaining traction, allowing seamless printing from smartphones and digital editing before printing. This hybrid experience appeals to tech-savvy users and expands the market’s reach.
Expanding E-commerce and Omnichannel Distribution
The growth of e-commerce platforms and omnichannel retail strategies is making instant print cameras more accessible to a wider audience. Online platforms enable consumers to compare features and access reviews, while omnichannel approaches enhance brand visibility and sales reach globally.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Instant Print Camera Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Instant Print Camera Market projected to grow between 2025 and 2032?
Who are the major players in this market?
Who are the leading companies in the Instant Print Camera Market?
Which region commanded the largest share of the Instant Print Camera Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Lens Type
- 1.2.1 Fixed Lens
- 1.2.2 Interchangeable Lens
- 1.3 By Product Type
- 1.3.1 Single Reflex
- 1.3.2 Non-Reflex
- 1.4 By Sensing Technology
- 1.4.1 CCD
- 1.4.2 CMOS
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 729 million → 2032: USD 1349.33 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Instant Print Camera Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Instant Print Camera Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Instant Print Camera Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Instant Print Camera Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Instant Print Camera Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Instant Print Camera Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Instant Print Camera Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Instant Print Camera Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 729 million → 2032: USD 1349.33 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Instant Print Camera Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Lens Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fixed Lens
- 12.3.7.2 Interchangeable Lens
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Single Reflex
- 12.4.7.2 Non-Reflex
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sensing Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 CCD
- 12.5.7.2 CMOS
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Instant Print Camera Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Instant Print Camera Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Instant Print Camera Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Olympus Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Canon Inc.
- 17.4 Leica Camera AG
- 17.5 FUJIFILM Holdings Corporation
- 17.6 OM Digital Solutions Corporation
- 17.7 Nikon Corporation
- 17.8 SIGMA CORPORATION
- 17.9 RICOH IMAGING COMPANY, LTD.
- 17.10 Eastman Kodak Company
- 17.11 Panasonic Corporation
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

