
Market Overview:
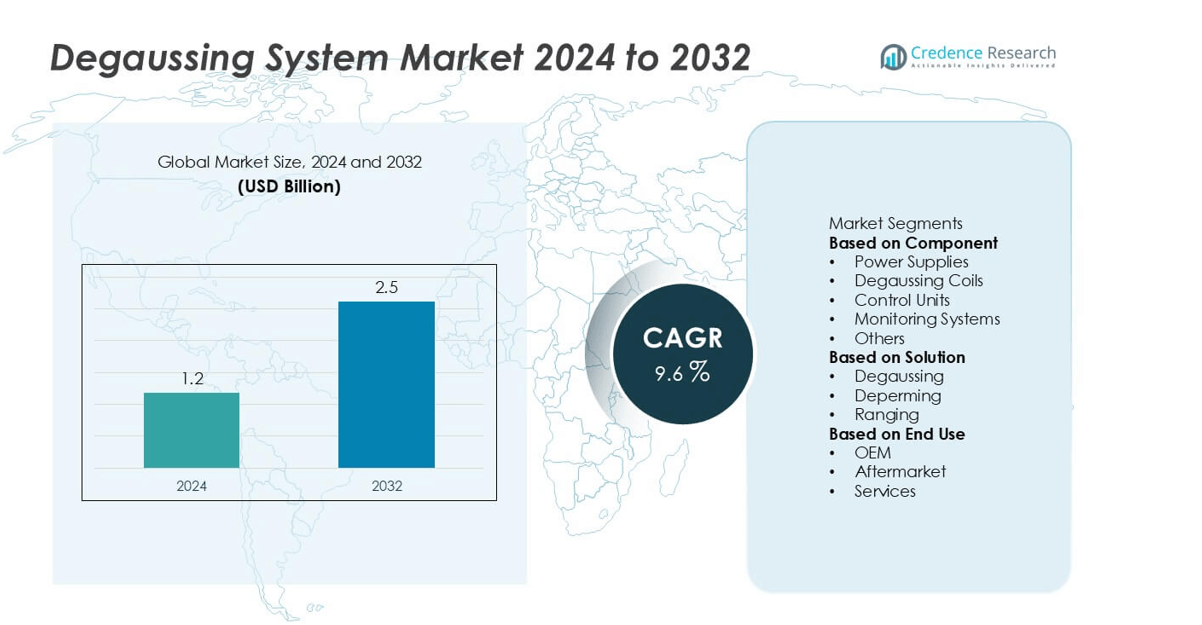
The global degaussing system market was valued at USD 1.2 billion in 2024 and is projected to reach USD 2.5 billion by 2032, growing at a CAGR of 9.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Degaussing System Market Size 2024 | USD 1.2 billion |
| Degaussing System Market, CAGR | 9.6% |
| Degaussing System Market Size 2032 | USD 2.5 billion |
The degaussing system market is led by prominent players such as L3Harris Technologies Inc, Ultra Electronics Holdings plc, Wärtsilä, Larsen & Toubro Limited, ECA Group, American Superconductor Corporation, IFEN SpA, Polyamp AB, STL Systems AG, and DA Group. These companies dominate through technological expertise, extensive product portfolios, and strong global partnerships with naval defense agencies. North America leads the market with a 32% share, driven by significant U.S. defense investments and modernization initiatives. Asia-Pacific, holding 29%, follows closely due to expanding naval programs in China, India, and Japan, while Europe, with a 27% share, benefits from advanced shipbuilding capabilities and ongoing fleet upgrades across NATO countries.
Market Insights
- The global degaussing system market was valued at USD 1.2 billion in 2024 and is projected to reach USD 2.5 billion by 2032, registering a CAGR of 9.6% during the forecast period.
- Market growth is driven by rising naval modernization programs and the increasing demand for vessel stealth and magnetic signature reduction, particularly in defense sectors across major economies.
- Key trends include the integration of AI and digital monitoring systems, automation in control units, and the growing use of compact, energy-efficient degaussing coils, which hold a 38% segment share in 2024.
- The market is moderately competitive, with leading players such as L3Harris Technologies, Wärtsilä, Ultra Electronics, and Larsen & Toubro Limited focusing on innovation, partnerships, and defense contracts, though high installation costs remain a restraint.
- Regionally, North America leads with a 32% share, followed by Asia-Pacific (29%) and Europe (27%), supported by strong naval investments and shipbuilding activities.
Market Segmentation Analysis:
By Component
The degaussing coils segment dominated the market in 2024, accounting for approximately 38% of the global share. Degaussing coils are critical in minimizing a vessel’s magnetic signature and preventing detection by magnetic sensors and mines. Their widespread adoption in naval and commercial vessels, coupled with technological advancements in coil materials and configurations, drives this segment’s growth. Power supplies and control units also show steady demand, driven by modernization initiatives and integration of automated systems for improved efficiency and operational reliability in naval applications.
- For instance, L3Harris Technologies developed degaussing systems that provide precise, controlled direct current to independent degaussing coils embedded throughout a ship's hull. These systems use Bipolar Amplifier (BPA) power supplies with an output power rating of 8.7 kW and an output current of up to ±24 amperes per amplifier, operating in parallel for redundancy or increased power requirements
By Solution
The degaussing segment held the largest market share of around 45% in 2024, owing to its essential role in reducing magnetic interference and enhancing vessel stealth capabilities. Naval defense forces worldwide are investing heavily in advanced degaussing systems to protect ships and submarines from magnetic mines and detection threats. The deperming and ranging segments are gaining traction as support solutions, particularly in retrofitting programs and performance verification, but degaussing remains the core technology underpinning maritime magnetic signature control.
- For instance, Wärtsilä Defense developed an automated degaussing control system that integrates with shipboard combat management networks and delivers magnetic compensation within 0.1 µT accuracy. The system can process magnetic field data from up to 24 onboard sensors simultaneously, optimizing coil currents in real time
By End Use
The OEM segment led the market with a 50% share in 2024, supported by increased production of new naval vessels and integration of advanced magnetic treatment systems during shipbuilding. Defense modernization programs in countries such as the U.S., India, and China have strengthened OEM demand, as governments emphasize stealth technologies in naval design. The aftermarket and services segments are also expanding, driven by system upgrades, maintenance contracts, and lifecycle management needs, particularly among fleets aiming to extend operational efficiency and compliance with modern naval standards.
Key Growth Drivers
Rising Naval Modernization and Fleet Expansion
Global naval forces are increasingly investing in modernizing their fleets to enhance defense capabilities, fueling demand for advanced degaussing systems. Many countries are commissioning new submarines, frigates, and destroyers equipped with low-magnetic-signature technologies to counter underwater mine threats. The integration of digital control systems and energy-efficient components in degaussing systems further accelerates adoption. This modernization trend, driven by defense budgets and strategic maritime security initiatives, remains a primary growth driver for the degaussing system market worldwide.
- For instance, BAE Systems is the prime contractor for the U.K. Royal Navy's Type 26 Global Combat Ships, also known as the City-class frigates, which are designed for anti-submarine warfare and other multi-mission roles. The ships are being built at BAE Systems' shipyards in Glasgow, Scotland.
Growing Emphasis on Vessel Stealth and Magnetic Signature Reduction
The need to reduce vessel detectability has intensified as naval warfare becomes more technology-driven. Degaussing systems play a crucial role in minimizing a ship’s magnetic footprint, making them essential for stealth operations. Increased use of advanced sensors and magnetic mines has prompted defense organizations to invest in next-generation degaussing and deperming technologies. As stealth becomes a defining factor in naval superiority, demand for magnetic treatment systems continues to rise across both new-build and retrofit applications.
- For instance, Ultra Electronics, now Ultra Maritime, has supplied numerous navies with advanced, automated degaussing systems. The systems employ a combination of technologies including some with fluxgate magnetometers and adaptive real-time compensation for the reduction of a vessel's magnetic signature.
Technological Advancements and Automation in Degaussing Systems
Rapid advancements in automation, real-time monitoring, and control technologies are transforming degaussing systems. Modern systems now feature intelligent control units, compact coils, and predictive maintenance capabilities, improving efficiency and reducing operational downtime. Integration with digital ship management platforms enhances system accuracy and responsiveness, supporting fleet readiness. These innovations not only improve system performance but also lower lifecycle costs, encouraging widespread adoption among naval and commercial vessel operators seeking smarter, energy-efficient degaussing solutions.
Key Trends & Opportunities
Integration of AI and Digital Monitoring Systems
The integration of artificial intelligence (AI) and IoT-based monitoring is emerging as a major trend in the degaussing system market. Smart monitoring platforms enable real-time magnetic field analysis, predictive maintenance, and automated calibration. This digital shift enhances operational reliability, reduces human intervention, and supports data-driven decision-making. As navies and shipbuilders adopt AI-driven automation for performance optimization, the demand for intelligent degaussing and control systems is expected to create new growth opportunities in the coming years.
- For instance, the Chinese People's Liberation Army (PLA) Navy has integrated an AI-assisted decision-making system within its degaussing support operations, which improved operational efficiency by 60% during a simulated emergency drill.
Rising Adoption in Commercial and Research Vessels
While defense remains the primary application, degaussing systems are increasingly used in commercial and research vessels to ensure magnetic safety and compliance with maritime standards. Offshore survey ships, oceanographic research vessels, and subsea exploration platforms are adopting compact, cost-effective systems. This expansion beyond defense applications opens new revenue streams for manufacturers. As maritime activities diversify, the commercial sector’s growing awareness of magnetic risk mitigation is expected to significantly contribute to market growth.
- For instance, Polyamp AB deployed its lightweight modular degaussing system on oceanographic research vessels operated by the Swedish Maritime Administration. Each system supports 18 magnetic coil zones and provides magnetic field stabilization below 0.3 µT during continuous survey operations.
Key Challenges
High Installation and Maintenance Costs
The high cost associated with installing and maintaining degaussing systems remains a major challenge. Advanced systems require complex integration with onboard electrical infrastructure, specialized components, and periodic recalibration. These expenses can deter smaller shipbuilders and commercial operators from adoption. Additionally, maintenance requires skilled technicians and frequent testing, increasing lifecycle costs. Manufacturers are focusing on developing cost-effective modular systems to address these concerns, but affordability continues to be a limiting factor in broader market penetration.
Limited Standardization and Technical Compatibility Issues
The lack of uniform standards for degaussing system design and integration creates compatibility challenges across different vessel types and naval fleets. Variations in magnetic field requirements, power configurations, and vessel materials complicate system standardization. This fragmentation often leads to longer installation timelines and customization costs. Furthermore, older vessels may face integration barriers due to outdated onboard electrical systems. To overcome these issues, manufacturers are increasingly investing in flexible, interoperable solutions that can adapt to diverse platform requirements.
Regional Analysis
North America
North America held a market share of 32% in 2024, driven by strong naval modernization initiatives and the presence of leading defense contractors in the United States. The U.S. Navy’s continuous investment in advanced degaussing and signature management technologies to enhance fleet stealth capabilities significantly supports regional growth. Additionally, the replacement of legacy systems with automated, digital degaussing units contributes to sustained demand. Canada’s focus on upgrading its naval fleet under defense procurement programs further strengthens the market outlook, ensuring North America remains a key hub for degaussing system innovation and deployment.
Europe
Europe accounted for 27% of the global degaussing system market in 2024, supported by robust naval expansion and modernization projects across the United Kingdom, France, Germany, and Italy. European shipyards are increasingly integrating advanced deperming and degaussing solutions into new naval platforms to meet NATO operational standards. The rise in cross-border defense collaborations and R&D investments in stealth technologies also fuels regional demand. Additionally, the emphasis on maritime security in the Baltic and North Seas reinforces Europe’s position as a prominent market for magnetic signature management solutions.
Asia-Pacific
Asia-Pacific captured 29% of the degaussing system market in 2024, driven by extensive naval development programs in China, India, Japan, and South Korea. Rising geopolitical tensions and increased defense budgets have accelerated procurement of technologically advanced vessels equipped with magnetic signature reduction systems. Domestic manufacturing capabilities, supported by government initiatives promoting defense indigenization, further boost regional production. Emerging shipbuilding hubs and modernization of existing fleets are expanding opportunities for both OEMs and aftermarket service providers, positioning Asia-Pacific as the fastest-growing regional market during the forecast period.
Middle East & Africa
The Middle East and Africa region held a 7% market share in 2024, primarily driven by defense investments aimed at enhancing naval surveillance and security in strategic maritime zones. Countries such as Saudi Arabia and the United Arab Emirates are focusing on fleet expansion and upgrading naval defense infrastructure. Growing maritime trade activities and the protection of offshore assets also stimulate demand for degaussing systems. However, budget constraints in some African nations and limited domestic manufacturing capabilities may slightly restrain regional growth compared to other global markets.
Latin America
Latin America accounted for 5% of the global degaussing system market in 2024, with growth supported by increasing naval procurement programs in Brazil, Mexico, and Chile. Regional governments are investing in strengthening maritime defense capabilities to safeguard coastal borders and trade routes. Brazil’s focus on modernizing its naval fleet, particularly submarine and surface vessel programs, contributes significantly to demand. Although limited defense spending in smaller economies poses a challenge, the gradual adoption of advanced ship technologies and regional shipbuilding initiatives are expected to drive steady market growth.
Market Segmentations:
By Component
- Power Supplies
- Degaussing Coils
- Control Units
- Monitoring Systems
- Others
By Solution
- Degaussing
- Deperming
- Ranging
By End Use
- OEM
- Aftermarket
- Services
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the degaussing system market includes major players such as L3Harris Technologies Inc, Ultra Electronics Holdings plc, Larsen & Toubro Limited, Wärtsilä, ECA Group, American Superconductor Corporation, IFEN SpA, Polyamp AB, STL Systems AG, and DA Group. These companies compete on technological innovation, product reliability, and strategic partnerships with naval forces and shipbuilders. The market is moderately consolidated, with established players focusing on expanding their portfolios through automation, digital control systems, and AI-integrated monitoring solutions. Strategic collaborations and government defense contracts remain crucial for sustaining market leadership. Additionally, growing investments in R&D to develop compact, energy-efficient degaussing solutions are enhancing competitiveness. Companies are also strengthening regional footprints by aligning with modernization programs and offering customized systems for both new-build and retrofit vessels, thereby ensuring long-term growth and market stability.
Key Player Analysis
- L3Harris Technologies Inc
- Ultra Electronics Holdings plc
- Larsen & Toubro Limited
- Wärtsilä
- ECA Group
- American Superconductor Corporation
- IFEN SpA
- Polyamp AB
- STL Systems AG
- DA Group
Recent Developments
- In September 2025, L3Harris Technologies Inc won a contract from Austal USA as the single-system vendor for the U.S. Navy’s T-AGOS-25 class ocean surveillance ships, which includes degaussing system solutions.
- In May 2024, Fincantieri Marinette Marine (FMM), the U.S. subsidiary of Fincantieri was awarded a contract exceeding USD 1 billion for the construction of the fifth and sixth Constellation-class frigates for the U.S. Navy.
- In August 2023, the Indonesian Navy added two Fani-class mine countermeasure vessels to its fleet. These vessels feature non-magnetic steel construction and include degaussing systems that help reduce magnetic signatures during mine-hunting operations. The ships also use electric propulsion systems, which help keep their acoustic signatures low
Report Coverage
The research report offers an in-depth analysis based on Component, Solution, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The degaussing system market will continue to grow steadily, driven by increased investments in naval modernization and stealth technologies.
- Rising global defense budgets will support the deployment of advanced magnetic signature reduction systems across naval fleets.
- Integration of AI, IoT, and digital monitoring systems will enhance automation and predictive maintenance capabilities.
- Demand for compact and energy-efficient degaussing coils will increase as shipbuilders prioritize space and power optimization.
- OEM installations will remain dominant, supported by the development of new submarines, destroyers, and surface vessels.
- Aftermarket and service segments will expand as older vessels undergo system upgrades and maintenance programs.
- Asia-Pacific will emerge as the fastest-growing region due to expanding defense industries and shipbuilding capacities.
- Collaborations between technology providers and naval defense agencies will strengthen innovation and system customization.
- Manufacturers will focus on developing modular, cost-effective degaussing systems to overcome installation challenges.
- Growing adoption in commercial and research vessels will diversify applications beyond traditional defense use.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Degaussing System market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Degaussing System market projected to grow between 2025 and 2032?
Which Degaussing System market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Degaussing System market?
Who are the leading companies in the Degaussing System market?
Which region commanded the largest share of the Degaussing System market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Degaussing System Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Degaussing System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1.2 billion → 2032: USD 2.5 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Degaussing System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Degaussing System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Degaussing System Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Degaussing System Market Drivers
- 3.3 Degaussing System Market Restraints & Challenges
- 3.4 Degaussing System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Degaussing System Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Degaussing System Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Degaussing System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Degaussing System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Degaussing System Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Degaussing System. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Degaussing System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Degaussing System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Degaussing System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Degaussing System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Degaussing System
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Degaussing System Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Degaussing System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Degaussing System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Degaussing System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Degaussing System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Degaussing System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Degaussing System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Degaussing System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
