
Low Loss Materials For 5G Market Overview:
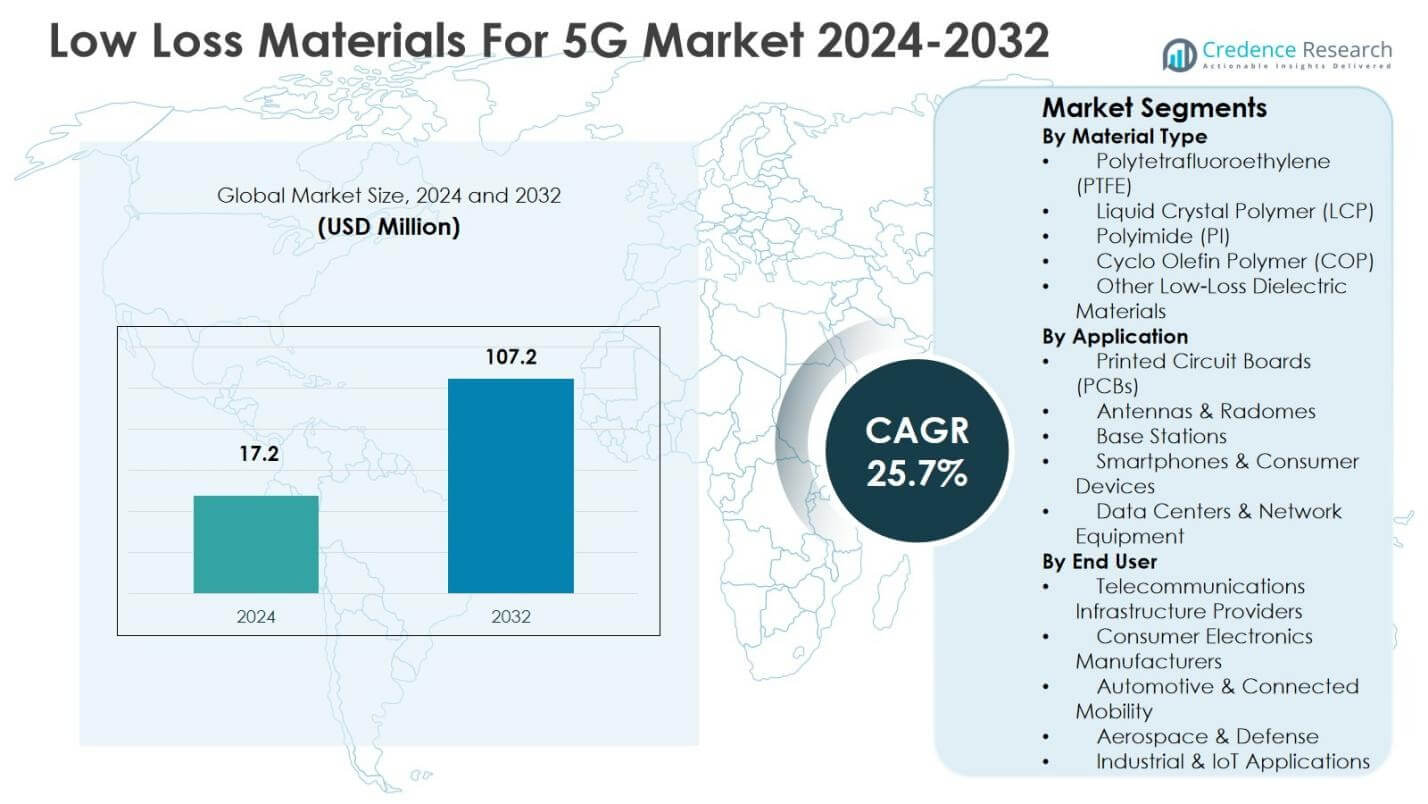
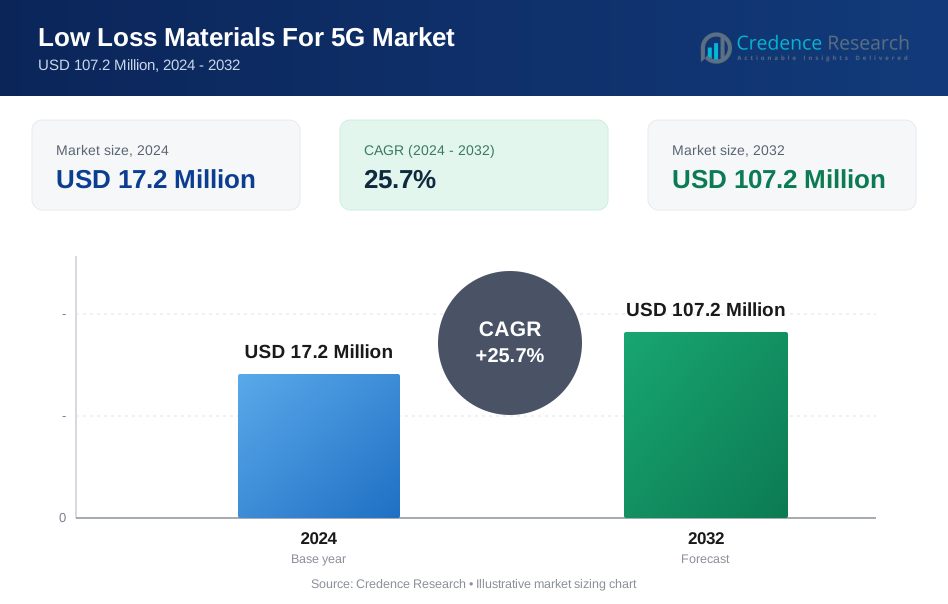
Low Loss Materials For 5G Market size was valued at USD 17.2 Million in 2024 and is anticipated to reach USD 107.2 Million by 2032, growing at a CAGR of 25.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Low Loss Materials For 5G Market Size 2024 | USD 17.2 million |
| Low Loss Materials For 5G Market, CAGR | 25.7% |
| Low Loss Materials For 5G Market Size 2032 | USD 107.2 million |
Low Loss Materials For 5G Market Insights
- Market growth is driven by rapid 5G infrastructure deployment, increasing mmWave adoption, and rising demand for high-frequency signal integrity across telecom equipment and electronic devices.
- Material innovation trends focus on ultra-low dielectric loss polymers, with PTFE holding 38.6% segment share in 2024 due to superior thermal stability and minimal signal attenuation.
- Market structure is shaped by strong R&D investments, capacity expansion, and long-term supply partnerships with telecom and PCB manufacturers to support antennas, PCBs, and base stations.
- Asia Pacific dominated with 7% regional share in 2024, followed by North America at 34.8%, while telecommunications infrastructure providers led end-user demand with a 46.3% segment share.
Low Loss Materials For 5G Market Segmentation Analysis:
By Material Type:
The By Material Type segment in the Low Loss Materials For 5G Market is led by Polytetrafluoroethylene (PTFE), which accounted for 38.6% market share in 2024, driven by its ultra-low dielectric constant, minimal signal attenuation, and strong thermal stability for high-frequency applications. PTFE is widely adopted in 5G base station antennas, RF substrates, and microwave circuits. Liquid Crystal Polymer (LCP) follows due to its flexibility and moisture resistance, while Polyimide (PI) and Cyclo Olefin Polymer (COP) support compact device designs. Growing mmWave deployment and dense network architectures continue to strengthen PTFE dominance.
- For instance, Rogers RO3035 laminates, ceramic-filled PTFE-based materials from the RO3000 series, deliver high-frequency performance in commercial microwave and RF circuits.
By Application:
The By Application segment is dominated by Printed Circuit Boards (PCBs), holding a 42.9% market share in 2024, supported by rising demand for high-frequency, low-latency signal transmission in 5G infrastructure and devices. Low loss materials are critical in multilayer PCBs to reduce insertion loss and enhance signal integrity at higher bandwidths. Base stations and antennas represent key secondary applications, while smartphones and data centers expand steadily with 5G densification. Continuous upgrades in network equipment, increased small-cell deployment, and advanced PCB material adoption remain the primary growth drivers for this segment.
- For instance, Isola Astra MT77 provides stable dielectric constant for multilayer PCBs in data center servers, ensuring low signal loss across 10 MHz to 40 GHz for high-speed 5G networking and edge computing reliability.
By End User:
The Telecommunications Infrastructure Providers segment accounted for the largest share at 46.3% in 2024, driven by large-scale investments in 5G network rollout, small-cell installations, and mmWave base station deployment. These providers require advanced low loss materials to ensure high data throughput, reduced latency, and stable network performance. Consumer electronics manufacturers follow, supported by rising 5G smartphone penetration. Automotive and industrial IoT adoption contributes steadily as connected systems expand. Government-backed 5G expansion programs and continuous network upgrades remain the core drivers sustaining dominance of telecommunications infrastructure providers.
Key Growth Drivers
Expanding Deployment of 5G Infrastructure
The Low Loss Materials For 5G Market is strongly driven by the rapid global deployment of 5G infrastructure, including macro base stations, small cells, and mmWave networks. High-frequency 5G signals require materials with low dielectric loss to maintain signal integrity, minimize attenuation, and support higher data rates. Telecom operators are investing heavily in network densification and capacity expansion to meet rising data traffic, directly increasing demand for advanced substrates, laminates, and polymers. Government-led spectrum auctions, smart city projects, and nationwide 5G rollout programs further accelerate material adoption across infrastructure components.
- For instance, Asahi Kasei developed XYRON™ modified polyphenylene ether (mPPE) resins, including foamed SunForce™, for 5G base stations, offering low dielectric constant (Dk) and low dissipation factor (Df) for improved signal transmission in antennas and modules.
Rising Adoption of High-Frequency Consumer Electronics
The growing penetration of 5G-enabled smartphones, tablets, wearables, and connected devices is a major driver for the Low Loss Materials For 5G Market. Device manufacturers increasingly rely on low loss polymers and laminates to support compact designs, higher bandwidth, and stable performance at elevated frequencies. As consumers demand faster connectivity, low latency, and seamless streaming, OEMs integrate advanced materials in antennas, RF modules, and printed circuit boards. Continuous device upgrades, shorter replacement cycles, and premium smartphone launches reinforce sustained demand for high-performance, low loss materials.
- For instance, DuPont provides Teflon laminates and Pyralux® flexible circuit materials for 5G RF modules and high-frequency PCBs, ensuring minimal signal loss in base stations and mobile devices to support multi-gigahertz transmission.
Growth of Automotive Connectivity and Industrial IoT
The expansion of connected vehicles and industrial IoT ecosystems significantly supports market growth. Advanced driver assistance systems, vehicle-to-everything communication, and autonomous driving platforms rely on 5G connectivity, requiring low loss materials to ensure reliable signal transmission. Similarly, smart factories and industrial automation systems depend on stable high-speed wireless networks for real-time data exchange. As automotive OEMs and industrial players integrate 5G-enabled solutions, demand for durable, thermally stable, and low dielectric loss materials continues to rise across harsh and mission-critical operating environments.
Key Trends & Opportunities
Increasing Adoption of mmWave and Advanced Antenna Designs
A key trend in the Low Loss Materials For 5G Market is the accelerating adoption of millimeter-wave frequencies and advanced antenna architectures such as massive MIMO and phased-array systems. These technologies demand materials with superior electrical performance, dimensional stability, and low signal loss at very high frequencies. This trend creates strong opportunities for suppliers offering innovative polymers, laminates, and composites tailored for mmWave applications. Material innovation focused on lightweight structures, thin substrates, and enhanced thermal performance positions manufacturers to capture growing demand from next-generation 5G and future 6G-ready networks.
- For instance, Rogers Corporation's RO3003 laminate features a dielectric constant of 3.00 ± 0.04 at 10 GHz and dissipation factor of 0.0013 at 10 GHz, enabling minimal signal attenuation in mmWave circuits up to 77 GHz.
Material Innovation and Miniaturization Opportunities
Ongoing material innovation presents significant opportunities as device and infrastructure designs move toward higher integration and miniaturization. Manufacturers are developing low loss materials with improved flexibility, moisture resistance, and processing efficiency to meet evolving design requirements. These advancements enable thinner PCBs, compact RF modules, and multi-layer antenna systems without compromising performance. Emerging applications such as edge computing hardware, private 5G networks, and indoor small-cell deployments further expand the addressable market, allowing material suppliers to differentiate through performance optimization and application-specific solutions.
- For instance, DuPont's Pyralux AP all-polyimide laminate offers low thermal expansion and excellent dimensional stability for rigid-flex fabrication, enabling 2 mil thick flexible circuits compatible with high-temperature assembly processes.
Key Challenges
High Cost of Advanced Low Loss Materials
One of the major challenges in the Low Loss Materials For 5G Market is the high cost associated with advanced polymers and high-frequency laminates. Materials such as PTFE and specialty composites involve complex manufacturing processes and stringent quality requirements, increasing overall production costs. These elevated costs can limit adoption among cost-sensitive device manufacturers and emerging market telecom operators. Price pressure from OEMs and competition from alternative materials intensify margin challenges, compelling suppliers to balance performance enhancements with cost optimization strategies.
Complex Processing and Supply Chain Constraints
Processing complexity and supply chain limitations present another significant challenge for market participants. Many low loss materials require specialized fabrication techniques, precise handling, and compatibility with advanced PCB manufacturing processes. Any inconsistency can impact electrical performance and yield rates. Additionally, dependence on limited raw material suppliers and global supply chain disruptions can affect availability and lead times. These constraints increase operational risks and demand close collaboration between material suppliers, PCB manufacturers, and end users to ensure consistent quality and scalable production.
Regional Analysis
North America
North America accounted for 34.8% market share in 2024 in the Low Loss Materials For 5G Market, supported by early adoption of 5G technology and strong investments in advanced telecom infrastructure. The region benefits from large-scale deployment of mmWave networks, dense small-cell installations, and continuous upgrades to data centers. Strong presence of leading material suppliers and telecom equipment manufacturers accelerates innovation and commercialization. High demand from aerospace, defense, and automotive connectivity applications further strengthens market growth. Favorable government initiatives for spectrum allocation and smart infrastructure continue to support sustained adoption of low loss materials.
Europe
Europe held 26.1% market share in 2024, driven by expanding 5G rollout across major economies and growing emphasis on industrial digitalization. The region’s focus on Industry 4.0, smart manufacturing, and connected mobility increases demand for low loss materials in base stations, antennas, and industrial communication systems. Regulatory support for energy-efficient and high-performance materials encourages adoption of advanced polymers and laminates. Strong automotive and aerospace industries further contribute to demand, particularly for vehicle connectivity and radar applications. Ongoing investments in private 5G networks and cross-border digital infrastructure support steady regional expansion.
Asia Pacific
Asia Pacific dominated the Low Loss Materials For 5G Market with a 31.7% market share in 2024, supported by large-scale 5G infrastructure deployment in China, Japan, South Korea, and India. High smartphone production, rapid urbanization, and aggressive network expansion by telecom operators drive significant material demand. The region benefits from strong electronics manufacturing ecosystems and cost-efficient production capabilities. Rising investments in smart cities, industrial automation, and connected transportation further fuel growth. Continuous expansion of data centers and local sourcing of advanced materials position Asia Pacific as a key growth engine for the market.
Latin America
Latin America captured 4.3% market share in 2024, reflecting gradual adoption of 5G technology across key markets such as Brazil, Mexico, and Chile. Telecom operators are increasingly investing in network upgrades to improve coverage and capacity, supporting demand for low loss materials in base stations and transmission equipment. Growing smartphone penetration and expanding data consumption contribute to steady market development. Government-led digital transformation initiatives and rising interest in smart infrastructure projects further support regional growth. While infrastructure deployment remains at an early stage, increasing private sector participation strengthens long-term market potential.
Middle East & Africa
The Middle East & Africa region accounted for 3.1% market share in 2024, driven by strategic investments in digital infrastructure and smart city initiatives. Countries in the Gulf Cooperation Council lead regional adoption through early 5G rollout and high investments in advanced telecom networks. Demand for low loss materials is supported by growing data center development, industrial connectivity, and defense applications. In Africa, gradual network modernization and increasing mobile data usage contribute to emerging demand. Government-backed digital economy programs and international partnerships are expected to enhance regional adoption over the forecast period.
Low Loss Materials For 5G Market Segmentations:
By Material Type
- Polytetrafluoroethylene (PTFE)
- Liquid Crystal Polymer (LCP)
- Polyimide (PI)
- Cyclo Olefin Polymer (COP)
- Other Low-Loss Dielectric Materials
By Application
- Printed Circuit Boards (PCBs)
- Antennas & Radomes
- Base Stations
- Smartphones & Consumer Devices
- Data Centers & Network Equipment
By End User
- Telecommunications Infrastructure Providers
- Consumer Electronics Manufacturers
- Automotive & Connected Mobility
- Aerospace & Defense
- Industrial & IoT Applications
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Low Loss Materials For 5G Market is shaped by key players such as Rogers Corporation, DuPont de Nemours, Inc., AGC Inc., Toray Industries, Inc., Shin-Etsu Chemical Co., Ltd., Mitsubishi Chemical Group, Panasonic Holdings Corporation, Sumitomo Chemical Co., Ltd., Isola Group, and Arlon Electronic Materials. The market is characterized by strong emphasis on material innovation, electrical performance optimization, and long-term supply agreements with telecom equipment manufacturers. Companies focus on developing ultra-low dielectric loss substrates and polymers to support mmWave frequencies, advanced antenna systems, and high-speed PCBs. Strategic investments in R&D, expansion of production capacity, and collaboration with PCB and semiconductor manufacturers strengthen market positioning. Growing demand from telecom infrastructure, consumer electronics, and automotive connectivity continues to intensify competition, while performance reliability and scalability remain key differentiating factors.
Key Player Analysis
- Rogers Corporation
- DuPont de Nemours, Inc.
- AGC Inc.
- Toray Industries, Inc.
- Shin-Etsu Chemical Co., Ltd.
- Mitsubishi Chemical Group
- Panasonic Holdings Corporation
- Sumitomo Chemical Co., Ltd.
- Arlon Electronic Materials
- Isola Group
Recent Developments
- In January 2024, DuPont launched a new line of low-loss dielectric materials designed specifically for high-frequency 5G applications, enhancing signal integrity in antennas and PCBs.
- In December 2025, SABIC announced an incremental expansion of its polyphenylene ether (PPE) oligomers production capacity, specifically for NORYL SA9000 used in high-performance PCBs supporting 5G base stations and AI servers, with completion scheduled for the second half of 2026.
Report Coverage
The research report offers an in-depth analysis based on Material Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Low Loss Materials For 5G Market will continue to expand with sustained global 5G network rollout and densification.
- Rising adoption of millimeter-wave frequencies will increase demand for ultra-low dielectric loss materials.
- Continuous innovation in polymers and laminates will improve thermal stability and signal integrity.
- Integration of low loss materials in advanced antenna and massive MIMO systems will accelerate.
- Growing production of 5G-enabled consumer electronics will support long-term material demand.
- Automotive connectivity and vehicle-to-everything applications will create new growth avenues.
- Expansion of private 5G networks in industrial and enterprise environments will drive adoption.
- Increased focus on miniaturization will encourage development of thinner and flexible materials.
- Strategic partnerships between material suppliers and telecom equipment manufacturers will strengthen supply chains.
- Early research into 6G-ready materials will influence future product development and market direction.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Low Loss Materials For 5G Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Low Loss Materials For 5G Market projected to grow between 2024 and 2032?
Which Low Loss Materials For 5G Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Low Loss Materials For 5G Market?
Who are the leading companies in the Low Loss Materials For 5G Market?
Which region commanded the largest share of the Low Loss Materials For 5G Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Low Loss Materials For 5G Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Low Loss Materials For 5G Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 17.2 Million → 2032: USD 107.2 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Low Loss Materials For 5G Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Low Loss Materials For 5G Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Low Loss Materials For 5G Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Low Loss Materials For 5G Market Drivers
- 3.3 Low Loss Materials For 5G Market Restraints & Challenges
- 3.4 Low Loss Materials For 5G Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Low Loss Materials For 5G Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Low Loss Materials For 5G Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Low Loss Materials For 5G category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Low Loss Materials For 5G Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Low Loss Materials For 5G Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Low Loss Materials For 5G market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Low Loss Materials For 5G Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Low Loss Materials For 5G Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Low Loss Materials For 5G Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Low Loss Materials For 5G (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Low Loss Materials For 5G Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Low Loss Materials For 5G Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Low Loss Materials For 5G Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Low Loss Materials For 5G Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Low Loss Materials For 5G Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Low Loss Materials For 5G Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Low Loss Materials For 5G Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Low Loss Materials For 5G Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Low Loss Materials For 5G Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
