
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Dietary Fibers Market Size 2024 | USD 7,160 Million |
| Dietary Fibers Market, CAGR | 8.96% |
| Dietary Fibers Market Size 2032 | USD 14,224.91 Million |
Market Overview
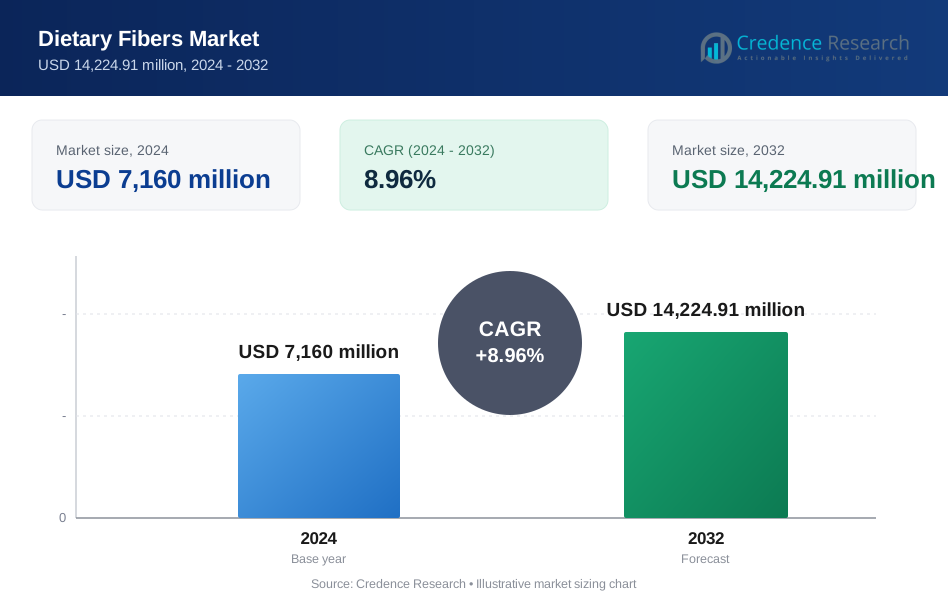
The Dietary Fibers Market is expected to grow from USD 7,160 million in 2024 to USD 14,224.91 million by 2032, registering a compound annual growth rate (CAGR) of 8.96%.
The dietary fibers market is driven by increasing consumer awareness of health benefits, including improved digestion, weight management, and reduced risk of chronic diseases. Growing demand for natural and plant-based foods, coupled with the rise in vegan and vegetarian diets, further boosts market growth. Additionally, the adoption of dietary fibers in functional foods, beverages, and supplements, along with the rising preference for clean-label products, aligns with shifting consumer preferences towards healthier lifestyles. Advancements in fiber extraction techniques and the incorporation of dietary fibers into various food applications are key trends enhancing market expansion.
The dietary fibers market is experiencing significant growth across various regions, driven by rising health awareness and demand for functional foods. Key players such as BENEO, ADM, Cargill, DuPont, Ingredion, and Roquette Frères are actively expanding their presence globally, with a strong foothold in North America, Europe, and the Asia-Pacific region. In North America, the demand for fiber-rich products is fueled by consumer interest in digestive health and weight management, while the Asia-Pacific region is witnessing rapid growth due to increasing disposable incomes and a shift towards plant-based diets. These players are innovating to meet regional consumer preferences and regulatory requirements.
Market Drivers
Growing Health and Wellness Awareness
Increasing awareness of the health benefits of dietary fiber is a major driver for market growth. Fiber is recognized for its role in disease prevention, including lowering the risk of heart disease, diabetes, and certain types of cancer. For instance, a study published in Nutrition Reviews found that individuals with high intakes of dietary fiber appear to be at significantly lower risk for developing coronary heart disease, stroke, hypertension, diabetes, obesity, and certain gastrointestinal diseases. It also supports digestive health by promoting healthy digestion, relieving constipation, and maintaining gut microbiota. Moreover, fiber-rich foods contribute to weight management by increasing satiety, reducing calorie intake, and promoting healthy metabolism.
Aging Population and Lifestyle Diseases
The aging global population has heightened the demand for dietary fiber to address age-related health issues, such as constipation and digestive disorders. As people age, the need for fiber-rich products to maintain digestive health and improve overall well-being increases. For instance, a narrative review in the International Journal of Medical and Pharmaceutical Research highlights the importance of dietary fiber in preventing obesity, type 2 diabetes, cancer, and cardiovascular disease. Furthermore, the rise in lifestyle diseases like obesity and diabetes further fuels the demand for fiber as an essential nutrient to manage these conditions and promote better health outcomes.
Shift Towards Natural and Organic Foods
There is a growing consumer preference for natural, organic, and minimally processed foods, with a focus on clean labels. Dietary fibers align perfectly with this trend as they are often derived from natural sources and are increasingly included in organic food products. Additionally, the demand for functional foods, which often contain added fiber to boost health benefits, continues to rise, further driving the market growth.
Plant-Based and Vegan Diets
The growing adoption of plant-based and vegan diets significantly contributes to the dietary fibers market. These diets are inherently rich in fiber, as plant-based foods serve as primary sources of this nutrient. Ethical and environmental concerns surrounding animal-based products are also driving the demand for plant-based fiber sources, further expanding the market for dietary fibers in food and beverages.
Market Trends
Health-Conscious Consumer Trends and Dietary Shifts
Growing awareness of the health benefits of dietary fiber is significantly shaping market trends. Increasing recognition of fiber's role in disease prevention, particularly in reducing the risk of chronic conditions such as heart disease, diabetes, and certain cancers, is driving consumer demand. Fiber’s ability to promote digestive health, relieve constipation, and support gut microbiota also contributes to its rising popularity. Furthermore, fiber-rich foods help with weight management by increasing satiety and reducing calorie intake. For instance, a report by Harvard Health highlights that high-fiber diets can help reduce the risk of developing dementia and support the immune system. Alongside these health benefits, there is a noticeable shift towards natural, organic, and minimally processed foods, with consumers seeking clean-label products with simple, transparent ingredient lists. The increasing demand for organic and functional foods, which often include added fiber, further accelerates the market's expansion. Moreover, the aging population, which faces digestive issues and requires dietary fiber to manage age-related health concerns, adds to the growing need for fiber-rich products. Additionally, the prevalence of lifestyle diseases such as obesity and diabetes is driving more consumers to adopt fiber-rich diets to manage these conditions effectively. The rise of plant-based and vegan diets, which rely on fiber-rich foods, is another significant factor driving the demand for dietary fiber. The growing interest in sustainable and ethical food choices is pushing consumers toward plant-based fiber sources, further supporting this market trend.
Innovation, Regulatory Support, and Regional Growth
The dietary fiber market is also experiencing significant growth due to innovations in product development and regulatory support. The food and beverage industry is incorporating fiber into a wide range of functional products, including yogurt, cereals, and beverages, catering to the increasing number of health-conscious consumers. Fiber supplements are also gaining popularity as a convenient way for individuals to meet their daily fiber requirements. In addition to innovation, regulatory bodies are providing support for fiber-rich products by allowing health claims, boosting consumer awareness and driving demand. Clear labeling of fiber content on food products also helps consumers make informed dietary choices. Another key trend is the dominance of soluble fiber, which is projected to continue leading the market due to its recognized health benefits, particularly in promoting gut health. The Asia-Pacific region is expected to lead the market, driven by growing health awareness, rising disposable incomes, and large populations. The COVID-19 pandemic has also accelerated the shift toward healthier eating habits, which further contributes to the increased demand for fiber-rich foods and supplements.
Market Challenges Analysis
Consumer Awareness and Acceptance Challenges
One of the significant barriers to the growth of the dietary fiber market is varying levels of consumer awareness. Many individuals remain unaware of the specific benefits of dietary fiber, often underestimating its importance in maintaining a balanced diet. For instance, a study published in Nutrients found that consumers are largely unaware of the many health benefits of dietary fiber, which dramatically decreases the likelihood that they consider this important nutrient during food choice. Misconceptions surrounding fiber, such as the belief that it causes bloating or digestive discomfort, can also deter consumers from incorporating more fiber into their daily intake. Additionally, some consumers may be reluctant to try fiber-rich products due to unfamiliarity or perceived inconvenience. Overcoming these knowledge gaps and changing consumer perceptions is essential for driving market growth. Manufacturers must invest in education and marketing campaigns to highlight the health benefits of dietary fiber, addressing common misconceptions and promoting its role in preventing chronic diseases, improving digestion, and supporting overall well-being.
Supply Chain, Competition, and Regulatory Hurdles
Supply chain challenges in the extraction and processing of dietary fiber are another hurdle for the market. Efficiently extracting fiber from a variety of sources such as fruits, vegetables, and grains can be complex, potentially impacting both supply consistency and costs. Furthermore, ensuring the standardization and consistent quality of fiber-rich products, particularly those derived from natural sources, presents a challenge for manufacturers. Alongside supply chain concerns, the dietary fiber market faces increasing competition from other functional ingredients, such as probiotics and prebiotics, which are gaining popularity for their gut health benefits. Other functional foods and supplements also vie for consumer attention, potentially diverting interest away from fiber-based products. Additionally, regulatory hurdles around health claims and labeling requirements can pose difficulties for manufacturers. Obtaining approval for health claims related to fiber, especially those addressing specific benefits, can be a lengthy and complex process. Compliance with fiber content and source labeling regulations further adds to the burden on manufacturers, especially smaller companies trying to navigate these requirements while keeping costs manageable.
Market Segmentation Analysis:
By Type:
The dietary fiber market is segmented into soluble and insoluble fibers, with each playing a unique role in health benefits. Soluble fibers, such as inulin, polydextrose, beta-glucan, and resistant starch, are gaining traction due to their ability to aid in digestion, lower cholesterol levels, and manage blood sugar. Inulin, in particular, is widely used for its prebiotic properties, promoting gut health. Insoluble fibers, including cellulose, hemicellulose, chitosan, chitin, and lignin, are primarily known for improving bowel movement regularity and preventing constipation. These fibers are commonly found in plant-based foods and are essential for maintaining a healthy digestive system. As consumer demand for functional foods grows, the inclusion of both soluble and insoluble fibers in a variety of food products continues to rise, contributing to market growth.
By Source: The source of dietary fibers plays a crucial role in determining their functionality and benefits. Cereals and grains, such as wheat, rice, and bran, are some of the primary sources of fiber in the diet. Wheat and rice bran, in particular, are rich in both soluble and insoluble fibers and are often used in functional food products. Fruits and vegetables, especially apples, are also significant contributors to the dietary fiber market, offering high amounts of both soluble and insoluble fibers. Other crops, such as oats and barley, are becoming increasingly popular as sources of beta-glucan and soluble fibers. As the market for natural, plant-based, and organic foods continues to expand, sourcing fibers from these materials aligns with growing consumer preferences for clean-label products, further driving market development.
Segments:
Based on Type:
- Soluble
- Inulin
- Polydextrose
- Dietary Fibers
- Beta-Glucan
- Insoluble
- Cellulose
- Hemicellulose
- Chitosan
- Chitin
- Lignin
- Resistant Starch
Based on Source:
- Cereals & Grains
- Wheat
- Rice
- Bran
- Others
- Fruits & Vegetables
- Apples
- Others
- Other Crops
Based on Application:
- Functional Food & Beverages
- Animal Feed
- Pet Food
- Pharmaceuticals
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the global dietary fibers market, accounting for approximately 30%. The region's high market share is driven by increasing consumer awareness of the health benefits of fiber, along with growing demand for functional foods and dietary supplements. The United States, in particular, is a major contributor to the growth of the market due to the rising prevalence of lifestyle diseases such as obesity and diabetes, which has increased the focus on preventive health measures. Moreover, the demand for clean-label and organic products is further boosting the consumption of dietary fibers. Manufacturers in North America are increasingly incorporating dietary fibers into a variety of products, including snacks, beverages, and dietary supplements, to cater to the health-conscious consumer base.
Asia-Pacific The Asia-Pacific region is expected to experience the highest growth rate in the dietary fibers market, with a projected market share of around 28%. This growth is driven by the increasing health awareness, rising disposable incomes, and growing population in countries such as China, India, and Japan. As consumers in the region become more health-conscious, there is a shift towards incorporating more fiber into their diets. The increasing adoption of plant-based diets and the demand for functional foods further contribute to the market expansion. The growing preference for natural and plant-based ingredients in dietary products aligns with the availability of fiber from local sources like rice, wheat, and fruits, supporting market growth in the region.
Key Player Analysis
- Kerry Inc.
- The Green Labs LLC
- Tate & Lyle
- Emsland Group
- Nexira
- ADM
- Ingredion Incorporated
- Cargill, Incorporated
- Roquette Frères
- DuPont
- BENEO
- Farbest Brands
Competitive Analysis
The dietary fibers market is highly competitive, with key players such as BENEO, ADM, Cargill, DuPont, Ingredion, Roquette Frères, Emsland Group, Kerry Inc., The Green Labs LLC, Nexira, Tate & Lyle, and Farbest Brands leading the market. These companies are focusing on product innovation, expanding their product portfolios, and investing in research and development to meet the growing demand for functional and health-promoting ingredients. Companies are increasingly developing fiber-rich products derived from natural, plant-based sources, catering to growing consumer demand for clean-label and functional foods. Many of these players emphasize sustainable sourcing, with a strong focus on health benefits such as improved digestion, weight management, and disease prevention. Competition is intensifying as brands strive to meet the rising demand for dietary supplements and food ingredients that promote gut health. Additionally, partnerships, mergers, and acquisitions are becoming common strategies to strengthen market presence and expand product offerings, further fueling competition. As consumer preferences shift toward health-conscious, plant-based diets, companies are investing in R&D to enhance their portfolios with innovative fiber solutions. The overall market dynamics are driven by advancements in technology, increasing health awareness, and a strong push for natural and organic ingredients.
Recent Developments
- In 2022, Brightseed Bioactives, a biotechnology company based in California, launched Brightseed Bio 01, a new dietary fiber that is formulated to enhance bioactive content and support gut health.
- In April 2022, Ingredion Incorporated acquired Germany-based KaTech, that provides advanced texture and stabilization solutions to the food and beverage industries. This acquisition expands Ingredion's Food Systems platform with a comprehensive suite of innovative solutions that assist food and beverage manufacturers with product formulation, ingredient functionality, and technical assistance.
Market Concentration & Characteristics
The dietary fibers market exhibits moderate to high concentration, with a few large players holding a significant share, while smaller regional players contribute to a diversified competitive landscape. Leading companies focus on product innovation, strategic partnerships, and expansions to strengthen their market position. These companies offer a range of dietary fiber solutions derived from natural sources such as cereals, grains, fruits, and vegetables, responding to the growing demand for health-promoting ingredients. Market characteristics include a shift towards clean-label, plant-based, and functional food products, as consumers become increasingly health-conscious. The market is characterized by continuous advancements in extraction and processing technologies, enabling the production of high-quality, cost-effective fibers. Additionally, the growing trend of personalized nutrition is influencing the market, with companies offering tailored fiber products to meet specific health needs, such as digestive health, weight management, and heart disease prevention. The emphasis on sustainability, ethical sourcing, and regulatory compliance also shapes the market dynamics.
Report Coverage
The research report offers an in-depth analysis based on Type, Source, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for dietary fibers is expected to grow as consumers become more health-conscious and focus on preventive health.
- The popularity of plant-based diets will drive the adoption of fiber-rich products derived from fruits, vegetables, and grains.
- Functional foods and beverages enriched with dietary fibers will continue to expand, catering to consumer preferences for convenience and health benefits.
- The dietary fiber market will see increased innovation in fiber extraction technologies, improving quality and reducing production costs.
- Soluble fibers like inulin and beta-glucan will dominate the market due to their digestive and heart health benefits.
- The growing trend of clean-label and organic products will encourage manufacturers to offer natural and minimally processed fiber solutions.
- Emerging markets, particularly in Asia-Pacific, will contribute to the significant growth of the dietary fibers market as disposable incomes rise.
- Personalized nutrition will influence the development of customized fiber products targeting specific health concerns such as obesity and gut health.
- Regulatory bodies will continue to support dietary fiber claims on product labels, further boosting consumer trust and awareness.
- Sustainability will be a key focus, with companies emphasizing ethical sourcing and eco-friendly practices in fiber production.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Health and Wellness Awareness
Increasing consumer understanding of the health benefits of dietary fiber, such as improved digestion, weight management, and reduced risk of chronic diseases, is driving demand for fiber-rich foods and supplements.
Aging Population and Lifestyle Diseases
The global rise in aging populations and the prevalence of lifestyle diseases like obesity and diabetes are boosting the need for dietary fibers to support digestive health and manage chronic conditions.
Shift Towards Natural and Organic Foods
Consumers are increasingly seeking natural, organic, and minimally processed foods, and dietary fibers derived from plant-based sources align with these clean-label preferences, fueling market growth.
Adoption of Plant-Based and Vegan Diets
The surge in plant-based and vegan diets, which are inherently high in fiber, is expanding the market as consumers look for ethical, sustainable, and health-promoting food options.
Innovation in Fiber Extraction and Functional Applications
Advancements in fiber extraction technologies and the incorporation of dietary fibers into a wide range of functional foods, beverages, and supplements are enhancing product quality and expanding market opportunities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Dietary Fibers market?
What factors are driving the growth of the Dietary Fibers market?
What are the key segments within the Dietary Fibers market?
What are some challenges faced by the Dietary Fibers market?
Who are the major players in the Dietary Fibers market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Soluble (Inulin, Polydextrose, Beta-Glucan, Resistant Starch)
- 1.2.2 Insoluble (Cellulose, Hemicellulose, Chitosan, Chitin, Lignin)
- 1.3 By Source
- 1.3.1 Cereals & Grains (Wheat, Rice, Bran, Others)
- 1.3.2 Fruits & Vegetables (Apples, Others)
- 1.3.3 Other Crops
- 1.4 By Application
- 1.4.1 Functional Food & Beverages
- 1.4.2 Animal Feed
- 1.4.3 Pet Food
- 1.4.4 Pharmaceuticals
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,160 million → 2032: USD 14,224.91 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dietary Fibers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dietary Fibers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dietary Fibers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dietary Fibers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dietary Fibers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dietary Fibers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dietary Fibers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dietary Fibers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,160 million → 2032: USD 14,224.91 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dietary Fibers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Soluble (Inulin, Polydextrose, Beta-Glucan, Resistant Starch)
- 12.3.7.2 Insoluble (Cellulose, Hemicellulose, Chitosan, Chitin, Lignin)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cereals & Grains (Wheat, Rice, Bran, Others)
- 12.4.7.2 Fruits & Vegetables (Apples, Others)
- 12.4.7.3 Other Crops
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Functional Food & Beverages
- 12.5.7.2 Animal Feed
- 12.5.7.3 Pet Food
- 12.5.7.4 Pharmaceuticals
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dietary Fibers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dietary Fibers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dietary Fibers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dietary Fibers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BENEO
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ADM
- 18.4 Cargill, Incorporated
- 18.5 DuPont
- 18.6 Ingredion Incorporated
- 18.7 Roquette Frères
- 18.8 Kerry Inc.
- 18.9 Tate & Lyle
- 18.10 Emsland Group
- 18.11 Nexira
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

