
Market Overview:
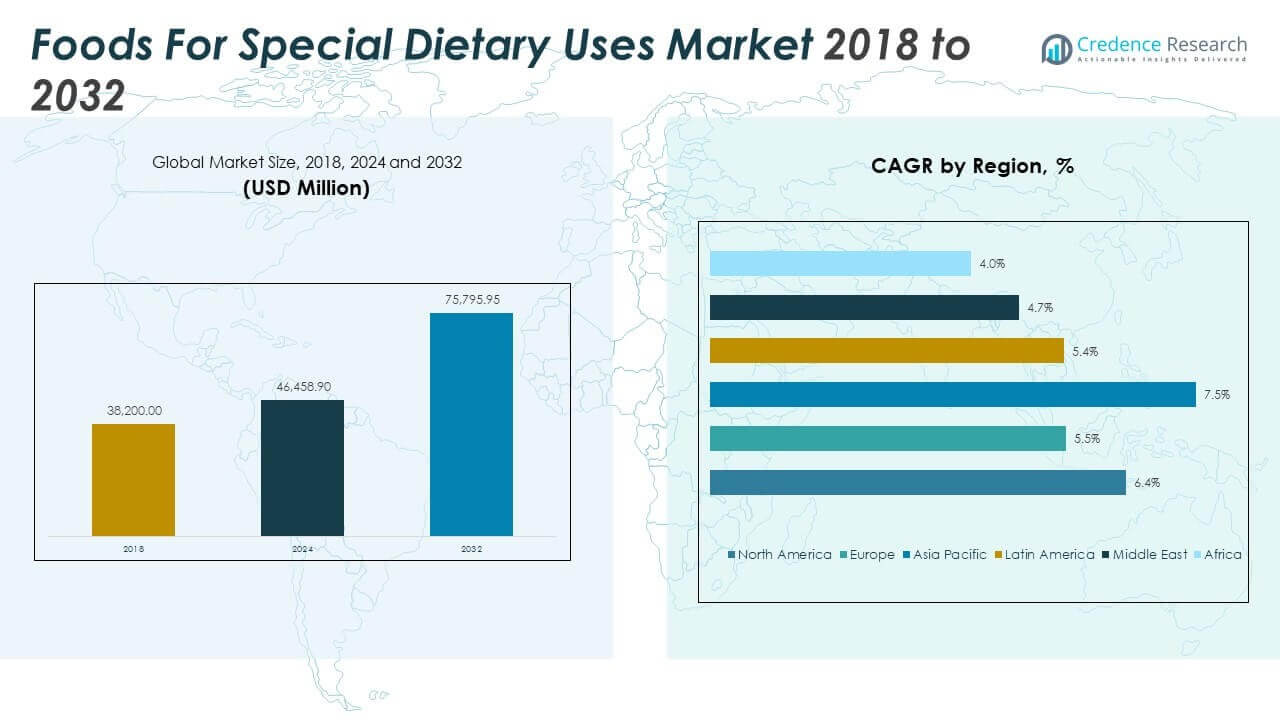
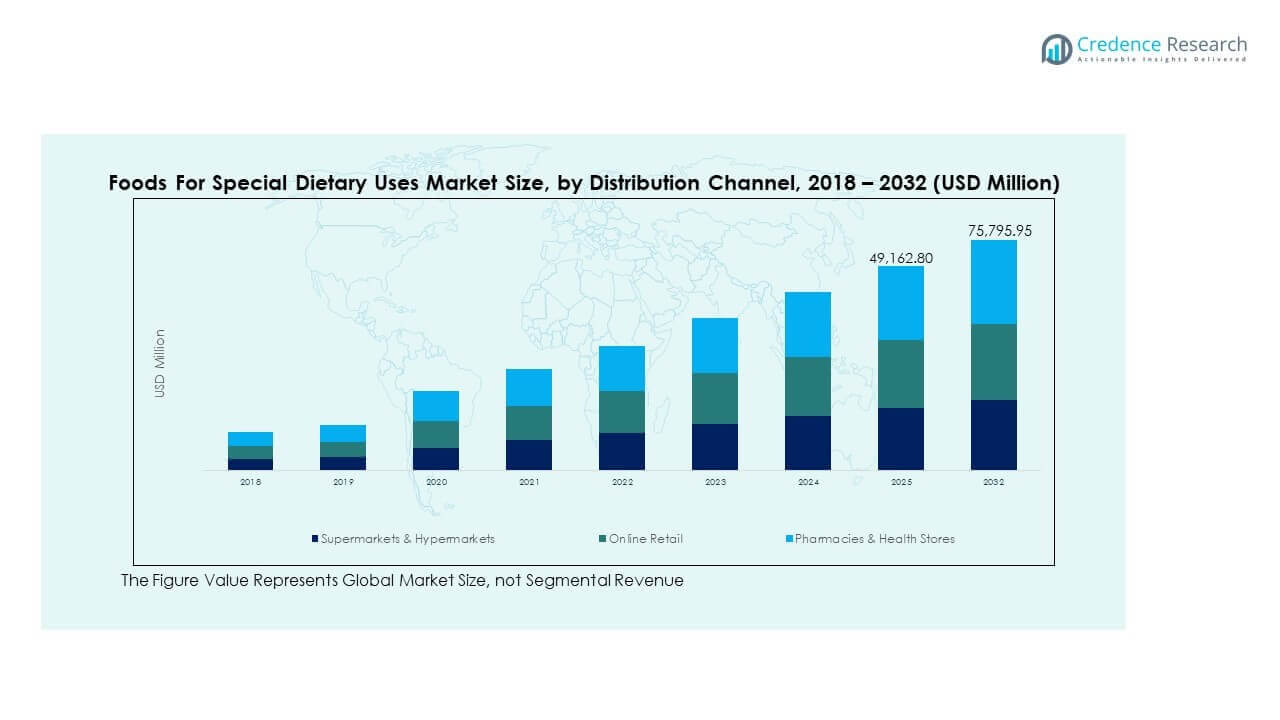
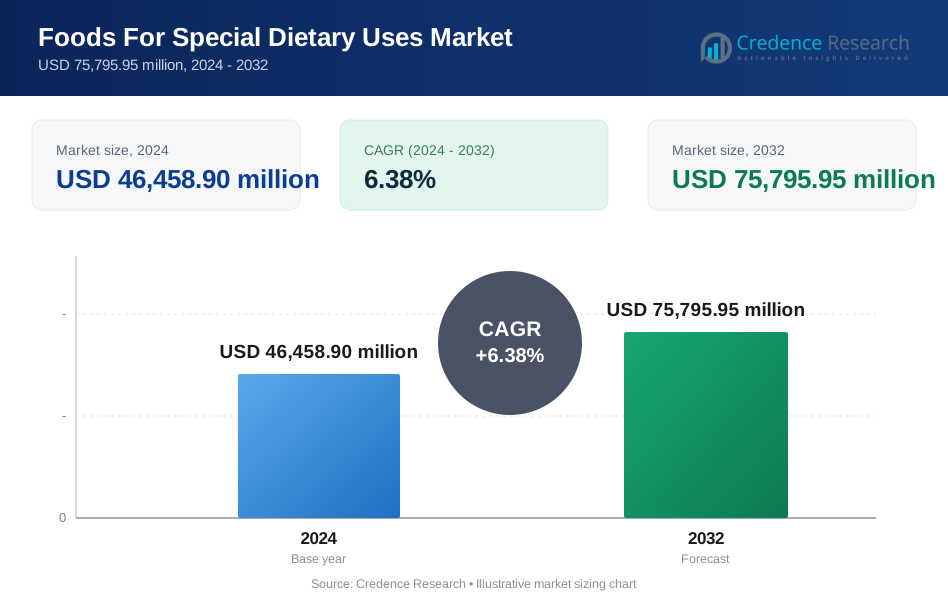
The Foods For Special Dietary Uses Market size was valued at USD 38,200.00 million in 2018 to USD 46,458.90 million in 2024 and is anticipated to reach USD 75,795.95 million by 2032, at a CAGR of 6.38% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Foods For Special Dietary Uses Market Size 2024 | USD 46,458.90 million |
| Foods For Special Dietary Uses Market, CAGR | 6.38% |
| Foods For Special Dietary Uses Market Size 2032 | USD 75,795.95 million |
The market is expanding due to rising demand for condition-specific nutrition. Consumers with diabetes, allergies, metabolic disorders, and digestive conditions are increasingly turning to targeted dietary solutions. Growth is supported by aging populations, growing chronic illness rates, and preventive health awareness. Food manufacturers continue to develop fortified, low-allergen, and high-protein options across product categories. Clinical nutrition adoption is also growing in hospitals and outpatient care. Increased marketing around functional benefits is driving consumer trial and repeat purchases. Label transparency, medical validation, and personalization further strengthen market adoption.
North America leads due to mature healthcare systems, advanced product innovation, and high spending on specialty nutrition. Europe follows closely with a focus on clean-label, organic, and allergen-free foods supported by regulatory frameworks. Asia Pacific is emerging as a high-growth region, driven by rising income, health awareness, and urban lifestyle shifts in countries like China, India, and Japan. Latin America, the Middle East, and Africa are showing steady gains, supported by nutrition programs, improving access, and growing urban populations.
Market Insights:
- The Foods for Special Dietary Uses Market reached USD 46,458.90 million in 2024 and is projected to reach USD 75,795.95 million by 2032, growing at a CAGR of 6.38% from a 2018 value of USD 38,200.00 million.
- North America led the market in 2024 with a 36.1% share due to strong healthcare infrastructure, followed by Asia Pacific at 30.9% and Europe at 20.7% driven by clean-label and organic demand.
- Asia Pacific is the fastest-growing region with a CAGR of 7.5%, supported by rising disposable income, health awareness, and demand for infant and functional nutrition.
- Infant formula & baby food dominated product share in 2024, while functional foods & nutraceuticals are growing due to consumer interest in performance and preventive nutrition.
- Supermarkets and hypermarkets lead distribution, while online retail is expanding rapidly with personalized health offerings and greater accessibility.
Market Drivers
Rising Global Prevalence of Chronic Diseases Is Prompting Long-Term Demand for Specialty Dietary Products
The growing burden of non-communicable diseases is fueling demand for health-focused food options. Consumers with diabetes, hypertension, and cardiovascular issues seek customized nutrition. The Foods For Special Dietary Uses Market benefits from this structural health shift. Patients are encouraged to manage conditions through dietary interventions, supporting long-term product adoption. Medical professionals recommend condition-specific diets, driving mainstream acceptance. Products with low sugar, low sodium, and heart-healthy fats show consistent shelf rotation. Specialized products cater to prevention, not just symptom management. This lifestyle pivot creates sustained, repeat-driven market growth.
- For instance, Abbott’s Glucerna diabetes-specific nutrition formula provides 10 grams of protein and 4 grams of fiber per 237 ml serving, using low-glycemic carbohydrates to help manage blood glucose levels in clinical nutrition settings.
Health-Conscious Population Across Age Groups Is Driving Nutritional Customization in Diets
Consumers across age brackets are demanding targeted nutritional solutions for various life stages. Infant formulas, geriatric nutrition, and maternal supplements are witnessing strong uptake. The Foods For Special Dietary Uses Market captures value across these age-focused product lines. Families prioritize nutrition from birth through old age, creating a continuous consumer base. Brands now create age-appropriate formulations that meet evolving dietary needs. Increasing focus on bone health, immunity, and cognitive function drives innovation. Fortified and functional food launches reflect these health targets. This age-wide appeal boosts volume and brand loyalty.
- For instance, Nestlé’s Boost High Protein nutritional drink provides 20 grams of protein and 240 calories per 325 ml bottle, formulated with added vitamins D and B12 to support muscle health in adults over 50.
Fitness-Oriented and Active Lifestyles Are Elevating Consumption of Functional and Protein-Rich Foods
Urban consumers adopting fitness regimens demand food products aligned with physical performance goals. Protein-rich foods, muscle recovery blends, and low-carb items dominate gym-friendly diets. The Foods For Special Dietary Uses Market benefits from this health-performance link. Athletes and active consumers prioritize macros, pushing demand for functional ingredients. Clean labels and performance claims influence purchase decisions. Brands introduce personalized meal solutions for pre- and post-workout needs. E-commerce and social media drive niche fitness food discovery. This growing lifestyle segment creates recurring demand across retail channels.
Medical Nutrition Therapy Adoption in Hospitals and Clinics Is Reinforcing Clinical Demand
Hospitals and healthcare centers increasingly prescribe special dietary foods to support treatment outcomes. Medical nutrition therapy requires tailored diets for post-surgery recovery, cancer care, or digestive issues. The Foods For Special Dietary Uses Market integrates into clinical pathways and insurance reimbursements. Medical-grade supplements and enteral nutrition are being positioned as therapeutic necessities. Institutional adoption improves credibility and builds scale. Clinical trials and efficacy data strengthen trust in product performance. Dieticians and specialists shape purchasing patterns for long-term conditions. Healthcare integration boosts volume sales and institutional partnerships.
Market Trends
Personalized Nutrition and DNA-Based Diet Planning Are Creating Tailored Consumer Experiences
Advances in genetics and diagnostics are enabling customized food solutions based on individual health profiles. Consumers now access diet plans tailored to gut health, metabolism, and food intolerance. The Foods For Special Dietary Uses Market leverages this personalization wave through subscription services and apps. Companies are partnering with health-tech firms to integrate meal plans with test results. These offerings often combine data insights with ready-to-eat or ready-to-mix products. Personalized meal kits and supplement packs gain traction across urban markets. Trust in science-backed personalization increases willingness to pay. This trend enhances consumer engagement and product differentiation.
Plant-Based and Allergen-Free Product Innovation Is Transforming the Ingredient Landscape
A shift toward plant-derived ingredients is shaping the innovation pipeline for special dietary foods. Vegan, dairy-free, and gluten-free formulations cater to multiple food sensitivities and lifestyle preferences. The Foods For Special Dietary Uses Market is seeing rapid launches of plant-based alternatives. Ingredient suppliers are developing hypoallergenic and clean-label inputs. Soy, pea, rice, and oat proteins are replacing conventional animal-based sources. Free-from labels are now mainstream in product packaging. Product formats include bars, beverages, spreads, and complete meals. This innovation meets rising ethical, health, and sustainability demands.
- For instance, Beyond Meat’s Beyond Steak Seared Tips provide 21 grams of protein and just 1 gram of saturated fat per 88-gram serving, using faba bean protein and wheat gluten as primary sources. In 2024, it became the first plant-based meat to meet the American Diabetes Association’s “Better Choices for Life” criteria and earned the American Heart Association’s Heart-Check certification.
Online Distribution and Direct-to-Consumer Channels Are Accelerating Market Reach
Digital commerce is changing how consumers access specialized dietary products. Direct-to-consumer brands use subscription models and targeted campaigns to build loyalty. The Foods For Special Dietary Uses Market expands through online-only brands and platforms. E-commerce enables broader reach for niche products and small-batch innovation. Social media marketing highlights nutritional claims and user testimonials. AI-based product recommendations enhance cross-selling opportunities. Digital tools reduce reliance on retail shelf space. These shifts create strong market penetration in underserved locations.
- For instance, Huel’s complete nutrition shakes deliver 27 essential vitamins and minerals per 400-calorie serving and support over 400,000 daily users globally through its direct-to-consumer subscription model and automated e-commerce fulfillment.
Globalization of Ethnic and Specialty Diets Is Expanding Flavor Profiles and Regional Variants
Cross-border influence on dietary habits is introducing new ethnic variants in specialty diets. Regional cuisines adapted to dietary needs are gaining attention. The Foods For Special Dietary Uses Market responds by localizing global product lines. Asian gluten-free noodles, Mediterranean diabetic meals, and Latin low-GI snacks are examples. Multinational brands localize SKUs to fit flavor and texture preferences. This cultural adaptation improves product relevance and trial rates. Diaspora communities also drive demand for familiar health foods. Localization improves adoption without compromising compliance.
Market Challenges Analysis
Stringent Regulatory Frameworks and Product Approval Delays Are Slowing Time-to-Market for New Launches
Global regulatory requirements for special dietary foods vary widely, making product development complex. Labeling laws, ingredient approvals, and health claim validations require time and resources. The Foods For Special Dietary Uses Market faces frequent compliance hurdles across regions. Companies must navigate FDA, EFSA, FSSAI, and other bodies with unique requirements. Approval cycles are often long, especially for novel ingredients. Smaller players struggle with clinical trial costs and dossier submissions. Product recalls due to labeling issues damage brand trust. Regulatory ambiguity slows innovation and deters smaller entrants.
High Product Pricing and Limited Insurance Coverage Restrict Mass-Market Accessibility
Many consumers find these products expensive due to ingredient quality, R&D investment, and supply complexity. Reimbursement frameworks often exclude over-the-counter or preventive dietary foods. The Foods For Special Dietary Uses Market thus remains skewed toward premium segments. Low- and middle-income consumers hesitate to adopt these products consistently. Hospitals face budget constraints in offering medical nutrition across patient classes. Market penetration remains urban-centric, limiting rural and semi-urban access. Price sensitivity affects loyalty in emerging markets. Companies must address affordability without reducing product efficacy.
Market Opportunities
Untapped Rural and Middle-Income Segments Offer Room for Affordable Product Extensions
The Foods For Special Dietary Uses Market holds strong growth potential in lower-income and rural areas. Rising health awareness and mobile health platforms open these regions to education and product access. Brands can launch sachets, trial packs, and lower-cost SKUs to drive first-time adoption. Local production and region-specific variants can improve margins. Government nutrition programs could further support institutional distribution.
Expansion into Geriatric Nutrition and Immunity-Focused Products Can Unlock Long-Term Value
Aging populations globally require targeted nutrition to manage bone, brain, and immune health. The Foods For Special Dietary Uses Market can benefit from proactive elderly health management. Immunity-boosting foods with proven bioavailability will attract aging consumers and caretakers. Geriatric formulations with easier digestion and higher nutrient density offer high-volume potential.
Market Segmentation Analysis:
The Foods for Special Dietary Uses Market is categorized by product type, application, and distribution channel, each contributing uniquely to the overall market value.
By product types, infant formula and baby food dominate, driven by demand for safe, high-nutrition products in early childhood. Gluten-free and allergen-free products are expanding rapidly due to rising food sensitivities. Medical and clinical nutrition foods hold firm demand in hospital and outpatient settings. Organic and natural special dietary foods are gaining traction, especially in developed markets. Functional foods and nutraceuticals appeal to fitness and preventive health consumers.
- For instance, a study-tested infant formula from Nestlé includes 1.0 g/L of 2'-FL and 0.5 g/L of LNnT, replicating key human milk oligosaccharides to support infant gut health and immunity.
By application, pediatric nutrition leads due to strong consumption in early development phases. Adult nutrition products serve active individuals with dietary goals or restrictions. Elderly nutrition continues to grow, supported by aging populations and care facilities. Clinical and hospital nutrition remains vital for recovery and therapeutic uses, with institutional demand.
By distribution, supermarkets and hypermarkets provide broad access and visibility. Online retail is gaining share due to convenience and subscription-based wellness programs. Pharmacies and health stores remain trusted points of sale for medically positioned dietary products. This multichannel ecosystem enhances product reach and consumer engagement.
- For instance, Nestlé’s Gerber Good Start formulas, including SoothePro and Gentle Pro, faced notable supply chain disruptions through 2024 and 2025, with several product variants reported as out of stock across major retailers despite ongoing supply chain optimization efforts.
Segmentation:
By Product Type
- Infant Formula & Baby Food
- Gluten-Free & Allergen-Free Products
- Medical & Clinical Nutrition Foods
- Organic & Natural Special Dietary Foods
- Functional Foods & Nutraceuticals
By Application
- Pediatric Nutrition
- Adult Nutrition
- Elderly Nutrition
- Clinical & Hospital Nutrition
By Distribution Channel
- Supermarkets & Hypermarkets
- Online Retail
- Pharmacies & Health Stores
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Foods For Special Dietary Uses Market size was valued at USD 13,969.74 million in 2018 to USD 16,785.32 million in 2024 and is anticipated to reach USD 27,347.32 million by 2032, at a CAGR of 6.4% during the forecast period. North America holds the largest market share of approximately 36.1% in 2024. High consumer awareness, strong healthcare systems, and insurance-supported clinical nutrition drive market strength. The U.S. dominates due to advanced product innovation, well-established brands, and a growing aging population. Infant nutrition and functional supplements show strong retail traction. Rising prevalence of lifestyle diseases boosts gluten-free and medical dietary food consumption. Hospital-based nutritional therapies also contribute to volume. E-commerce and specialized health stores expand consumer access. Regulatory clarity further supports rapid commercialization and product safety.
Europe
The Europe Foods For Special Dietary Uses Market size was valued at USD 8,308.50 million in 2018 to USD 9,629.66 million in 2024 and is anticipated to reach USD 14,647.77 million by 2032, at a CAGR of 5.5% during the forecast period. Europe accounts for 20.7% of the global market in 2024. High demand for allergen-free and organic dietary foods supports regional growth. Germany, France, and the UK are key markets with strong consumer health awareness. The region has strict food safety regulations that support premium product positioning. Government-backed nutrition programs increase clinical nutrition uptake. Sustainable sourcing and plant-based dietary trends shape product development. Pharmacies play a major role in adult and elderly nutrition sales. Health-conscious lifestyle choices push demand across all age groups. Local players actively cater to specialized needs with certified formulations.
Asia Pacific
The Asia Pacific Foods For Special Dietary Uses Market size was valued at USD 11,383.60 million in 2018 to USD 14,348.64 million in 2024 and is anticipated to reach USD 25,414.44 million by 2032, at a CAGR of 7.5% during the forecast period. Asia Pacific holds a market share of 30.9% in 2024, making it the second-largest region. China, Japan, and India lead in volume consumption due to rising urbanization and health awareness. Growing middle-class income and retail modernization support dietary product uptake. Infant nutrition is particularly strong, followed by functional foods for adults. Online channels fuel growth among tech-savvy consumers. Traditional health beliefs merge with modern dietary needs. Domestic brands localize products to suit regional tastes and dietary restrictions. Government efforts to reduce malnutrition add to institutional demand.
Latin America
The Latin America Foods For Special Dietary Uses Market size was valued at USD 2,483.00 million in 2018 to USD 2,991.49 million in 2024 and is anticipated to reach USD 4,537.90 million by 2032, at a CAGR of 5.4% during the forecast period. The region contributes 6.4% to the global market share in 2024. Brazil and Mexico dominate consumption due to growing urban health trends and awareness campaigns. Pediatric and maternal nutrition products are widely adopted. Functional beverages and snacks are gaining popularity among younger demographics. Supermarkets remain the main retail channel, but online sales are rising. Local production capabilities are improving, lowering dependency on imports. Regulatory updates are aligning with global food safety standards. Economic recovery supports greater household spending on health-related food categories.
Middle East
The Middle East Foods For Special Dietary Uses Market size was valued at USD 1,222.40 million in 2018 to USD 1,374.88 million in 2024 and is anticipated to reach USD 1,978.69 million by 2032, at a CAGR of 4.7% during the forecast period. The region holds about 3.0% of the global share in 2024. Demand is driven by chronic disease prevalence, especially diabetes and cardiovascular conditions. Countries like the UAE and Saudi Arabia lead in adopting clinical and functional nutrition products. The region imports a significant portion of specialty dietary foods. Health and fitness culture is growing, influencing product preferences. Pharmacies and private hospitals play a key role in clinical nutrition delivery. Regulatory frameworks are evolving to support product approvals. Local partnerships and halal-certified formulations help address cultural dietary needs.
Africa
The Africa Foods For Special Dietary Uses Market size was valued at USD 832.76 million in 2018 to USD 1,328.91 million in 2024 and is anticipated to reach USD 1,869.83 million by 2032, at a CAGR of 4.0% during the forecast period. Africa holds 2.9% of the global market share in 2024. Growth is led by nutrition improvement initiatives in healthcare and public programs. South Africa and Egypt show early signs of demand for infant and elderly nutrition products. International aid programs and non-profits introduce fortified foods in underserved regions. Urban centers see rising demand for organic and allergen-free offerings. Product affordability remains a key challenge. Domestic manufacturing is limited, increasing reliance on imports. Awareness and accessibility continue to grow with education and retail expansion. Government focus on reducing malnutrition supports clinical food distribution.
Key Player Analysis:
- Nestlé S.A.
- Abbott Laboratories
- Danone S.A.
- Mead Johnson Nutrition Company
- The Kraft Heinz Company
- General Mills, Inc.
- Kellogg Company
- GlaxoSmithKline plc
- Pfizer Inc.
- Bayer AG
- DSM Nutritional Products
- Reckitt Benckiser Group plc
- Hain Celestial Group, Inc.
- Amway Corporation
- Herbalife Nutrition Ltd.
- Nature's Bounty Co.
- Glanbia plc
- Arla Foods amba
- PepsiCo, Inc.
Competitive Analysis:
The Foods for Special Dietary Uses Market shows strong competition among global food, nutrition, and healthcare companies. Large multinational players lead through broad product portfolios, strong clinical credibility, and global distribution reach. These firms focus on infant nutrition, medical foods, and functional products to secure stable demand. Product quality, safety compliance, and brand trust remain core competitive factors. Companies invest in research to improve formulation accuracy and nutritional outcomes. Strategic acquisitions help expand geographic presence and strengthen specialty segments. Partnerships with hospitals and healthcare providers improve institutional sales. Private-label brands compete on pricing within retail channels. Regional players gain traction by tailoring products to local dietary needs. Competition continues to intensify as consumer awareness and regulatory standards rise.
Recent Developments:
- In November 2025, Nestlé Health Science announced a multi-year $2 million partnership with Special Olympics, focusing on the Motor Activity Training Program and Healthy Athletes screening to support nutrition for athletes with intellectual disabilities.
- In November 2025, Abbott Laboratories launched an upgraded Ensure Diabetes Care formula featuring a triple care system with myo-inositol, low-glycemic carbohydrates, high protein, and fiber to aid blood sugar control, metabolic health, and weight management for diabetes patients.
- In May 2025, Danone S.A. agreed to acquire a majority stake in Kate Farms, a U.S. producer of plant-based organic nutrition formulas and shakes for medical and everyday needs, expanding its specialized nutrition offerings.
Report Coverage:
The research report offers an in-depth analysis based on product type, application, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing consumer awareness of preventive health will sustain long-term demand for dietary-specific foods.
- The rise in chronic lifestyle diseases will continue to drive adoption of medical and clinical nutrition.
- Urbanization and income growth across Asia Pacific will accelerate regional market expansion.
- Online retail and subscription models will reshape how consumers access and repurchase dietary products.
- Product innovation in allergen-free, plant-based, and fortified foods will diversify market offerings.
- Elderly nutrition will gain focus as aging populations demand high-nutrition, easy-to-digest formats.
- Hospitals and clinics will integrate more specialized dietary solutions into routine care protocols.
- Regulatory harmonization across regions will improve global product availability and cross-border trade.
- Smaller brands will enter through e-commerce and localized offerings, increasing market fragmentation.
- Multinational companies will focus on regional manufacturing and culturally adapted dietary variants.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Prevalence of Chronic Diseases
The increasing incidence of diabetes, cardiovascular diseases, and metabolic disorders is prompting consumers to seek condition-specific dietary products, driving sustained demand for foods tailored to medical and preventive needs.
Health-Conscious Population Across Age Groups
Growing awareness of nutrition's role in lifelong health is fueling demand for specialized products such as infant formula, geriatric nutrition, and maternal supplements, expanding the market across all age brackets.
Fitness-Oriented and Active Lifestyles
Urbanization and the adoption of fitness regimens are boosting consumption of protein-rich, functional, and performance-oriented foods, as consumers seek products that support muscle recovery, energy, and overall wellness.
Medical Nutrition Therapy in Healthcare Settings
Hospitals and clinics are increasingly integrating special dietary foods into treatment protocols for recovery and chronic disease management, reinforcing clinical demand and institutional adoption.
Innovation in Plant-Based and Allergen-Free Products
The shift toward plant-based, vegan, and allergen-free formulations is expanding the market by catering to food sensitivities, ethical preferences, and sustainability concerns, attracting new consumer segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Foods For Special Dietary Uses Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Foods For Special Dietary Uses Market projected to grow between 2024 and 2032?
Which Foods For Special Dietary Uses Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Foods For Special Dietary Uses Market?
Who are the leading companies in the Foods For Special Dietary Uses Market?
Which region commanded the largest share of the Foods For Special Dietary Uses Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Pediatric Nutrition
- 1.2.2 Adult Nutrition
- 1.2.3 Elderly Nutrition
- 1.2.4 Clinical & Hospital Nutrition
- 1.3 By Product Type
- 1.3.1 Infant Formula & Baby Food
- 1.3.2 Gluten-Free & Allergen-Free Products
- 1.3.3 Medical & Clinical Nutrition Foods
- 1.3.4 Organic & Natural Special Dietary Foods
- 1.3.5 Functional Foods & Nutraceuticals
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 46,458.90 million → 2032: USD 75,795.95 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Foods For Special Dietary Uses Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Foods For Special Dietary Uses Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Foods For Special Dietary Uses Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Foods For Special Dietary Uses Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Foods For Special Dietary Uses Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Foods For Special Dietary Uses Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Foods For Special Dietary Uses Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Foods For Special Dietary Uses Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 46,458.90 million → 2032: USD 75,795.95 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Foods For Special Dietary Uses Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pediatric Nutrition
- 12.3.7.2 Adult Nutrition
- 12.3.7.3 Elderly Nutrition
- 12.3.7.4 Clinical & Hospital Nutrition
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Infant Formula & Baby Food
- 12.4.7.2 Gluten-Free & Allergen-Free Products
- 12.4.7.3 Medical & Clinical Nutrition Foods
- 12.4.7.4 Organic & Natural Special Dietary Foods
- 12.4.7.5 Functional Foods & Nutraceuticals
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Foods For Special Dietary Uses End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Foods For Special Dietary Uses Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Foods For Special Dietary Uses Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Foods For Special Dietary Uses Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nestlé S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Abbott Laboratories
- 18.4 Danone S.A.
- 18.5 Mead Johnson Nutrition Company
- 18.6 The Kraft Heinz Company
- 18.7 General Mills, Inc.
- 18.8 Kellogg Company
- 18.9 GlaxoSmithKline plc
- 18.10 Bayer AG
- 18.11 DSM Nutritional Products
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

