
Market Overview
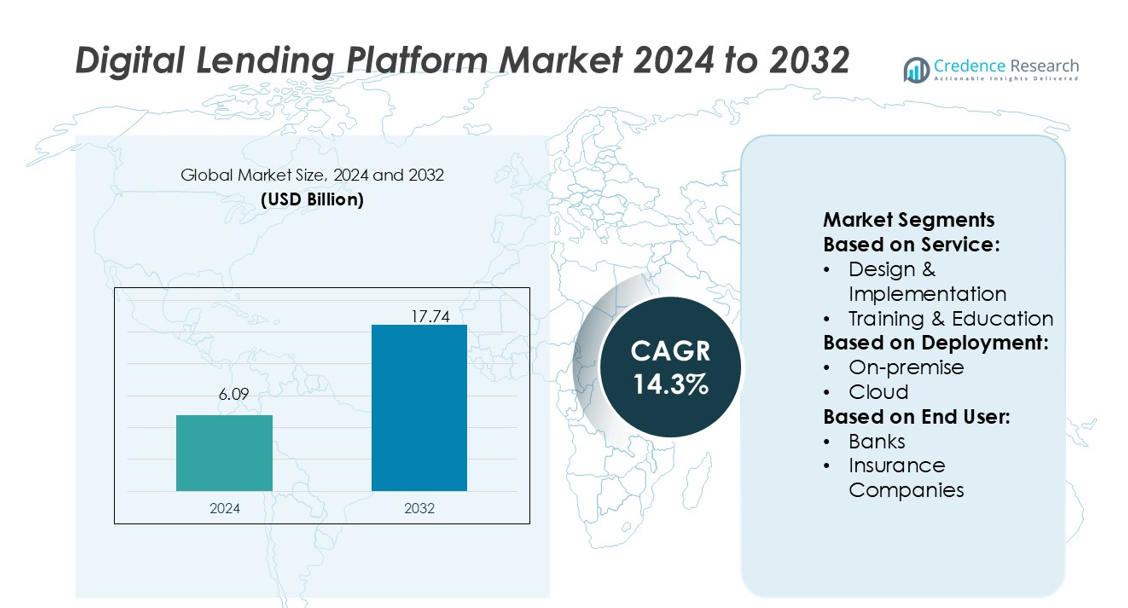
Digital Lending Platform Market size was valued USD 6.09 billion in 2024 and is anticipated to reach USD 17.74 billion by 2032, at a CAGR of 14.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Digital Lending Platform Market Size 2024 | USD 6.09 billion |
| Digital Lending Platform Market, CAGR | 14.3% |
| Digital Lending Platform Market Size 2032 | USD 17.74 billion |
The digital lending platform market features strong competition among leading players such as FIS, Fiserv, Inc., Tavant, Pegasystems Inc., Nucleus Software, Ellie Mae, Inc., Newgen Software, Roostify, Sigma Infosolutions, and Wizni, Inc. These companies focus on enhancing automation, cloud integration, and AI-driven analytics to improve lending efficiency and risk assessment. North America leads the global market with a 37% share, supported by advanced fintech infrastructure, strong regulatory frameworks, and high adoption of digital banking solutions. The region’s dominance is reinforced by significant investments in data-driven lending systems and growing collaborations between financial institutions and technology providers.
Market Insights
- The Digital Lending Platform Market was valued at USD 6.09 billion in 2024 and is projected to reach USD 17.74 billion by 2032, growing at a CAGR of 14.3% during the forecast period.
- Market growth is driven by increasing demand for automated loan processing, AI-powered analytics, and seamless digital onboarding across financial institutions.
- Cloud-based deployment holds a dominant segment share of over 60%, offering scalability, cost efficiency, and real-time processing advantages to banks and fintech firms.
- The competitive landscape features key players such as FIS, Fiserv, Tavant, Pegasystems Inc., and Nucleus Software, focusing on AI-driven risk assessment and automation.
- North America leads with a 37% regional share due to advanced fintech infrastructure and strong regulatory frameworks, while Asia-Pacific emerges as the fastest-growing region supported by digital inclusion initiatives and mobile-first lending adoption.
Market Segmentation Analysis:
By Service
Design & Implementation dominates the digital lending platform market, holding nearly 35% share. This dominance stems from high demand for end-to-end integration of loan origination, underwriting, and disbursement modules. Financial institutions prefer tailored platform setups that align with regulatory and security frameworks. The rise in digital transformation initiatives among banks and fintechs drives the need for seamless design services. Continuous deployment of scalable, API-based architectures enhances efficiency and customer experience, reinforcing the leadership of this segment.
- For instance, FIS’ Code Connect API marketplace hosts over 700 open APIs that support modular lending functions, including credit decisioning, collateral management, and repayment scheduling.
By Deployment
Cloud-based deployment leads the segment with more than 60% market share. Its dominance is driven by scalability, faster implementation, and lower upfront costs compared to on-premise solutions. Financial institutions increasingly adopt cloud-based lending systems to support remote access, real-time analytics, and integration with AI-driven credit scoring tools. Cloud models also improve regulatory compliance and cybersecurity through continuous updates. Providers like Fiserv and Temenos expand their SaaS lending platforms to meet the growing demand from mid-tier banks and credit unions.
- For instance, Roostify has processed over 10 million documents via its cloud platform, using Google Cloud’s Lending DocAI for document extraction and classification.Roostify Beyond service embeds document validation and classification at the point-of-sale, enabling real-time error detection instead of manual review.
By End-user
Banks account for the largest market share, exceeding 45% in the digital lending platform market. Their dominance results from large-scale adoption of automation in loan origination and portfolio management. Banks leverage digital lending solutions to enhance risk assessment, reduce processing time, and improve customer retention. Integration with advanced analytics enables faster credit decisions and personalized lending offers. Rising competition from fintech firms further accelerates digital adoption among banks, making them the primary end-user driving market growth.
Key Growth Drivers
Rising Demand for Automated Loan Processing
Financial institutions are increasingly adopting digital lending platforms to reduce loan approval times and operational costs. Automation in credit scoring, document verification, and underwriting enables faster decision-making and improves customer experience. For instance, banks using AI-driven systems can process applications up to 70% faster than traditional methods. This growing emphasis on workflow automation and efficiency is propelling widespread adoption across retail, SME, and corporate lending segments.
- For instance, Pega has pushed forward its agentic AI and workflow automation fabric capabilities. Its newly launched Agentic Process Fabric™ orchestrates over 150 registered AI agents across systems and datasets.
Expanding Fintech Ecosystem and Strategic Partnerships
The surge in fintech startups and collaborations with traditional banks is a major growth catalyst. These partnerships enhance accessibility to credit through digital channels and mobile-first platforms. For example, fintech APIs enable seamless integration with core banking systems for real-time loan approvals. The growing number of digital-first consumers and financial inclusion initiatives in emerging markets further accelerates this ecosystem expansion, boosting overall market penetration.
- For instance, BRAC Bank in Bangladesh, Nucleus deployed its FinnAxia® solution with an extensive API stack in under 90 days, facilitating real-time credit checks and supply chain finance module integration.
Increasing Adoption of AI and Data Analytics
AI and predictive analytics are transforming the digital lending landscape by improving risk assessment accuracy and customer targeting. Platforms equipped with machine learning models evaluate alternative data sources, such as payment history and digital behavior, to assess creditworthiness. Companies integrating AI-driven analytics report up to 30% lower default rates. The rising focus on personalized loan offerings and fraud detection continues to fuel AI adoption in lending operations.
Key Trends & Opportunities
Growth of Cloud-Based Lending Platforms
Cloud deployment is becoming the preferred model due to scalability, flexibility, and cost efficiency. Institutions using cloud-based platforms benefit from faster deployment cycles and real-time updates. Vendors are introducing SaaS lending platforms with integrated compliance and data security features, reducing maintenance burdens for financial institutions. The ongoing migration to cloud environments presents opportunities for vendors to offer modular and API-driven digital lending ecosystems.
- For instance, Fiserv’s Banking Hub now gives instant, self-service access to over 500 developers integrating with core banking APIs via a unified workspace.
Expansion into SME and Microfinance Segments
Digital lending platforms are gaining traction among SMEs and microfinance institutions seeking quick and transparent funding. Automated credit evaluation using alternative data allows lenders to reach underserved sectors efficiently. This trend supports economic development and financial inclusion goals in developing countries. Vendors offering tailored solutions for small enterprises are expected to capture substantial growth opportunities over the forecast period.
- For instance, Ellie Mae’s Encompass platform connects approximately 186,500 mortgage professionals across lending and service-provider ecosystems via the Ellie Mae Network, enabling electronic ordering of credit, title, fraud, compliance, and more.
Integration of Blockchain for Secure Transactions
Blockchain technology is emerging as a key innovation in ensuring transparency and traceability in digital lending. Distributed ledgers facilitate tamper-proof loan records and smart contract automation, reducing fraud risk. Several fintech companies are piloting blockchain-enabled lending platforms to enhance trust and data integrity. The technology’s ability to improve security and streamline loan settlement processes presents a significant growth avenue.
Key Challenges
Data Privacy and Cybersecurity Concerns
Rising data breaches and security threats pose a serious challenge to digital lending platforms. Financial institutions handle sensitive borrower information, making them prime targets for cyberattacks. Ensuring compliance with data protection regulations such as GDPR and CCPA adds to operational complexity. Vendors must invest in encryption, multi-factor authentication, and secure APIs to maintain user trust and safeguard digital transactions.
Regulatory Compliance and Integration Complexity
Varying regulatory frameworks across regions create hurdles for global platform adoption. Compliance with KYC, AML, and local lending norms requires continuous updates and customization. Integrating digital lending platforms with legacy systems of banks and credit unions further adds complexity and cost. These challenges often delay deployment timelines and increase the total cost of ownership, limiting adoption among smaller institutions.
Regional Analysis
North America
North America dominates the digital lending platform market with a 37% share in 2024. The region’s leadership stems from strong fintech adoption, high internet penetration, and advanced banking infrastructure. U.S. banks and credit unions invest heavily in AI-powered lending systems for faster credit evaluation and fraud prevention. Companies like Fiserv, FIS, and Temenos continue expanding cloud-based solutions that comply with strict regulatory frameworks. The growing collaboration between fintech firms and traditional lenders, combined with digital-first customer preferences, reinforces North America’s position as the largest and most mature market globally.
Europe
Europe accounts for nearly 28% of the global market, driven by open banking regulations and digital transformation initiatives. The U.K., Germany, and France lead adoption through PSD2 compliance and fintech integration. European banks prioritize automation, data analytics, and cloud-based lending to improve efficiency and meet regulatory demands. Companies such as Finastra and Sopra Banking Software are enhancing modular platforms to serve retail and SME lenders. The region’s focus on sustainable finance, coupled with expanding peer-to-peer lending ecosystems, strengthens Europe’s position as a major hub for digital lending innovation.
Asia-Pacific
Asia-Pacific holds a 24% market share and represents the fastest-growing regional segment. Rapid digitalization, mobile banking expansion, and government-backed fintech programs drive market growth in China, India, and Southeast Asia. Banks and non-banking financial institutions adopt digital platforms to serve unbanked and underbanked populations. Leading players like TCS, Infosys Finacle, and OneConnect offer scalable cloud-based platforms tailored for high-volume lending. The region’s strong smartphone adoption and favorable regulations supporting financial inclusion continue to accelerate digital lending adoption across both developed and emerging economies.
Latin America
Latin America captures nearly 7% of the global market share, supported by expanding fintech ecosystems in Brazil, Mexico, and Colombia. The demand for faster credit access and lower borrowing costs drives digital lending platform adoption among banks and microfinance institutions. Fintech startups such as Nubank and Creditas lead innovation through AI-driven loan processing and cloud-native platforms. Governments in the region are implementing open finance initiatives to promote competition and inclusion. Despite challenges related to regulation and cybersecurity, the region’s growing digital literacy supports steady market expansion.
Middle East & Africa
The Middle East & Africa region holds a 4% market share, with growth fueled by increasing investments in financial digitization. The UAE, Saudi Arabia, and South Africa lead adoption due to strong fintech infrastructure and supportive government initiatives. Banks and fintech firms implement digital lending platforms to enhance SME financing and consumer credit services. Regional players like eFinance and Network International are advancing cloud-based systems for faster deployment. While low financial inclusion and connectivity challenges persist, rising smartphone usage and regulatory modernization are driving future growth prospects in the region.
Market Segmentations:
By Service:
- Design & Implementation
- Training & Education
By Deployment:
- On-premise
- Cloud
By End User:
- Banks
- Insurance Companies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The digital lending platform market is highly competitive, with key players including Sigma Infosolutions, FIS, Roostify, Wizni, Inc., Pegasystems Inc., Nucleus Software, Tavant, Fiserv, Inc., Ellie Mae, Inc., and Newgen Software. The digital lending platform market is characterized by intense competition driven by rapid technological innovation and rising demand for automation in financial services. Companies are prioritizing cloud-based deployment, AI-powered analytics, and API-driven integration to deliver faster, more secure, and customer-centric lending solutions. Vendors focus on improving platform scalability, compliance, and interoperability with core banking systems to attract financial institutions and fintechs. Strategic partnerships, mergers, and product enhancements are common strategies to expand market reach. The increasing emphasis on personalized lending, real-time risk assessment, and digital onboarding continues to shape the competitive dynamics of this evolving market.
Key Player Analysis
- Sigma Infosolutions
- FIS
- Roostify
- Wizni, Inc.
- Pegasystems Inc.
- Nucleus Software
- Tavant
- Fiserv, Inc.
- Ellie Mae, Inc.
- Newgen Software
Recent Developments
- In April 2025, Fiserv, Inc. announced that it had entered into a definitive agreement to acquire Brazilian fintech company Money Money Serviços Financeiros S.A. This strategic acquisition aims to enhance Fiserv's services in Brazil, enabling small and medium-sized businesses (SMBs) to access capital for growth and development.
- In October 2024, the new JioFinance app, developed by Jio Financial Services (JFSL), was launched, offering a comprehensive range of digital financial services. The app offers an aggregated view of users' bank and mutual fund holdings, improving financial management.
- In September 2024, Akme Fintrade (India) Limited, one of the leading technology-driven lending platforms, entered into a strategic co-lending partnership with MAS Financial Services Limited to provide loans to small business owners.
- In February 2024, Dvara Money, a leading fintech company, announced a strategic partnership with Jana Small Finance Bank Limited (Jana SFB). This collaboration aims to harness the technological capabilities of Jana SFB and the innovative Spark Money platform by Dvara Money to set new standards in digital banking services
Report Coverage
The research report offers an in-depth analysis based on Service, Deployment, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth as banks accelerate digital transformation initiatives.
- AI and machine learning will play a central role in credit scoring and risk management.
- Cloud-based platforms will dominate due to scalability, cost-efficiency, and faster deployment.
- Fintech collaborations with traditional lenders will expand to enhance customer reach.
- Mobile-first lending solutions will rise, targeting underserved and unbanked populations.
- Blockchain adoption will increase to improve transaction transparency and data security.
- Regulatory frameworks will evolve to support open banking and digital compliance.
- Predictive analytics will enhance loan personalization and borrower experience.
- Integration of APIs will streamline workflows across multiple financial services.
- Sustainable and inclusive lending models will gain momentum in emerging economies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Automation of Loan Processing
Financial institutions are rapidly adopting digital lending platforms to automate credit scoring, document verification, and underwriting, significantly reducing loan approval times and operational costs. This automation enables faster, more efficient lending processes and enhances customer satisfaction.
Cloud-Based Deployment and Scalability
The shift toward cloud-based digital lending platforms offers banks and fintechs scalability, cost efficiency, and real-time processing capabilities. Cloud deployment supports remote access, seamless integration with AI tools, and continuous regulatory compliance, driving widespread adoption.
AI and Predictive Analytics Integration
AI-powered analytics and machine learning models are transforming risk assessment and credit decisioning by leveraging alternative data sources. This leads to more accurate credit evaluations, lower default rates, and personalized lending offers, fueling market growth.
Expansion of Fintech Ecosystem and Partnerships
The proliferation of fintech startups and their collaborations with traditional banks are expanding access to digital lending solutions. These partnerships enable real-time loan approvals and broaden the reach to underserved and unbanked populations, accelerating market penetration.
Regulatory Support and Digital Inclusion Initiatives
Supportive regulatory frameworks and government-backed digital inclusion programs, especially in emerging markets, are encouraging the adoption of digital lending platforms. These initiatives promote financial inclusion and drive the growth of digital lending across diverse customer segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Digital Lending Platforms Market?
At what Compound Annual Growth Rate is the Digital Lending Platform Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Digital Lending Platforms Market?
What are the key segments within the Digital Lending Platforms Market?
Who are the major players in the Digital Lending Platforms Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service
- 1.2.1 Design & Implementation
- 1.2.2 Training & Education
- 1.3 By End User
- 1.3.1 Banks
- 1.3.2 Insurance Companies
- 1.3.3 Credit Unions
- 1.3.4 Fintech Firms
- 1.4 By Deployment
- 1.4.1 On-premise
- 1.4.2 Cloud
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6.09 billion → 2032: USD 17.74 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Digital Lending Platforms Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Digital Lending Platforms Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Digital Lending Platforms Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Digital Lending Platforms Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Digital Lending Platforms Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Digital Lending Platforms Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Digital Lending Platforms Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Digital Lending Platforms Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6.09 billion → 2032: USD 17.74 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Digital Lending Platforms Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Design & Implementation
- 12.3.7.2 Training & Education
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Banks
- 12.4.7.2 Insurance Companies
- 12.4.7.3 Credit Unions
- 12.4.7.4 Fintech Firms
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-premise
- 12.5.7.2 Cloud
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Digital Lending Platforms End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Digital Lending Platforms Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Digital Lending Platforms Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Digital Lending Platforms Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 FIS
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Fiserv, Inc.
- 18.4 Tavant
- 18.5 Pegasystems Inc.
- 18.6 Nucleus Software
- 18.7 Ellie Mae, Inc.
- 18.8 Newgen Software
- 18.9 Roostify
- 18.10 Sigma Infosolutions
- 18.11 Wizni, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

