
Market Overview
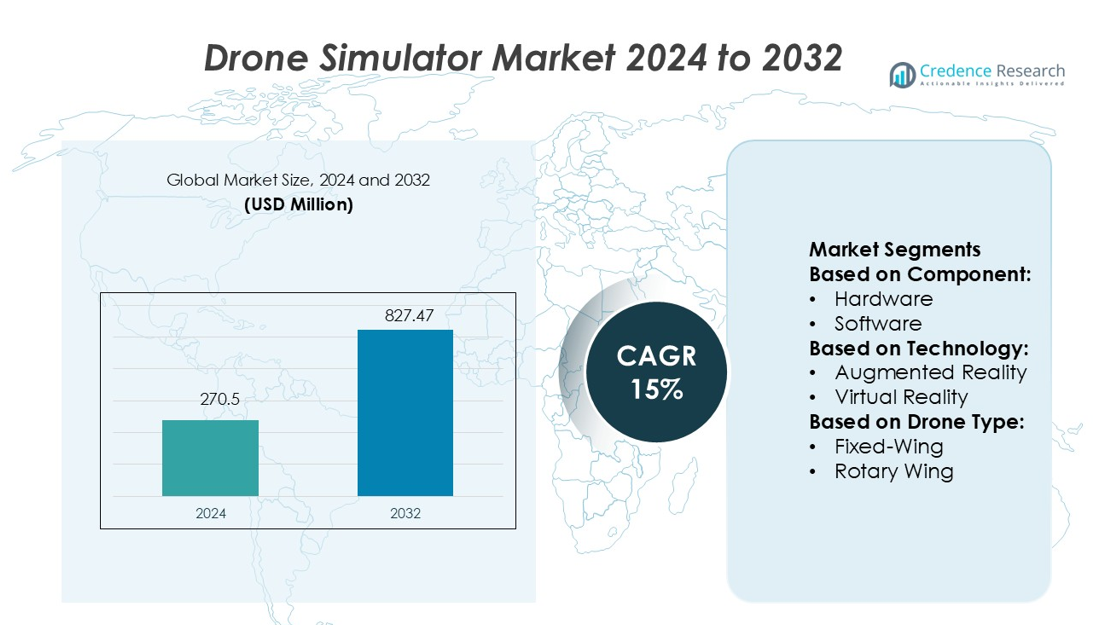
Drone Simulator Market size was valued USD 270.5 million in 2024 and is anticipated to reach USD 827.47 million by 2032, at a CAGR of 15% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Drone Simulator Market Size 2024 | USD 270.5 million |
| Drone Simulator Market, CAGR | 15% |
| Drone Simulator Market Size 2032 | USD 827.47 million |
The Drone Simulator Market is shaped by strong competition from leading players such as Skydio, Autel Robotics, SZ DJI Technology, Inc., 3DR, Inc., Pix4D, Parrot Drone SAS, RedBird, AgEagle Aerial Systems Inc, Airware Limited, and Mapbox. These companies focus on enhancing simulation accuracy, integrating AI-driven features, and expanding VR and AR capabilities to strengthen their market positions. Strategic partnerships with defense agencies and commercial operators support product innovation and global reach. North America leads the Drone Simulator Market with a 36% share, supported by advanced aviation infrastructure, significant defense investments, and strong regulatory frameworks driving widespread simulator adoption.
Market Insights
- The Drone Simulator Market size was valued at USD 270.5 million in 2024 and is anticipated to reach USD 827.47 million by 2032, at a CAGR of 15% during the forecast period.
- Rising demand for AI-powered simulators and immersive VR/AR training solutions is driving rapid technology adoption across defense and commercial sectors.
- Strong competition among major companies is accelerating product innovation, platform integration, and strategic partnerships with operators and training institutions.
- High initial investment costs and limited standardization remain key restraints, particularly in emerging markets with slower regulatory alignment.
- North America leads the market with a 36% share, followed by Europe with 27% and Asia Pacific with 24%; hardware dominates the component segment with 62% market share.
Market Segmentation Analysis:
By Component
Hardware dominates the Drone Simulator Market with a 62% share. The strong growth of this sub-segment is driven by the rising demand for advanced control systems, flight control hardware, and high-performance computing platforms. High-fidelity simulators are increasingly used for pilot training, mission planning, and defense applications. Hardware-based simulators offer realistic flight conditions, improving training quality and reducing operational risks. The growing investment in military drone programs and commercial drone operations supports hardware adoption, making it the leading component in the market.
- For instance, Skydio, Inc. developed its X10 drone, which deploys in under 40 seconds as a backpack-ready unit and includes modular camera payloads. One configuration, the VT300-Z, features a 48 MP telephoto zoom and a 64 MP narrow-angle camera, while another, the VT300-L, offers a 50 MP wide-angle and 64 MP narrow-angle camera.
By Technology
Virtual Reality (VR) holds the largest market share of 68% in the technology segment. Its dominance is supported by its ability to deliver immersive flight experiences and enhance real-time decision-making. VR technology allows pilots to practice complex missions in controlled environments without physical risks. The demand is rising across defense, agriculture, and logistics sectors for training and operational readiness. VR simulators are cost-effective compared to live flight training, accelerating adoption among commercial and government agencies worldwide.
- For instance, Autel reports its industrial drone model Autel Alpha supports video transmission up to 20 kilometres via its SkyLink 3.0 system.
By Drone Type
Fixed-wing drones lead the market with a 54% share in the drone type segment. Their popularity stems from longer flight endurance, higher payload capacity, and superior performance for surveillance and mapping missions. Fixed-wing simulators support realistic mission training, making them essential for military and industrial use. The increasing use of fixed-wing drones in defense, environmental monitoring, and border security drives the need for accurate simulation tools. This dominance highlights the growing focus on strategic and operational training for long-range drone missions.
Key Growth Drivers
Rising Adoption of Drones for Defense and Commercial Applications
The increasing use of drones in defense, logistics, agriculture, and surveillance drives simulator demand. Military agencies rely on simulators for pilot training, mission planning, and risk reduction. Commercial operators use them to train staff without incurring high operational costs. This adoption enables safer, faster, and more efficient mission execution. Advanced simulation platforms replicate real-time flight conditions, improving operational accuracy. Growing defense budgets and commercial drone deliveries are strengthening the market, making simulators a critical training and operational tool.
- For instance, DJI’s Mavic 3 Enterprise series features a maximum flight time of 45 minutes and a maximum horizontal distance of 32 km under ideal conditions.
Technological Advancements in Simulation Systems
Continuous innovation in simulation hardware and software enhances the accuracy and immersion of training programs. Integrating virtual reality, haptic feedback, and AI improves pilot response and mission adaptability. These systems allow trainees to practice real-world scenarios, including emergency situations, without operational risks. Upgraded visualization and sensor integration increase demand from both defense and commercial users. As simulation platforms become more affordable and scalable, more organizations are investing in modernized drone training environments.
- For instance, Pix4D's viDoc RTK Rover, when used with the PIX4Dcatch app, delivers centimeter-level absolute accuracy. In 2022, Bureau Veritas certified the device to be accurate to within 5 cm for trench measurements, demonstrating its capability for professional-grade terrestrial scanning.
Cost Efficiency and Operational Safety Benefits
Drone simulators reduce costs linked to maintenance, fuel, and operational risks during live flight training. Organizations prefer simulators for skill development and compliance training because they provide repeatable, safe environments. Simulations also minimize drone damage, lowering overall training expenses. High-fidelity platforms offer realistic mission planning and execution, ensuring precision in actual flights. These cost and safety advantages make simulation an attractive alternative to conventional flight training programs across industries.
Key Trends & Opportunities
Growing Integration of VR and AR Technologies
The use of virtual and augmented reality technologies is transforming drone training methods. These immersive tools provide lifelike flight environments, enhancing pilot performance and mission planning accuracy. VR and AR simulators help users gain real-time feedback and hands-on experience without physical risk. This integration creates opportunities for developers to offer more adaptive and cost-effective solutions. Industries like defense, logistics, and emergency response are expected to benefit the most from this trend.
- For instance, ANAFI USA platform supports full AES-XTS 512-bit encrypted SD cards and live feed streams in 720p via Skycontroller, enabling safe simulation of complex operational scenarios without physical risk.
Expansion of Commercial Drone Training Programs
The rising adoption of drones in logistics, agriculture, and surveillance is increasing the need for certified pilots. Training centers and companies are investing in simulation platforms to build skilled operator bases. Regulatory support for commercial drone operations is further driving demand. This trend is creating opportunities for simulator providers to develop scalable solutions tailored to enterprise training needs. Market players are focusing on portable and cloud-based simulators to meet growing global demand.
- For instance, Redbird reports over 2,000 training devices in service worldwide across its BATD and AATD platforms. Training centres and companies are investing in simulation platforms to build skilled operator bases.
Increasing Use of AI-Powered Simulation Tools
AI integration is enhancing simulation accuracy, predictive capabilities, and adaptability. These intelligent systems analyze trainee performance and adjust scenarios dynamically. Real-time feedback improves learning efficiency and operational preparedness. AI-based tools are becoming essential in high-risk missions such as defense surveillance and disaster management. This trend opens opportunities for companies offering intelligent, automated training solutions with strong analytical capabilities.
Key Challenges
High Initial Cost of Advanced Simulation Systems
Advanced drone simulators require significant investment in hardware, software, and integration. High acquisition and maintenance costs limit adoption among small training centers and commercial operators. This cost barrier restricts market penetration in price-sensitive regions. Although long-term savings are possible, upfront costs remain a key concern. Many organizations prefer cost-effective alternatives, slowing widespread adoption of high-end training platforms.
Limited Standardization and Regulatory Complexity
The lack of uniform global regulations for drone operations and training complicates simulator deployment. Different countries have varying certification and compliance standards. This inconsistency hinders cross-border training programs and simulator sales. Manufacturers must adapt products to meet multiple standards, raising development costs. The regulatory complexity delays market growth, especially for commercial drone applications in emerging economies.
Regional Analysis
North America
North America leads the Drone Simulator Market with a 36% share. Strong defense investments, advanced aviation infrastructure, and the presence of major simulator providers support this leadership. The U.S. Department of Defense and commercial drone operators are increasingly adopting simulators for pilot training and mission planning. Expanding drone use in logistics, agriculture, and surveillance drives demand. Technology adoption is high, with VR and AI integration enhancing simulation quality. Strategic partnerships between defense agencies and technology firms further strengthen regional dominance, ensuring sustained growth and innovation in training solutions.
Europe
Europe holds a 27% share of the Drone Simulator Market, driven by strong regulatory support and defense modernization programs. Countries like Germany, the U.K., and France invest in simulation systems for advanced pilot training and operational planning. The European Union’s drone integration framework also supports commercial training expansion. Growing demand in security, infrastructure inspection, and logistics enhances adoption. The presence of established aerospace and defense companies fuels technological advancement. Collaborations between public institutions and private firms are enabling greater innovation and driving long-term growth.
Asia Pacific
Asia Pacific accounts for a 24% market share, supported by rapid drone adoption in defense, commercial, and agricultural applications. China, Japan, and India are major contributors to regional growth. Government investments in drone programs and training infrastructure are expanding. Cost-effective simulator solutions appeal to both military and private operators. The rise in commercial drone delivery services also drives demand for skilled pilots. Strong manufacturing capabilities and growing technology adoption make the region a key hub for future drone simulation development.
Latin America
Latin America holds a 5% share of the Drone Simulator Market, with growing interest in agricultural monitoring, infrastructure inspection, and security applications. Brazil and Mexico lead regional adoption due to expanding drone programs. Simulator demand is rising as governments and private sectors invest in cost-efficient training solutions. Limited infrastructure remains a challenge, but ongoing regulatory improvements support market expansion. Partnerships with international simulator providers are improving access to advanced technology. Gradual modernization of commercial and defense sectors will likely drive future market growth in this region.
Middle East & Africa
The Middle East & Africa region captures an 8% share of the Drone Simulator Market. Rising investments in border surveillance, oil infrastructure monitoring, and security applications drive demand. Countries such as the UAE and Saudi Arabia are actively adopting simulation systems to strengthen operational training. Government-led modernization programs support simulator integration across defense and civil sectors. The growing presence of global players through partnerships boosts technology transfer. Although adoption is slower than other regions, increasing security focus creates strong long-term growth potential.
Market Segmentations:
By Component:
- Hardware
- Software
By Technology:
- Augmented Reality
- Virtual Reality
By Drone Type:
- Fixed-Wing
- Rotary Wing
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Drone Simulator Market is highly competitive with key players including Skydio, Autel Robotics, SZ DJI Technology, Inc., 3DR, Inc., Pix4D, Parrot Drone SAS, RedBird, AgEagle Aerial Systems Inc, Airware Limited, and Mapbox. The Drone Simulator Market is characterized by strong competition and rapid technological innovation. Companies are focusing on enhancing simulation accuracy, integrating advanced virtual and augmented reality, and improving flight data visualization. Continuous investments in AI-powered training platforms and cloud-based solutions are enabling more flexible and cost-efficient training environments. Market participants are also targeting both defense and commercial sectors through scalable, high-fidelity simulation systems. Strategic collaborations with training centers, regulatory bodies, and aviation authorities are strengthening market presence. The emphasis on immersive experiences, operational safety, and regulatory compliance continues to shape the competitive dynamics of this growing market.
Key Player Analysis
- Skydio
- Autel Robotics
- SZ DJI Technology, Inc.
- 3DR, Inc.
- Pix4D
- Parrot Drone SAS
- RedBird
- AgEagle Aerial Systems Inc
- Airware Limited
- Mapbox
Recent Developments
- In February 2025, Pix4D and Freefly Systems announced a partnership aimed at enhancing drone data workflows by integrating Pix4D's advanced photogrammetry software with Freefly's cutting-edge drone technology. This collaboration seeks to streamline the process of capturing, processing, and analyzing aerial data, making it more efficient for industries such as construction, surveying, and agriculture.
- In January 2025, SZ DJI Technology Co., Ltd. launched the DJI Flip, a lightweight and foldable drone designed for vloggers, resembling a mini unicycle. Weighing just 249 grams, it features a 1/1.3-inch 48MP CMOS sensor capable of recording 4K HDR videos at 60 fps and slow-motion at 100 fps, along with SmartPhoto technology for enhanced clarity.
- In December 2024, MVRsimulation (MVR) has unveiled a streamlined first-person-view (FPV) UAV simulator at the Interservice/Industry Training, Simulation and Education Conference.
- In May 2024, Droneshield announced the release of DroneSentry C2 Next-Gen v1.00, an advanced command-and-control system that enhances the capabilities of anti-drone systems by providing centralized monitoring and control functionalities. It allows users to efficiently manage multiple sensors and countermeasures to protect critical infrastructure, public events, military installations, and other sensitive areas from potential drone threats
Report Coverage
The research report offers an in-depth analysis based on Component, Technology, Drone Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for drone simulators will grow with rising adoption of unmanned systems in multiple industries.
- Virtual and augmented reality integration will enhance training realism and mission readiness.
- AI-powered platforms will improve pilot performance tracking and adaptive learning.
- Cloud-based simulation systems will expand access for remote and large-scale training programs.
- Defense modernization programs will drive strong investments in advanced simulation tools.
- Commercial drone operators will increasingly rely on simulators to cut training costs.
- Regulatory developments will push for standardized simulation-based certification.
- Portable and modular simulators will gain popularity for flexible deployments.
- Partnerships between simulator developers and drone manufacturers will accelerate innovation.
- Advanced analytics and real-time scenario modeling will shape the next generation of training systems.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Drone Simulator Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Drone Simulator Market projected to grow between 2025 and 2032?
Which Drone Simulator Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Drone Simulator Market?
Who are the leading companies in the Drone Simulator Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 270.5 million → 2032: USD 827.47 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Drone Simulator Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Drone Simulator Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Drone Simulator Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Drone Simulator Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Drone Simulator Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Drone Simulator Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Drone Simulator Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Drone Simulator Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 270.5 million → 2032: USD 827.47 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Drone Simulator Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Drone Simulator Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Drone Simulator Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Drone Simulator Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

