
Market Overview:
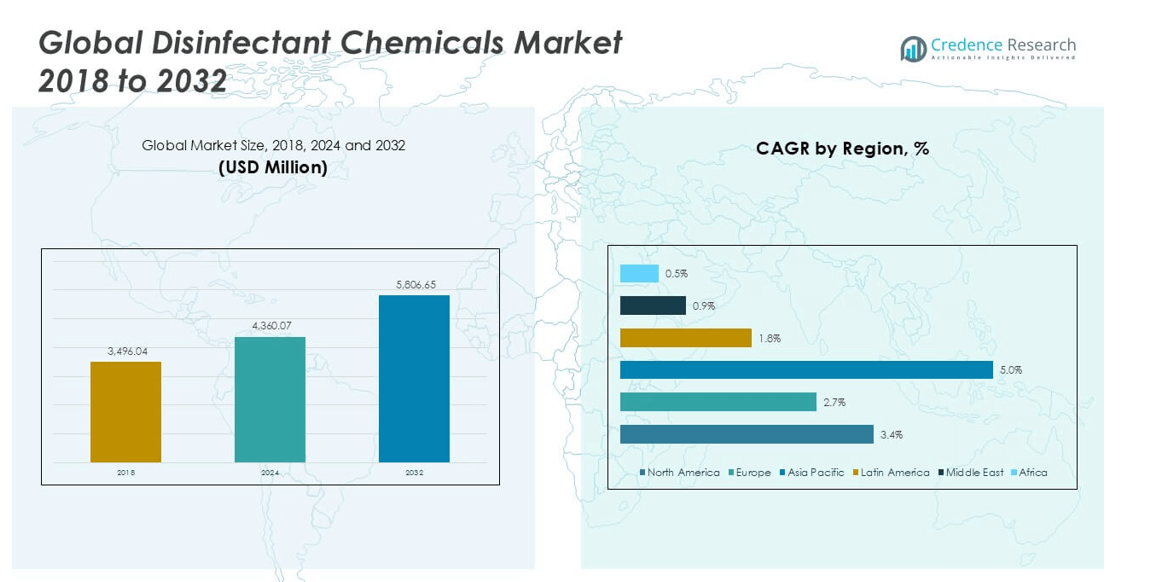
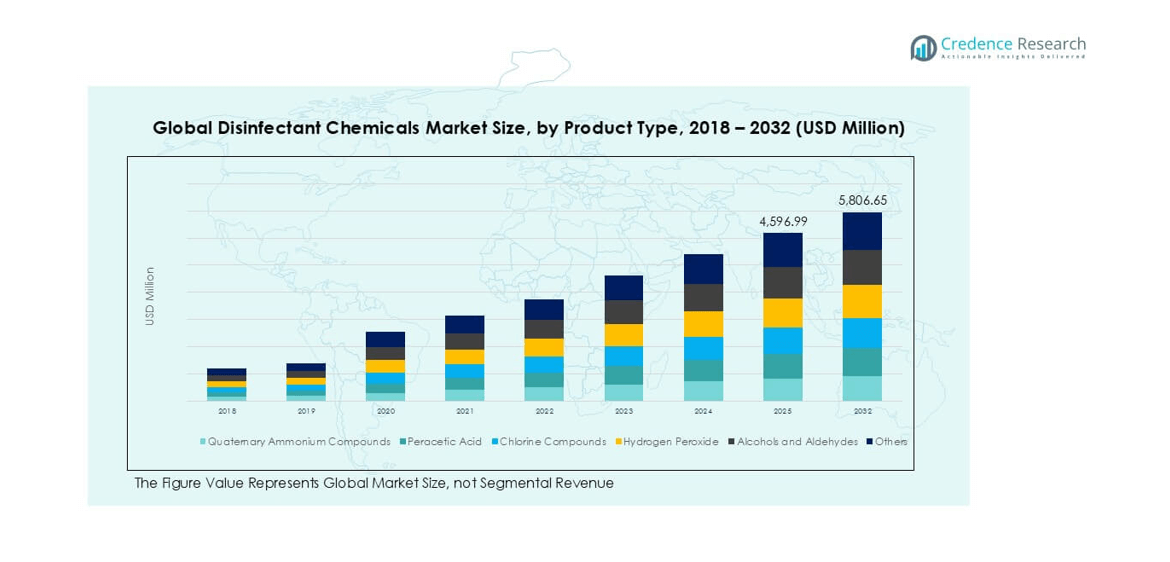
The Disinfectant Chemicals market size was valued at USD 3,496.04 million in 2018 and grew to USD 4,360.07 million in 2024. It is anticipated to reach USD 5,806.65 million by 2032, at a CAGR of 3.39% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Disinfectant Chemicals Market Size 2024 | USD 4,360.07 million |
| Disinfectant Chemicals Market, CAGR | 3.39% |
| Disinfectant Chemicals Market Size 2032 | USD 5,806.65 million |
The disinfectant chemicals market is led by major players including Reckitt Benckiser, Ecolab Inc., Diversey, Procter & Gamble, 3M, Lonza Group, Clorox Company, BASF SE, AkzoNobel, and Stepan Company, which dominate through broad product portfolios and strong global presence. North America emerged as the leading region in 2024, accounting for 42.3% of the global market share, supported by advanced healthcare infrastructure, stringent infection control standards, and high consumer awareness in residential cleaning. Europe followed with 28.8% share, driven by regulatory compliance and rising demand for eco-friendly solutions, while Asia Pacific captured 20.3% share, supported by rapid industrialization and growing hygiene awareness.
Market Insights
- The disinfectant chemicals market was valued at USD 4,360.07 million in 2024 and is projected to reach USD 5,806.65 million by 2032, growing at a CAGR of 3.39%.
- Growth is driven by rising healthcare-associated infection concerns, expanding food and beverage processing demand, and increased household and institutional hygiene awareness.
- Key trends include the shift toward eco-friendly, bio-based disinfectants and innovation in ready-to-use formats such as wipes and sprays, which appeal to both commercial and residential users.
- The competitive landscape is dominated by players like Reckitt Benckiser, Ecolab, Diversey, Procter & Gamble, 3M, Lonza, and Clorox, who focus on sustainable product development and expansion into emerging markets.
- Regionally, North America led with 42.3% share in 2024, followed by Europe at 28.8% and Asia Pacific at 20.3%, with Asia Pacific showing the fastest growth at a 5.0% CAGR, while Latin America, Middle East, and Africa together accounted for under 10%
Market Segmentation Analysis:
By Product Type
Quaternary ammonium compounds led the disinfectant chemicals market in 2024, holding the largest share due to their wide usage in healthcare, institutional cleaning, and food safety environments. Their popularity stems from broad-spectrum antimicrobial properties, surface compatibility, and cost-effectiveness. Chlorine compounds and hydrogen peroxide followed closely, driven by high demand in water treatment and hospital sterilization. Peracetic acid gained traction in food and beverage processing for residue-free disinfection. Alcohols and aldehydes maintained steady adoption in clinical environments, while the “Others” category, including iodine-based solutions, showed niche growth in specialized disinfection applications.
- For instance, Diversey, now part of Solenis, is a major global supplier of hygiene and cleaning products, including quaternary ammonium-based disinfectants, for hospitals, schools, and food processing facilities across North America and Europe.
By Formulation
Liquid disinfectants dominated the market with the highest share in 2024, favored for versatility and ease of application across industrial, commercial, and healthcare sectors. Liquids are widely used in bulk cleaning and surface sanitation, particularly in hospitals and food facilities. Sprays captured growing adoption due to convenience and faster application in high-traffic commercial and institutional spaces. Wipes also expanded steadily, driven by rising household and office demand for portable and single-use hygiene solutions. The segment’s performance reflects shifting consumer preference toward easy-to-use, ready-to-apply disinfectant formats.
- For instance, in 2023, Reckitt's Lysol brand returned to growth, with improved distribution of wipes and the launch of a new air sanitizer in the US.
By Application
Healthcare remained the leading application segment in 2024, accounting for the largest revenue share due to stringent infection control protocols in hospitals and clinics. Demand was reinforced by the need for sterilization in surgical and patient-care environments. Commercial and institutional use ranked second, supported by increasing hygiene practices across schools, offices, and hospitality sectors. Food and beverage processing showed significant demand, particularly in preventing contamination risks. Household use surged post-pandemic, supported by awareness of everyday sanitation. Industrial usage and other niche applications contributed to overall growth, though with relatively smaller market shares.
Market Overview
Rising Healthcare-Associated Infection Concerns
The growing prevalence of healthcare-associated infections (HAIs) is a major driver for disinfectant chemicals. Hospitals, clinics, and diagnostic centers face rising pressure to maintain sterile environments to reduce infection risks and meet global safety standards. Regulatory frameworks like CDC guidelines and WHO recommendations continue to enforce stricter disinfection protocols, driving higher demand for advanced cleaning agents. Quaternary ammonium compounds, chlorine compounds, and hydrogen peroxide are extensively used for surface sterilization, surgical instruments, and intensive care environments. Expanding hospital infrastructure in developing economies further accelerates product consumption, making healthcare the largest application segment.
- For instance, in 2023, Ecolab delivered a wide range of hygiene and infection prevention solutions, including concentrated quaternary ammonium and hydrogen peroxide disinfectants, to hospitals and healthcare facilities globally.
Expansion of Food & Beverage Processing Industry
The food and beverage sector increasingly relies on disinfectant chemicals to maintain hygiene across production, packaging, and distribution. Rising consumer demand for safe and contamination-free food is pushing producers to adopt stringent sanitation standards. Regulatory bodies like the FDA and EFSA mandate strict use of approved disinfectants to prevent microbial contamination. Peracetic acid and chlorine compounds are widely used due to their effectiveness and safety in food contact surfaces. Global expansion of packaged and processed food industries, along with growing export standards, is fueling sustained demand for disinfectant chemicals across this sector.
- For instance, Solvay is a supplier of hydrogen peroxide–based disinfectants to the food and beverage industry, ensuring compliance with hygiene standards in Europe and North America.
Growing Awareness in Residential and Commercial Spaces
Increased consumer awareness of hygiene, amplified by the COVID-19 pandemic, has permanently elevated demand for disinfectants in households, offices, and public facilities. Everyday sanitation routines now include the use of wipes, sprays, and liquid disinfectants for surfaces, contributing to a steady shift in consumer purchasing behavior. Commercial facilities such as schools, retail outlets, and hospitality venues prioritize visible hygiene standards to reassure customers and staff. This behavioral change has transformed disinfectants from being primarily institutional products to mainstream household essentials. Continued emphasis on preventive health and wellness ensures robust market demand in residential and commercial applications.
Key Trends & Opportunities
Shift Toward Eco-Friendly and Bio-Based Disinfectants
Sustainability has become a key trend, with rising demand for eco-friendly and bio-based disinfectants that minimize chemical residues and reduce environmental impact. Consumers and institutions increasingly prefer hydrogen peroxide, plant-derived alcohols, and biodegradable formulations over chlorine-based products. Companies are investing in green chemistry solutions, aiming to align with regulations like REACH and EPA Safer Choice standards. This shift creates opportunities for manufacturers to expand product portfolios with sustainable disinfectants that appeal to both environmentally conscious consumers and institutions striving for green certifications.
- For instance, Evonik supplied more than 15,000 metric tons of hydrogen peroxide–based eco-friendly disinfectants in 2023, targeting food processors and healthcare facilities seeking biodegradable sanitation solutions.
Innovation in Ready-to-Use and Advanced Formulations
The market is witnessing strong opportunities in advanced product formats such as ready-to-use sprays, pre-saturated wipes, and concentrated liquids designed for quick application. Digital monitoring solutions integrated with disinfection systems in healthcare and commercial facilities also present growth avenues. Rising adoption of automated disinfection systems, including UV and electrostatic sprayers supported by chemical formulations, adds momentum. This innovation-driven trend offers opportunities for companies to differentiate offerings through convenience, efficiency, and safety while tapping into diverse customer segments.
Key Challenges
Health Risks and Toxicity Concerns
Despite strong demand, disinfectant chemicals face scrutiny over potential health hazards linked to overexposure. Prolonged use of chlorine compounds and aldehyde-based disinfectants may cause respiratory issues, skin irritation, or indoor air quality concerns. Rising awareness among consumers and healthcare professionals has increased pressure on manufacturers to develop safer, less toxic formulations. Regulatory compliance related to worker safety, permissible exposure limits, and product labeling adds to industry complexity. Failure to address toxicity concerns may limit adoption in sensitive environments like schools, food facilities, and residential settings.
Volatile Raw Material Prices and Supply Chain Disruptions
The market is challenged by fluctuating raw material costs for chemical feedstocks such as ethanol, chlorine, and hydrogen peroxide. Geopolitical tensions, energy price volatility, and trade disruptions often lead to higher production costs. Smaller manufacturers struggle to manage price instability, reducing competitiveness against large global players. In addition, transportation delays and global supply chain disruptions affect product availability, particularly in emerging markets. These factors create uncertainty for end users and hinder stable long-term adoption, pressing companies to adopt localized supply strategies and cost-control measures.
Regional Analysis
North America
North America dominated the disinfectant chemicals market in 2024, holding 42.3% share with a market size of USD 1,843.48 million, up from USD 1,494.01 million in 2018. The region is projected to reach USD 2,462.08 million by 2032, expanding at a CAGR of 3.4%. Strong demand arises from stringent healthcare protocols, infection prevention practices, and regulatory compliance across hospitals and food facilities. High consumer awareness in residential cleaning and widespread institutional use further sustain growth. Continuous investment in advanced disinfectants and sustainable formulations positions North America as the leading regional market.
Europe
Europe accounted for 28.8% share of the global disinfectant chemicals market in 2024, valued at USD 1,256.22 million, compared with USD 1,043.03 million in 2018. The region is forecasted to reach USD 1,580.10 million by 2032, growing at a CAGR of 2.7%. Growth is supported by strict regulatory frameworks such as REACH and the Biocidal Products Regulation (BPR), ensuring the use of effective and safe disinfectants. Demand remains concentrated in healthcare, food processing, and institutional cleaning. The region’s rising focus on green and biodegradable disinfectants also fuels steady adoption across industrial and household applications.
Asia Pacific
Asia Pacific emerged as the fastest-growing regional market, registering 20.3% share in 2024 with a market size of USD 886.71 million, rising from USD 654.58 million in 2018. It is expected to reach USD 1,341.39 million by 2032 at a CAGR of 5.0%, the highest globally. Growth is driven by rapid healthcare infrastructure expansion, increasing population, and heightened hygiene awareness. Strong government initiatives in infection prevention, especially in China and India, reinforce demand. Expanding food processing industries and rising adoption of household disinfectants further accelerate market expansion, positioning Asia Pacific as a critical growth hub.
Latin America
Latin America captured 4.5% share of the global disinfectant chemicals market in 2024, reaching USD 198.54 million, up from USD 161.25 million in 2018. The market is projected to grow to USD 233.29 million by 2032 at a CAGR of 1.8%. Demand is primarily concentrated in healthcare and institutional sectors, with Brazil and Mexico leading consumption. Moderate growth reflects limited healthcare infrastructure and economic fluctuations. However, rising investments in hygiene awareness campaigns and adoption of disinfectants in food and beverage processing are providing steady demand, despite relatively lower market penetration compared to developed regions.
Middle East
The Middle East accounted for 2.3% share in 2024, with a market value of USD 99.05 million, up from USD 87.83 million in 2018. The market is projected to reach USD 108.68 million by 2032, growing at a CAGR of 0.9%. Adoption is mainly driven by healthcare facilities and institutional cleaning demand in countries like Saudi Arabia and the UAE. However, the region experiences slower growth due to limited diversification in industrial and household applications. Increasing urbanization and a gradual rise in hygiene standards offer some growth potential, though expansion remains relatively subdued compared to other regions.
Africa
Africa represented 1.7% share of the disinfectant chemicals market in 2024, valued at USD 76.08 million, up from USD 55.34 million in 2018. The market is estimated to reach USD 81.12 million by 2032, growing at a modest CAGR of 0.5%. Adoption is limited by low healthcare infrastructure penetration and affordability challenges in many countries. Growth opportunities exist in urban areas where institutional facilities and hospitals are expanding. International aid programs and rising awareness of sanitation contribute to incremental demand. However, overall growth in Africa remains the slowest globally due to economic and infrastructural constraints.
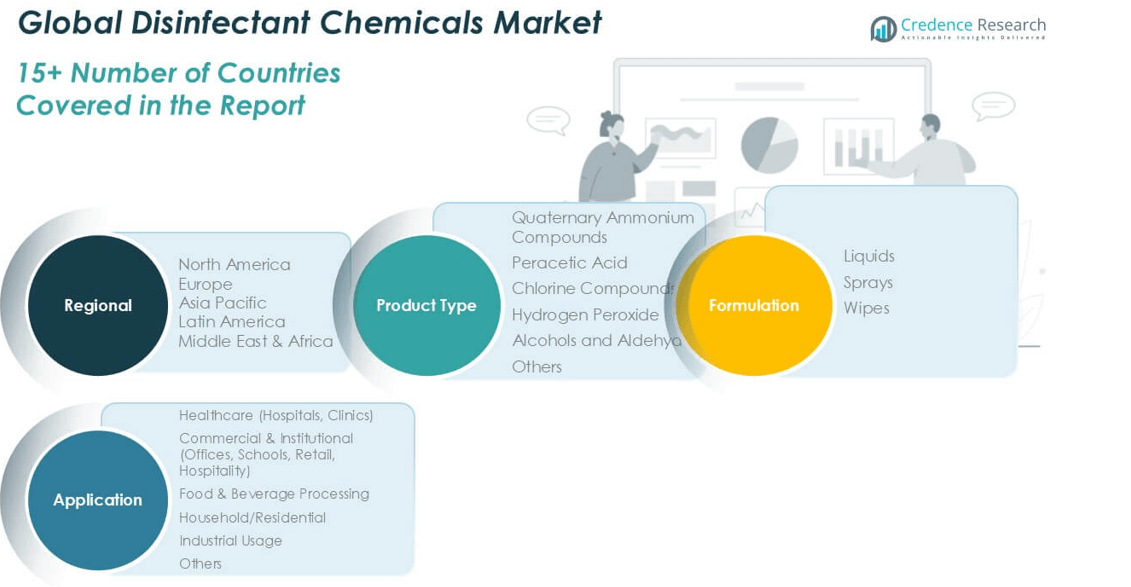
Market Segmentations:
By Product Type
- Quaternary Ammonium Compounds
- Peracetic Acid
- Chlorine Compounds
- Hydrogen Peroxide
- Alcohols and Aldehydes
- Others
By Formulation
- Liquids
- Sprays
- Wipes
By Application
- Healthcare (Hospitals, Clinics)
- Commercial & Institutional (Offices, Schools, Retail, Hospitality)
- Food & Beverage Processing
- Household/Residential
- Industrial Usage
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The disinfectant chemicals market is moderately consolidated, with global players such as Reckitt Benckiser, Ecolab Inc., Diversey, Procter & Gamble, 3M, Lonza Group, Clorox Company, BASF SE, AkzoNobel, and Stepan Company dominating industry growth. These companies leverage extensive product portfolios, global distribution networks, and strong R&D capabilities to maintain leadership. Innovation in eco-friendly formulations, residue-free disinfectants, and ready-to-use applications remains a core strategy to meet evolving consumer and regulatory demands. Financial strength allows key players to expand into emerging markets, while partnerships and acquisitions help broaden reach across healthcare, food processing, and residential sectors. Smaller regional firms compete by offering cost-effective and localized solutions, though brand recognition and compliance with international standards remain barriers. Competitive intensity is further heightened by increasing demand for sustainable disinfectants and rising regulatory scrutiny, prompting continuous innovation and differentiation.
Key Player Analysis
- Reckitt Benckiser Group plc
- Ecolab Inc.
- Diversey, Inc.
- Procter & Gamble
- 3M Company
- Lonza Group AG
- Clorox Company
- BASF SE
- AkzoNobel N.V.
- Stepan Company
Recent Developments
- In June 2023, an EPA-approved air sanitizer spray has been unveiled in the U.S.A. by Lysol Air Sanitizer. The brand's initial introduction was the EPA-approved air sanitizer spray.
- In March 2022, PDI launched Sani-24® Germicidal Disposable Wipe, Sani-HyPerCide® Germicidal Disposable Wipe, and Sani-HyPerCide® Germicidal Spray as a way of combating healthcare infections (HAIs) that were growing in number and addressing Covid-19 challenges in health care settings.
- In March 2022, PDI will launch new products like Sani-24 Germicidal Disposable Wipe, Sani-HyPerCide Germicidal Disposable Wipe, and Sani-HyPerCide Germicidal Spray. These highly advanced disinfectants will thus help infection control staff tackle the increasing prevalence of healthcare-associated infections (HAIs)
Report Coverage
The research report offers an in-depth analysis based on Product Type, Formulation, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The disinfectant chemicals market will continue steady growth driven by rising hygiene awareness.
- Healthcare will remain the largest application segment supported by infection control protocols.
- Asia Pacific will see the fastest growth due to expanding healthcare infrastructure and population needs.
- Eco-friendly and bio-based disinfectants will gain strong adoption across industries.
- Ready-to-use formats like sprays and wipes will dominate household and institutional demand.
- Key players will expand portfolios through innovation and acquisitions in emerging markets.
- Regulatory compliance will shape product development toward safer and less toxic formulations.
- Food and beverage processing will increase usage to meet strict global safety standards.
- Competition will intensify as regional manufacturers enter with cost-effective solutions.
- Long-term growth will rely on sustainability, innovation, and strong regional distribution networks.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Healthcare-Associated Infection Concerns
The increasing prevalence of healthcare-associated infections (HAIs) is driving hospitals and clinics to adopt stricter disinfection protocols, boosting demand for advanced disinfectant chemicals, especially in developed and rapidly developing healthcare markets.
Expansion of Food & Beverage Processing Industry
Stringent hygiene standards and regulatory requirements in food and beverage processing are fueling the use of disinfectant chemicals to prevent contamination, with compounds like peracetic acid and chlorine widely adopted for residue-free and safe disinfection.
Growing Awareness in Residential and Commercial Spaces
Post-pandemic consumer behavior has shifted toward routine use of disinfectants in homes, offices, and public facilities, leading to sustained demand for easy-to-use formats like wipes and sprays across both household and institutional segments.
Shift Toward Eco-Friendly and Bio-Based Disinfectants
Increasing environmental and health concerns are prompting consumers and institutions to prefer hydrogen peroxide, plant-derived alcohols, and biodegradable formulations, encouraging manufacturers to innovate and expand sustainable product lines.
Innovation in Ready-to-Use and Advanced Formulations
The market is experiencing strong growth in ready-to-use sprays, wipes, and concentrated liquids, as well as digital and automated disinfection systems, which offer convenience, efficiency, and appeal to a broad range of commercial and residential users.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Disinfectant Chemicals market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Disinfectant Chemicals market projected to grow between 2025 and 2032?
Which Disinfectant Chemicals market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Disinfectant Chemicals market?
Who are the leading companies in the Disinfectant Chemicals market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Healthcare (Hospitals, Clinics)
- 1.2.2 Commercial & Institutional (Offices, Schools, Retail, Hospitality)
- 1.2.3 Food & Beverage Processing
- 1.2.4 Household/Residential
- 1.2.5 Industrial Usage
- 1.2.6 Others
- 1.3 By Formulation
- 1.3.1 Liquids
- 1.3.2 Sprays
- 1.3.3 Wipes
- 1.4 By Product Type
- 1.4.1 Quaternary Ammonium Compounds
- 1.4.2 Peracetic Acid
- 1.4.3 Chlorine Compounds
- 1.4.4 Hydrogen Peroxide
- 1.4.5 Alcohols and Aldehydes
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,360.07 million → 2032: USD 5,806.65 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Disinfectant Chemicals Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Disinfectant Chemicals Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Disinfectant Chemicals Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Disinfectant Chemicals Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Disinfectant Chemicals Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Disinfectant Chemicals Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Disinfectant Chemicals Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Disinfectant Chemicals Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,360.07 million → 2032: USD 5,806.65 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Disinfectant Chemicals Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Healthcare (Hospitals, Clinics)
- 12.3.7.2 Commercial & Institutional (Offices, Schools, Retail, Hospitality)
- 12.3.7.3 Food & Beverage Processing
- 12.3.7.4 Household/Residential
- 12.3.7.5 Industrial Usage
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Formulation - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Liquids
- 12.4.7.2 Sprays
- 12.4.7.3 Wipes
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Quaternary Ammonium Compounds
- 12.5.7.2 Peracetic Acid
- 12.5.7.3 Chlorine Compounds
- 12.5.7.4 Hydrogen Peroxide
- 12.5.7.5 Alcohols and Aldehydes
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Disinfectant Chemicals End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Disinfectant Chemicals Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Disinfectant Chemicals Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Disinfectant Chemicals Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Reckitt Benckiser Group plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ecolab Inc.
- 18.4 Diversey, Inc.
- 18.5 Procter & Gamble
- 18.6 3M Company
- 18.7 Lonza Group AG
- 18.8 Clorox Company
- 18.9 BASF SE
- 18.10 AkzoNobel N.V.
- 18.11 Stepan Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

