
Market Overview:
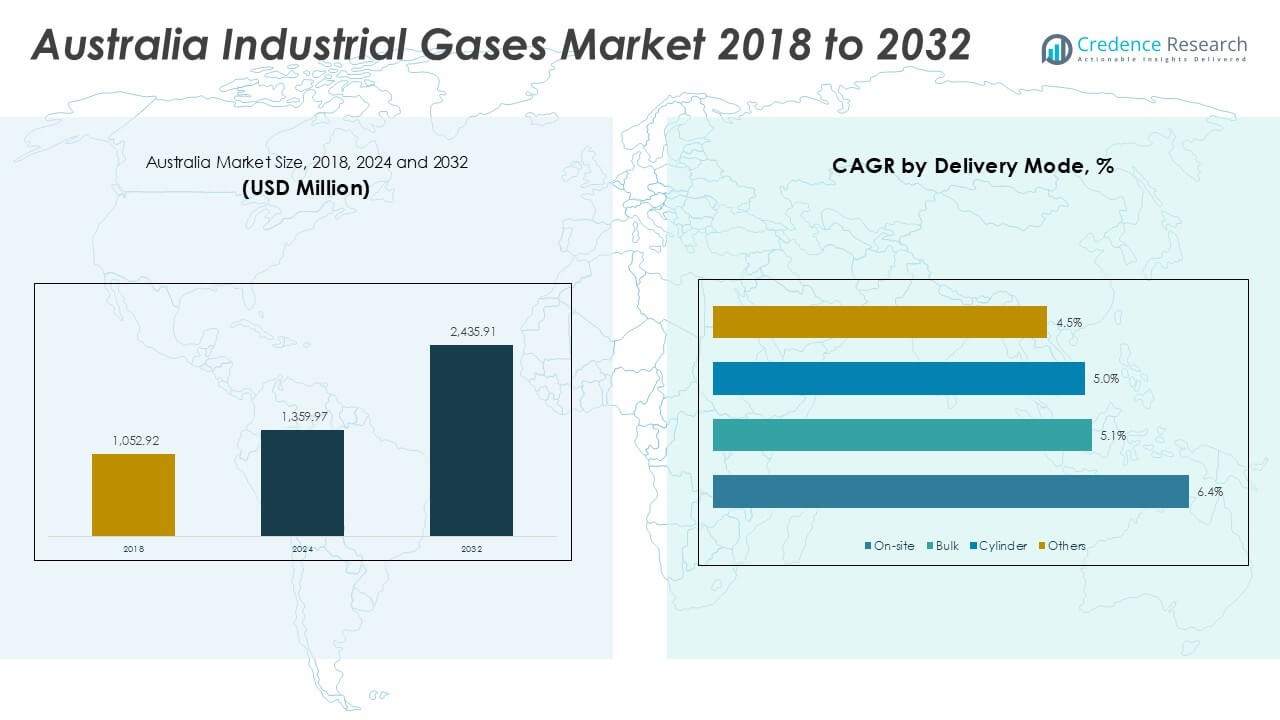
The Australia Industrial Gases Market size was valued at USD 1,052.92 million in 2018 to USD 1,359.97 million in 2024 and is anticipated to reach USD 2,435.91 million by 2032, at a CAGR of 7.56% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Industrial Gases Market Size 2024 | USD 1,359.97 million |
| Australia Industrial Gases Market, CAGR | 7.56% |
| Australia Industrial Gases Market Size 2032 | USD 2,435.91 million |
Growth is driven by strong demand from healthcare, food and beverage, and mining industries. Oxygen plays a vital role in medical treatments, while nitrogen and carbon dioxide are critical for packaging and carbonation in the food sector. Mining and metallurgy require gases like oxygen and acetylene for extraction and refining. Rising investments in clean energy and hydrogen projects also expand new opportunities. Sustainability pressures further strengthen adoption across industries.
Regionally, eastern Australia leads due to established healthcare systems, advanced manufacturing, and strong food processing bases. Western Australia shows significant demand supported by mining and natural resource industries. Northern and southern regions, including Queensland and South Australia, are emerging with growth in food processing, research, and clean energy projects. The Australia Industrial Gases Market demonstrates a balanced landscape, where mature regions sustain demand and developing regions create fresh opportunities for expansion.
Market Insights
- The Australia Industrial Gases Market size was USD 1,052.92 million in 2018, reached USD 1,359.97 million in 2024, and is projected to hit USD 2,435.91 million by 2032, at a CAGR of 7.56%.
- The Global Industrial Gases Market size was valued at USD 87,600.00 million in 2018 to USD 1,10,625.01 million in 2024 and is anticipated to reach USD 1,95,368.52 million by 2032, at a CAGR of 7.44% during the forecast period.
- Eastern Australia held 41% share in 2024, driven by healthcare, advanced manufacturing, and food processing; Western Australia accounted for 33% due to mining and energy demand; Northern and Southern regions together made up 26%, supported by food, research, and clean energy projects.
- Queensland within Northern Australia is the fastest-growing region, holding part of the 26% share, fueled by food processing expansion, medical applications, and renewable energy investments.
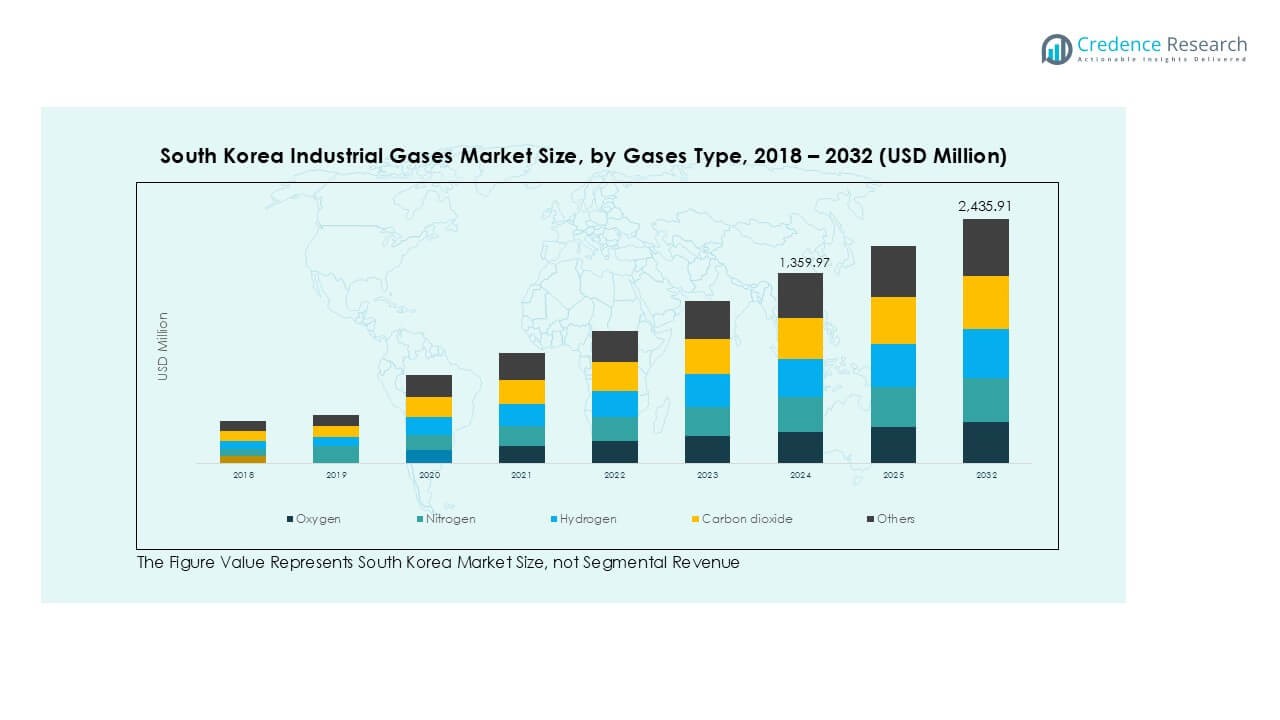
- Oxygen led the gases type segment in 2024 with 34% share, supported by demand from healthcare, metallurgy, and mining sectors.
- Nitrogen accounted for 28% share, largely driven by its extensive use in packaging and food preservation industries across the country.
Market Drivers
Growing Demand From Healthcare Sector With Focus On Medical Applications Of Industrial Gases
The healthcare industry creates consistent demand for oxygen, nitrogen, and other medical-grade gases. Hospitals require oxygen for respiratory treatments and surgical operations, making it a core necessity. Nitrous oxide remains vital for anesthesia, and medical nitrogen supports cryopreservation and equipment sterilization. The growth of chronic respiratory diseases boosts reliance on oxygen supply chains. The Australia Industrial Gases Market benefits from rising healthcare infrastructure investments across metropolitan and regional centers. Government programs supporting advanced medical facilities further drive gas consumption. Pharmaceutical production also depends on sterile gas applications. It ensures strong long-term demand growth within the healthcare ecosystem.
Expansion Of Food And Beverage Industry With High Reliance On Preservative Applications
Food and beverage companies adopt gases like nitrogen and carbon dioxide to enhance product safety. Nitrogen protects packaged foods by reducing oxidation and extending shelf life. Carbon dioxide plays a crucial role in carbonation and storage stability of beverages. The Australia Industrial Gases Market gains strength from its integration in dairy, meat, and processed food industries. Food export growth also expands gas requirements for preservation during long shipments. Large retail networks and changing consumer preferences increase packaged food adoption. This reliance makes gases indispensable for ensuring consistent product quality. It highlights the sector as a key driver of gas demand.
- For instance, BOC, a Linde company, opened the South Pacific’s largest merchant carbon dioxide processing facility in Longford, Victoria in December 2024, with a capacity to produce more than 60,000 tonnes of beverage-grade CO2 annually enough to carbonate 7.5 billion liters of drinks, supporting large-scale food and beverage operations across Australia.
Rising Role Of Mining And Energy Sectors Requiring Specialty Gases For Efficiency
The mining industry remains a dominant pillar of the Australian economy. Specialty gases support mineral extraction, refining, and environmental safety processes. Oxygen improves combustion efficiency in metal smelting, reducing operational costs. The Australia Industrial Gases Market benefits from mining projects expanding in Western Australia and Queensland. Energy companies depend on industrial gases for refining oil and natural gas. Hydrogen plays a growing role in clean energy projects, creating new applications. Government emphasis on low-emission technologies supports this trend. It enhances the demand outlook across mining and energy-related industries.
Adoption Of Cleaner Production And Rising Sustainability Standards Across Industries
Sustainability requirements influence industrial operations across Australia. Manufacturers adopt eco-friendly gases to meet emission reduction goals. Carbon capture projects rely on gases for storage and processing, encouraging investments. The Australia Industrial Gases Market strengthens through alignment with decarbonization strategies. Environmental regulations create new demand for gas solutions in industrial applications. Industrial users adopt gases to replace older, pollutive fuels. Hydrogen and bio-based gases gain focus for long-term energy transition. It positions the sector as a core enabler of cleaner operations across industries.
- For instance, BOC and bp Australia officially opened the nation’s first hydrogen refuelling station at the bp Port of Brisbane Truckstop in August 2023, with the on-site BOC electrolyser powered by solar energy and producing hydrogen that enables fleet vehicles to fully refuel within approximately 3–5 minutes, demonstrating the practical deployment of clean hydrogen infrastructure for industrial use.
Market Trends
Integration Of Digital Technologies Into Production And Distribution Systems For Efficiency Gains
Gas producers adopt digital monitoring tools to improve supply chain visibility. Smart sensors track storage conditions and enable predictive maintenance of equipment. Companies employ automation to enhance cylinder filling and distribution. The Australia Industrial Gases Market shows steady integration of IoT platforms in logistics. Remote monitoring improves safety and reduces operational disruptions. Predictive analytics allows producers to forecast demand and optimize inventory. Digital platforms strengthen customer service by ensuring timely delivery. It reflects a shift toward technologically advanced supply networks.
Growing Role Of Hydrogen Economy Driving New Demand For Sustainable Gas Solutions
Hydrogen adoption gains momentum across transportation and energy projects. Public and private initiatives highlight hydrogen’s role in decarbonization. Pilot projects for hydrogen fueling stations are expanding in major states. The Australia Industrial Gases Market captures growth from hydrogen’s integration in energy systems. Companies invest in infrastructure for production, storage, and distribution. Partnerships between gas suppliers and energy developers accelerate hydrogen scaling. Industries view hydrogen as a long-term clean energy carrier. It positions industrial gases as essential to future energy solutions.
- For instance, Viva Energy launched Australia’s largest hydrogen refuelling station in Geelong, Victoria, in June 2025, featuring a 2.5-megawatt electrolyzer and the capacity to supply up to 1,000 kilograms of renewable hydrogen per day for fleets of heavy transport vehicles and buses.
Increasing Use Of Specialty Gases In Electronics, Manufacturing, And Research Applications
Specialty gases gain traction in semiconductor and electronics manufacturing. High-purity gases are critical for etching and deposition processes. Research labs also require consistent gas supply for advanced testing. The Australia Industrial Gases Market benefits from the growing technology manufacturing ecosystem. Global firms expand their presence in Australia, fueling higher demand. Specialty gases support precision operations where impurities cannot be tolerated. The trend highlights diversification beyond traditional bulk gas consumption. It creates sustained growth opportunities in knowledge-intensive industries.
Rising Investments In Renewable Energy And Carbon Neutral Projects Influencing Gas Adoption
Renewable energy projects rely on gases for storage, efficiency, and processing. Companies adopt carbon dioxide in carbon capture and utilization projects. The Australia Industrial Gases Market sees rising demand for gases in energy transition activities. Gas producers partner with renewable developers to expand application areas. Investment in wind, solar, and bioenergy drives complementary gas usage. Companies explore blending gases into renewable storage solutions. The push for net-zero targets creates new customer segments for suppliers. It demonstrates long-term alignment with national energy goals.
- For instance, Coregas operates a hydrogen refuelling facility at Port Kembla, commissioned in July 2023, with a refuelling capacity of 400 kilograms of hydrogen per day for heavy transport vehicles, marking a critical step in supporting Australia’s clean energy and decarbonization strategy.
Market Challenges Analysis
High Production And Distribution Costs Impacting Pricing And Supply Reliability For Customers
The cost structure of industrial gas production requires heavy capital investments. Setting up air separation units and liquefaction plants increases financial pressure. The Australia Industrial Gases Market faces challenges in balancing cost and affordability. Energy prices contribute significantly to production costs, raising overall expenses. Distribution logistics add further pressure, particularly in remote regions. Transporting gases requires specialized infrastructure and compliance with safety rules. Smaller companies struggle to compete with larger players due to scale advantages. It creates barriers for new entrants and reduces competitive flexibility.
Regulatory Pressures And Environmental Concerns Limiting Traditional Production Practices
Strict environmental rules affect traditional gas production and storage methods. Authorities demand adherence to sustainability guidelines across industrial sectors. The Australia Industrial Gases Market adapts operations to comply with emissions limits. Producers face costs for retrofitting facilities with cleaner technologies. Community opposition to large-scale projects also creates regulatory delays. Safety standards add complexity to distribution in densely populated areas. Transition toward hydrogen and bio-based gases requires additional investment. It increases operational risks for companies unable to adapt quickly.
Market Opportunities
Expanding Hydrogen Economy Creating New Demand Pathways For Energy Transition Projects
The hydrogen economy emerges as a transformative opportunity across Australia. Government strategies support investments in hydrogen production and export. The Australia Industrial Gases Market gains a growth platform through its integration with energy policies. Companies scale infrastructure to capture demand from transportation and power generation. Exports position Australia as a global hydrogen supplier. Hydrogen blending into natural gas pipelines adds domestic demand. It secures long-term opportunities in renewable-aligned industrial ecosystems.
Technological Innovation And Strategic Partnerships Strengthening Application Scope Across Industries
Innovation in energy-efficient separation and liquefaction enhances competitiveness of producers. The Australia Industrial Gases Market benefits from partnerships between suppliers and end-users. Collaboration accelerates adoption in healthcare, food, and mining sectors. Investments in digital platforms open new revenue models for companies. Expansion of storage solutions enables more reliable supply. Companies focus on developing bio-based gases for eco-conscious customers. It strengthens opportunities across industries seeking efficiency and sustainability.
Market Segmentation Analysis
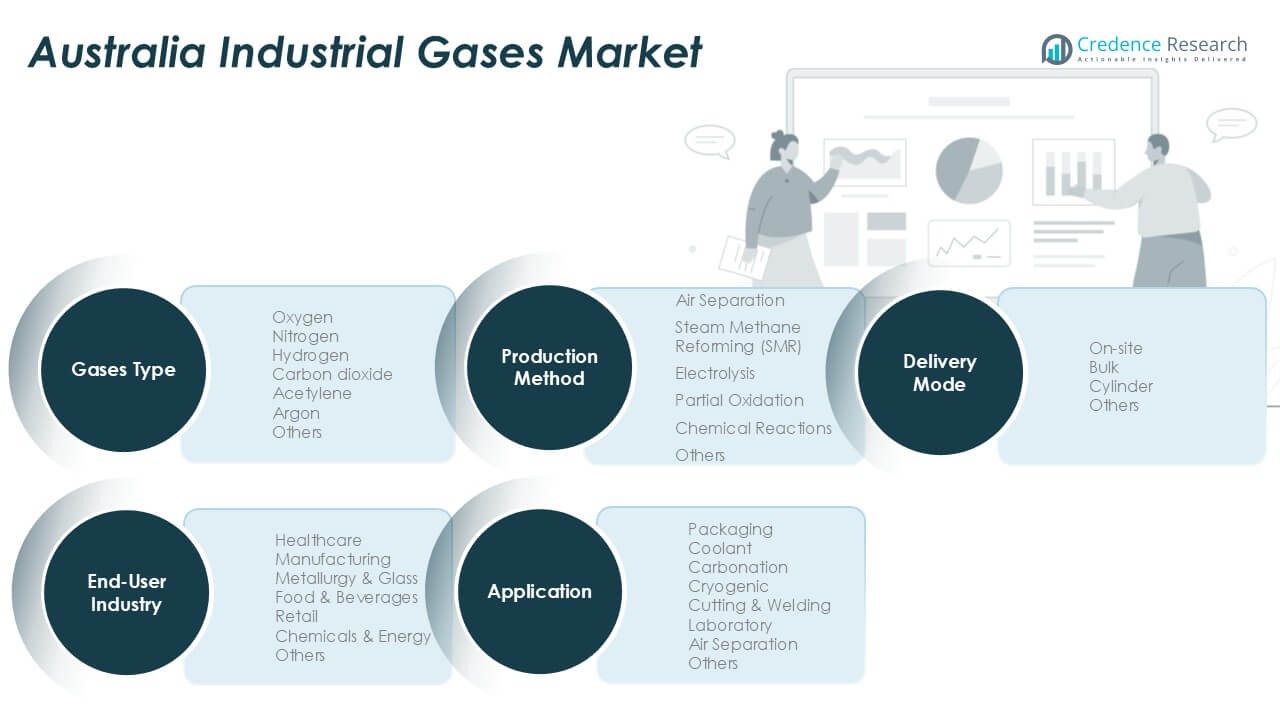
By Gases Type
The Australia Industrial Gases Market by gases type is dominated by oxygen, which is essential for healthcare, metallurgy, and mining. Nitrogen plays a strong role in packaging, preservation, and chemical processes. Hydrogen is expanding quickly with energy transition projects and clean fuel applications. Carbon dioxide supports beverage carbonation and water treatment industries. Acetylene and argon serve niche welding, fabrication, and industrial needs. Other specialty gases cater to research and advanced manufacturing sectors. It shows balanced demand across diverse categories.
By Application
Packaging and carbonation remain leading applications due to strong food and beverage demand. Cryogenic applications are expanding with medical, energy, and space-related activities. Cutting and welding support construction, automotive, and heavy industries. Laboratory demand is rising with research and biotechnology advancements. Air separation is a core application driving gas production efficiency. Other uses continue to emerge across smaller industries. The Australia Industrial Gases Market benefits from versatile usage across multiple application areas.
- For instance, Linde Engineering signed an agreement in March 2024 to deliver an air separation unit with a capacity of 63,000 Nm³/h of oxygen and a nitrogen wash unit of 392,000 Nm³/h syngas to Australia’s largest urea plant in Karratha, directly supporting expanded fertilizer and food sector inputs.
By End-User Industry
Healthcare accounts for high demand due to oxygen and nitrogen usage in hospitals and treatment facilities. Manufacturing relies on gases for cooling, cutting, and production efficiency. Metallurgy and glass industries depend on oxygen for smelting and processing. Food and beverages adopt nitrogen and carbon dioxide for packaging and carbonation. Chemicals and energy sectors drive hydrogen and other industrial gas demand. Retail contributes through smaller-scale supply. Other industries add incremental opportunities. It reflects the broad adoption of gases across the economy.
- For instance, in May 2025, Air Liquide Australia signed an agreement with Manildra Group to build the country’s largest food and beverage-grade carbon dioxide plant in Bomaderry, New South Wales, with an annual production capacity exceeding 90,000 tonnes to support food, water treatment, and manufacturing sectors.
By Production Method
Air separation is the dominant production method due to its efficiency and scalability. Steam methane reforming supports hydrogen production for industrial and energy applications. Electrolysis is gaining attention for green hydrogen generation. Partial oxidation and chemical reactions provide niche production capabilities. Other methods serve specialized industry requirements. The Australia Industrial Gases Market continues to evolve as companies invest in advanced, energy-efficient production systems. It supports the transition to sustainable gas supply models.
By Delivery Mode
On-site delivery dominates for large-scale industrial users such as healthcare facilities, refineries, and manufacturing hubs. Bulk delivery provides reliable supply for medium to large operations across food and mining industries. Cylinder distribution supports smaller enterprises and specialized applications requiring portability. Other delivery modes address custom requirements for niche industries. The Australia Industrial Gases Market ensures flexible supply systems tailored to varying industry demands. It highlights adaptability as a key competitive advantage for suppliers.
Segmentation
By Gases Type
- Oxygen
- Nitrogen
- Hydrogen
- Carbon Dioxide
- Acetylene
- Argon
- Others
By Application
- Packaging
- Coolant
- Carbonation
- Cryogenic
- Cutting & Welding
- Laboratory
- Air Separation
- Others
By End-User Industry
- Healthcare
- Manufacturing
- Metallurgy & Glass
- Food & Beverages
- Retail
- Chemicals & Energy
- Others
By Production Method
- Air Separation
- Steam Methane Reforming (SMR)
- Electrolysis
- Partial Oxidation
- Chemical Reactions
- Others
By Delivery Mode
- On-site
- Bulk
- Cylinder
- Others
Regional Analysis
Eastern Australia
Eastern Australia, led by New South Wales and Victoria, holds the largest share of 41% in the Australia Industrial Gases Market. Strong industrial bases, healthcare infrastructure, and advanced manufacturing clusters drive high consumption. The healthcare sector creates stable demand for oxygen and nitrogen across hospitals and research facilities. Manufacturing and food industries rely on nitrogen and carbon dioxide for packaging and preservation. Energy projects in this region also support growth through hydrogen adoption. It remains the core hub for suppliers, with steady demand across diversified applications.
Western Australia
Western Australia captures 33% share due to its dominant mining and resource-driven economy. Mining operations depend on oxygen and specialty gases for extraction and refining processes. Energy projects across LNG and natural gas increase gas consumption significantly. Regional infrastructure supports large-scale supply chains for both bulk and on-site deliveries. The Australia Industrial Gases Market benefits here from high resource activity and export-focused demand. It provides consistent opportunities for suppliers due to long-term mining and energy reliance. The subregion remains critical for growth in industrial-grade gases.
Northern and Southern Australia
Northern and Southern Australia collectively account for 26% share of the market. Northern areas like Queensland show rising demand from food processing, medical services, and packaging applications. Southern regions, including South Australia and Tasmania, see adoption in manufacturing and clean energy projects. Growing investment in hydrogen and renewable energy initiatives further boosts prospects. The Australia Industrial Gases Market finds new opportunities in these regions due to expanding healthcare and sustainability programs. It demonstrates stable but emerging growth potential in secondary industrial hubs. These areas provide new avenues for suppliers expanding beyond the eastern and western strongholds.
Key Player Analysis
- BOC Australia
- Air Liquide Australia
- Linde (Linde Material Handling)
- Coregas
- Supagas
- BASF Australia
- Wesfarmers Kleenheat Gas
- Iwatani Australia
- Messer & Opie
- Air Products & Chemicals, Inc.
Competitive Analysis
The Australia Industrial Gases Market features a competitive landscape shaped by global leaders and regional players. BOC Australia, Air Liquide, Linde, and Air Products maintain strong dominance through large production facilities, on-site supply models, and long-term contracts. Domestic firms such as Coregas, Supagas, and Wesfarmers Kleenheat Gas secure niche positions with regional supply networks and customized services. BASF Australia and Iwatani Australia expand portfolios by integrating specialty and energy-focused gases, including hydrogen. Competition centers on innovation, cost control, and expanding customer reach across healthcare, mining, and energy sectors. It is defined by strategic expansions, mergers, and technology adoption aimed at strengthening market positions.
Recent Developments
- In September 2025, Envision Energy established a new strategic partnership in Australia targeting renewable energy advancement, the development of net zero industrial parks, as well as new green hydrogen and ammonia projects, strengthening its long-term commitment to Australia’s industrial gases and sustainable energy sectors.
- In May 2025, Air Liquide Australia signed an agreement with Manildra Group to build the country's largest food and beverage grade carbon dioxide (CO₂) plant in Bomaderry, New South Wales. The new facility, planned for construction starting in the second half of 2025, will have a production capacity of over 90,000 tonnes annually, supporting numerous sectors including food, hospitality, water treatment, and manufacturing.
Report Coverage
The research report offers an in-depth analysis based on Gases Type, Application, End-User Industry, Production Method and Delivery Mode. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Australia Industrial Gases Market will strengthen with growing healthcare reliance on oxygen and nitrogen.
- Mining and energy sectors will sustain demand for oxygen, hydrogen, and other specialty gases.
- Food and beverage applications will expand through packaging and carbonation, boosting nitrogen and carbon dioxide usage.
- Hydrogen adoption will accelerate as clean energy projects and national policies advance.
- Technological upgrades in air separation and electrolysis will enhance efficiency and supply reliability.
- Regional demand diversification will rise, with Queensland and South Australia emerging as high-growth areas.
- Digital integration in distribution and monitoring will improve logistics and customer service.
- Strategic mergers and partnerships will increase competition and expand product portfolios.
- Specialty gas applications in electronics and research will broaden beyond traditional industrial use.
- Sustainability pressures will shape investment in eco-friendly production and renewable-aligned gases.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Healthcare Sector Expansion
Australia's growing healthcare infrastructure and rising incidence of chronic respiratory diseases are driving strong demand for medical-grade oxygen, nitrogen, and other specialty gases, making healthcare a core market pillar.
Growth in Food & Beverage Industry
The increasing adoption of industrial gases for food packaging, preservation, and beverage carbonation is fueling market growth, as food exports and consumer demand for packaged goods rise across Australia.
Mining and Energy Sector Demand
Australia's robust mining and energy industries require large volumes of industrial gases such as oxygen for extraction and refining, and hydrogen for emerging clean energy projects, supporting sustained market expansion.
Hydrogen Economy and Clean Energy Initiatives
Government and private investments in hydrogen production, refueling infrastructure, and renewable energy projects are creating new demand pathways for industrial gases, positioning the sector as a key enabler of Australia's energy transition.
Technological Advancements and Digital Integration
The adoption of digital monitoring, automation, and advanced production methods like electrolysis is improving supply chain efficiency, reducing operational costs, and enabling more reliable and sustainable gas delivery.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Australia Industrial Gases market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Australia Industrial Gases market projected to grow between 2025 and 2032?
Which Australia Industrial Gases market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Australia Industrial Gases market?
Who are the leading companies in the Australia Industrial Gases market?
Which region commanded the largest share of the Australia Industrial Gases market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Gases Type
- 1.2.1 Oxygen
- 1.2.2 Nitrogen
- 1.2.3 Hydrogen
- 1.2.4 Carbon Dioxide
- 1.2.5 Acetylene
- 1.2.6 Argon
- 1.2.7 Others
- 1.3 By Application
- 1.3.1 Packaging
- 1.3.2 Coolant
- 1.3.3 Carbonation
- 1.3.4 Cryogenic
- 1.3.5 Cutting & Welding
- 1.3.6 Laboratory
- 1.3.7 Air Separation
- 1.3.8 Others
- 1.4 By End-User Industry
- 1.4.1 Healthcare
- 1.4.2 Manufacturing
- 1.4.3 Metallurgy & Glass
- 1.4.4 Food & Beverages
- 1.4.5 Retail
- 1.4.6 Chemicals & Energy
- 1.4.7 Others
- 1.5 By Production Method
- 1.5.1 Air Separation
- 1.5.2 Steam Methane Reforming (SMR)
- 1.5.3 Electrolysis
- 1.5.4 Partial Oxidation
- 1.5.5 Chemical Reactions
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,359.97 million → 2032: USD 2,435.91 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Industrial Gases Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Industrial Gases Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Industrial Gases Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Industrial Gases Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Industrial Gases Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Industrial Gases Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Industrial Gases Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Industrial Gases Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,359.97 million → 2032: USD 2,435.91 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Industrial Gases Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Gases Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Oxygen
- 12.3.7.2 Nitrogen
- 12.3.7.3 Hydrogen
- 12.3.7.4 Carbon Dioxide
- 12.3.7.5 Acetylene
- 12.3.7.6 Argon
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Packaging
- 12.4.7.2 Coolant
- 12.4.7.3 Carbonation
- 12.4.7.4 Cryogenic
- 12.4.7.5 Cutting & Welding
- 12.4.7.6 Laboratory
- 12.4.7.7 Air Separation
- 12.4.7.8 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Healthcare
- 12.5.7.2 Manufacturing
- 12.5.7.3 Metallurgy & Glass
- 12.5.7.4 Food & Beverages
- 12.5.7.5 Retail
- 12.5.7.6 Chemicals & Energy
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Production Method - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Air Separation
- 12.6.7.2 Steam Methane Reforming (SMR)
- 12.6.7.3 Electrolysis
- 12.6.7.4 Partial Oxidation
- 12.6.7.5 Chemical Reactions
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Industrial Gases End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Industrial Gases Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Industrial Gases Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Industrial Gases Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BOC Australia
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Air Liquide Australia
- 18.4 Linde
- 18.5 Coregas
- 18.6 Supagas
- 18.7 BASF Australia
- 18.8 Wesfarmers Kleenheat Gas
- 18.9 Iwatani Australia
- 18.10 Messer & Opie
- 18.11 Air Products & Chemicals, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

