
Market Overview
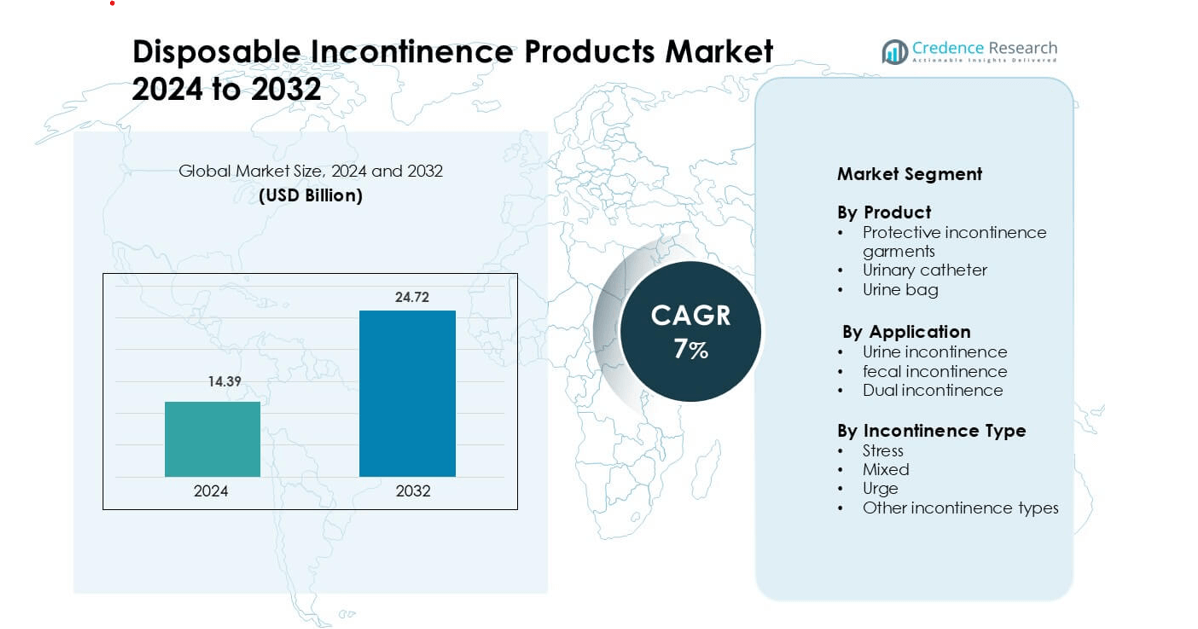
Disposable Incontinence Products Market was valued at USD 14.39 billion in 2024 and is anticipated to reach USD 24.72 billion by 2032, growing at a CAGR of 7 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Disposable Incontinence Products Market Size 2024 | USD 14.39 billion |
| Disposable Incontinence Products Market, CAGR | 7% |
| Disposable Incontinence Products Market Size 2032 | USD 24.72 billion |
Major participants in the Disposable Incontinence Products Market include FUBURG, BD, Hollister, Attends, B Braun, Cardinal Health, ABENA, Essity, Coloplast, and ConvaTec. These companies focus on high-absorbency cores, breathable fabrics, odor-control layers, and skin-friendly materials to support long wear and reduce irritation. Product portfolios span adult diapers, pads, liners, and pull-up underwear used in hospitals, nursing homes, and home-care settings. North America leads the market with 37% share, driven by a large aging population, strong insurance reimbursement, and wide availability of premium incontinence solutions through retail, pharmacies, and e-commerce channels.
Market Insights
- The Disposable Incontinence Products Market reached USD 14.39 billion in 2024 and is projected to grow at a 7% CAGR during the forecast period.
- Demand increases as hospitals and home-care providers use high-absorbency diapers and pads for aging patients and post-surgery care; adult diapers remain the largest segment with 46% share due to strong adoption in elderly care.
- Trends include breathable fabrics, odor-neutralizing technology, gender-specific designs, and biodegradable product lines to improve comfort and sustainability.
- Competition grows as FUBURG, Essity, Hollister, B Braun, CardinalHealth, Coloplast, and ConvaTec expand product portfolios and partner with pharmacies and online retailers for wider distribution.
- North America leads the market with 37% share, supported by advanced healthcare infrastructure and strong insurance coverage, while Europe and Asia Pacific show rapid growth due to rising geriatric populations and expanding home-care usage.
Market Segmentation Analysis:
By Product
Protective incontinence garments hold the dominant position with 46% share, driven by strong adoption in elder care, post-surgery recovery, and home-care settings. These products offer high absorption, odor control, and skin-safe materials, making them suitable for long wear. Hospitals and long-term care facilities use pull-ups, adult diapers, and pads to reduce bedding changes and improve hygiene. Urinary catheters and urine bags follow, supporting patients with mobility issues or surgical recovery needs. As aging populations rise, demand for discreet, comfortable garments continues to drive the product segment forward.
- For instance, Essity’s TENA ProSkin line integrates ConfioAir breathable technology and super-absorbent polymers, proven through clinical studies to reduce skin irritation and maintain normal skin pH.
By Application
Urine incontinence leads this segment with 67% share, supported by a large patient base tied to aging, childbirth complications, chronic diseases, and mobility limitations. Hospitals and caregivers rely on disposable diapers, pads, and liners to prevent leakage and maintain hygiene. Fecal incontinence products are used in long-term care and severe gastrointestinal disorders, while dual incontinence solutions support bedridden and post-stroke patients. Growing awareness, improved product design, and better comfort features strengthen the dominance of urine incontinence applications.
- For instance, Essity’s TENA Slip Maxi offers documented absorption capacity exceeding 2,000 milliliters, verified through ISO standard absorbency tests, ensuring leakage protection for extended wear.
By Incontinence Type
Stress incontinence dominates with 41% share, driven by high prevalence among elderly women, post-menopausal patients, and individuals with weakened pelvic muscles. Protective garments and pads remain the preferred choice due to their comfort, discreet fit, and effective absorption. Urge incontinence follows, supported by demand from patients with neurological or bladder control issues. Mixed incontinence solutions serve users with combined symptoms, while other types remain niche. Rising awareness, improved product materials, and the shift toward home-based care support continued growth in stress incontinence products.
Key Growth Drivers
Rising Geriatric Population and Home-Care Adoption
The global rise in elderly populations drives sustained demand for disposable incontinence products. Age-related bladder weakness, dementia, reduced mobility, and post-surgery recovery make adult diapers, pads, and pull-ups essential in long-term care. Families increasingly prefer home-care over institutional treatment, boosting sales through pharmacies and online channels. Products with breathable layers, odor control, and skin-friendly materials reduce rashes and improve comfort during extended wear. Hospitals and nursing homes rely on protective garments to improve hygiene, reduce linen changes, and protect patients with limited mobility. As life expectancy increases and chronic diseases rise, adoption continues to accelerate across both developed and emerging markets.
- For instance, Cardinal Health serves more than 100,000 locations and provides medical products to over 75% of hospitals in the United States.
Expansion of Healthcare Infrastructure and Post-Surgical Use
Improved hospital capacity and investments in nursing homes, rehabilitation centers, and assisted living facilities strengthen market growth. Patients recovering from prostate surgery, childbirth complications, or urological disorders rely on disposable incontinence pads and garments. Healthcare providers choose high-absorbency, leak-proof solutions to maintain hygiene and prevent skin infections. Catheters and urine bags support bedridden patients and critical care units. Insurance reimbursement in developed countries further boosts adoption. Growth in outpatient surgeries and minimal-invasive procedures extends demand, as many patients require temporary incontinence support during recovery.
- For instance, more than 100 million urinary catheters, including Foley catheters, are sold or used globally each year. This is a well-established statistic in medical literature.
Product Innovation and Comfort-Focused Design
Manufacturers compete through innovations that improve comfort, discretion, and skin protection. Super-absorbent polymers, odor-lock barriers, and moisture-wicking surfaces reduce irritation and leakage. Gender-specific designs, body-fit shaping, and ultra-thin products help users maintain confidence during daily activities. Biodegradable and reduced-plastic variants respond to sustainability expectations. Subscription models and discreet delivery services make purchasing easier for home-care users. As awareness increases and stigma declines, premium incontinence products gain market share among active adults seeking comfortable, long-wear solutions.
Key Trends & Opportunities
Sustainable and Eco-Friendly Product Development
Environmental concerns push manufacturers to reduce plastic content and improve biodegradability. Companies invest in recyclable packaging, organic top sheets, and reusable components while maintaining absorbency and strength. Healthcare facilities show growing interest in eco-certified supplies for hygiene compliance. This trend also boosts demand for premium products among users looking for skin-safe, chemical-free alternatives. Brands offering greener solutions gain a competitive advantage and stronger consumer loyalty.
- For instance, ABENA’s Abri-Flex and Abri-San Premium products are produced using FSC-certified pulp and carry the Nordic Swan Ecolabel, with documented reductions in energy and water consumption during manufacturing.
Growth of E-Commerce, Subscription Services, and Discreet Delivery
Digital platforms make purchasing easier for users who prefer privacy and home delivery. Subscription models ensure regular restocking of pads, liners, and diapers without pharmacy visits. Online reviews and comparison tools help customers find products with better fit, odor control, and absorbency. As mobile shopping expands in emerging markets, companies partner with e-commerce and medical supply platforms to serve a wider customer base.
- For instance, Coloplast is a global company that develops medical devices and services for intimate healthcare needs (ostomy, continence, etc.). Its products currently help over 2 million people around the world in total.
Key Challenges
Skin Irritation, Disposal Issues, and Environmental Concerns
Although products are more advanced, long-term use can cause rashes, dermatitis, or discomfort if not designed with breathable and skin-safe materials. High usage also creates large volumes of non-biodegradable waste, raising environmental concerns for households and healthcare facilities. Regulations on waste management may increase costs for producers and buyers. These challenges push manufacturers to balance performance with sustainability and dermatological safety.
Stigma, Limited Awareness, and Price Sensitivity in Developing Regions
Social stigma prevents many patients from seeking incontinence support, especially in emerging markets. Limited awareness, low reimbursement, and high product cost restrict adoption. Hospitals often prioritize basic hygiene supplies over premium solutions. Manufacturers must invest in education, affordable product ranges, and clinical endorsements to expand adoption. Overcoming these barriers is essential to unlock long-term growth in underpenetrated regions.
Regional Analysis
North America
North America holds 37% share, supported by advanced healthcare infrastructure, strong insurance reimbursement, and high awareness of incontinence management. The U.S. leads due to large geriatric populations, wide retail availability, and strong home-care adoption. Hospitals and nursing homes demand high-absorbency diapers, pads, and pull-ups to maintain hygiene and reduce linen changes. Manufacturers focus on breathable fabrics, odor-control layers, and dermatologically tested products for long wear. E-commerce and subscription services further strengthen adoption among home users. Growing chronic diseases and post-surgical recovery cases continue to push steady demand across the region.
Europe
Europe accounts for 31% share, led by Germany, the U.K., and France, where elderly care programs and well-established reimbursement policies support product usage. Nursing homes and assisted-living centers rely on high-absorbency solutions for long-term patients. Sustainability expectations drive demand for biodegradable pads and reduced-plastic packaging. Strong presence of hygiene product manufacturers enables wide product availability. Awareness campaigns and government support improve early diagnosis and treatment of incontinence. Rising preference for discreet, comfortable products encourages growth in premium disposable segments.
Asia Pacific
Asia Pacific holds 23% share and remains the fastest-growing region due to large aging populations, expanding healthcare access, and rising home-care spending. Japan leads adoption with strong demand for adult diapers and pull-ups, while China and India show rapid growth as awareness improves. Local and global brands expand retail and online distribution to reach urban and rural users. Hospitals adopt disposable incontinence products to reduce infection risk and maintain hygiene. Increasing chronic illnesses and mobility-related disorders further support market momentum.
Latin America
Latin America captures 6% share, driven by expanding healthcare systems in Brazil, Mexico, and Argentina. Rising cases of diabetes, obesity, and post-surgical recovery create higher demand for adult diapers and pads. Pharmacy chains and online platforms help improve product availability. Cost sensitivity remains a barrier to premium options, but awareness campaigns gradually improve acceptance. Growth in private hospitals and elderly-care services is expected to support long-term adoption.
Middle East & Africa
Middle East & Africa hold 3% share, supported by increasing use in hospitals, maternal care, and chronic disease treatment. GCC nations show higher adoption due to better healthcare spending and import of premium incontinence products. Africa remains a developing market where limited awareness and affordability challenges restrict usage. However, urbanization, rising life expectancy, and expansion of retail pharmacies are improving market accessibility. Over time, improved healthcare infrastructure and home-care services will drive gradual growth across the region.
Market Segmentations:
By Product
- Protective incontinence garments
- Urinary catheter
- Urine bag
By Application
- Urine incontinence
- Fecal incontinence
- Dual incontinence
By Incontinence Type
- Stress
- Mixed
- Urge
- Other incontinence types
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Disposable Incontinence Products Market includes global healthcare brands and specialized hygiene manufacturers focused on high-absorbency, skin-safe, and discreet products. Companies such as FUBURG, BD, Hollister, Attends, B Braun, CardinalHealth, ABENA, Essity, Coloplast, and ConvaTec compete through innovation in fluid-locking polymers, breathable materials, and odor-control technology. Product lines span adult diapers, pads, liners, and protective underwear designed for hospitals, long-term care centers, and home-care users. Firms invest in ergonomic designs, dermatologically tested surfaces, and gender-specific fits to increase comfort and leakage protection. Sustainability also reshapes competition, as manufacturers introduce biodegradable fabrics and reduced-plastic packaging. Growing partnerships with pharmacies, online retailers, and healthcare providers support wider product access and subscription-based purchasing models. As aging populations rise and home-care adoption expands, companies with strong distribution networks and clinically validated products gain a competitive advantage.
Key Player Analysis
Recent Developments
- In 2024, Hollister Named a new CEO overseeing portfolios including Continence Care. Signals leadership focus across continence product lines.
- In March 2024, BD: DME MACs revised PureWick coding and billing guidance. Crosswalked the system from HCPCS K1006 to E2001 effective Jan 1, 2024.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Incontinence Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise as aging populations and home-care services expand worldwide.
- Product innovation will focus on thinner, breathable, and skin-friendly designs for long wear.
- Sustainable and biodegradable incontinence products will gain stronger market preference.
- E-commerce and subscription models will drive recurring sales and discreet purchasing.
- Hospitals and nursing homes will continue shifting from reusable to disposable hygiene solutions.
- Growth in minimally invasive surgeries will increase short-term incontinence product usage.
- Premium products with odor control, fast absorption, and leak barriers will gain market share.
- Manufacturers will invest in gender-specific and body-contoured designs for better comfort.
- Awareness campaigns will reduce stigma and encourage more users to seek medical support.
- Asia Pacific will remain the fastest-growing region with rising healthcare access and elderly care.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Disposable Incontinence Products Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Disposable Incontinence Products Market projected to grow between 2025 and 2032?
Which Disposable Incontinence Products Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Disposable Incontinence Products Market?
Who are the leading companies in the Disposable Incontinence Products Market?
Which region commanded the largest share of the Disposable Incontinence Products Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14.39 billion → 2032: USD 24.72 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Disposable Incontinence Products Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Disposable Incontinence Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Disposable Incontinence Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Disposable Incontinence Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Disposable Incontinence Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Disposable Incontinence Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Disposable Incontinence Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Disposable Incontinence Products Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14.39 billion → 2032: USD 24.72 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Disposable Incontinence Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Disposable Incontinence Products Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Disposable Incontinence Products Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Disposable Incontinence Products Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

