
Market Overview
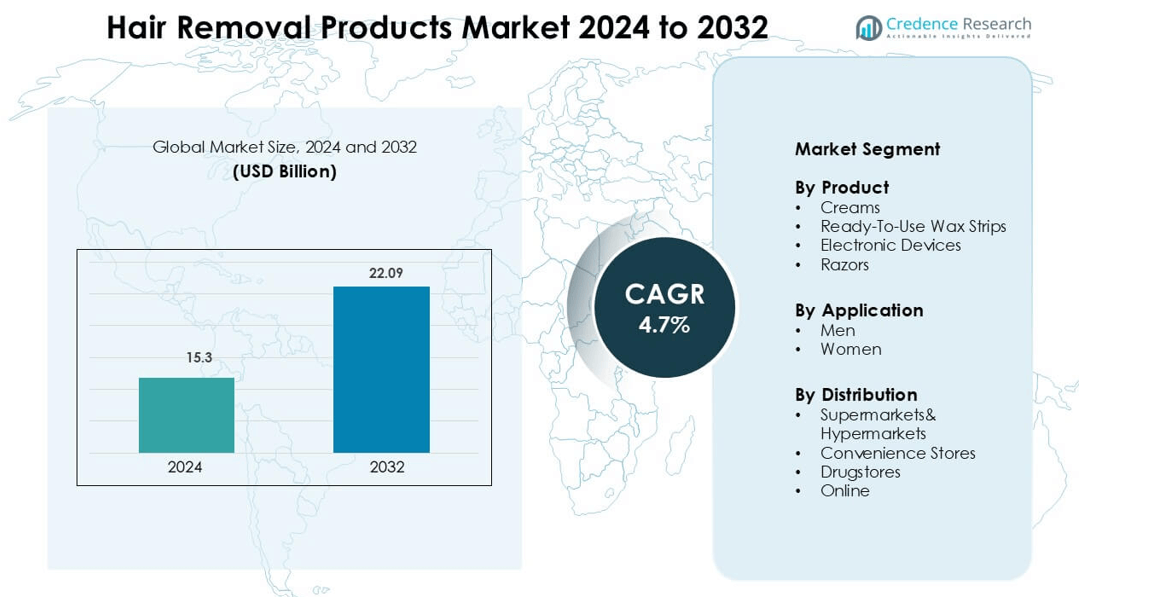
Hair Removal Products Market was valued at USD 15.3 billion in 2024 and is anticipated to reach USD 22.09 billion by 2032, growing at a CAGR of 4.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hair Removal Products Market Size 2024 | USD 15.3 billion |
| Hair Removal Products Market, CAGR | 4.7% |
| Hair Removal Products Market Size 2032 | USD 22.09 billion |
The Hair Removal Products Market includes major players such as Procter & Gamble, Philips Personal Care B.V., Reckitt Benckiser Group PLC, Church & Dwight Co., Inc., Emjoi Inc., Sally Hansen, SI&D (Aust) Pty Ltd, Helios Lifestyle Private Limited, Vijohnkart.com, and Revitol. These companies compete through sensitive-skin creams, ready-to-use wax strips, advanced razors, and rechargeable grooming devices. Many brands highlight natural ingredients, dermatologist-tested formulations, and reusable tools to increase customer loyalty. North America leads the global market with 36% share, driven by strong retail presence, high grooming awareness, and rapid adoption of premium and at-home hair removal solutions.
Market Insights
- The Hair Removal Products Market is valued at USD 15.3 billion in 2024 and is set to reach USD 22.09 billion by 2032, growing at a 4.7 % CAGR during the forecast period.
- Rising preference for at-home grooming solutions drives demand for creams, ready-to-use wax strips, razors, and compact electronic devices that offer fast and affordable results.
- Product innovation remains strong, with brands launching sensitive-skin formulas, natural ingredients, moisturizing wax blends, and rechargeable devices that ensure smoother and longer-lasting outcomes.
- The market is competitive, with global and regional players focusing on packaging, price differentiation, dermatologically tested options, and online promotions, while substitutes like salon waxing and laser treatments pose a restraint.
- North America leads with 36% market share due to strong retail presence and high grooming spending, while creams hold the dominant product segment share, supported by easy use, low cost, and growing adoption among both women and an expanding male customer base.
Market Segmentation Analysis:
By Product
Creams, ready-to-use wax strips, electronic devices, and razors form the key categories. Creams hold the largest share due to easy use, quick results, and low cost. Demand rises in urban areas where consumers prefer painless options and chemical formulations that suit sensitive skin. Advertising and frequent product launches support wider reach. Ready-to-use strips grow as users want longer-lasting outcomes at home. Electronic devices also gain attention because of reusable features, yet high price limits mass use. Razors remain common among budget users, but shifting interest toward smoother, irritation-free results keeps creams in the leading position.
- For instance, Veet, marketed by Reckitt Benckiser Group PLC, sells ready-to-use wax strips tested for precision hair pull-out lengths of 1.5 mm or lower, allowing cleaner results on short hair according to brand guidelines.
By Application
Women dominate the market as they account for the highest consumption of hair removal creams, wax strips, and razors across regular grooming routines. Frequent use, preference for smoother skin, and rising beauty awareness support their leading share. Social media influence and personal care trends further boost product uptake. Men show steady growth due to expanding grooming habits and rising sales of electronic trimmers and razors. Brands introduce sensitive-skin creams and faster hair removal options tailored for male users. However, women continue to lead because of broader product acceptance and higher repeat purchases.
- For instance, Emjoi markets the Emjoi eRase e60 epilator with 60 tweezer heads documented to remove hair as short as 0.3 mm, a feature widely promoted for women seeking smoother results.
By Distribution Channel
Supermarkets and hypermarkets lead the segment as consumers prefer in-store buying, instant product access, and availability of multiple brands in one place. Promotions, trial packs, and visibility on shelves drive higher sales for creams and wax strips. Drugstores also attract users seeking dermatology-backed labels and expert recommendations. Convenience stores offer quick restocking for razors and small packs. Online channels grow fastest as buyers look for privacy, discounts, subscription packs, and wider brand availability. Despite this growth, supermarkets and hypermarkets dominate due to strong retail presence and trusted product selection.
Key Growth Drivers
Growing Preference for At-Home Grooming Solutions
The Hair Removal Products Market benefits from strong demand for convenient, at-home grooming solutions. Busy lifestyles and higher self-care awareness push consumers to choose creams, ready-to-use wax strips, razors, and small electronic tools instead of salon visits. These products save time, reduce long-term grooming cost, and provide privacy to users who prefer personal care at home. Manufacturers promote smooth-skin outcomes, painless formulas, and fast application to increase adoption. Subscription kits, combo packs, and dermatologically tested variants also improve repeat purchases. The rise of e-commerce and doorstep delivery strengthens access to both premium and budget products, encouraging wider consumption across age groups and income levels.
- For instance, In May 2017, Gillette launched "Gillette on Demand," an on-demand razor and blade replenishment service in the U.S.
Strong Pace of Product Innovation and Skin-Safe Formulations
Product innovation acts as a key growth driver because users prioritize safety and comfort while removing hair. Companies invest in gentle chemicals, sensitive-skin creams, and peel-off wax strips that reduce redness or irritation. Electronic devices now include precision tips, rechargeable units, and multi-use attachments, making them suitable for various body areas. Brands also produce paraben-free and dermatology-certified options to gain trust. Clear packaging, ingredient transparency, and skin-type targeting further improve acceptance. This focus on new technology and safe ingredients expands the consumer base and shifts users away from traditional shaving toward more effective alternatives that promise smoother and longer-lasting results.
- For instance, Veet Pure line depilatory creams are listed as free from parabens, dyes, and mineral oils, with formulas tested for sensitive skin on company product labels.
Rising Grooming Demand Among Men
Men form a growing customer group in the Hair Removal Products Market as personal care routines become more common. Beard shaping, body grooming, and hygiene-focused shaving influence demand for razors, trimmers, hair removal creams, and waxing strips. Sports culture, gym-focused lifestyles, and media influence also increase use across younger consumers. Brands market quick-acting, non-irritating formulas with stronger fragrances to suit male users. Barbers and salons encourage retail purchases of grooming products for home use. As acceptance grows in urban areas, companies launch gender-specific marketing campaigns and dedicated product lines, supporting a steady rise in male grooming adoption.
Key Trends and Opportunities
Shift Toward Skin-Friendly and Organic Ingredients
A major trend in the Hair Removal Products Market is the transition to organic, natural, and sensitive-skin formulations. Consumers want safer ingredients, especially those who experience rash, redness, or ingrown hair from harsh chemical options. Brands introduce aloe vera, chamomile, shea butter, and toxin-free formulas to target concerned users. Wax strips and creams now focus on moisturizing effects and post-care results. Clean-label marketing and dermatologist approvals help build trust. This trend opens opportunities for premium pricing and loyal customer groups that value wellness-linked personal care.
- For instance, Sally Hansen Hair Remover Wax Strip Kit lists vitamin E and after-use Azulene Oil or finishing wipes extract in moisturizing agents on its packaging.
Rapid Adoption of Online Retail and Subscription Services
Online platforms create strong opportunities, as users compare reviews, explore niche brands, and buy products discreetly. Digital discounts, seasonal deals, and doorstep delivery increase purchasing frequency. Subscription services allow regular restocking of razors, strips, and creams, supporting long-term customer retention. Social media influencers, grooming tutorials, and product trials further raise awareness. As digital payment and logistics improve, small brands scale faster and reach markets where retail distribution is limited.
- For instance, Gillette’s shave subscription service in the United States surpassed 100,000 active members according to Procter & Gamble disclosures, providing scheduled blade replenishment.
Key Challenges
High Risk of Skin Sensitivity and Product Reactions
The market faces challenges due to potential side effects linked with certain creams, wax strips, and electronic tools. Skin irritation, allergy, burns, and redness discourage repeat use among sensitive users. Negative experiences lead some consumers back to shaving or professional salon treatments. Companies must test products rigorously, offer hypoallergenic formulas, and provide clear usage guidelines to reduce safety concerns. Regulatory approvals and dermatologist certifications become essential to building trust. Despite efforts, the perception of risk remains a key barrier in attracting new users.
Presence of Strong Substitutes and Salon-Based Services
At-home hair removal products compete directly with salon waxing, laser treatments, and professional grooming services that promise longer-lasting results. Growing interest in laser hair reduction shifts some consumers away from frequent purchase of creams and strips. Professional services also appeal to users who want expert handling and are willing to pay more. To compete, brands must highlight convenience, affordability, and improved results from advanced formulas and devices. While demand remains strong, long-term growth relies on continuous innovation to retain users against improving salon technologies.
Regional Analysis
North America
North America holds the largest share of the Hair Removal Products Market, accounting for nearly 36% of total revenue. Consumers prefer creams, razors, and ready-to-use wax strips for fast at-home grooming. Premium brands promote sensitive-skin formulas, refillable razors, and subscription packs that increase repeat purchases. Strong retail networks across supermarkets, drugstores, and online channels improve product availability. Beauty influencers and rising male grooming trends support steady demand. High awareness of skincare and quick adoption of new products keep North America in the leading position.
Europe
Europe represents roughly 28% of the market share, driven by strong demand for high-quality and skin-safe products. Users prefer wax strips and creams that offer longer-lasting and irritation-free results. Strict cosmetic regulations encourage safer, certified formulations, increasing trust in branded products. Sustainable packaging, organic ingredients, and dermatologist-approved labels attract premium buyers. Well-developed supermarket chains and fast-growing e-commerce channels support product reach. Growing acceptance of male grooming further drives adoption, helping Europe maintain a strong market position.
Asia-Pacific
Asia-Pacific holds nearly 24% of the global share and shows the fastest growth rate among regions. Rising urban populations, improved income levels, and social media influence encourage frequent grooming habits. Affordable razors and depilatory creams lead sales, while electronic devices gain interest in urban areas. India, China, Japan, and South Korea contribute the largest volumes due to high young consumer populations. Online marketplaces offer discounts, brand variety, and doorstep delivery, which increase product penetration. As awareness rises, Asia-Pacific continues to capture a growing share each year.
Latin America
Latin America accounts for about 7% of the market share. Brazil and Mexico drive demand, supported by strong grooming culture and frequent use of wax strips and razors. Budget-friendly products dominate, while premium creams appeal to customers seeking smoother and irritation-free results. Salons influence brand choices, and many consumers buy products recommended by professionals. Growth in online shopping improves access to international brands. Despite price sensitivity, stable beauty spending and rising urban populations support consistent market demand.
Middle East & Africa
The Middle East & Africa region holds close to 5% of the market share. Rising beauty consciousness among women and higher availability of branded products drive demand. Climate conditions push consumers to prefer skin-friendly creams and soothing wax formulas. Urban shoppers often purchase through supermarkets and pharmacies, while online platforms attract younger users. Grooming interest among men also increases razor and trimmer usage. Although premium adoption remains limited due to price constraints, gradual retail expansion supports steady growth potential.
Market Segmentations:
By Product
- Creams
- Ready-To-Use Wax Strips
- Electronic Devices
- Razors
By Application
- Men
- Women
By Distribution
- Supermarkets& Hypermarkets
- Convenience Stores
- Drugstores
- Online
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Hair Removal Products Market features a mix of multinational corporations, regional manufacturers, and fast-growing direct-to-consumer brands. Companies invest in product innovation, dermatologist-tested ingredients, and sensitive-skin formulations to strengthen customer trust. Creams and wax strips remain highly competitive, with brands focusing on pain-free application, moisturizing elements, and long-lasting smoothness. Razor manufacturers push reusable handles, eco-friendly blades, and subscription models that increase repeat sales. Electronic hair removal devices gain ground through rechargeable units and multi-area attachments. Marketing on social media, endorsements, and influencer campaigns raise visibility among younger buyers. E-commerce platforms allow smaller brands to expand quickly with trial packs and value bundles. Major players also compete on packaging, fragrance, natural ingredients, and after-care benefits. As men adopt grooming routines, companies launch dedicated product lines with faster action and strong fragrances. Continuous innovation, pricing competition, and digital marketing define the current industry rivalry.
Key Player Analysis
- Procter & Gamble
- SI&D (Aust) Pty Ltd
- Philips Personal Care B.V.
- Sally Hansen
- Helios Lifestyle Private Limited.
- Church & Dwight Co., Inc.
- com
- Emjoi, Inc.
- Reckitt Benckiser Group PLC
- Revitol
Recent Developments
- In October 2025, Philips Personal Care B.V. launched OneBlade Intimate in India, a unisex device for sensitive areas. Philips positions it for Gen Z, citing high intimate-grooming adoption. Early testing showed strong intent to switch.
- In March 2025, Procter & Gamble (Gillette Venus): Rolled out upgrades across the Venus lineup and partnered with the WTA. The push highlights shave, trim, and style options for diverse needs. Campaign features pro tennis athletes.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Distribution and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for at-home hair removal products will increase as users seek privacy and convenience.
- Sensitive-skin and chemical-free formulations will gain higher customer acceptance.
- Electronic grooming devices will see rising adoption due to reusable and long-lasting performance.
- Subscription razor and wax refill models will improve brand loyalty and repeat purchases.
- Male grooming products will expand as more men adopt regular body and facial hair care.
- Online sales will grow faster than retail stores because of discounts, reviews, and wider product choices.
- Organic and eco-friendly packaging will attract buyers focused on sustainability.
- Brands will focus on multi-benefit creams and wax strips that reduce irritation and offer smoother results.
- Regional brands will compete strongly with global players through price-friendly products.
- Innovation in post-care products such as soothing gels and anti-ingrown solutions will strengthen overall sales

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hair Removal Products Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Hair Removal Products Market projected to grow between 2025 and 2032?
Which Hair Removal Products Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Hair Removal Products Market?
Who are the leading companies in the Hair Removal Products Market?
Which region commanded the largest share of the Hair Removal Products Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15.3 Billion → 2032: USD 22.09 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hair Removal Products Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hair Removal Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hair Removal Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hair Removal Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hair Removal Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hair Removal Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hair Removal Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hair Removal Products Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15.3 Billion → 2032: USD 22.09 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hair Removal Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hair Removal Products Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Hair Removal Products Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Hair Removal Products Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

