
Market Overview:
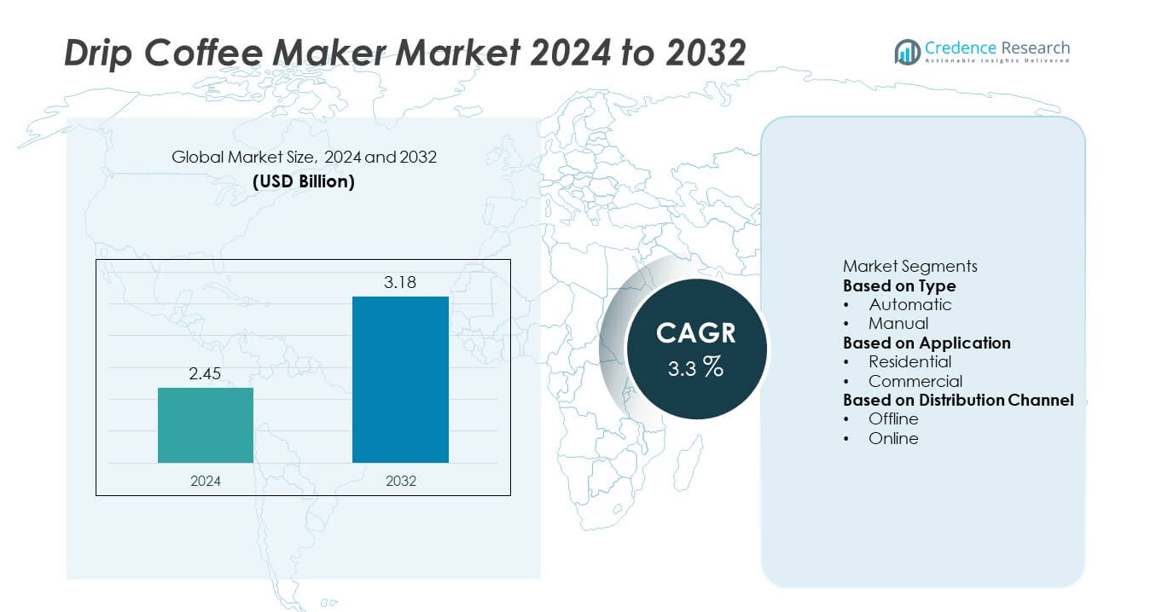
The drip coffee maker market was valued at USD 2.45 billion in 2024 and is projected to reach USD 3.18 billion by 2032, growing at a CAGR of 3.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Drip Coffee Maker Market Size 2024 | USD 2.45 billion |
| Drip Coffee Maker Market, CAGR | 3.3% |
| Drip Coffee Maker Market Size 2032 | USD 3.18 billion |
The drip coffee maker market is dominated by major players such as Electrolux AB, illycaffè S.p.A., GROUPE SEB UK, Ltd., BSH Hausgeräte GmbH, Spectrum Brands, Gruppo Cimbali S.p.A., Morphy Richards India, Espresso Supply, Inc., De’Longhi Appliances S.r.l., and Koninklijke Philips N.V. These companies lead through product innovation, efficient brewing technology, and strong global distribution networks. Continuous advancements in automatic and smart coffee machines enhance their competitive edge. North America remains the leading region with a 38% market share in 2024, driven by high coffee consumption and household adoption, followed by Europe with 32%, supported by premium home appliance demand and sustainability-focused consumers.
Market Insights
- The drip coffee maker market was valued at USD 2.45 billion in 2024 and is projected to reach USD 3.18 billion by 2032, growing at a CAGR of 3.3% during the forecast period.
- Growth is driven by rising demand for convenient, programmable, and energy-efficient home brewing appliances, fueled by increasing coffee consumption and lifestyle modernization.
- Key trends include the adoption of smart, Wi-Fi-enabled drip machines, sustainability-focused designs, and growing popularity of compact models suited for urban households.
- The market is competitive, with leading players such as Electrolux AB, De’Longhi Appliances S.r.l., BSH Hausgeräte GmbH, and GROUPE SEB UK, Ltd. focusing on innovation, digital integration, and eco-friendly manufacturing.
- North America dominated with a 38% share, followed by Europe at 32% and Asia-Pacific at 21%; by type, automatic models led with a 64% share, while the residential segment accounted for 58% of total market demand.
Market Segmentation Analysis:
By Type
The automatic segment dominated the drip coffee maker market with a 64% share in 2024. Its leadership is driven by rising consumer preference for convenience, consistency, and programmable brewing features. Automatic machines offer time-saving benefits, appealing to busy households and small offices. The availability of smart models with digital controls, thermal carafes, and adjustable brew strength further enhances popularity. Manufacturers are also integrating energy-efficient systems and compact designs, strengthening adoption across both developed and emerging markets.
- For instance, the De'Longhi All-in-One Combination Coffee Maker & Espresso Machine (COM532M) features a dual heating system, a large 47-ounce water reservoir for the espresso side, and a digital touchscreen. The machine supports customizable strength control and includes a 24-hour programmable timer.
By Application
The residential segment accounted for a 58% share in 2024, making it the leading application area. Increasing home coffee consumption and lifestyle shifts toward premium brewing experiences drive this dominance. Consumers are investing in drip coffee makers to enjoy café-style beverages at home. The rise of remote working has also boosted daily household coffee preparation. Compact, easy-to-clean, and aesthetically designed drip coffee makers are gaining traction, especially in urban homes where convenience and modern design are key purchasing factors.
- For instance, Koninklijke Philips N.V. launched the Café GAIA Drip Coffee Maker equipped with a 1.2-litre glass jug and 1000-watt heating element. The system brews up to 10 cups in 10 minutes, maintaining a stable extraction temperature of 93 °C. The model’s auto shut-off function after 30 minutes of inactivity improved household energy efficiency across European markets.
By Distribution Channel
The offline segment held a 67% share in 2024, remaining the dominant sales channel for drip coffee makers. Supermarkets, specialty stores, and brand-exclusive outlets offer consumers direct product testing and demonstrations, influencing purchase decisions. Strong retail presence and promotional discounts enhance offline sales globally. However, manufacturers are increasingly expanding online distribution through e-commerce platforms to capture younger consumers and digital shoppers. The combination of in-store engagement and digital convenience supports balanced growth across both channels.
Key Growth Drivers
Rising Demand for Convenient Home Brewing Solutions
Increasing consumer preference for convenience and premium home-brewed coffee is driving demand for drip coffee makers. Busy lifestyles and the growing remote work culture have boosted daily coffee consumption at home. Automatic drip machines with programmable timers and customizable brewing options appeal to users seeking effortless preparation. Manufacturers are launching compact, easy-to-use models catering to small households and apartments, further expanding residential adoption.
- For instance, Morphy Richards India introduced its Brew Blend coffee maker equipped with a 600-watt heating system and 6-cup brewing capacity. It features an anti-drip function that prevents spillage during serving and a reusable filter design.
Growing Popularity of Specialty and Premium Coffee
Consumers are shifting toward specialty blends and high-quality brewing, enhancing the appeal of advanced drip coffee makers. Features like temperature control, adjustable brew strength, and multi-cup brewing are gaining traction. The availability of machines designed for single-origin and artisanal coffee promotes at-home café experiences. Rising disposable incomes and the trend toward premium lifestyle appliances further accelerate market growth, especially in urban regions.
- For instance, Gruppo Cimbali acquired a majority stake in Slayer Espresso in 2017 to expand its position in the high-end espresso segment. This strategic move allowed Slayer, known for its handcrafted machines and customizable features, to leverage Gruppo Cimbali's manufacturing capabilities to reach a broader market.
Expansion of Commercial Coffee Consumption
The commercial segment, including offices, cafés, and quick-service restaurants, is increasingly adopting drip coffee makers for high-volume brewing. Consistent output, reliability, and low maintenance make these machines ideal for professional settings. Businesses are investing in energy-efficient and automated units to reduce operational costs. The hospitality sector’s recovery and growing demand for quick, freshly brewed coffee options in workplaces continue to support segment expansion globally.
Key Trends & Opportunities
Integration of Smart and Connected Features
Manufacturers are incorporating IoT and Wi-Fi connectivity into drip coffee makers, allowing users to control brewing remotely via mobile apps. Smart features such as voice commands, scheduling, and maintenance alerts enhance convenience and personalization. These innovations appeal to tech-savvy consumers seeking seamless smart-home integration. The trend also enables brands to differentiate their products and strengthen premium positioning in the market.
- For instance, Electrolux AB offers smart home compatibility for certain appliances like ovens and air conditioners, which can be controlled remotely through apps such as the Electrolux App, and are compatible with Google Assistant and Alexa.
Sustainability and Energy Efficiency Focus
Growing awareness of sustainability is pushing manufacturers to design energy-efficient, recyclable, and eco-friendly drip coffee makers. Consumers increasingly prefer models with reusable filters, reduced plastic use, and auto shut-off functions. Companies are also adopting environmentally responsible production practices and packaging. This shift toward green innovation aligns with global environmental goals and strengthens brand reputation among eco-conscious buyers.
- For instance, Groupe SEB UK Ltd., under its Tefal brand, offers an Evidence Eco-Design bean-to-cup machine that incorporates recycled materials into its components. This model includes an auto power-off function. Tefal has also introduced other eco-design products, such as its Renew range of cookware made from 100% recycled aluminum.
Key Challenges
Intense Competition from Alternative Brewing Methods
The drip coffee maker market faces strong competition from single-serve pod machines, espresso makers, and French presses. These alternatives attract consumers seeking faster or more customizable brewing experiences. Changing consumer preferences toward specialty coffee formats may limit demand for traditional drip machines. To remain competitive, manufacturers must focus on innovation, smart features, and aesthetic design enhancements.
High Maintenance and Limited Awareness in Emerging Markets
Maintenance requirements and low product awareness in developing regions restrain broader adoption. Consumers often perceive drip coffee makers as complex or expensive compared to manual brewing tools. Limited brand presence and inadequate after-sales support further affect demand. Educating users about convenience, cost-effectiveness, and performance benefits will be crucial to expanding penetration in untapped markets.
Regional Analysis
North America
North America held the largest 38% share in 2024, supported by a strong coffee culture and high household appliance penetration. The U.S. dominates the region, driven by the popularity of home brewing and advanced automatic coffee makers. Demand for programmable and smart-enabled drip machines continues to rise, particularly among working professionals. Major brands are launching premium models with thermal carafes and eco-friendly designs. Retail chains and online platforms further enhance accessibility, sustaining market leadership across residential and small commercial segments.
Europe
Europe accounted for a 32% share in 2024, driven by established café culture and growing adoption of premium home brewing systems. Germany, France, and the U.K. represent the key markets, emphasizing high-quality design and energy efficiency. Consumers prefer compact, stylish models with programmable brewing and temperature control functions. Rising demand for sustainable and recyclable appliances aligns with strict EU energy regulations. Continuous innovation and strong distribution networks from leading global brands support steady market expansion in both household and hospitality sectors.
Asia-Pacific
Asia-Pacific captured a 21% share in 2024, emerging as the fastest-growing regional market. Rising urbanization, disposable incomes, and exposure to Western coffee culture are fueling adoption across China, Japan, and South Korea. Growing café chains and expanding office spaces drive demand for commercial-grade drip machines. Consumers increasingly prefer mid-priced models offering automation and modern design. Manufacturers are focusing on localized marketing and energy-efficient features to attract new users. Expanding e-commerce platforms and rapid lifestyle changes further accelerate regional growth.
Latin America
Latin America accounted for a 6% share in 2024, supported by increasing coffee consumption and a strong café tradition. Brazil and Mexico dominate regional demand due to their established coffee production and growing domestic consumption. Rising middle-class income and the availability of affordable automatic machines contribute to steady adoption. However, limited awareness of premium features and higher costs of imported models pose challenges. Local distribution partnerships and promotional campaigns are helping international brands strengthen their foothold in the region.
Middle East & Africa
The Middle East & Africa held a 3% share in 2024, reflecting gradual adoption of modern brewing appliances. Urban centers such as the UAE, Saudi Arabia, and South Africa are driving demand through expanding hospitality sectors and café chains. Consumers increasingly favor convenient and stylish coffee makers suited for office and household use. However, limited product availability and price sensitivity in several African markets restrict widespread adoption. Growing café culture, tourism, and entry of global brands are expected to enhance regional market presence.
Market Segmentations:
By Type
- Automatic
- Manual
By Application
- Residential
- Commercial
By Distribution Channel
- Offline
- Online
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the drip coffee maker market includes leading players such as Electrolux AB, illycaffè S.p.A., GROUPE SEB UK, Ltd., BSH Hausgeräte GmbH, Spectrum Brands, Gruppo Cimbali S.p.A., Morphy Richards India, Espresso Supply, Inc., De’Longhi Appliances S.r.l., and Koninklijke Philips N.V. These companies focus on product innovation, energy efficiency, and smart brewing technologies to strengthen market presence. Manufacturers are introducing advanced automatic machines with programmable settings, improved filtration systems, and thermal carafes to meet diverse consumer needs. Strategic partnerships, mergers, and product expansions are key strategies to enhance brand visibility and distribution networks. Premium design, digital integration, and sustainability remain central to competition. Continuous investment in R&D and product differentiation supports growth, while strong retail and e-commerce channels help these companies maintain leadership across global markets.
Key Player Analysis
- Electrolux AB
- illycaffè S.p.A.
- GROUPE SEB UK, Ltd.
- BSH Hausgeräte GmbH
- Spectrum Brands
- Gruppo Cimbali S.p.A.
- Morphy Richards India
- Espresso Supply, Inc.
- De’Longhi Appliances S.r.l.
- Koninklijke Philips N.V.
Recent Developments
- In July 2024, Ninja introduced the Ninja Luxe Café, a versatile three-in-one coffee maker designed to brew precisely measured espresso, cold brew, and drip coffee.
- In 2024, BSH Hausgeräte GmbH (owner of Bosch/Siemens home appliances) published a historical review of its coffee machine evolution, emphasising next-generation electric drip/filter and bean-to-cup machines.
- In May 2023, De’Longhi America introduced TrueBrew, a groundbreaking fully automatic drip coffee machine. This innovative appliance features built-in technology that precisely grinds, measures, and brews coffee in various sizes with just the press of a button, thanks to De’Longhi’s patented Bean Extract Technology.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The drip coffee maker market is expected to show steady expansion through 2032 due to rising home coffee consumption and technological improvements.
- Automatic models with smart controls and advanced brewing features will continue to dominate market demand globally.
- Growing awareness of sustainability will encourage adoption of energy-efficient and recyclable drip coffee makers.
- Manufacturers will emphasize digital integration, app connectivity, and personalized brewing settings to attract tech-savvy users.
- Residential demand will remain strong, supported by the popularity of compact and stylish coffee appliances.
- Commercial spaces such as offices and cafés will increase investments in reliable and high-capacity drip systems.
- North America will maintain its leadership position, while Asia-Pacific will record the fastest growth through urban lifestyle shifts.
- Competitive intensity will rise as brands enhance product design, performance, and online presence.
- Companies will adopt strategic partnerships and mergers to strengthen regional distribution networks.
- Sustainable manufacturing, reusable filters, and recyclable components will define the industry’s long-term direction.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Drip Coffee Maker market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Drip Coffee Maker market projected to grow between 2025 and 2032
Which Drip Coffee Maker market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Drip Coffee Maker market?
Who are the leading companies in the Drip Coffee Maker market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.45 billion → 2032: USD 3.18 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Drip Coffee Maker Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Drip Coffee Maker Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Drip Coffee Maker Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Drip Coffee Maker Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Drip Coffee Maker Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Drip Coffee Maker Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Drip Coffee Maker Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Drip Coffee Maker Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.45 billion → 2032: USD 3.18 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Drip Coffee Maker Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Drip Coffee Maker Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Drip Coffee Maker Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Drip Coffee Maker Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

