
Self-injection and biologics drive dosing hardware demand
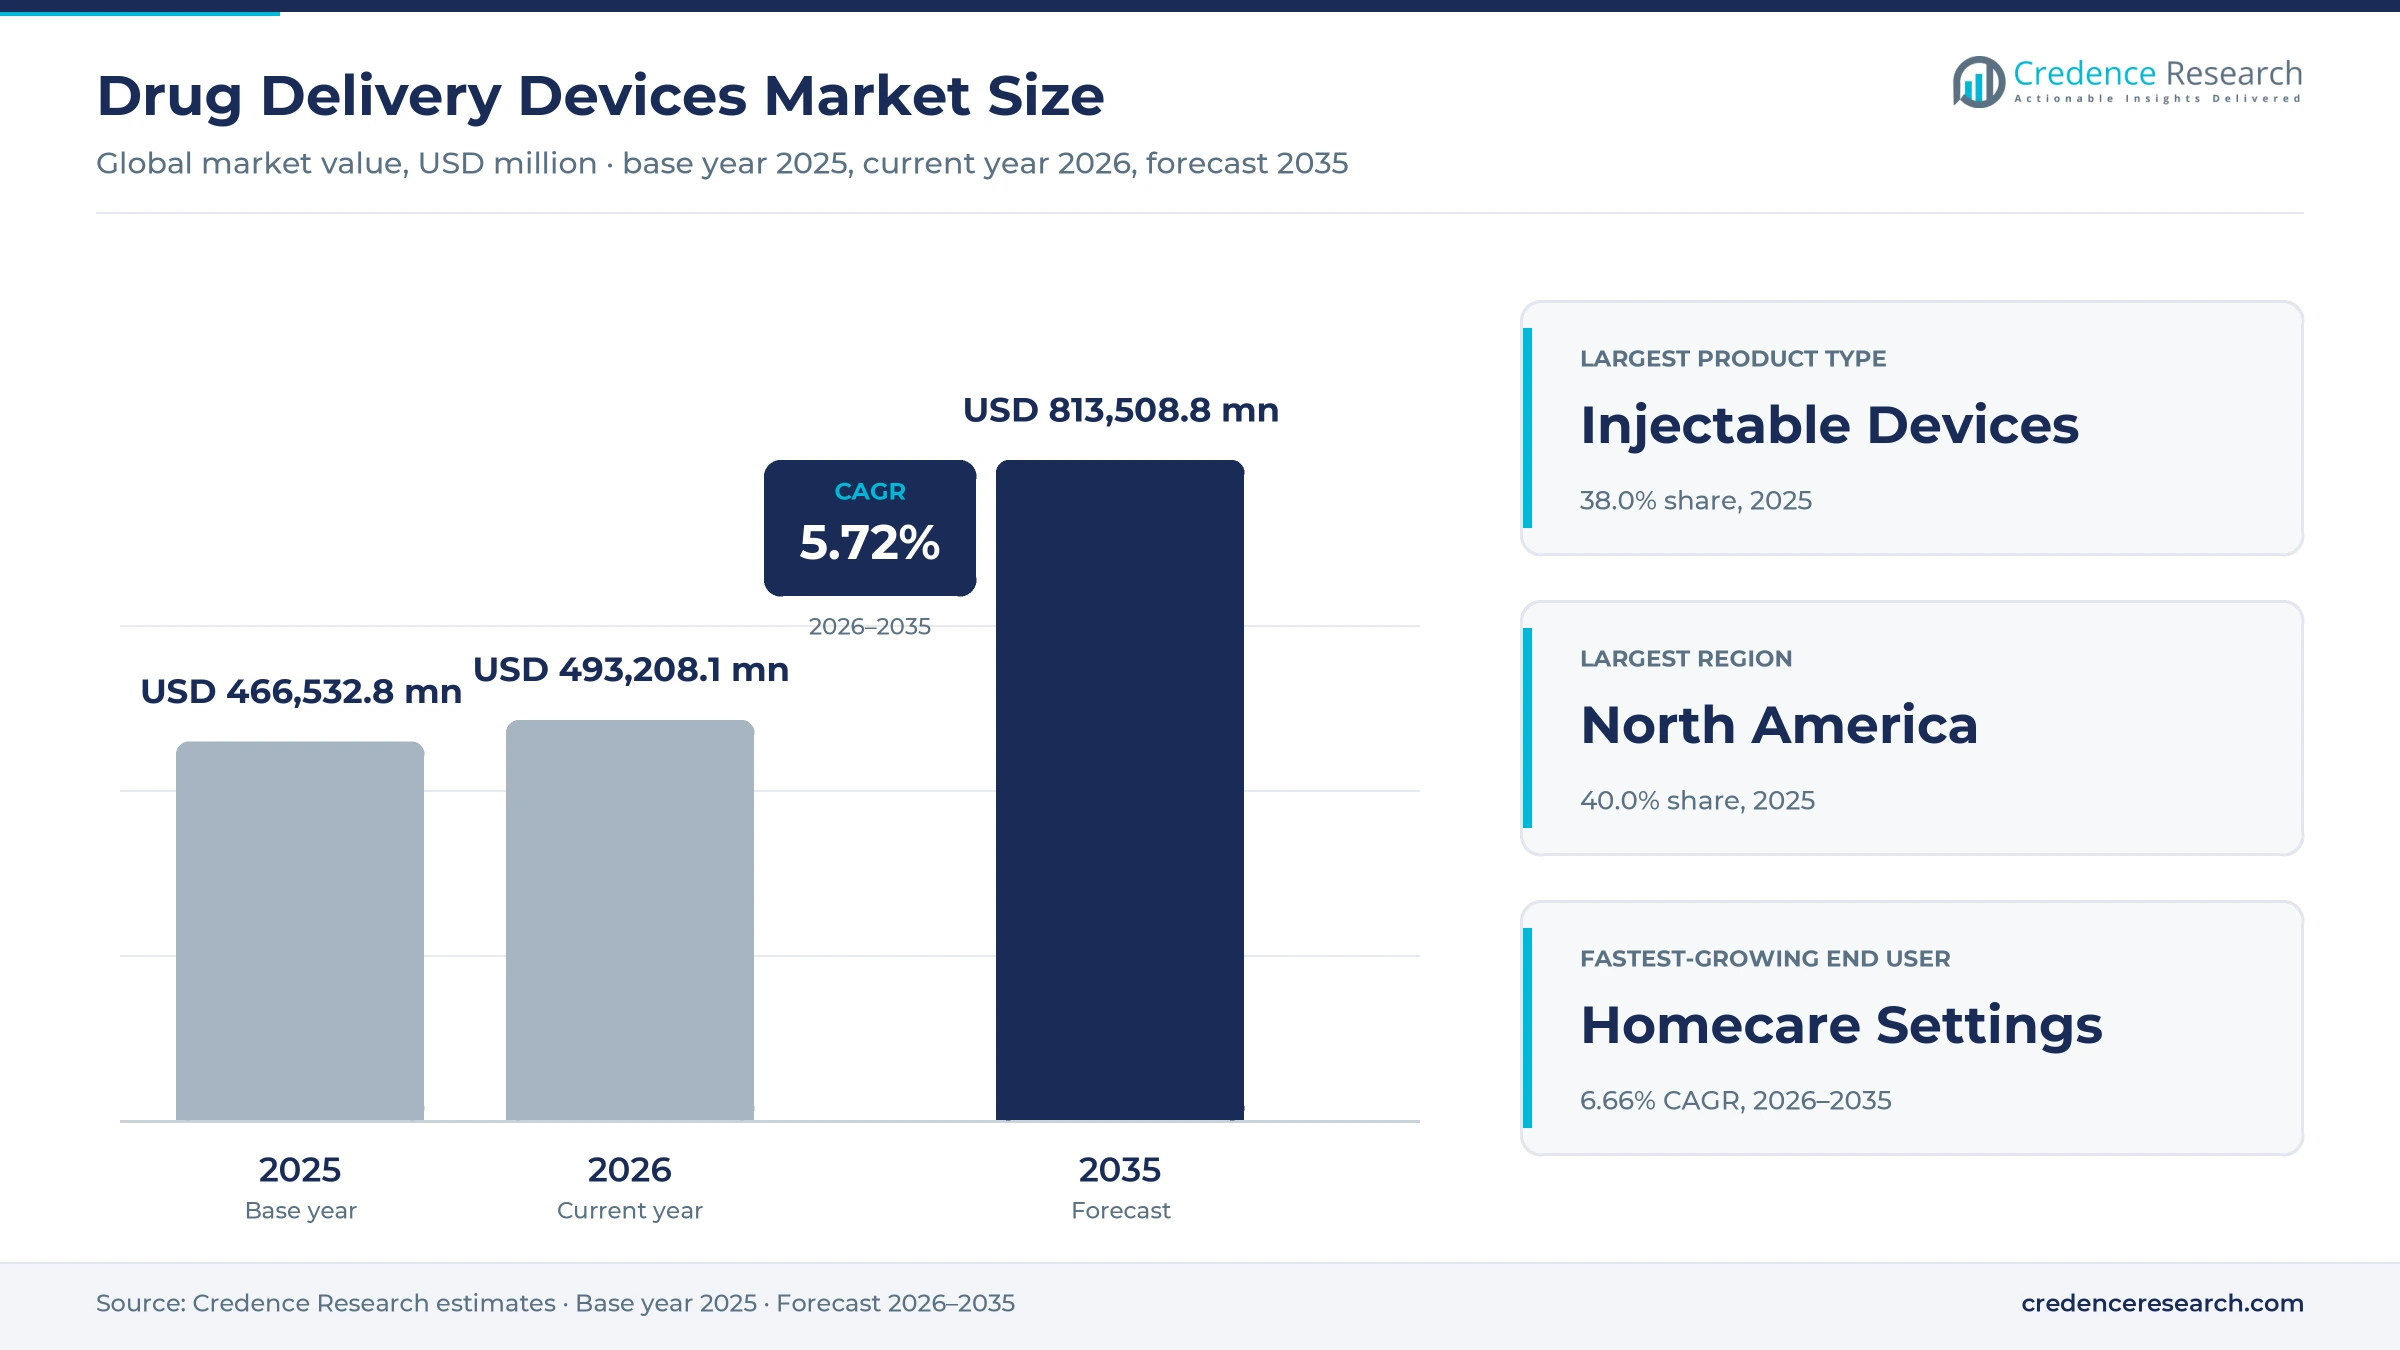
The global drug delivery devices market was valued at USD 466.53 billion in 2025 and is projected to increase from USD 493.21 billion in 2026 to USD 813.51 billion by 2035, registering a CAGR of 5.72% during 2026–2035. Demand comes from rising rates of diabetes, cancer, asthma and autoimmune disease, and from a pipeline of biologic medicines that need precise injection or infusion. North America held the largest regional share, 40.0% in 2025, because high biologic use and broad insurance coverage support premium autoinjectors, pumps and wearable injectors. Asia Pacific is the fastest-growing region at 6.96% a year, as China and India expand hospital capacity and local syringe production. The commercial picture shifted in 2025, when U.S. regulators approved an at-home autoinjector for an Alzheimer's disease antibody. As a result, makers are shifting investment from basic syringes toward self-injection systems for patients at home.
Which products and care settings does this analysis cover?
The analysis counts infusion pumps, implantable stents that release medicine, injectable systems, inhalers, nebulizers, transdermal patches and other dosing products, valued at manufacturer selling prices. Drug makers buy many components for combination products, while hospitals, clinics and home care providers buy pumps, syringes and nebulizers through tenders and distributors.
The value of the medicines themselves sits outside the scope of this analysis, which counts only the hardware that holds and doses them. The value chain runs from glass, polymer and tubing suppliers through component and system makers to drug companies, distributors, hospitals and patients.
Drug Delivery Devices Market Insights
- The drug delivery devices market grows from USD 466.53 billion in 2025 to USD 813.51 billion by 2035, a 5.72% CAGR driven by chronic disease and home injection.
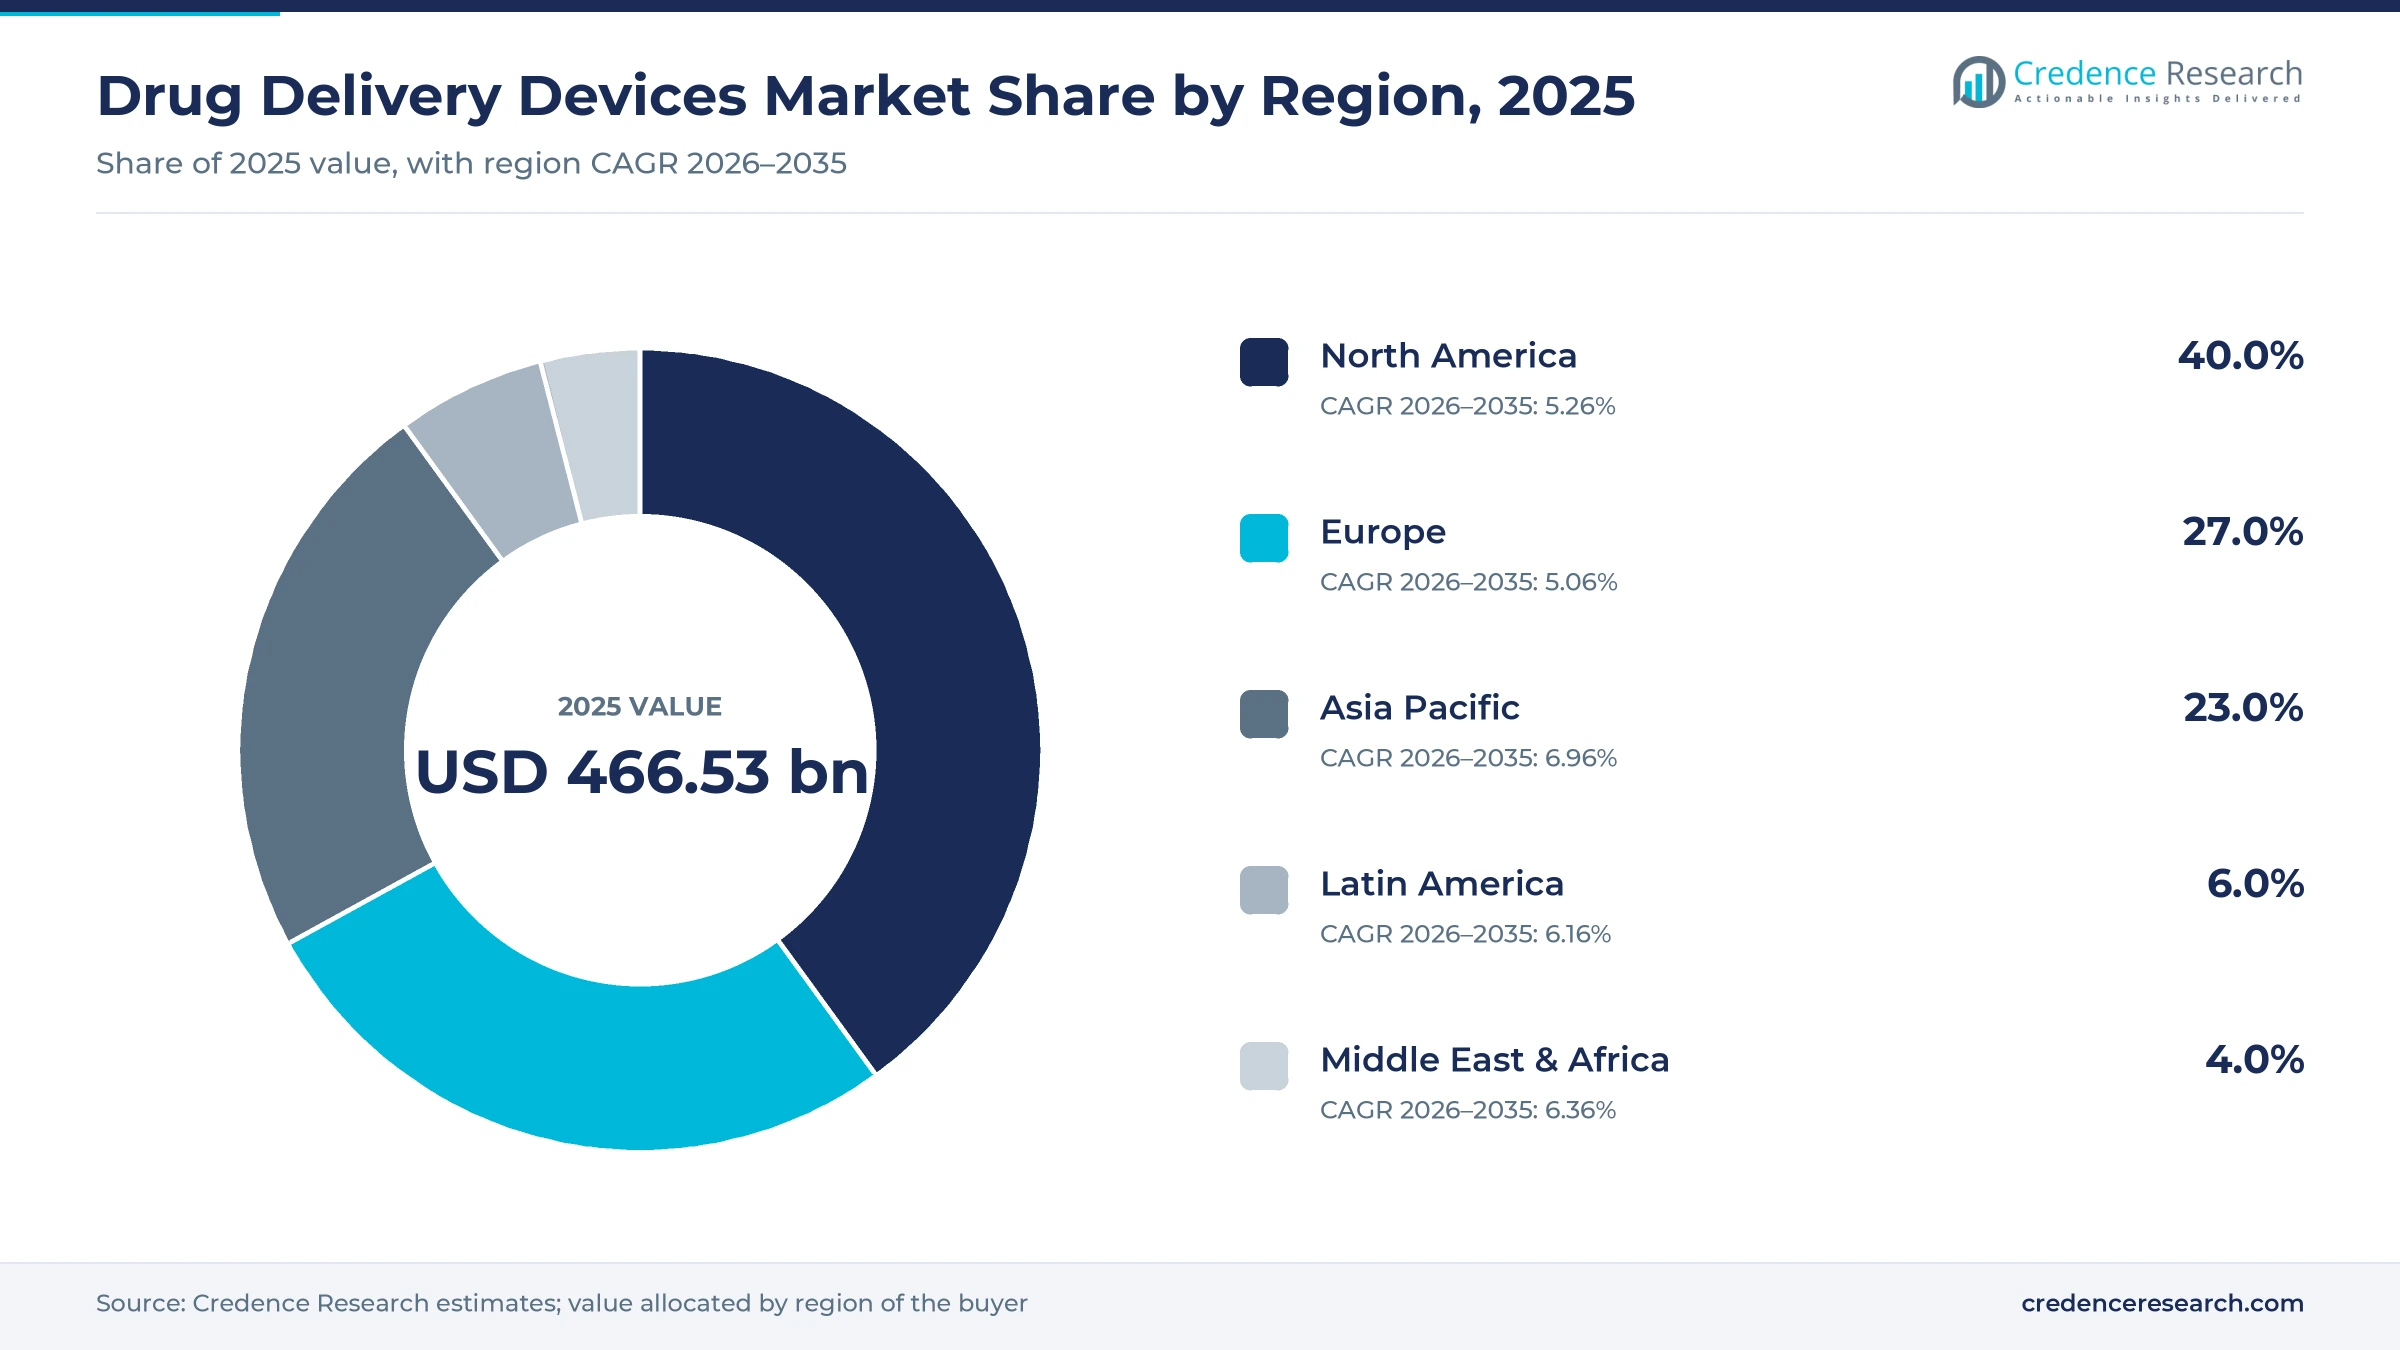
- North America held 40.0% of global drug delivery device value in 2025, supported by high biologic use and broad coverage for self-injection.
- Injectable devices led product types with 38.0% of 2025 value, and they also grow fastest at 6.35% a year.
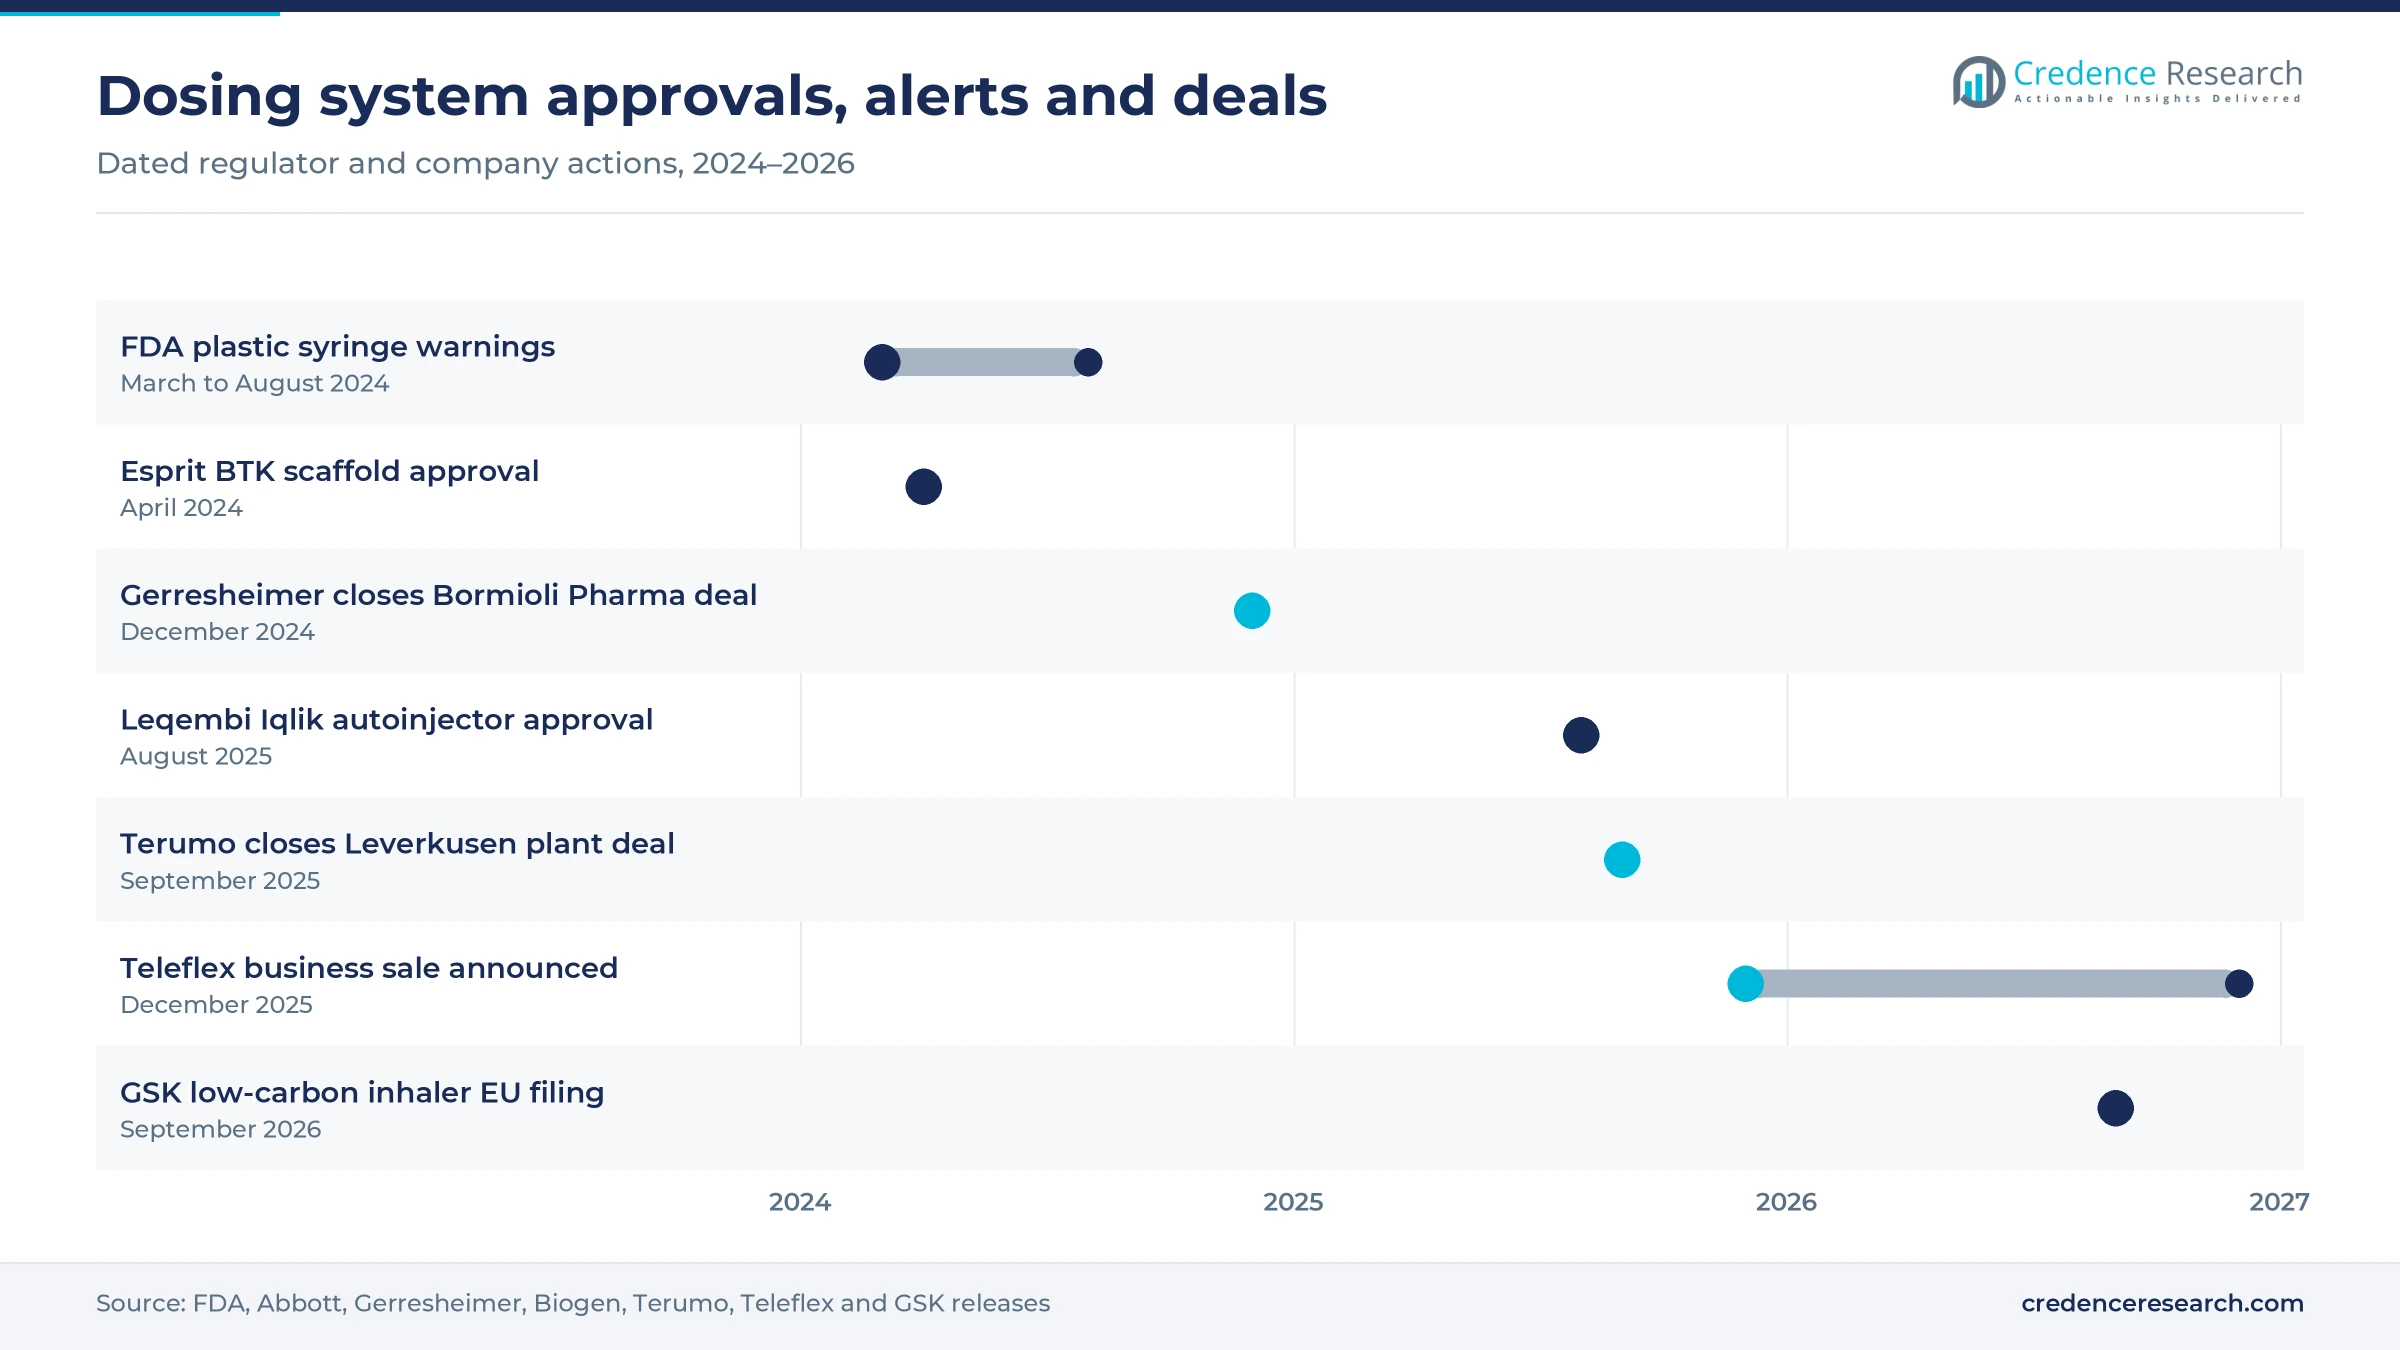
- In August 2025, the FDA approved Leqembi Iqlik, a weekly subcutaneous autoinjector that lets Alzheimer's patients take maintenance doses at home.
- Gerresheimer, Terumo and Teleflex reshaped their portfolios through deals completed or announced between December 2024 and December 2025.
Injectable devices lead as home treatment expands
Why do injectable systems take most product spending?
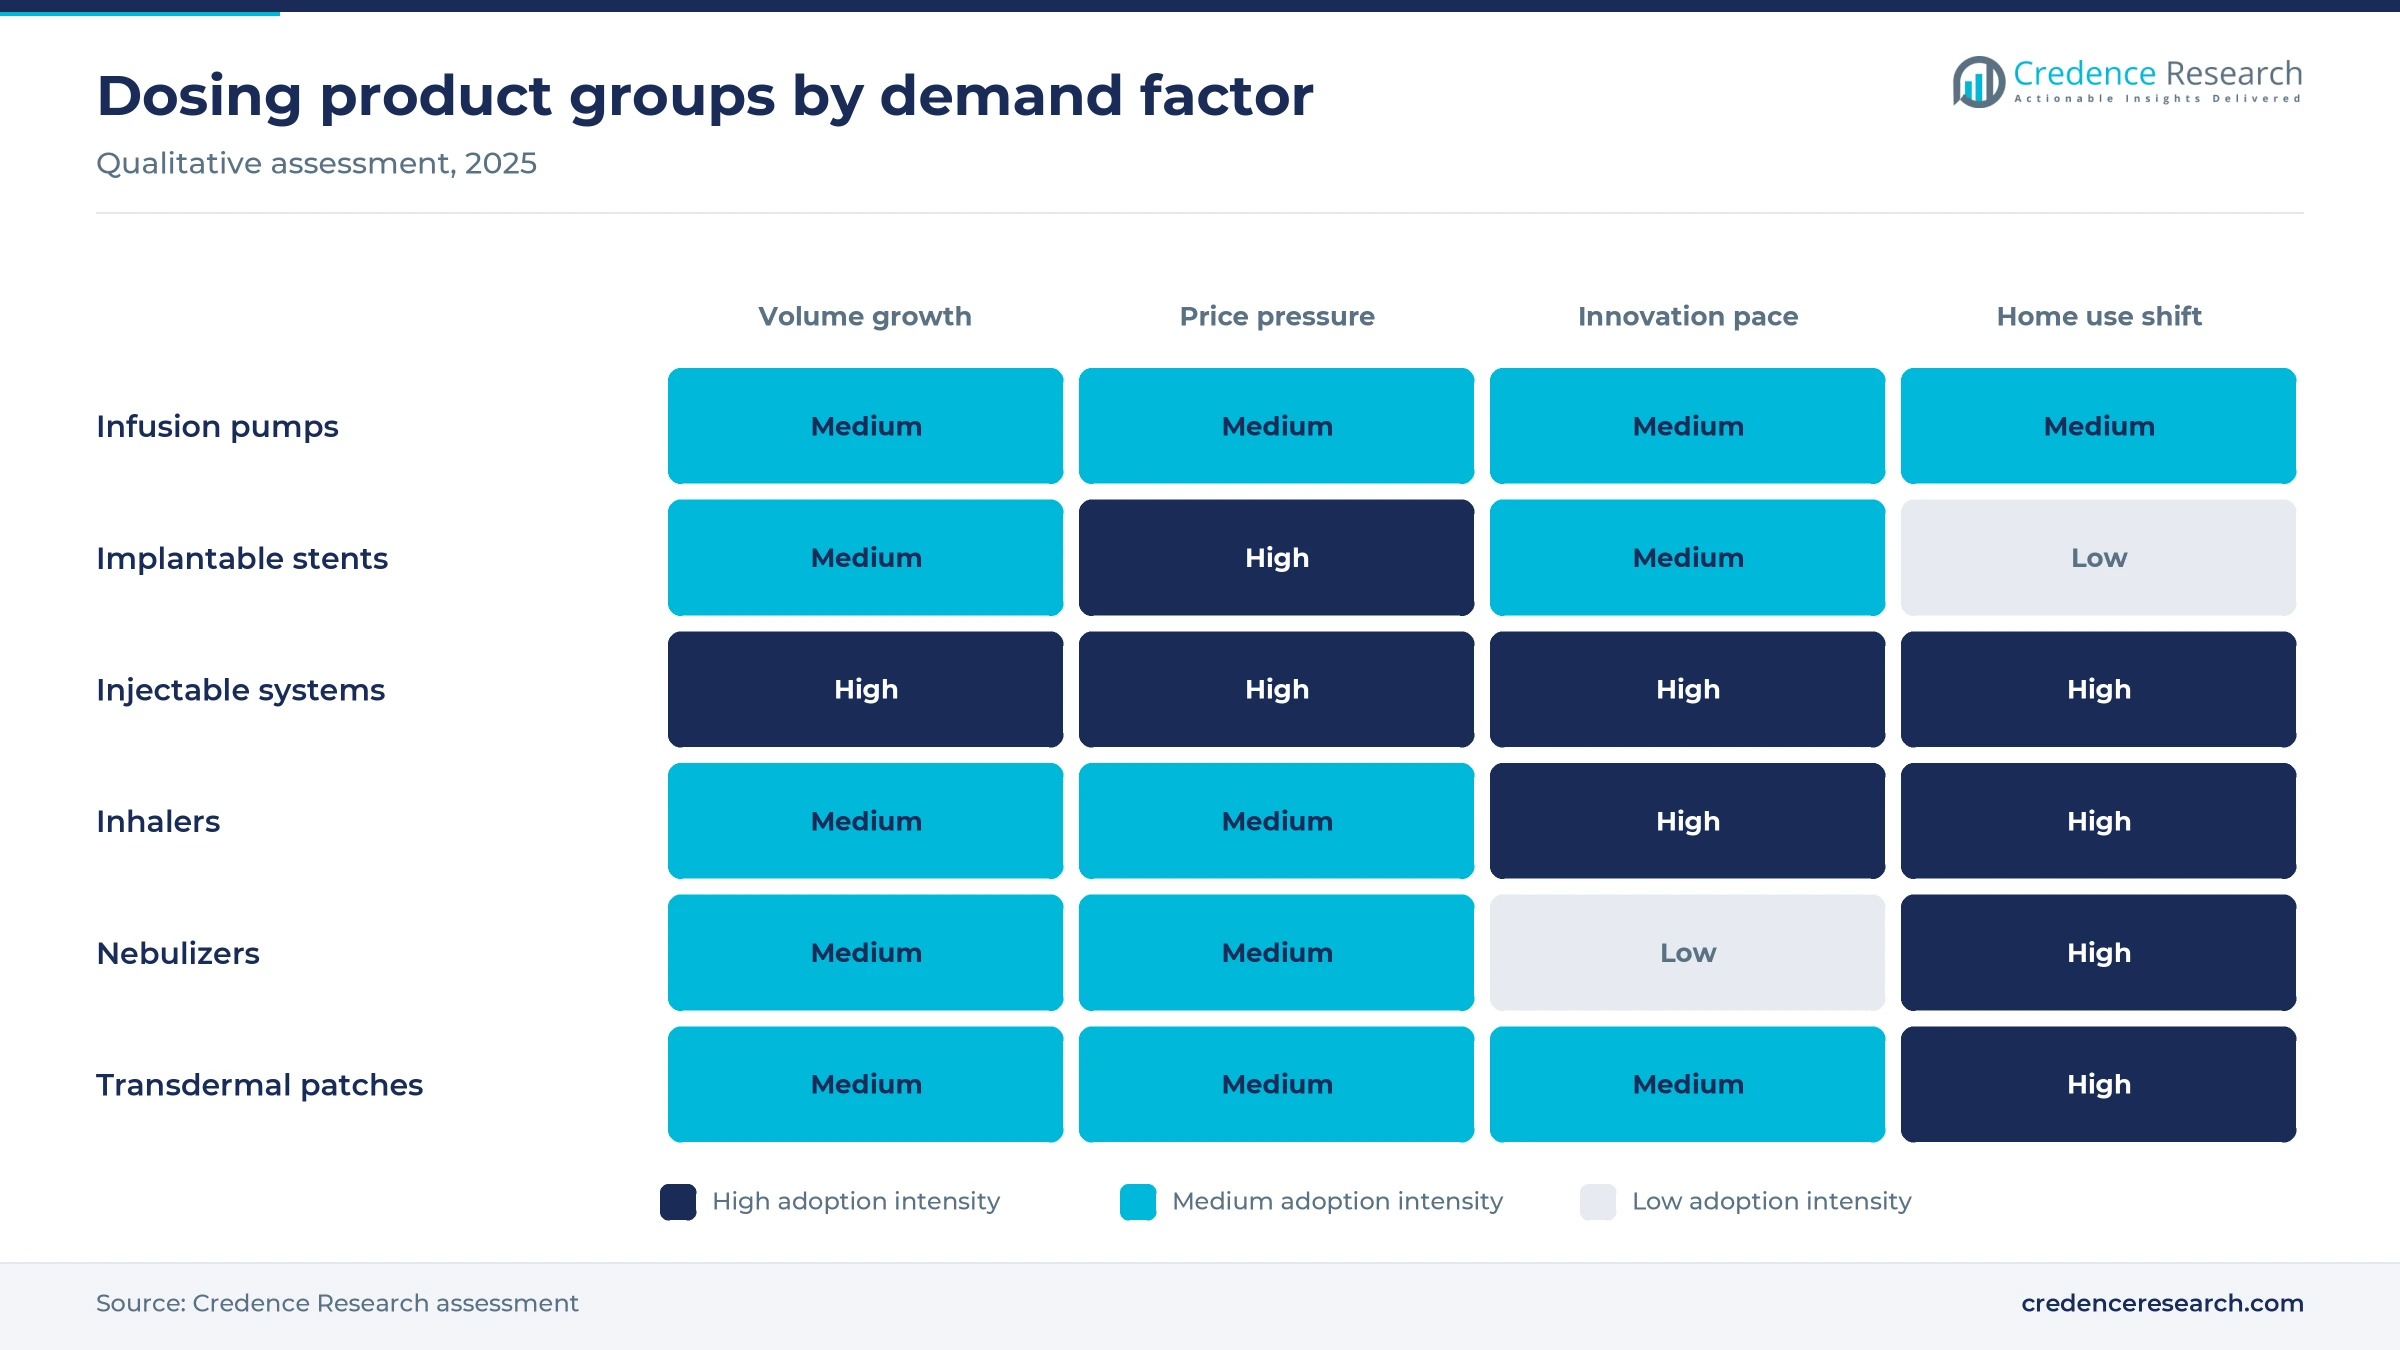
Based on product type, the market is categorized into drug infusion pumps, implantable stents, injectable devices, inhalers, nebulizers, transdermal patches and others. Injectable Devices led with a 38.0% share of 2025 value, because syringes, prefilled syringes, pens and autoinjectors are used for vaccines, insulin and most biologics. Injectable Devices also grow fastest at 6.35% a year, as more biologics move to self-injection. Inhalers keep a large base of repeat users with asthma and chronic lung disease.
How does the parenteral route keep its lead?
Based on route of administration, the market is categorized into inhalation, transdermal, implantable and parenteral. The Parenteral route led with a 58.0% share of 2025 value, because injection and infusion remain the only practical way to give large protein medicines. The Parenteral route also grows fastest at 6.05% a year, as subcutaneous versions replace some hospital infusions. Inhalation keeps steady demand from patients with asthma and chronic obstructive lung disease.
Which therapy areas drive dosing system demand?
Based on application, the market is categorized into oncology, infectious diseases, respiratory diseases, autoimmune diseases, cardiovascular diseases and others. Oncology led with a 24.0% share of 2025 value, because chemotherapy and cancer antibodies need infusion pumps, ports and closed transfer systems. Autoimmune Diseases grow fastest at 6.55% a year, as patients with arthritis, psoriasis and bowel disease use autoinjectors at home. Respiratory diseases keep a large base of inhaler and nebulizer users worldwide.
Where is treatment moving across care settings?
Based on end-users, the market is categorized into hospitals and clinics, ambulatory surgical centers, homecare settings and others. Hospitals & Clinics led with a 55.0% share of 2025 value, because they run infusion suites, intensive care units and vaccination programs. Homecare Settings grow fastest at 6.66% a year, as autoinjectors, wearable injectors and portable pumps let patients treat themselves. Ambulatory surgical centers add demand for implants and short infusions.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Injectable Devices | 38.0% | Injectable Devices | 6.35% |
| By Route of Administration | Parenteral | 58.0% | Parenteral | 6.05% |
| By Application | Oncology | 24.0% | Autoimmune Diseases | 6.55% |
| By End-Users | Hospitals & Clinics | 55.0% | Homecare Settings | 6.66% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Chronic disease and biologic launches lift demand
How does the diabetes burden sustain injection demand?
Diabetes creates the largest single pool of repeat users, because many patients inject insulin or newer metabolic medicines every day or every week. The World Health Organization reports that the number of people living with diabetes rose from 200 million in 1990 to 830 million in 2022. Each insulin or incretin user needs pens, needles, pumps or prefilled syringes throughout treatment, often for decades after diagnosis. As a result, unit volumes for injection products rise steadily with population growth and longer survival.
Why do biologic launches widen the self-injection pool?
New biologic medicines widen the self-injection pool, because drug makers now design products for home use from the start. In August 2025, the FDA approved Leqembi Iqlik, a subcutaneous autoinjector that gives a 360 mg maintenance dose of lecanemab in about 15 seconds. Patients with early Alzheimer's disease can switch to this weekly injection after 18 months of intravenous treatment. In turn, demand for autoinjectors and high-volume syringes grows in neurology as well as immunology.
How do aging populations lift infusion and implant volumes?
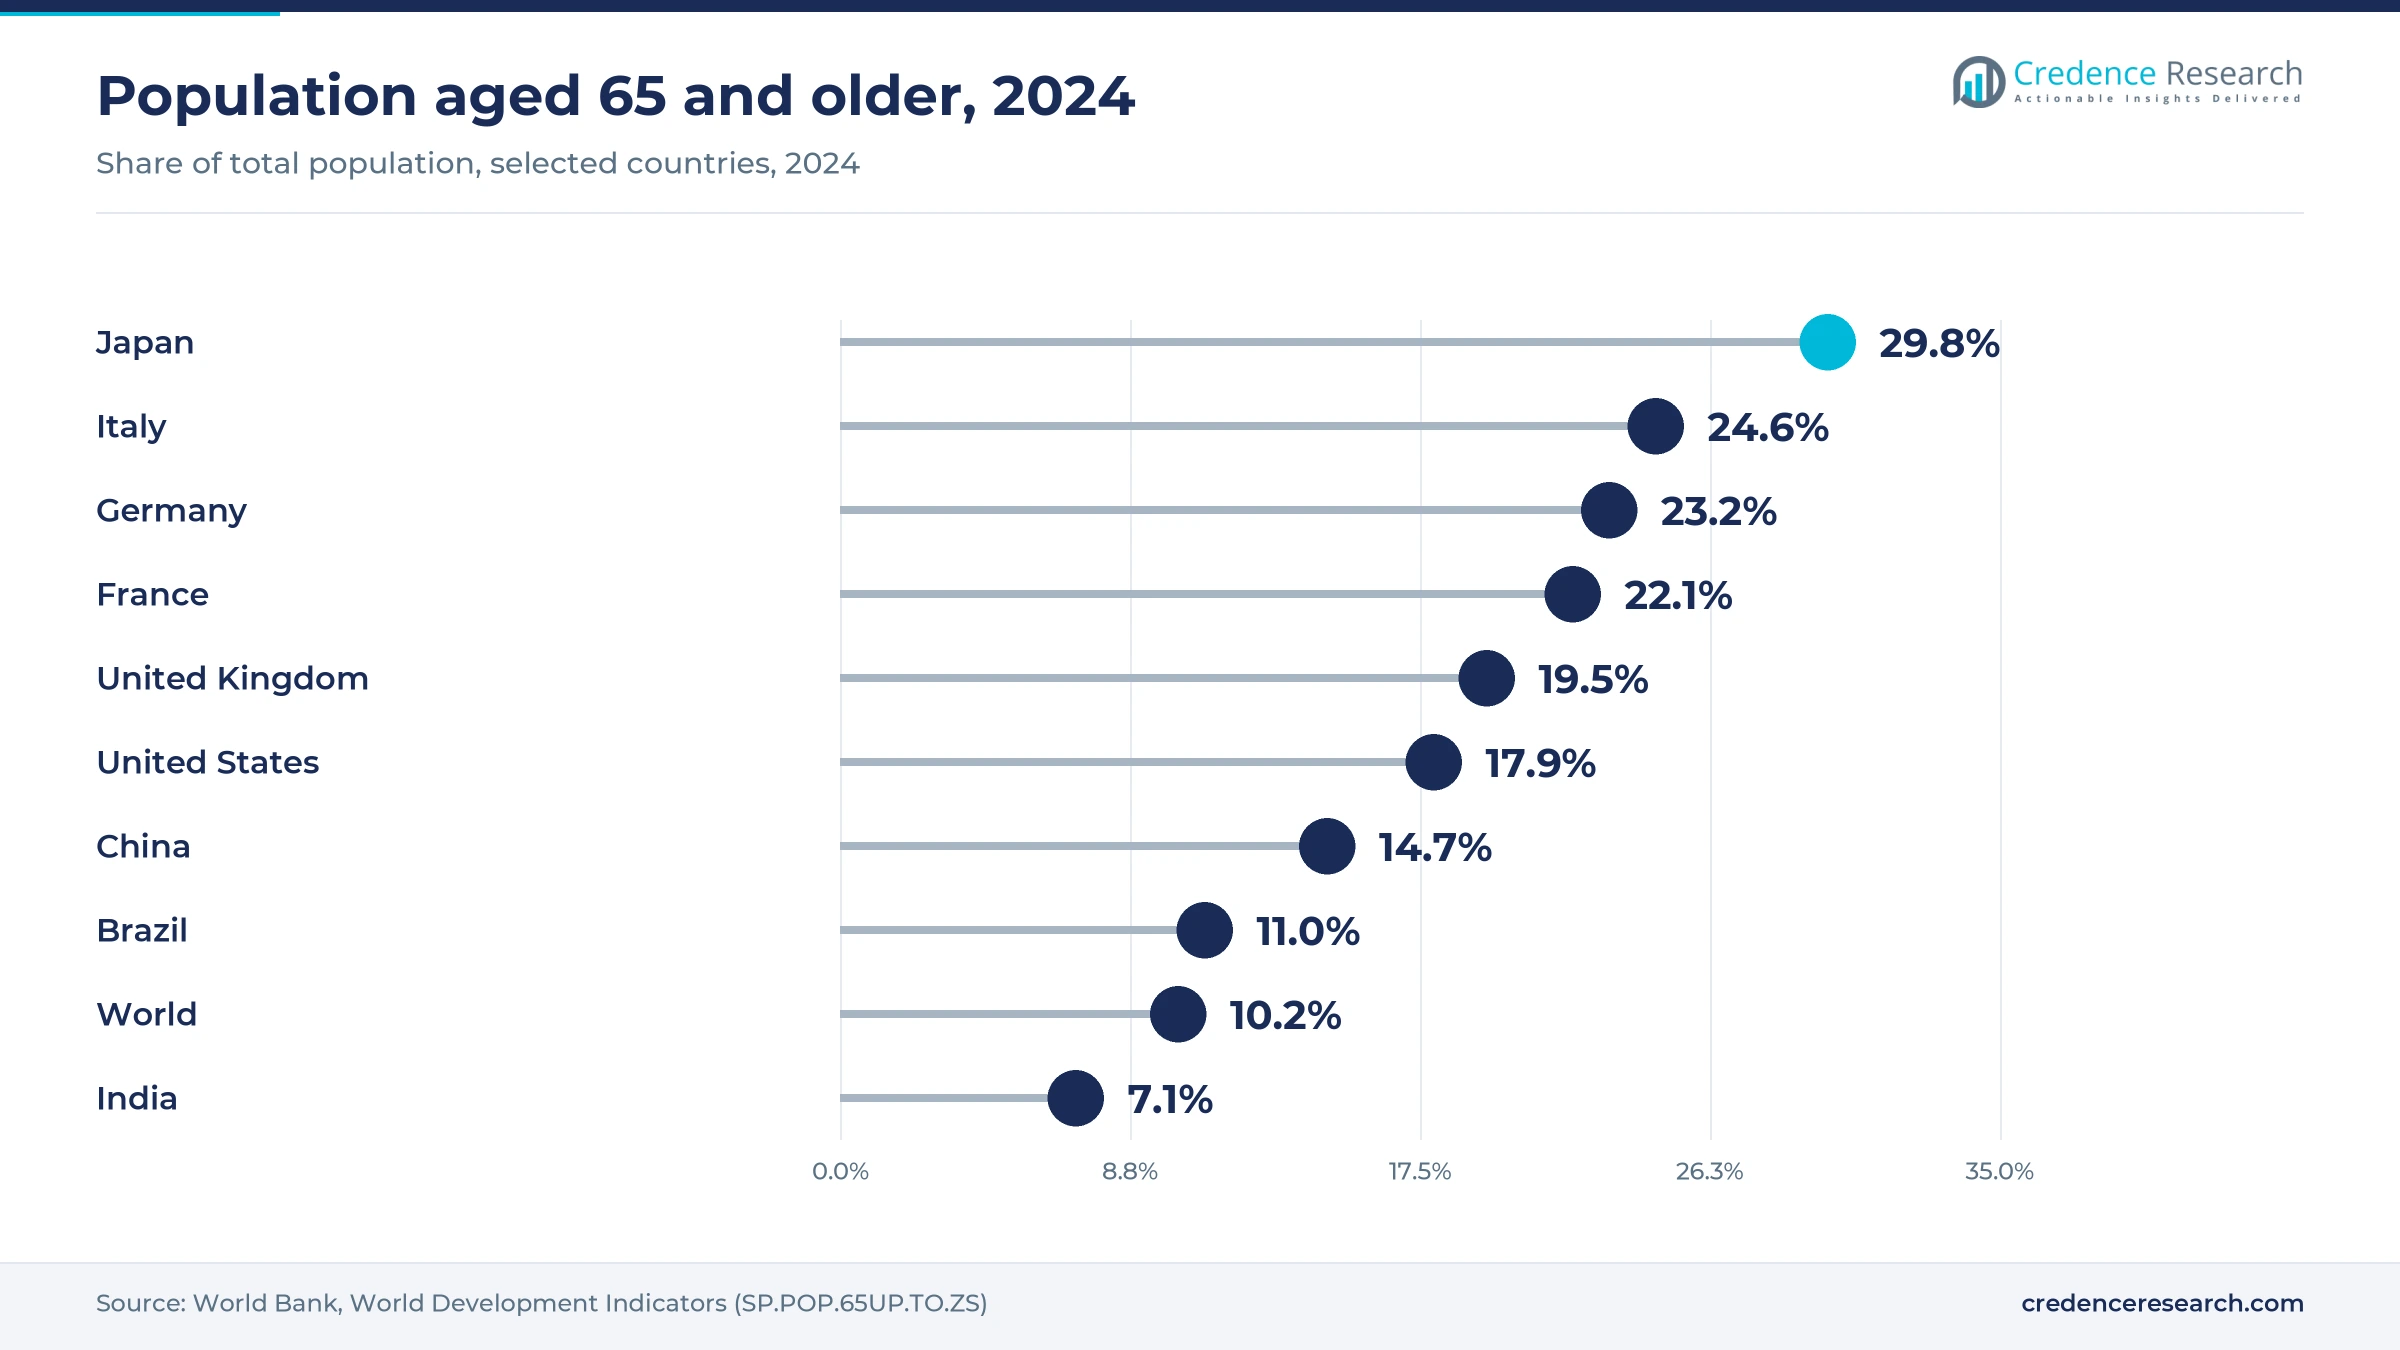
Aging populations lift infusion and implant volumes, because older patients have more cancer, heart disease and chronic pain. People aged 65 and older made up 29.8% of Japan's population and 24.6% of Italy's in 2024, according to World Bank data. These patients often need infusion pumps in hospital, stents that release medicine into arteries, and patches for pain relief or hormone therapy at home. As a result, hospitals and home care providers keep adding dosing equipment.
Why does the shift to home care favor wearable systems?
The shift of treatment into homes favors wearable and easy-to-use systems, because payers want to cut costly infusion center visits. Patients who can inject or infuse at home save travel time, and hospitals free chairs for sicker patients. In January 2025, BD showed its Libertas wearable injector and Evolve on-body injector, both still in development, at the Pharmapack packaging and dosing exhibition in Paris. In turn, drug makers and component suppliers are investing in large-volume subcutaneous systems for the next wave of biologics.
Autoinjectors and low-carbon inhalers reshape demand
How is self-injection shifting device design?
Self-injection is shifting device design toward thicker medicines and shorter needles, because many new biologics are highly concentrated. In January 2025, BD presented its Neopak XtraFlow glass prefillable syringe with an 8 mm needle and thinner walls for viscous biologics. The same exhibition featured plunger stoppers for 1 to 3 mL doses that lower glide force. As a result, competition now centers on comfort, injection time and compatibility with filling lines.
Why are low-carbon propellants rising in inhaler design?
Low-carbon propellants are rising in inhaler design, because metered dose inhalers release greenhouse gases with every puff. In September 2026, GSK announced an EU regulatory submission for a version of its Ventolin inhaler that uses the propellant HFA-152a. The company said the change could cut greenhouse gas emissions by about 92% per inhaler, with first launches expected in 2027 if approved. In turn, inhaler makers must requalify valves, canisters and filling processes.
Can resorbable implants open a vascular opportunity?
Implant makers have a clear opening in resorbable scaffolds, because they release medicine and then dissolve instead of staying in the artery. In April 2024, the FDA approved the Abbott Esprit BTK scaffold, which releases everolimus to treat narrowed arteries below the knee. Patients with chronic limb-threatening ischemia had few options beyond balloon angioplasty. As a result, coronary stents and leg artery implants could gain new resorbable designs.
Where can suppliers win share in contract filling?
Component suppliers have room to grow in contract filling and assembly, because drug makers want one partner for containers, filling and final assembly. In September 2025, Terumo completed its purchase of a WuXi Biologics drug product plant in Leverkusen, Germany, to fill vials and polymer syringes and add assembly. Gerresheimer completed its purchase of Bormioli Pharma in December 2024 to widen its glass and plastic packaging range. As a result, integrated suppliers have strong prospects in Europe and the United States.
Supply quality, pricing and rules slow uptake
Why do syringe quality failures disrupt supply?
Quality failures are a major constraint, because hospitals cannot tolerate leaks or breakage in products used for every injection. Starting in November 2023, the FDA warned about plastic syringes made in China, and by August 2024 it told users to stop using syringes from three named makers unless absolutely necessary. Hospital buyers then had to find other qualified sources at short notice. As a result, purchasing teams now audit plant locations more closely, which favors suppliers with proven quality records.
How do tenders and price pressure limit value growth?
Price pressure limits value growth, because public hospitals buy syringes, needles and infusion sets through large tenders. Basic products have many competing makers in China, India and Europe, so prices stay low even when volumes rise. Suppliers must therefore cut costs through automation, larger plants and higher output per line. In turn, unit volumes rise faster than value for mature products, while premium systems carry most of the margin.
Why do combination product rules slow launches?
Rules for combination products slow launches, because regulators review the medicine and the device together. A new autoinjector or wearable injector needs human factors studies, stability data and proof that each dose is accurate. Changes to a container or propellant can require new filings, as the GSK inhaler submission in September 2026 shows. As a result, smaller device makers often need drug company partners with large regulatory teams.
How do waste and cost concerns slow adoption at home?
Waste and cost concerns slow adoption, because single-use autoinjectors and wearable injectors add plastic, glass and electronic waste. Health systems also question whether premium systems are worth the price compared with vials and syringes. Patients in many low-income countries pay for supplies out of pocket, which limits access to pens and pumps. In turn, makers are testing reusable designs, recycling programs and lower-cost models for emerging markets.
North America leads as Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 186.61 | 40.0% | 5.26% |
| Europe | 125.96 | 27.0% | 5.06% |
| Asia Pacific | 107.30 | 23.0% | 6.96% |
| Latin America | 27.99 | 6.0% | 6.16% |
| Middle East & Africa | 18.66 | 4.0% | 6.36% |
Why does North America hold the largest regional share?
North America held a 40.0% share of 2025 value and grows at 5.26% a year through 2035. The United States drives this position, because it has the highest use of biologics, pens, autoinjectors and home infusion. People aged 65 and older made up 17.9% of the U.S. population in 2024, which adds patients with cancer, heart disease and diabetes. U.S. regulators approved the Esprit BTK scaffold and the Leqembi Iqlik autoinjector between 2024 and 2025, which keeps new systems reaching this region first.
How fast is Asia Pacific adding patients?
Asia Pacific held a 23.0% share of 2025 value and is the fastest-growing region at 6.96% a year. China and India are expanding hospital capacity, vaccination programs and local production of syringes and infusion sets. Japan adds high-value demand from the oldest population among major economies, with 29.8% of residents aged 65 or older in 2024. China's share reached 14.7% and India's 7.1%, which points to rising demand as these populations age over the next decade.
What shapes demand across Europe?
Europe held a 27.0% share of 2025 value and grows at 5.06% a year through 2035. Germany, France, Italy and the United Kingdom account for most spending, and people aged 65 and older made up 23.2% of Germany's population and 22.1% of France's in 2024. Tender-based purchasing keeps prices low for syringes, needles and other basic products. However, Europe is also a center of component making, with glass, polymer and tubing plants serving drug makers worldwide, and the 2026 GSK inhaler filing shows how climate rules shape design.
Where is Latin America adding demand?
Latin America held a 6.0% share of 2025 value and grows at 6.16% a year through 2035. Brazil and Mexico lead regional demand, and people aged 65 and older made up 11.0% of Brazil's population in 2024. Public health systems buy syringes and infusion sets through tenders, while private hospitals add pumps and pens.
What limits growth in the Middle East and Africa?
The Middle East and Africa held a 4.0% share of 2025 value and grows at 6.36% a year through 2035. Gulf states add higher-value demand from new hospitals and specialty clinics that buy pumps and biologic systems. Access in sub-Saharan Africa remains limited, because many patients still rely on vials, syringes and donated vaccine supplies.
Approvals and deals in injectables since 2024
| Development | Status and market relevance |
|---|---|
| In April 2024, Abbott received FDA approval for the Esprit BTK everolimus-eluting resorbable scaffold for arteries below the knee. | Approved; first resorbable scaffold of its kind for chronic limb-threatening ischemia in the U.S. |
| In December 2024, Gerresheimer completed its acquisition of the holding company of Bormioli Pharma. | Completed; adds glass and plastic containers, closures and dosing systems to its range |
| In August 2025, the FDA approved Leqembi Iqlik, a weekly subcutaneous autoinjector for early Alzheimer's disease maintenance. | Approved; U.S. launch set for October 2025 for at-home use |
| In September 2025, Terumo completed its acquisition of a WuXi Biologics drug product plant in Leverkusen, Germany. | Completed; adds contract filling of vials and polymer syringes plus assembly |
| In December 2025, Teleflex agreed to sell its Acute Care, Interventional Urology and OEM businesses. | Announced; closing expected in the second half of 2026, leaving a focus on vascular access, interventional and surgical |
Wearable injectors and polymer syringes lead innovation
- Wearable on-body injectors stick to the skin and deliver large volumes over several minutes, which lets patients avoid infusion center visits.
- Polymer prefillable syringes resist breakage and suit sensitive biologics, which supports contract filling such as the Terumo Leverkusen plant acquired in September 2025.
- Low-carbon inhaler propellants such as HFA-152a could cut emissions by about 92% per inhaler, which helps health systems meet climate targets.
- Resorbable drug-eluting scaffolds release medicine into the artery and then dissolve, which leaves no permanent metal implant behind.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Packaging makers and medtech groups compete on scale
Competition is led by component and packaging makers, diversified medical technology groups and drug companies that design their own dosing formats. BD supplies syringes, needles, prefillable syringes and pens, and it is developing wearable injectors for biologics. Gerresheimer AG and Terumo Medical Corporation compete in glass and polymer syringes, vials and contract filling for drug makers. Abbott and Gore offer vascular implants, including drug-eluting and covered stents. Teleflex Incorporated sells vascular access and interventional products used to give medicines in hospitals. Novartis AG markets inhaled and injectable medicines in its own formats, while Hindustan Syringes & Medical Devices is a major Indian maker of disposable syringes and needles. RAUMEDIC supplies polymer tubing and molded components that drug makers and pump makers use in infusion systems. As a result, drug makers often favor suppliers that can combine containers, devices, filling and regulatory support under one contract.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| BD | Diversified | Syringes, needles, prefillable syringes, pens and wearable injectors in development |
| Gerresheimer AG | Packaging | Glass and plastic containers, syringes and dosing systems, expanded by Bormioli Pharma |
| Terumo Medical Corporation | Diversified | Polymer prefillable syringes, infusion products and contract filling |
| Abbott | Diversified | Drug-eluting coronary stents and the Esprit BTK resorbable scaffold |
| W. L. Gore & Associates, Inc. | Specialist | Stent grafts, covered stents and medical membranes |
| Teleflex Incorporated | Diversified | Vascular access catheters and interventional products |
| Novartis AG | Pharma | Inhaled and injectable medicines in proprietary formats |
| Hindustan Syringes & Medical Devices | Specialist | Disposable syringes and needles from India |
| RAUMEDIC | Components | Polymer tubing and components for infusion and dosing systems |
Home injection and biologics set the growth pace
Credence Research's view is that home injection and biologic launches will set the pace of growth through 2035, because both move treatment out of hospitals and raise the value of each dose. The overall market grows at 5.72% a year, supported by chronic disease and aging populations in Asia Pacific and Europe. Basic syringes and infusion sets keep large volumes, but tender pricing limits their value growth. Companies that combine reliable containers, easy self-injection systems and filling capacity will win the most new contracts, while single-product makers face pressure on price.
How Credence Research sized spending on dosing systems
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which builds spending by product type, route of administration, application, end user and region. Regional and segment splits are Credence Research estimates informed by World Health Organization and World Bank statistics, U.S. regulator documents and company press releases. No primary interviews or surveys were used in preparing this edition of the report.
Dosing system spending outlook to 2035
By 2035, the drug delivery devices market is projected to reach USD 813.51 billion, with growth led by self-injection systems, wearable injectors and home infusion. Injectable systems will remain the largest product group, although price pressure will keep value growth moderate for basic syringes. North America keeps the highest spending per patient, while Asia Pacific adds the most new users and local production. Home care will take a larger share of routine treatment over the forecast period. As a result, advantage will depend on quality, ease of use and filling capacity.
Frequently Asked Questions
How big is the global drug delivery devices market?
Which product type leads drug delivery devices?
Which region leads drug delivery device spending?
Which application grows fastest?
Which care setting grows fastest?
What recent approvals shaped the market?
Who are the leading drug delivery device companies?
What restrains growth in drug delivery devices?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Drug Infusion Pumps
- 1.2.2 Implantable Stents
- 1.2.3 Injectable Devices
- 1.2.4 Inhalers
- 1.2.5 Nebulizers
- 1.2.6 Transdermal Patches
- 1.2.7 Others
- 1.3 By Route of Administration
- 1.3.1 Parenteral
- 1.3.2 Inhalation
- 1.3.3 Transdermal
- 1.3.4 Implantable
- 1.4 By Application
- 1.4.1 Oncology
- 1.4.2 Infectious Diseases
- 1.4.3 Respiratory Diseases
- 1.4.4 Autoimmune Diseases
- 1.4.5 Cardiovascular Diseases
- 1.4.6 Others
- 1.5 By End-Users
- 1.5.1 Hospitals & Clinics
- 1.5.2 Ambulatory Surgical Centers
- 1.5.3 Homecare Settings
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 466.53 billion → 2035: USD 813.51 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Drug Delivery Devices Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Drug Delivery Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Drug Delivery Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Drug Delivery Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Drug Delivery Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Drug Delivery Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Drug Delivery Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Drug Delivery Devices Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 466.53 billion → 2035: USD 813.51 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Drug Delivery Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Drug Infusion Pumps
- 12.3.7.2 Implantable Stents
- 12.3.7.3 Injectable Devices
- 12.3.7.4 Inhalers
- 12.3.7.5 Nebulizers
- 12.3.7.6 Transdermal Patches
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Route of Administration - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Parenteral
- 12.4.7.2 Inhalation
- 12.4.7.3 Transdermal
- 12.4.7.4 Implantable
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oncology
- 12.5.7.2 Infectious Diseases
- 12.5.7.3 Respiratory Diseases
- 12.5.7.4 Autoimmune Diseases
- 12.5.7.5 Cardiovascular Diseases
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-Users - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Hospitals & Clinics
- 12.6.7.2 Ambulatory Surgical Centers
- 12.6.7.3 Homecare Settings
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Drug Delivery Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Drug Delivery Devices Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Drug Delivery Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Drug Delivery Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Gerresheimer AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Abbott
- 18.4 W. L. Gore & Associates, Inc.
- 18.5 Terumo Medical Corporation
- 18.6 BD
- 18.7 Novartis AG
- 18.8 Teleflex Incorporated
- 18.9 Hindustan Syringes & Medical Devices
- 18.10 RAUMEDIC
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

