
Market Overview:
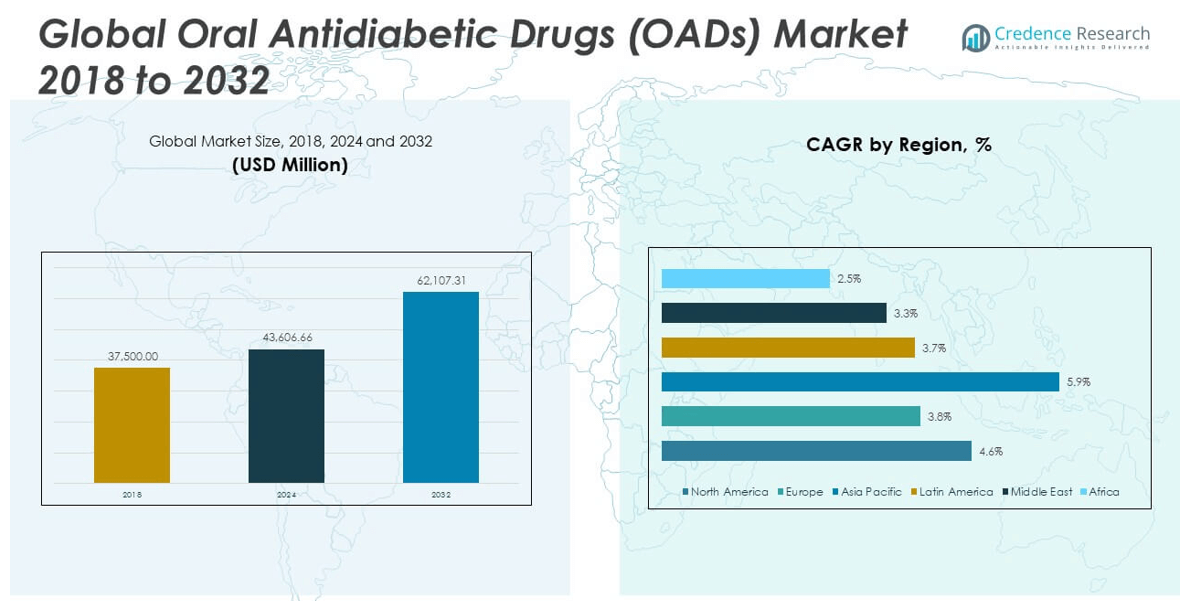
The Global Oral Antidiabetic Drugs (OADs) Market size was valued at USD 37,500.00 million in 2018 to USD 43,606.66 million in 2024 and is anticipated to reach USD 62,107.31 million by 2032, at a CAGR of 4.56% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Oral Antidiabetic Drugs (OADs) Market Size 2024 | USD 43,606.66 million |
| Oral Antidiabetic Drugs (OADs) Market, CAGR | 4.56% |
| Oral Antidiabetic Drugs (OADs) Market Size 2032 | USD 62,107.31 million |
The market is growing steadily due to the rising global prevalence of type 2 diabetes, increasing sedentary lifestyles, and an aging population. Pharmaceutical companies are actively investing in the development of novel drug classes such as SGLT2 inhibitors and DPP-4 inhibitors, which offer improved glycemic control and lower risk of hypoglycemia. Growing patient awareness, improved diagnosis rates, and greater access to healthcare in developing nations are accelerating the uptake of oral antidiabetic drugs. In addition, advancements in drug delivery technologies and fixed-dose combinations are enhancing patient adherence and long-term disease management.
North America currently leads the global market, driven by high diabetes incidence, robust healthcare infrastructure, and early adoption of new therapies. Europe follows closely due to favorable reimbursement policies and strong R&D activity. Meanwhile, Asia Pacific is emerging as the fastest-growing region, fueled by a rapidly expanding diabetic population, increasing urbanization, and rising healthcare expenditures in countries like China and India. Latin America and the Middle East & Africa are also witnessing growing demand, supported by improved medical access and rising awareness of diabetes management.
Market Insights:
- The Global Oral Antidiabetic Drugs (OADs) Market was valued at USD 37,500.00 million in 2018, reached USD 43,606.66 million in 2024, and is projected to reach USD 62,107.31 million by 2032, growing at a CAGR of 4.56%.
- Rising prevalence of type 2 diabetes, driven by sedentary lifestyles and obesity, fuels sustained demand for oral antidiabetic drugs.
- Innovation in drug classes like SGLT2 inhibitors and DPP-4 inhibitors supports better glycemic control and adoption.
- Limited access to healthcare and drug affordability challenges hinder growth in low-income regions.
- Regulatory complexity and market fragmentation across countries delay product launches and compliance.
- North America leads due to advanced healthcare infrastructure, high diagnosis rates, and strong reimbursement models.
- Asia Pacific emerges as the fastest-growing region, backed by increasing diabetes burden and expanding healthcare access.
Market Drivers:
Rising Type 2 Diabetes Prevalence Fueling Demand for Oral Therapeutics:
The increasing global burden of type 2 diabetes remains a major driver for the Global Oral Antidiabetic Drugs (OADs) Market. It affects millions worldwide, with lifestyle-related risk factors such as poor diet, obesity, and physical inactivity contributing to its rapid growth. The market benefits from expanding diagnostic capabilities and earlier detection. Healthcare providers prescribe oral antidiabetic drugs as a first-line treatment in many cases. The convenience of oral administration enhances patient compliance and treatment continuity. It allows for scalable distribution in both developed and developing healthcare systems. Governments and NGOs actively implement diabetes awareness campaigns, increasing diagnosis and treatment. This sustained demand strengthens the market position for leading pharmaceutical players.
- For instance, Novo Nordisk reported reaching over 36 million patients globally in 2023 through its range of oral and injectable antidiabetic products, demonstrating its large-scale impact on access to diabetes care.
Product Innovation and Drug Class Expansion Driving Therapeutic Adoption:
Manufacturers actively innovate to introduce next-generation drug classes, such as SGLT2 inhibitors and DPP-4 inhibitors, which offer improved efficacy and safety profiles. These novel therapies reduce blood glucose levels without causing hypoglycemia, a major side effect in traditional drugs. The Global Oral Antidiabetic Drugs (OADs) Market gains momentum through the integration of dual and triple combination drugs in a single pill. It supports simplified treatment protocols and better patient adherence. Pharmaceutical companies focus on differentiating their products through extended-release formulations and once-daily dosing. These innovations enable physicians to customize therapy based on patient risk and comorbidities. Drug pipelines remain active with numerous candidates in late-stage trials. This innovation pipeline fosters a competitive and evolving therapeutic landscape.
- For instance, Eli Lilly’s Jardiance (empagliflozin), an SGLT2 inhibitor, demonstrated a 38% reduction in cardiovascular death or hospitalization for heart failure in the EMPEROR-Reduced trial, highlighting the expanding role of OADs in comorbidity management.
Government Health Policies and Insurance Access Expanding Treatment Coverage:
Public health systems worldwide prioritize diabetes management due to its long-term economic and societal burden. Governments expand reimbursement frameworks and healthcare access for chronic disease treatment. In countries like the U.S., Germany, and Japan, insurance plans cover most oral diabetes medications. This broadens treatment reach and drives prescription volumes. The Global Oral Antidiabetic Drugs (OADs) Market responds by aligning with public health goals and access initiatives. Emerging economies also invest in universal healthcare schemes and essential medicine access programs. It supports increased availability of generic OADs in low- and middle-income regions. These programs strengthen long-term treatment outcomes while boosting market demand. Pharmaceutical manufacturers benefit from consistent and predictable revenue streams through public procurement.
Growing Elderly Population Driving Chronic Disease Therapeutic Demand:
The global aging trend directly impacts the demand for oral antidiabetic drugs, with older populations at higher risk for type 2 diabetes. Aging leads to reduced glucose tolerance and insulin sensitivity, requiring long-term pharmacological intervention. The Global Oral Antidiabetic Drugs (OADs) Market benefits from this demographic shift. It supports increased focus on therapies tailored for geriatric patients, such as low-risk, easy-to-administer formulations. Pharmaceutical firms actively invest in patient-centric drug delivery formats, including blister packs and memory aid packaging. Healthcare providers prefer oral medications for elderly patients over injectable therapies. The growing focus on geriatric care management further integrates these drugs into long-term treatment plans. This driver is expected to remain a stable growth contributor for the market.
Market Trends:
Personalized Diabetes Therapy Gaining Traction in Drug Development and Delivery:
Personalized treatment is reshaping diabetes management, with pharmacogenomics influencing how therapies are prescribed. Patients respond differently to oral antidiabetic drugs based on genetic and lifestyle factors. The Global Oral Antidiabetic Drugs (OADs) Market adapts by supporting precision medicine approaches in drug development. Pharmaceutical companies explore biomarkers that predict drug efficacy and tolerability. It allows for targeted treatment and reduced trial-and-error prescriptions. Wearable glucose monitors and digital health platforms complement this shift, offering real-time feedback on therapy outcomes. Clinicians use this data to tailor therapy adjustments. Companies that invest in integrating digital tools with drug products gain a competitive edge in personalized care.
- For instance, Sanofi has partnered with Abbott to integrate continuous glucose monitoring data from FreeStyle Libre with their digital health platform, enabling data-driven therapy adjustments for over 4.5 million users as of 2023.
Fixed-Dose Combination Pills Enhancing Convenience and Driving Market Preference:
Demand for fixed-dose combinations (FDCs) has grown significantly due to improved treatment adherence and reduced pill burden. FDCs integrate multiple active ingredients, streamlining patient therapy. In the Global Oral Antidiabetic Drugs (OADs) Market, companies develop FDCs that combine drugs from different classes like metformin and DPP-4 inhibitors. These combinations optimize glucose control while reducing the need for multiple prescriptions. It enhances patient convenience and minimizes dose complexity. Regulatory bodies increasingly approve such therapies, given clinical data supporting efficacy and safety. FDCs gain popularity in regions with high diabetes prevalence and limited follow-up access. Pharmacies stock FDCs due to better patient compliance outcomes. Manufacturers use this format to boost brand loyalty and simplify supply chains.
- For instance, Merck’s Janumet, a fixed-dose combination of sitagliptin and metformin for type 2 diabetes, remains an FDA-approved, widely prescribed oral medication, available in various strengths and prescribed as once or twice daily dosing for optimal effect.
Digital Health Integration Transforming Monitoring and Adherence Support:
Technology integration in chronic disease management influences the oral antidiabetic drugs landscape. Digital tools help monitor glucose levels and track medication adherence. The Global Oral Antidiabetic Drugs (OADs) Market sees increasing partnerships between pharmaceutical companies and health tech firms. Apps and connected devices provide personalized feedback and reminders. It improves patient engagement and empowers better disease control. Some manufacturers bundle medication with companion apps or coaching platforms. These tools collect data for physicians to adjust prescriptions efficiently. Regulatory authorities show growing support for digitally-enabled therapy models. It represents a convergence of drug therapy and digital behavior support.
Sustainability in Manufacturing and Packaging Gaining Strategic Importance:
Environmental responsibility influences drug production strategies, including those in the oral antidiabetic segment. Companies in the Global Oral Antidiabetic Drugs (OADs) Market adopt sustainable practices in manufacturing, energy use, and packaging. It aligns with investor and stakeholder expectations for ESG compliance. Green chemistry methods and eco-friendly solvents reduce environmental impact. Recyclable packaging and efficient supply chain models also gain traction. Pharmaceutical firms publish annual sustainability targets linked to drug portfolios. These efforts build brand value and meet procurement criteria in government contracts. Consumers show growing preference for ethical pharmaceutical brands. Sustainability trends shape long-term strategic planning and influence market reputation.
Market Challenges Analysis:
Regulatory Complexity and Varying Approval Timelines Slowing Global Market Access:
Obtaining regulatory approval across regions presents a significant challenge for pharmaceutical firms. Authorities in the U.S., Europe, and Asia apply different approval standards and clinical requirements. This lack of harmonization delays product entry into high-potential markets. The Global Oral Antidiabetic Drugs (OADs) Market faces high costs for conducting region-specific trials and submitting documentation. It strains small and mid-sized companies with limited budgets. Drug recalls and safety concerns can damage public trust and restrict adoption. Post-marketing surveillance requirements increase administrative burdens. Complex pricing regulations in Europe and reimbursement limitations in emerging countries further impact profitability. Companies must navigate these hurdles strategically to ensure successful commercialization.
Generic Competition and Price Erosion Threatening Profit Margins:
Patent expirations expose branded drugs to generic competition, sharply reducing pricing power. The Global Oral Antidiabetic Drugs (OADs) Market sees significant pricing pressure in both developed and developing markets. Generics often dominate formularies due to lower cost, forcing originator companies to compete on price. It limits revenue potential and reduces incentives for further R&D investment. Government price controls and tenders accelerate this erosion, especially in Asia Pacific and Latin America. Patients may shift between brands due to availability or insurance restrictions. Brand loyalty diminishes in high-volume, low-margin segments. Sustaining profitability under such conditions requires continuous product innovation and operational efficiency.
Market Opportunities:
Expanding Healthcare Infrastructure in Emerging Markets Unlocking Growth Potential:
Rapid urbanization, rising disposable income, and government-led health reforms create strong demand for diabetes care in emerging countries. The Global Oral Antidiabetic Drugs (OADs) Market can expand its footprint in Southeast Asia, Latin America, and Africa. These regions prioritize essential medicine access and universal coverage. It opens distribution opportunities for generics and affordable branded drugs. Local partnerships support market penetration through tailored outreach and education. The shift in treatment-seeking behavior fuels demand for oral therapies due to convenience.
Innovation in Drug Formulations and Digital Integration Enhancing Market Differentiation:
Pharmaceutical firms can invest in novel formulations such as extended-release tablets, chewable forms, and dual-mechanism agents. These innovations enhance patient outcomes and adherence. The Global Oral Antidiabetic Drugs (OADs) Market benefits from bundling products with digital adherence tools or real-time glucose monitoring systems. It provides added value and appeals to tech-savvy consumers. Personalized therapy platforms and AI-assisted dosing support open new commercialization pathways.
Market Segmentation Analysis:
By Drugs
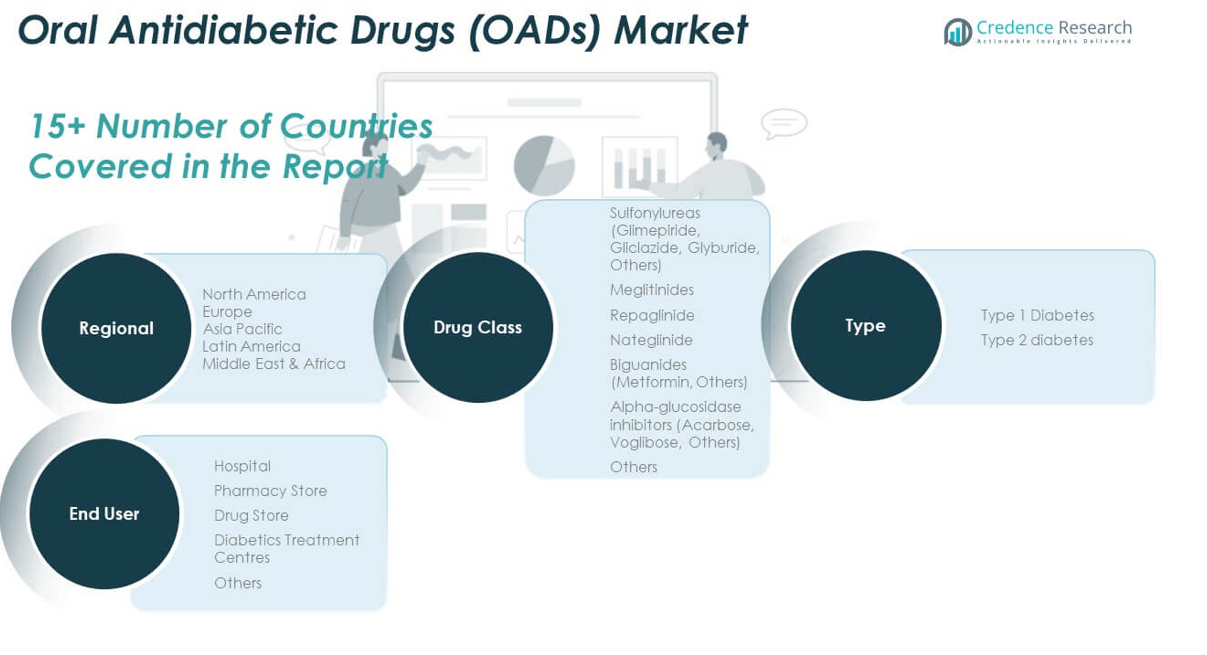
The Global Oral Antidiabetic Drugs (OADs) Market includes multiple drug classes, with biguanides, especially metformin, maintaining dominance due to their proven safety, cost-effectiveness, and primary use in early-stage type 2 diabetes. Sulfonylureas such as glimepiride, gliclazide, and glyburide continue to hold a sizable share but are gradually declining due to concerns over hypoglycemia. Meglitinides, including repaglinide and nateglinide, offer short-acting glucose control and are prescribed for patients with erratic meal patterns. Alpha-glucosidase inhibitors like acarbose and voglibose serve targeted populations, particularly in Asia. The "others" category covers evolving oral agents used in combination therapies.
- For instance, Bristol Myers Squibb’s Glucophage (metformin), originally launched in the 1990s, remains the most widely prescribed oral antidiabetic globally, with over 120 million annual prescriptions in the United States alone.
By Type
The market is segmented into Type 1 and Type 2 diabetes. Type 2 dominates due to its global prevalence and the growing need for oral therapeutic options. Oral antidiabetic drugs are typically first-line interventions in type 2 diabetes, whereas type 1 diabetes primarily requires insulin. Some oral drugs are being evaluated as adjuncts in type 1 care, but adoption remains limited.
- For instance, AstraZeneca’s SGLT2 inhibitor, dapagliflozin, received FDA approval in 2021 as an adjunct to insulin in type 1 diabetes for patients with a BMI ≥ 27 kg/m², demonstrating its expanding application across diabetes types while remaining limited in total patient adoption.
By End-user
Hospitals and pharmacy stores lead in drug distribution, supported by structured prescriptions and regular patient monitoring. Drug stores offer wider access in semi-urban and rural regions, especially in emerging markets. Diabetics treatment centres contribute to specialized care and are expanding in urban areas. Others, such as private clinics and online pharmacies, are emerging as alternative channels. The Global Oral Antidiabetic Drugs (OADs) Market adapts across these end-user segments to expand access, improve outcomes, and support diverse healthcare systems.
Segmentation:
By Drugs
- Sulfonylureas (Glimepiride, Gliclazide, Glyburide, Others)
- Meglitinides
- Repaglinide
- Nateglinide
- Biguanides (Metformin, Others)
- Alpha-glucosidase Inhibitors (Acarbose, Voglibose, Others)
- Others
By Type
- Type 1 Diabetes
- Type 2 Diabetes
By End-user
- Hospitals
- Pharmacy Stores
- Drug Stores
- Diabetics Treatment Centres
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Oral Antidiabetic Drugs (OADs) Market size was valued at USD 13,762.50 million in 2018 to USD 15,811.51 million in 2024 and is anticipated to reach USD 22,489.17 million by 2032, at a CAGR of 4.6% during the forecast period. North America accounted for approximately 36.2% of the global market share in 2024. The region benefits from advanced healthcare infrastructure, widespread diabetes screening programs, and a high level of patient awareness. The U.S. leads in terms of drug adoption due to insurance coverage and access to innovative therapies. It also serves as a major hub for clinical trials and regulatory approvals. Pharmaceutical firms prioritize this market for product launches and partnerships. Canada and Mexico contribute through expanding access to chronic disease treatments. Market growth is supported by increasing type 2 diabetes incidence and strong adoption of DPP-4 and SGLT2 inhibitors. The Global Oral Antidiabetic Drugs (OADs) Market remains highly competitive in this region due to the presence of leading global pharmaceutical companies.
Europe
The Europe Oral Antidiabetic Drugs (OADs) Market size was valued at USD 9,536.25 million in 2018 to USD 10,643.19 million in 2024 and is anticipated to reach USD 14,287.95 million by 2032, at a CAGR of 3.8% during the forecast period. Europe held nearly 24.4% of the global market share in 2024. The region shows strong regulatory support and reimbursement coverage for oral diabetic therapies. Germany, France, and the UK drive significant demand through public health systems and early adoption of fixed-dose combinations. It maintains a balance between branded and generic drugs due to cost-control policies. Eastern Europe shows rising drug uptake supported by improved healthcare infrastructure. Pharmaceutical companies target regional guidelines to align with treatment protocols. The market benefits from an aging population and rising obesity-related complications. Research collaborations and public-private initiatives sustain long-term market engagement in this region.
Asia Pacific
The Asia Pacific Oral Antidiabetic Drugs (OADs) Market size was valued at USD 9,037.50 million in 2018 to USD 10,982.15 million in 2024 and is anticipated to reach USD 17,284.51 million by 2032, at a CAGR of 5.9% during the forecast period. Asia Pacific captured approximately 25.2% of the global market share in 2024. The region leads in growth rate due to its rapidly expanding diabetic population and urbanization. China and India dominate in terms of volume, supported by growing healthcare investments and large patient bases. It attracts multinational drug manufacturers seeking scalable market access. Government-led screening initiatives and national diabetes programs drive diagnosis and treatment rates. Japan and South Korea contribute with advanced therapeutic adoption and digital integration. Local manufacturing and generic availability improve affordability in Southeast Asia. The Global Oral Antidiabetic Drugs (OADs) Market is poised for expansion in this region due to rising middle-class healthcare consumption.
Latin America
The Latin America Oral Antidiabetic Drugs (OADs) Market size was valued at USD 2,718.75 million in 2018 to USD 3,134.88 million in 2024 and is anticipated to reach USD 4,184.17 million by 2032, at a CAGR of 3.7% during the forecast period. Latin America accounted for around 7.2% of the global market share in 2024. Brazil leads the region with strong urban demand and an expanding public healthcare network. Argentina and Mexico are adopting more oral therapies due to rising diabetes awareness. Economic constraints pose pricing challenges but also drive demand for cost-effective generics. It presents opportunities for branded generics and government procurement programs. Urbanization and lifestyle shifts increase type 2 diabetes risk across the region. Private sector expansion in healthcare supports drug distribution and access. The market shows consistent growth driven by broader access and improved patient education.
Middle East
The Middle East Oral Antidiabetic Drugs (OADs) Market size was valued at USD 1,503.75 million in 2018 to USD 1,643.69 million in 2024 and is anticipated to reach USD 2,124.41 million by 2032, at a CAGR of 3.3% during the forecast period. The region held approximately 3.8% of the global market share in 2024. Gulf Cooperation Council (GCC) countries dominate due to high per capita healthcare spending and rising obesity-related diabetes cases. Urban populations adopt newer oral therapies quickly, supported by private healthcare providers. It benefits from national strategies targeting non-communicable diseases. Multinational companies partner with local distributors to strengthen access. Public health campaigns improve disease awareness and diagnosis rates. Market expansion continues in Saudi Arabia and UAE, where digital platforms enhance adherence. The Global Oral Antidiabetic Drugs (OADs) Market finds favorable conditions in this region through private-public health collaboration.
Africa
The Africa Oral Antidiabetic Drugs (OADs) Market size was valued at USD 941.25 million in 2018 to USD 1,391.23 million in 2024 and is anticipated to reach USD 1,737.09 million by 2032, at a CAGR of 2.5% during the forecast period. Africa contributed approximately 3.2% of the global market share in 2024. The region faces challenges due to limited healthcare infrastructure and late-stage diabetes diagnosis. South Africa leads in drug consumption through both public and private channels. Egypt shows increasing adoption driven by national diabetes programs. It presents unmet needs in access to essential medicines and diagnostic services. NGOs and global health initiatives support treatment availability in rural areas. Urban centers show higher uptake of oral antidiabetic drugs. Pharmaceutical firms explore local manufacturing and affordability strategies to serve this diverse and growing market.
Key Player Analysis:
- Sanofi S.A.
- Eli Lilly and Company
- AstraZeneca plc
- Astellas Pharma Inc.
- Johnson & Johnson (Janssen Pharmaceuticals)
- Boehringer Ingelheim
- Merck & Co.
- Takeda Pharmaceutical Company Limited
- Bristol Myers Squibb
- Novartis AG
- Pfizer Inc.
Competitive Analysis:
The Global Oral Antidiabetic Drugs (OADs) Market is highly competitive, with several multinational pharmaceutical companies holding strong market positions. Key players include Sanofi, Eli Lilly, AstraZeneca, Boehringer Ingelheim, Merck & Co., Johnson & Johnson, and Novartis. It is characterized by robust R&D pipelines, strategic collaborations, and frequent product launches aimed at expanding therapeutic portfolios. Companies focus on developing fixed-dose combinations, extended-release formulations, and innovative drug classes like SGLT2 and DPP-4 inhibitors. Patent expirations continue to drive generic competition, particularly in cost-sensitive regions. Market leaders differentiate through advanced clinical trial outcomes, regulatory approvals, and global marketing capabilities. Competitive intensity is high in both branded and generic segments.
Recent Developments:
- In July 2025, Sanofi S.A. entered an exclusive distribution partnership with Emcure Pharmaceuticals to broaden the reach of its oral antidiabetic drugs in India. Under this agreement, Emcure will distribute and promote Sanofi’s oral antidiabetic portfolio, including leading brands such as Amaryl (glimepiride) and Cetapin (metformin), allowing more patients across India to access these medications.
- In April 2025, Eli Lilly and Company announced that its oral GLP-1 agonist pill, orforglipron, successfully completed Phase 3 trials. Orforglipron demonstrated clinically meaningful reductions in HbA1c and body weight in adults with type 2 diabetes, and Lilly plans to submit for FDA approval as a type 2 diabetes treatment in 2026, with weight management submissions to follow globally later in 2025.
- In July 2025, Boehringer Ingelheim launched the THULITE phase 2 clinical study to evaluate the efficacy and safety of BI 1815368, an oral medication for diabetic macular edema, a complication of diabetes. This trial signals Boehringer Ingelheim’s continued investment in novel oral therapies targeting diabetes complications.
- In July 2025, Merck & Co. reported encouraging topline results from the first two Phase 3 trials of enlicitide, its oral PCSK9 inhibitor, showing significant LDL-cholesterol reduction. Although primarily for hyperlipidemia, these advancements indicate Merck’s continued focus on metabolic disease research with crossover relevance to type 2 diabetes.
Market Concentration & Characteristics:
The Global Oral Antidiabetic Drugs (OADs) Market is moderately concentrated, with a few leading players dominating global revenues through extensive product portfolios and wide distribution networks. It features a mix of branded and generic drugs, with branded therapies holding a premium in developed regions. Market dynamics vary by geography, with innovation driving growth in developed economies and cost-efficiency guiding trends in emerging markets. It responds to changing clinical guidelines, rising demand for personalized therapies, and patient-centric delivery models. Growth remains steady due to the chronic nature of diabetes and consistent demand across demographics.
Report Coverage:
The research report offers an in-depth analysis based on drug class, type of diabetes, and end-user segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will rise steadily with the increasing global prevalence of type 2 diabetes and expanding elderly population.
- Product innovation will focus on safer, more effective drug classes such as SGLT2 and DPP-4 inhibitors.
- Fixed-dose combinations and once-daily regimens will enhance patient adherence and drive adoption.
- Digital integration and remote monitoring will support personalized therapy and adherence programs.
- Emerging markets in Asia Pacific and Latin America will offer strong growth potential due to rising healthcare investments.
- Generic drug penetration will intensify, particularly in cost-sensitive regions with growing diabetic populations.
- Reimbursement expansions and public health initiatives will widen treatment access in developing nations.
- Collaborations between pharma and tech firms will enable data-driven disease management.
- Regulatory bodies will increasingly favor fast-track approvals for innovative and affordable therapies.
- Market competition will remain high, pushing companies to differentiate through R&D, pricing, and global outreach.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Type 2 Diabetes
The global increase in type 2 diabetes, driven by sedentary lifestyles, obesity, and aging populations, is fueling sustained demand for oral antidiabetic drugs as first-line therapy, especially in both developed and emerging markets.
Product Innovation in Drug Classes
Pharmaceutical companies are investing in novel drug classes such as SGLT2 and DPP-4 inhibitors, as well as fixed-dose combinations and extended-release formulations, which offer improved efficacy, safety, and patient adherence, thereby driving market growth.
Expanding Healthcare Access and Insurance Coverage
Broader healthcare infrastructure, government reimbursement policies, and insurance coverage in both developed and developing countries are increasing patient access to oral antidiabetic drugs, supporting higher prescription volumes and market expansion.
Growing Elderly Population
The rising proportion of elderly individuals, who are at higher risk for type 2 diabetes and require long-term pharmacological management, is boosting demand for oral antidiabetic drugs tailored to geriatric needs and chronic disease management.
Digital Health Integration and Personalized Therapy
The integration of digital health tools, such as glucose monitoring apps and personalized therapy platforms, is enhancing patient engagement, adherence, and outcomes, supporting the adoption and differentiation of oral antidiabetic therapies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Oral Antidiabetic Drugs (OADs) Market?
What factors are driving the growth of the Global Oral Antidiabetic Drugs (OADs) Market?
What are the key segments within the Global Oral Antidiabetic Drugs (OADs) Market?
Who are the major players in the Global Oral Antidiabetic Drugs (OADs) Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Type 1 Diabetes
- 1.2.2 Type 2 Diabetes
- 1.3 By Drugs
- 1.3.1 Sulfonylureas (Glimepiride, Gliclazide, Glyburide, Others)
- 1.3.2 Meglitinides (Repaglinide, Nateglinide)
- 1.3.3 Biguanides (Metformin, Others)
- 1.3.4 Alpha-glucosidase Inhibitors (Acarbose, Voglibose, Others)
- 1.3.5 Others
- 1.4 By End-user
- 1.4.1 Hospitals
- 1.4.2 Pharmacy Stores
- 1.4.3 Drug Stores
- 1.4.4 Diabetics Treatment Centres
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 43,606.66 million → 2032: USD 62,107.31 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Oral Antidiabetic Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Oral Antidiabetic Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Oral Antidiabetic Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Oral Antidiabetic Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Oral Antidiabetic Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Oral Antidiabetic Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Oral Antidiabetic Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Oral Antidiabetic Drugs Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 43,606.66 million → 2032: USD 62,107.31 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Oral Antidiabetic Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Type 1 Diabetes
- 12.3.7.2 Type 2 Diabetes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Drugs - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Sulfonylureas (Glimepiride, Gliclazide, Glyburide, Others)
- 12.4.7.2 Meglitinides (Repaglinide, Nateglinide)
- 12.4.7.3 Biguanides (Metformin, Others)
- 12.4.7.4 Alpha-glucosidase Inhibitors (Acarbose, Voglibose, Others)
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-user - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals
- 12.5.7.2 Pharmacy Stores
- 12.5.7.3 Drug Stores
- 12.5.7.4 Diabetics Treatment Centres
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Oral Antidiabetic Drugs End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Oral Antidiabetic Drugs Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Oral Antidiabetic Drugs Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Oral Antidiabetic Drugs Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sanofi S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Eli Lilly and Company
- 18.4 AstraZeneca plc
- 18.5 Astellas Pharma Inc.
- 18.6 Johnson & Johnson (Janssen Pharmaceuticals)
- 18.7 Boehringer Ingelheim
- 18.8 Merck & Co.
- 18.9 Takeda Pharmaceutical Company Limited
- 18.10 Bristol Myers Squibb
- 18.11 Novartis AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

