
Market Overview
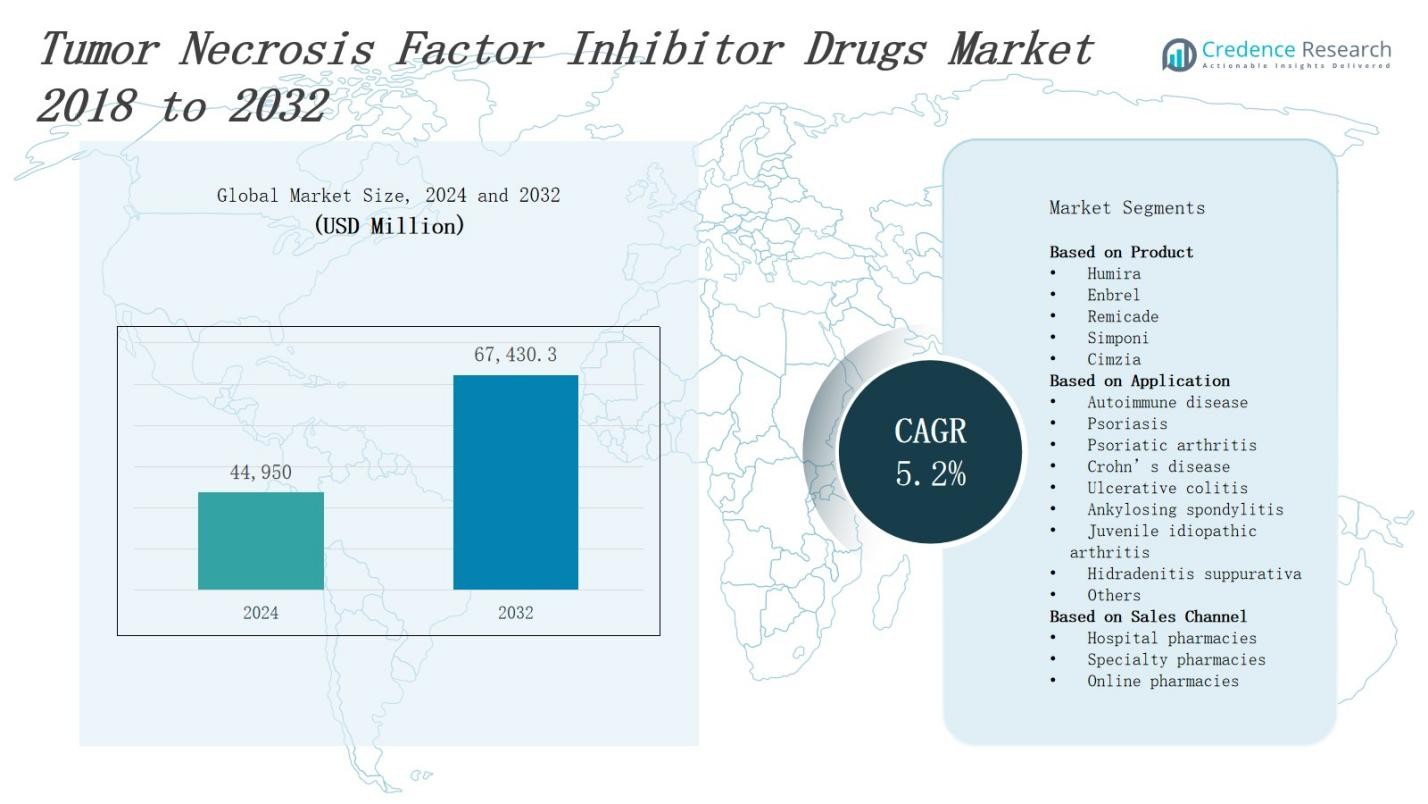
The Tumor Necrosis Factor Inhibitor Drugs Market is projected to grow from USD 44,950 million in 2024 to USD 67,430.3 million by 2032, expanding at a CAGR of 5.2%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Tumor Necrosis Factor Inhibitor Drugs Market Size 2024 | USD 44,950 Million |
| Tumor Necrosis Factor Inhibitor Drugs Market, CAGR | 5.2% |
| Tumor Necrosis Factor Inhibitor Drugs Market Size 2032 | USD 67,430.3 Million |
The tumor necrosis factor inhibitor drugs market grows driven by increasing prevalence of autoimmune diseases such as rheumatoid arthritis, psoriasis, and inflammatory bowel disease. Rising awareness and early diagnosis boost demand for effective treatments. Advances in biologic therapies enhance drug efficacy and safety profiles, encouraging physician adoption. Expanding access to healthcare in emerging markets further supports growth. Trends include the development of biosimilars to reduce treatment costs and improve affordability. Additionally, personalized medicine approaches and combination therapies gain traction, optimizing patient outcomes. Continuous innovation and strong pipeline development sustain competitive momentum in this dynamic market.
The tumor necrosis factor inhibitor drugs market spans key regions including North America, Europe, Asia-Pacific, and the Rest of the World. North America leads with 38% market share, followed by Europe at 29%, Asia-Pacific at 22%, and the Rest of the World holding 11%. Major players driving growth across these regions include AbbVie Inc., Janssen Biotech, Amgen Inc., Pfizer Inc., Merck & Co., and Samsung Bioepis. These companies focus on expanding regional presence through product innovation, biosimilar development, and strategic collaborations to capture diverse patient populations.
Market Insights
- The tumor necrosis factor inhibitor drugs market is projected to grow from USD 44,950 million in 2024 to USD 67,430 million by 2032, at a CAGR of 5.2%.
- Increasing prevalence of autoimmune diseases like rheumatoid arthritis, psoriasis, and inflammatory bowel disease drives demand for effective treatments.
- Advances in biologic therapies improve drug efficacy and safety, boosting physician adoption and patient compliance.
- Expanding healthcare access in emerging markets supports market growth by reaching new patient populations.
- Development and adoption of biosimilars reduce treatment costs and enhance affordability, especially in price-sensitive regions.
- Personalized medicine and combination therapies gain traction, optimizing patient outcomes and treatment customization.
- North America leads with 38% market share, followed by Europe at 29%, Asia-Pacific at 22%, and the Rest of the World at 11%, driven by regional healthcare infrastructure and policies.
Market Drivers
Rising Prevalence of Autoimmune Diseases
The tumor necrosis factor inhibitor drugs market benefits from the growing prevalence of autoimmune disorders such as rheumatoid arthritis, psoriasis, and Crohn’s disease worldwide. Increasing patient populations create steady demand for effective therapeutic options. Early diagnosis and improved disease awareness among healthcare professionals drive prescription rates. Patients seek targeted therapies that manage symptoms and improve quality of life. This growing patient base propels market expansion and encourages further drug development.
- For instance, infliximab, a TNF-targeting monoclonal antibody developed by Janssen, is FDA-approved for Crohn’s disease, rheumatoid arthritis, and psoriasis, and works by blocking TNF to reduce inflammation.
Advancements in Biologic Therapies
Innovations in biologic drugs enhance the efficacy and safety of tumor necrosis factor inhibitors, encouraging physician preference and patient compliance. It enables treatment customization based on patient needs and disease severity. New formulations offer improved delivery methods and reduced side effects. Ongoing clinical trials focus on expanding indications and refining therapeutic protocols. These advancements maintain strong market momentum and support adoption across diverse healthcare settings.
- For instance, AbbVie's Humira, a leading TNF inhibitor, continues to demonstrate high effectiveness in multiple autoimmune disorders such as rheumatoid arthritis and Crohn’s disease, supported by extensive clinical data that enhance physician confidence and patient trust.
Expansion of Healthcare Access in Emerging Markets
The tumor necrosis factor inhibitor drugs market gains from increasing healthcare infrastructure and insurance coverage in developing regions. Enhanced access to medical services and rising disposable incomes expand patient reach. Governments and private sectors invest in disease awareness programs and treatment availability. It creates new growth opportunities beyond traditional markets. Expansion in emerging economies diversifies revenue streams and strengthens global market presence.
Development and Adoption of Biosimilars
Biosimilars present cost-effective alternatives to original tumor necrosis factor inhibitors, reducing treatment expenses and increasing affordability. Growing acceptance among physicians and patients supports wider biosimilar use. Regulatory frameworks become more favorable, accelerating approval and market entry. This drives competitive pricing and broader insurance reimbursement. It encourages market penetration in price-sensitive regions and stimulates overall demand for inhibitor therapies.
Market Trends
Increasing Adoption of Biosimilars to Enhance Market Affordability
The tumor necrosis factor inhibitor drugs market experiences a growing shift toward biosimilars, which provide cost-effective alternatives to original biologics. It enables broader patient access by lowering treatment costs and expanding insurance coverage. Physicians show increased confidence in biosimilars due to improved regulatory standards and demonstrated clinical equivalence. Competitive pricing among manufacturers drives market penetration, especially in price-sensitive regions. The trend supports sustainable growth while maintaining therapeutic efficacy.
- For instance, Amgen launched Amjevita, a biosimilar of Humira (adalimumab), which has gained significant market share in the U.S. by offering a cost-effective alternative while maintaining clinical equivalence.
Integration of Personalized Medicine in Treatment Approaches
Personalized medicine gains traction within the tumor necrosis factor inhibitor drugs market, allowing tailored therapies based on genetic and biomarker profiles. It improves treatment outcomes by optimizing drug selection and dosage for individual patients. Clinicians increasingly rely on diagnostic tools to identify responders and reduce adverse effects. This approach enhances patient adherence and long-term disease management. Personalized strategies reflect a trend toward precision healthcare that transforms treatment paradigms in autoimmune disorders.
Expansion of Combination Therapy Practices to Improve Efficacy
Combination therapies that include tumor necrosis factor inhibitors alongside other immunomodulatory agents gain popularity for managing complex autoimmune diseases. It offers synergistic effects that improve symptom control and reduce disease progression. Healthcare providers adopt these protocols to address varied patient responses and enhance overall efficacy. Clinical research continues to explore novel drug combinations and dosing regimens. This trend contributes to diversified treatment options and improved patient outcomes within the market.
- For instance, Novartis is also investigating secukinumab paired with conventional immunosuppressants in psoriatic arthritis to address varied patient responses and optimize treatment efficacy.
Advances in Drug Delivery Systems to Boost Patient Compliance
Innovations in drug delivery methods enhance the tumor necrosis factor inhibitor drugs market by improving convenience and reducing administration-related discomfort. It includes the development of pre-filled syringes, auto-injectors, and subcutaneous formulations. These technologies simplify dosing schedules and minimize hospital visits. Patient compliance improves, leading to better disease control and reduced healthcare costs. The focus on user-friendly delivery aligns with broader efforts to optimize treatment experience and adherence.
Market Challenges Analysis
High Treatment Costs and Reimbursement Barriers Limit Market Growth
The tumor necrosis factor inhibitor drugs market faces challenges related to the high cost of biologic therapies, which restricts patient access in several regions. It creates financial burdens for healthcare systems and patients, particularly where insurance coverage remains limited or inconsistent. Payers impose stringent reimbursement criteria that delay or deny treatment approval. This situation hampers market expansion, especially in low- and middle-income countries. Manufacturers and policymakers must address affordability to ensure wider adoption and sustainable growth.
Safety Concerns and Risk of Adverse Effects Impact Adoption Rates
Safety issues linked to tumor necrosis factor inhibitors pose significant challenges for market acceptance and long-term use. It carries risks of infections, immunogenic reactions, and other serious side effects that necessitate careful patient monitoring. Concerns over safety influence physician prescribing behavior and patient compliance. Ongoing pharmacovigilance and post-market surveillance require substantial resources. These factors complicate treatment protocols and may limit uptake, especially among patients with comorbidities or compromised immune systems.
Market Opportunities
Expanding Indications and Emerging Therapeutic Areas Drive Market Potential
The tumor necrosis factor inhibitor drugs market gains significant opportunities from expanding indications beyond traditional autoimmune diseases. It explores applications in conditions such as hidradenitis suppurativa, uveitis, and certain rare inflammatory disorders. Clinical trials investigating novel uses broaden therapeutic scope and patient populations. This expansion increases demand and encourages innovation in drug development. Growing interest in early intervention strategies further supports market growth by targeting disease progression and improving long-term outcomes.
Growth Potential in Emerging Markets through Improved Healthcare Infrastructure
Emerging markets offer promising opportunities for the tumor necrosis factor inhibitor drugs market due to rising healthcare investments and expanding insurance coverage. It benefits from increasing awareness of autoimmune diseases and improved diagnostic capabilities. Government initiatives focus on enhancing treatment accessibility and affordability in these regions. Collaborations between local and global pharmaceutical companies accelerate market penetration. Expanding patient populations and rising disposable incomes also contribute to revenue growth, positioning emerging markets as key drivers for future expansion.
Market Segmentation Analysis:
By Product
The tumor necrosis factor inhibitor drugs market divides into key products including Humira, Enbrel, Remicade, Simponi, and Cimzia. Humira leads due to its wide approval across multiple indications and strong physician preference. Enbrel and Remicade hold significant market shares supported by established clinical data and global presence. Simponi and Cimzia target specific patient groups with differentiated delivery methods. It benefits from continuous product lifecycle management and patent expirations driving biosimilar competition within this segment.
- For instance, Humira (adalimumab) is approved for multiple chronic inflammatory conditions, including rheumatoid arthritis, Crohn's disease, and psoriasis, and is available in various administration forms such as prefilled pens and syringes, with several interchangeable biosimilars approved by the FDA as recent as 2024.
By Application
The tumor necrosis factor inhibitor drugs market covers a broad range of autoimmune and inflammatory conditions. It addresses autoimmune diseases, psoriasis, psoriatic arthritis, Crohn’s disease, ulcerative colitis, ankylosing spondylitis, juvenile idiopathic arthritis, and hidradenitis suppurativa. Autoimmune diseases and psoriasis remain the largest application areas due to high prevalence. Emerging indications such as hidradenitis suppurativa contribute to incremental growth. The diverse application base supports steady demand and encourages tailored therapeutic development.
- For instance, infliximab, a monoclonal antibody drug developed by Janssen, is FDA-approved for Crohn’s disease, rheumatoid arthritis, ankylosing spondylitis, and chronic plaque psoriasis, demonstrating broad therapeutic use across autoimmune conditions.
By Sales Channel
The tumor necrosis factor inhibitor drugs market distributes products through hospital pharmacies, specialty pharmacies, and online pharmacies. Hospital pharmacies dominate due to direct access in clinical settings and inpatient care. Specialty pharmacies focus on managing complex therapies and patient support programs. Online pharmacies gain traction through convenience and wider reach, particularly in regions with advanced digital infrastructure. It adapts sales strategies to optimize channel efficiency and enhance patient accessibility across geographies.
Segments:
Based on Product
- Humira
- Enbrel
- Remicade
- Simponi
- Cimzia
Based on Application
- Autoimmune disease
- Psoriasis
- Psoriatic arthritis
- Crohn’s disease
- Ulcerative colitis
- Ankylosing spondylitis
- Juvenile idiopathic arthritis
- Hidradenitis suppurativa
- Others
Based on Sales Channel
- Hospital pharmacies
- Specialty pharmacies
- Online pharmacies
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share in the tumor necrosis factor inhibitor drugs market with 38% market dominance. It benefits from a high prevalence of autoimmune diseases and strong healthcare infrastructure. Advanced diagnostics and early disease detection support widespread adoption of these therapies. Favorable reimbursement policies and well-established pharmaceutical distribution networks enhance market penetration. The presence of major biopharmaceutical companies and continuous research investments sustain innovation. It also gains from growing patient awareness and physician preference for biologic treatments. North America remains a critical region for market growth and product launches.
Europe
Europe commands 29% of the tumor necrosis factor inhibitor drugs market, driven by increasing government initiatives promoting access to biologic therapies. It maintains comprehensive healthcare systems and reimbursement frameworks that facilitate patient access. Rising incidence of autoimmune and inflammatory diseases fuels demand. European countries focus on biosimilar adoption to reduce treatment costs and improve affordability. It benefits from active clinical trials and collaborations between public and private sectors. Stringent regulatory standards ensure high-quality therapies, strengthening market confidence and expansion.
Asia-Pacific
Asia-Pacific represents 22% of the tumor necrosis factor inhibitor drugs market, demonstrating the fastest growth trajectory. Rising healthcare expenditure and improving medical infrastructure support market expansion. Increasing disease awareness and expanding middle-class populations drive demand for effective therapies. It experiences growing acceptance of biosimilars due to cost sensitivity and accessibility challenges. Emerging economies implement policies to enhance healthcare coverage and treatment availability. The region attracts investment from global pharmaceutical companies seeking new patient bases and growth opportunities.
Rest of the World
The Rest of the World accounts for 11% of the tumor necrosis factor inhibitor drugs market. It includes Latin America, the Middle East, and Africa, where market growth depends on improving healthcare infrastructure and increasing disease diagnosis rates. It faces challenges such as limited reimbursement and affordability constraints, which slow adoption. Governments and international organizations focus on raising awareness and expanding access to advanced therapies. The market shows potential through gradual penetration of biosimilars and growing patient populations. Strategic partnerships aim to address unmet medical needs and unlock new opportunities.
Key Player Analysis
- Janssen Biotech, Inc.
- Sandoz Group AG
- Merck & Co., Inc.
- AbbVie Inc.
- Bio-Thera Solutions, Ltd.
- Pfizer Inc.
- Samsung Bioepis Co., Ltd.
- Amgen Inc.
- UCB, Inc.
- Boehringer Ingelheim Pharmaceuticals, Inc.
Competitive Analysis
The tumor necrosis factor inhibitor drugs market features intense competition among leading pharmaceutical companies focusing on innovation, product differentiation, and strategic collaborations. Key players such as AbbVie Inc., Janssen Biotech, Inc., Amgen Inc., and Pfizer Inc. compete by expanding their biologic portfolios and launching biosimilars to capture broader patient segments. It emphasizes research and development to improve drug efficacy and safety profiles, addressing unmet medical needs. Competitive pricing strategies and global market expansion drive revenue growth. Partnerships and acquisitions enable companies to enhance manufacturing capabilities and distribution networks. The market’s dynamic landscape demands continuous investment in clinical trials and regulatory approvals to maintain leadership positions and respond to evolving healthcare demands.
Recent Developments
- On February 26, 2025, TNF Pharmaceuticals commenced a Phase 2b clinical trial for isomyosamine, an oral TNF-alpha inhibitor, targeting sarcopenia and frailty in patients post-hip fracture.
- In May 2024, Teva Pharmaceuticals (US) partnered with Alvotech (Luxembourg) to launch SIMLANDI (adalimumab-ryvk) injection in the U.S. This is an interchangeable biosimilar to Humira for treating various autoimmune conditions such as rheumatoid arthritis, Crohn’s disease, and psoriasis.
- In August 2023, CVS Health launched Cordavis, which partners on commercializing FDA-approved biosimilar products including TNF inhibitors in the U.S.
- On April 14, 2025, Sandoz initiated an antitrust lawsuit against Amgen in the U.S. District Court for the Eastern District of Virginia. Sandoz alleges that Amgen unlawfully acquired exclusive rights to certain etanercept-related patents, known as the Brockhaus Patents, to block biosimilar competition.
Market Concentration & Characteristics
The tumor necrosis factor inhibitor drugs market demonstrates a moderately concentrated structure dominated by a few key players, including AbbVie Inc., Janssen Biotech, Amgen Inc., and Pfizer Inc. It features intense competition driven by innovation, patent expirations, and the entry of biosimilars. Market leaders focus on expanding their biologic portfolios and enhancing drug efficacy through continuous research and development. It balances high barriers to entry due to complex manufacturing and regulatory requirements with opportunities created by growing demand for autoimmune disease treatments. The presence of biosimilars intensifies price competition, encouraging affordability and wider adoption. Companies invest in strategic partnerships, acquisitions, and geographic expansion to strengthen market share and diversify offerings. This dynamic competitive environment fosters rapid technological advancements and supports sustained growth in the tumor necrosis factor inhibitor drugs market.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The tumor necrosis factor inhibitor drugs market will expand due to rising autoimmune disease prevalence worldwide.
- Advances in biologic therapies will improve treatment effectiveness and safety profiles.
- Biosimilar development will increase affordability and access to these drugs.
- Emerging markets will become key growth areas with improving healthcare infrastructure.
- Personalized medicine approaches will enhance treatment customization and patient outcomes.
- Combination therapies will gain popularity to address complex autoimmune conditions.
- Digital health technologies will support better disease monitoring and patient adherence.
- Regulatory frameworks will evolve to accelerate biosimilar approvals and market entry.
- Strategic collaborations and partnerships will drive innovation and expand geographic reach.
- Continuous pipeline development will introduce novel inhibitors targeting unmet medical needs.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Autoimmune Diseases
The increasing incidence of autoimmune conditions such as rheumatoid arthritis, psoriasis, and Crohn’s disease is expanding the patient pool, driving sustained demand for tumor necrosis factor inhibitor drugs as effective treatment options.
Advancements in Biologic Therapies
Continuous innovation in biologic drugs has improved the efficacy and safety profiles of TNF inhibitors, leading to greater physician adoption and higher patient compliance, which in turn fuels market growth.
Expansion of Healthcare Access in Emerging Markets
Improved healthcare infrastructure and insurance coverage in developing regions are enabling more patients to access advanced therapies, broadening the market’s geographic reach and supporting overall expansion.
Development and Adoption of Biosimilars
The introduction and growing acceptance of biosimilars are reducing treatment costs and increasing affordability, especially in price-sensitive regions, thereby expanding patient access and driving market penetration.
Personalized Medicine and Combination Therapies
The integration of personalized medicine and combination therapy approaches is optimizing treatment outcomes for patients, increasing the attractiveness and utilization of TNF inhibitor drugs in complex autoimmune disease management.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Tumor necrosis factor inhibitor drugs market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Tumor necrosis factor inhibitor drugs market projected to grow between 2025 and 2032?
Which Tumor necrosis factor inhibitor drugs market segment held the largest share in 2024?
What is the base year considered for Tumor Necrosis Factor (TNF) Inhibitors Market?
What are the primary factors fueling the growth of the Tumor necrosis factor inhibitor drugs market?
Who are the leading companies in the Tumor necrosis factor inhibitor drugs market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Humira
- 1.2.2 Enbrel
- 1.2.3 Remicade
- 1.2.4 Simponi
- 1.2.5 Cimzia
- 1.3 By Application
- 1.3.1 Autoimmune disease
- 1.3.2 Psoriasis
- 1.3.3 Psoriatic arthritis
- 1.3.4 Crohn’s disease
- 1.3.5 Ulcerative colitis
- 1.3.6 Ankylosing spondylitis
- 1.3.7 Juvenile idiopathic arthritis
- 1.3.8 Hidradenitis suppurativa
- 1.3.9 Others
- 1.4 By Sales Channel
- 1.4.1 Hospital pharmacies
- 1.4.2 Specialty pharmacies
- 1.4.3 Online pharmacies
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 44,950 million → 2032: USD 67,430.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Tumor Necrosis Factor Inhibitor Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Tumor Necrosis Factor Inhibitor Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Tumor Necrosis Factor Inhibitor Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Tumor Necrosis Factor Inhibitor Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Tumor Necrosis Factor Inhibitor Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Tumor Necrosis Factor Inhibitor Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Tumor Necrosis Factor Inhibitor Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Tumor Necrosis Factor Inhibitor Drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 44,950 million → 2032: USD 67,430.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Tumor Necrosis Factor Inhibitor Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Humira
- 12.3.7.2 Enbrel
- 12.3.7.3 Remicade
- 12.3.7.4 Simponi
- 12.3.7.5 Cimzia
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Autoimmune disease
- 12.4.7.2 Psoriasis
- 12.4.7.3 Psoriatic arthritis
- 12.4.7.4 Crohn’s disease
- 12.4.7.5 Ulcerative colitis
- 12.4.7.6 Ankylosing spondylitis
- 12.4.7.7 Juvenile idiopathic arthritis
- 12.4.7.8 Hidradenitis suppurativa
- 12.4.7.9 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospital pharmacies
- 12.5.7.2 Specialty pharmacies
- 12.5.7.3 Online pharmacies
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Tumor Necrosis Factor Inhibitor Drugs End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Tumor Necrosis Factor Inhibitor Drugs Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Tumor Necrosis Factor Inhibitor Drugs Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Tumor Necrosis Factor Inhibitor Drugs Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AbbVie Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Janssen Biotech, Inc.
- 18.4 Amgen Inc.
- 18.5 Pfizer Inc.
- 18.6 Merck & Co., Inc.
- 18.7 Samsung Bioepis Co., Ltd.
- 18.8 Sandoz Group AG
- 18.9 UCB, Inc.
- 18.10 Bio-Thera Solutions, Ltd.
- 18.11 Boehringer Ingelheim Pharmaceuticals, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

