
Market Overview
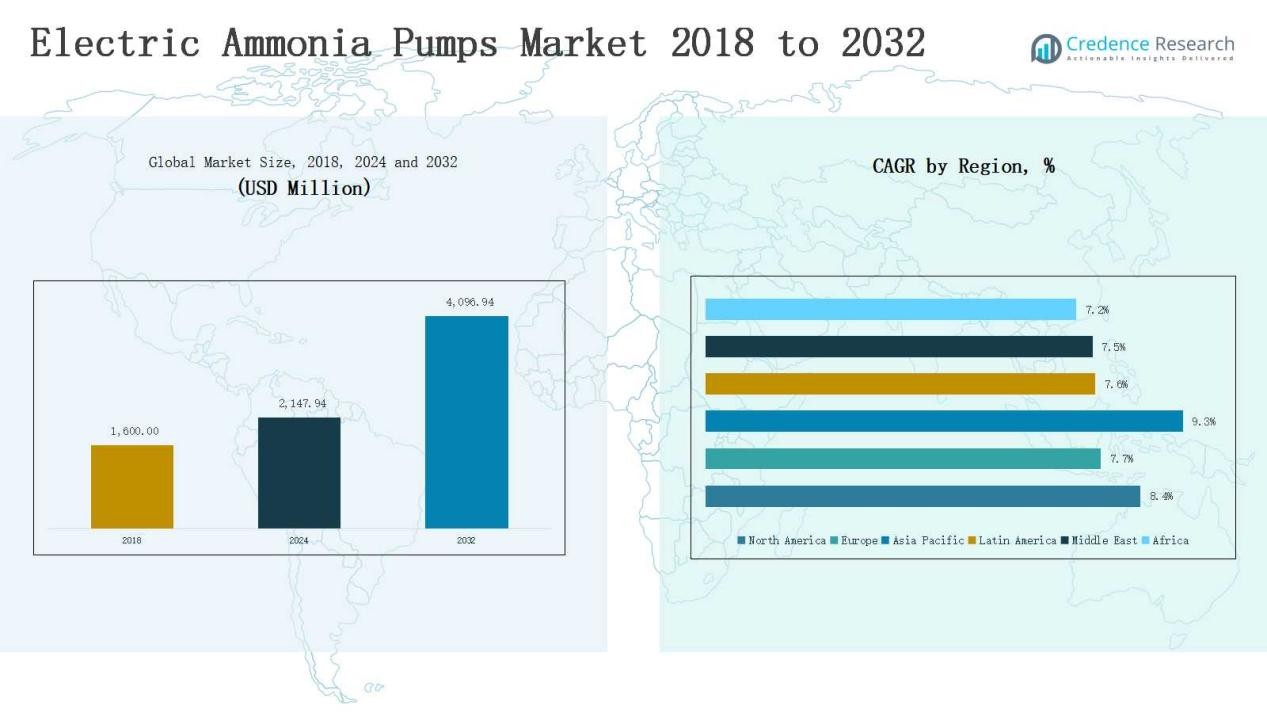
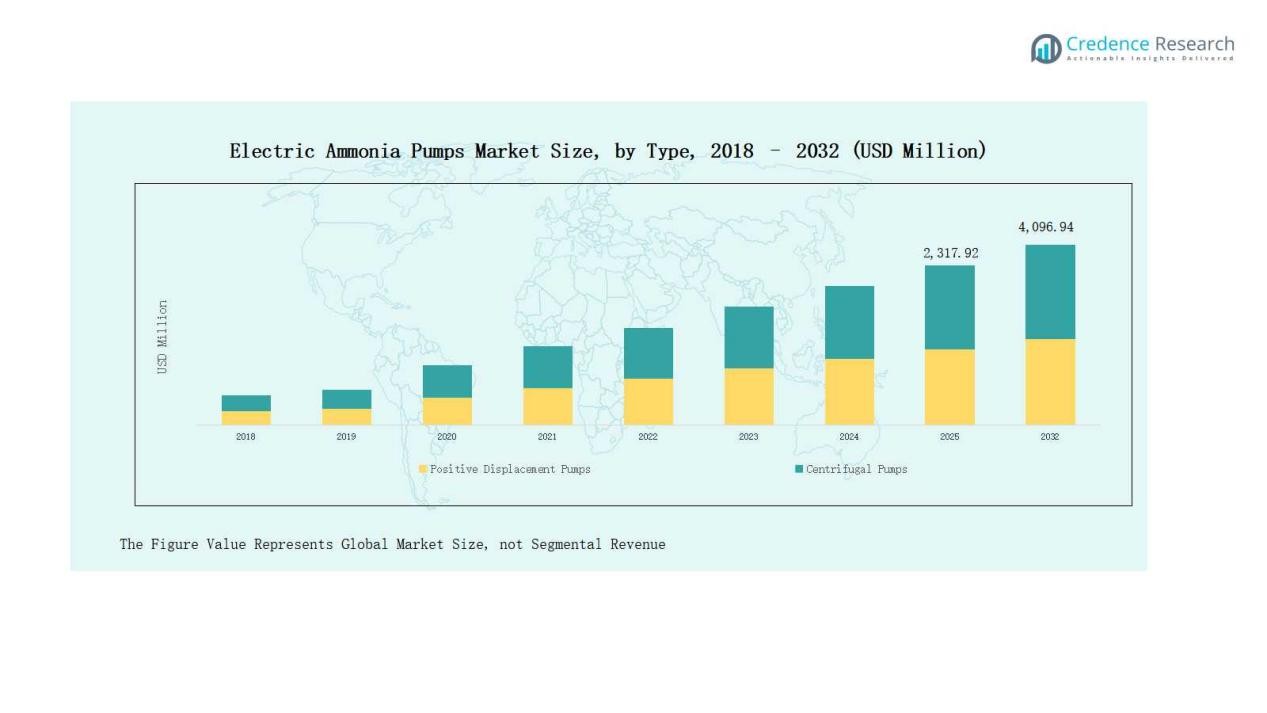
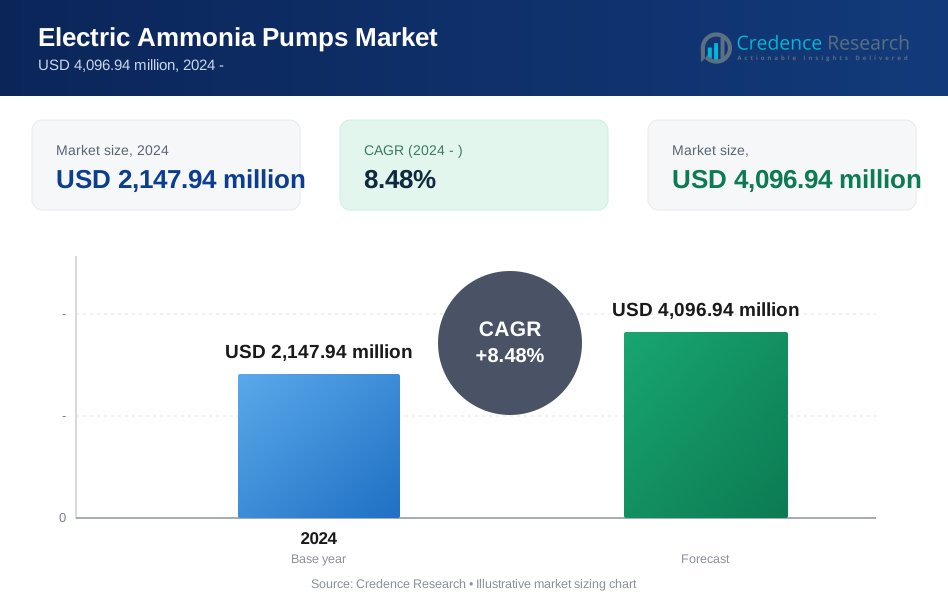
Electric Ammonia Pumps Market size was valued at USD 1,600.00 million in 2018 to USD 2,147.94 million in 2024 and is anticipated to reach USD 4,096.94 million by 2032, at a CAGR of 8.48% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Ammonia Pumps Market Size 2024 | USD 2,147.94 Million |
| Electric Ammonia Pumps Market, CAGR | 8.48% |
| Electric Ammonia Pumps Market Size 2032 | USD 4,096.94 Million |
The Electric Ammonia Pumps Market is shaped by key players such as Baker Hughes, Lutz Pumpen GmbH, WITTE PUMPS & TECHNOLOGY GmbH, PSG, Celeros Flow Technology, Cornell Pump, Hayward Tyler, and IWAKI Europe GmbH, each focusing on product innovation, energy efficiency, and compliance with environmental standards to strengthen their positions. These companies maintain competitive advantages through advanced materials, expanded electric-powered portfolios, and strong global distribution networks. Regionally, Asia Pacific led the market in 2024 with a dominant 40% share, supported by rapid industrialization, strong chemical processing demand, and expanding cold storage infrastructure across China, India, and Japan.
Market Insights
- The Electric Ammonia Pumps Market grew from USD 1,600.00 million in 2018 to USD 2,147.94 million in 2024 and is projected to reach USD 4,096.94 million by 2032.
- Positive displacement pumps led the market with 58% share in 2024, driven by reliability in high-pressure ammonia applications, while centrifugal pumps held 42% with rising use in cooling systems.
- Stainless steel dominated materials with 52% share in 2024 due to durability and corrosion resistance, while alloy materials held 33% and polymer-based designs captured 15%.
- Electric-powered pumps commanded 64% of the market in 2024, supported by energy efficiency and sustainability goals, whereas diesel-powered pumps retained 36% mainly in remote operations.
- Asia Pacific led the market with 40% share in 2024, followed by Europe and North America at 24% each, while Latin America, Middle East, and Africa collectively contributed 16%.
Market Segment Insights
By Type
Positive displacement pumps accounted for the largest share of the electric ammonia pumps market in 2024, holding 58% of total revenue. Their dominance is driven by superior handling of high-pressure ammonia applications, consistent flow delivery, and operational reliability across refrigeration and chemical processing plants. Centrifugal pumps, while representing 42% of the market, are gaining traction in large-scale industrial cooling systems due to their efficiency and lower maintenance costs.
- For instance, GEA Group supplied positive displacement ammonia pumps for a European food processing facility, ensuring stable flow in ultra-low temperature refrigeration lines
By Material
Stainless steel emerged as the leading material segment with a 52% market share in 2024, supported by its durability, corrosion resistance, and suitability for food-grade applications. Alloy materials captured 33% of revenue, favored in oil and gas sectors where high strength and temperature resistance are critical. Polymer-based materials accounted for the remaining 15%, growing steadily in lightweight pump designs and cost-sensitive applications.
- For instance, Flowserve announced supplying dry gas seals and systems for ADNOC’s carbon capture project in the UAE, utilizing its flow control technology.
By Power Source
Electric-powered pumps dominated the market with a 64% share in 2024, fueled by increasing demand for energy-efficient solutions, lower operating costs, and alignment with sustainability goals in manufacturing and chemical industries. Diesel-powered pumps retained a 36% share, mainly serving remote locations and oilfield operations where stable grid electricity is unavailable, though their growth is restrained by rising environmental regulations and fuel costs.
Key Growth Drivers
Rising Demand for Refrigeration and Cooling Systems
The increasing use of ammonia in refrigeration and industrial cooling systems is a major driver for electric ammonia pumps. Food processing, cold storage, and marine applications rely heavily on efficient and reliable ammonia circulation. Growing demand for frozen food, pharmaceuticals, and chemical storage is further accelerating adoption. Positive displacement and centrifugal pumps with electric power sources are increasingly preferred for their energy efficiency, operational stability, and cost savings, strengthening market growth across industries.
- For instance, GEA Group supplied its Grasso V-series ammonia screw compressors with electric drive for a new cold storage facility in France, designed to support the region’s frozen food supply chain.
Shift Toward Energy Efficiency and Sustainability
Global emphasis on sustainable operations and lower emissions is driving the adoption of electric-powered ammonia pumps. These pumps reduce fuel dependency, optimize energy use, and comply with stringent environmental regulations. Industries are transitioning from diesel-powered pumps to electric models to achieve long-term cost efficiency and align with corporate ESG commitments. Advancements in pump design, such as variable speed drives and high-efficiency motors, further support this shift, positioning electric ammonia pumps as a sustainable alternative in diverse industrial applications.
- For instance, Grundfos implemented electric ammonia pumps equipped with high-efficiency motors in industrial refrigeration systems, enabling clients to meet stricter emissions regulations while lowering operational costs.
Expansion of the Chemical and Oil & Gas Industries
The expansion of the chemical and oil & gas industries has boosted demand for reliable ammonia circulation systems. Electric ammonia pumps are essential for chemical processing, refining, and offshore operations where precision, durability, and continuous flow are critical. Growth in emerging economies, particularly in Asia Pacific and the Middle East, is fueling infrastructure investment in petrochemical plants and processing units. As companies seek durable and high-capacity pumping solutions, the reliance on advanced electric ammonia pumps continues to increase globally.
Key Trends & Opportunities
Technological Advancements in Pump Design
Technological innovation is reshaping the electric ammonia pumps market. Integration of smart monitoring, automation, and IoT-based controls is enabling predictive maintenance and reducing downtime. Manufacturers are investing in corrosion-resistant materials and advanced sealing systems to extend service life and reduce leakage risks. The development of energy-efficient motors and customized pump solutions for specialized industries presents a major opportunity for companies to differentiate their offerings and strengthen market share in both developed and emerging regions.
- For instance, EBARA Corporation announced the development of a leak-free canned motor pump for liquid ammonia, designed to minimize leakage risks in ammonia-handling environments within chemical and energy segments.
Growing Adoption in Emerging Economies
Emerging economies across Asia Pacific, Latin America, and Africa present strong growth opportunities. Rapid industrialization, urbanization, and rising demand for cold storage and chemical processing are fueling the adoption of electric ammonia pumps. Governments are investing in infrastructure and food security initiatives, further driving demand for refrigeration systems. Local manufacturers are also entering the market with cost-effective pump designs, increasing accessibility. These regions are expected to record the fastest growth rates, offering global players new opportunities for expansion.
- For instance, German-based GEA, a global technology supplier, introduced energy-efficient ammonia compressor and pump packages for industrial cold storage applications, including in Southeast Asia.
Key Challenges
High Initial Investment and Maintenance Costs
Despite long-term benefits, electric ammonia pumps require significant upfront investment. Installation of advanced electric-powered systems, particularly stainless-steel pumps, increases capital expenditure for industries with budget constraints. Maintenance of seals, motors, and electronic control systems adds to operational costs. For small and mid-scale businesses, this cost factor often limits adoption, creating challenges for widespread penetration of electric ammonia pumps, especially in price-sensitive markets.
Stringent Safety and Environmental Regulations
Ammonia is a hazardous substance, requiring strict compliance with safety and environmental standards. Industries using ammonia pumps must adhere to regulations on storage, handling, and emissions, which raises operational complexity and cost. Non-compliance can result in fines and operational shutdowns, discouraging smaller operators. Manufacturers are required to design pumps with advanced safety features, increasing design costs. These regulatory pressures challenge both producers and end-users, slowing down large-scale adoption in some regions.
Competition from Alternative Refrigerants and Systems
The increasing use of alternative refrigerants and advanced cooling technologies poses a challenge for the electric ammonia pumps market. Industries are exploring substitutes like CO₂-based systems and low-GWP refrigerants to meet environmental goals. These alternatives, combined with innovations in cooling equipment, could reduce ammonia dependency. If industries adopt these substitutes at scale, the growth potential for electric ammonia pumps may be restrained, pushing manufacturers to innovate further to maintain competitiveness in the global market.
Regional Analysis
North America
North America held a 24% share of the global electric ammonia pumps market in 2024, with revenue of USD 508.19 million. The region is projected to reach USD 964.38 million by 2032, expanding at a CAGR of 8.4%. Growth is driven by strong demand from industrial refrigeration, food processing, and oil & gas sectors. The U.S. leads adoption due to advanced infrastructure, while Canada and Mexico are expanding with investments in cold storage facilities and petrochemical industries. Favorable regulations supporting energy-efficient technologies also strengthen the region’s market position.
Europe
Europe accounted for 24% of the market in 2024, valued at USD 510.72 million, and is projected to reach USD 916.70 million by 2032, growing at a CAGR of 7.7%. Strong adoption in Germany, France, and the UK is supported by mature food processing industries and stringent environmental standards. The region’s emphasis on sustainable refrigeration technologies drives the shift from diesel-powered to electric-powered pumps. Increasing investments in pharmaceuticals and chemicals also contribute to stable demand. Eastern Europe is gradually expanding adoption, supported by industrial modernization initiatives.
Asia Pacific
Asia Pacific dominated the market with a 40% share in 2024, generating USD 848.11 million in revenue. It is expected to grow at the fastest CAGR of 9.3%, reaching USD 1,716.25 million by 2032. China, India, and Japan lead the regional market, supported by rapid industrialization, chemical processing, and rising demand for cold storage facilities. Government initiatives to expand food security infrastructure and renewable energy integration further strengthen growth. Asia Pacific remains the primary hub for manufacturing and exports, offering significant opportunities for pump manufacturers.
Latin America
Latin America represented a 7% share of the global market in 2024, with revenue of USD 144.75 million. It is projected to reach USD 257.57 million by 2032, expanding at a CAGR of 7.6%. Brazil dominates demand, supported by a large food and beverage industry and growing chemical processing sector. Argentina and Mexico contribute moderately, with rising adoption in industrial manufacturing. Despite economic fluctuations, government efforts to modernize cold storage and expand export-based industries are creating opportunities for electric ammonia pump suppliers in the region.
Middle East
The Middle East held a 6% share in 2024, valued at USD 106.52 million, and is forecasted to reach USD 188.89 million by 2032, growing at a CAGR of 7.5%. GCC countries lead regional adoption, supported by oil and gas investments and industrial expansion. Demand for ammonia-based refrigeration in petrochemicals and marine applications fuels pump installations. Israel and Turkey show rising adoption through chemical manufacturing growth. However, the market faces challenges from reliance on fossil fuel-driven industries, pushing companies to adopt electric-powered alternatives to align with sustainability goals.
Africa
Africa captured a 2% share in 2024, with market revenue of USD 29.65 million. The region is expected to reach USD 53.14 million by 2032, growing at a CAGR of 7.2%. South Africa leads adoption, driven by its food and beverage sector and rising industrial investments. Egypt and Nigeria are gradually expanding usage with new infrastructure and chemical processing projects. Limited access to advanced technology and high upfront costs remain challenges, but growing urbanization and regional trade agreements present opportunities for pump manufacturers to strengthen presence.
Market Segmentations:
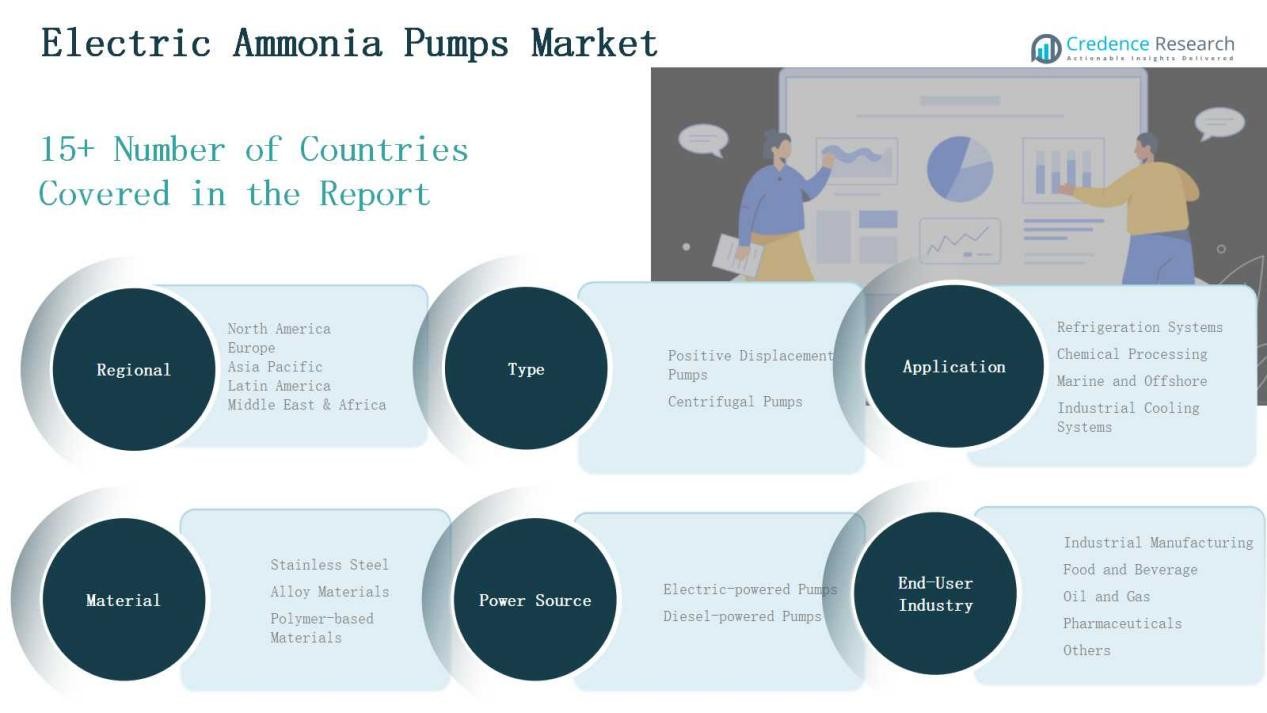
By Type
- Positive Displacement Pumps
- Centrifugal Pumps
By Material
- Stainless Steel
- Alloy Materials
- Polymer-based Materials
By Power Source
- Electric-powered Pumps
- Diesel-powered Pumps
By End-User Industry
- Industrial Manufacturing
- Food and Beverage
- Oil and Gas
- Pharmaceuticals
- Others
By Application
- Refrigeration Systems
- Chemical Processing
- Marine and Offshore
- Industrial Cooling Systems
By Region
- North America (U.S., Canada, Mexico)
- Europe (UK, France, Germany, Italy, Spain, Russia, Rest of Europe)
- Asia Pacific (China, Japan, South Korea, India, Australia, Southeast Asia, Rest of APAC)
- Latin America (Brazil, Argentina, Rest of Latin America)
- Middle East (GCC, Israel, Turkey, Rest of Middle East)
- Africa (South Africa, Egypt, Rest of Africa)
Competitive Landscape
The competitive landscape of the Electric Ammonia Pumps Market is defined by the presence of global leaders and specialized regional players competing on product innovation, efficiency, and industry-specific solutions. Key companies such as Baker Hughes, Lutz Pumpen GmbH, WITTE PUMPS & TECHNOLOGY GmbH, PSG, Celeros Flow Technology, Cornell Pump, Hayward Tyler, and IWAKI Europe GmbH dominate through extensive product portfolios and strong global distribution networks. These players focus on enhancing pump reliability, energy efficiency, and safety standards to meet the rising demand from industries including food and beverage, oil and gas, and chemical processing. Strategic investments in stainless-steel and polymer-based materials, along with electric-powered technologies, strengthen their ability to address regulatory compliance and sustainability goals. Partnerships, acquisitions, and expansions into emerging markets remain central growth strategies. Competition is also intensifying from regional manufacturers offering cost-effective solutions, creating a balanced mix of global innovation and localized affordability in the market.
Key Players
- Baker Hughes
- Lutz Pumpen GmbH
- WITTE PUMPS & TECHNOLOGY GmbH
- PSG
- Celeros Flow Technology
- Cornell Pump
- Hayward Tyler
- IWAKI Europe GmbH
Recent Developments
- In September 2024, Svanehøj introduced a high-pressure centrifugal ammonia fuel pump capable of delivering injection pressure up to 100 bar with a hermetically sealed design.
- In June 2025, Honeywell completed the acquisition of Sundyne for USD 2.16 billion, strengthening its portfolio in advanced pumps and compressors for ammonia and process industries.
- In September 2025, Nikkiso Clean Energy & Industrial Gases Group launched a next-generation submerged electric ammonia pump at the Gastech 2025 Conference. The new pump is seal-less, copper-free, and integrated with a motor-pump design, offering over 2,500 cubic meters per hour capacity and industry-leading reliability with a mean time between outages exceeding 16,000 operating hours.
- In April 2025, CF Industries formed a joint venture with JERA Co., Inc. and Mitsui & Co., Ltd. to build a low-carbon ammonia production facility at the Blue Point Complex, Louisiana. The facility will include CO₂ capture, and the partners plan large-scale ammonia production.
- In May 2025, Marubeni and ExxonMobil signed a long-term offtake agreement for about 250,000 tonnes per year of low-carbon ammonia from ExxonMobil’s facility in Baytown, Texas. Marubeni also agreed to take an equity stake in the facility.
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Power Source, End User Industry, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for electric ammonia pumps will rise with expanding refrigeration and cold storage facilities.
- Adoption will increase in chemical and oil & gas sectors for reliable ammonia circulation.
- Electric-powered pumps will continue replacing diesel-powered units due to efficiency and compliance.
- Stainless steel pumps will dominate material use because of durability and corrosion resistance.
- Asia Pacific will remain the leading growth region supported by industrial expansion.
- North America and Europe will sustain strong adoption driven by regulatory standards.
- Integration of smart monitoring and IoT-enabled controls will improve operational reliability.
- Manufacturers will focus on sustainable designs to meet stricter environmental regulations.
- Emerging economies will present new opportunities through infrastructure and food industry growth.
- Competitive intensity will increase as regional players offer cost-effective pump solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Electric Ammonia Pumps Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electric Ammonia Pumps Market projected to grow between 2025 and 2032?
Which Electric Ammonia Pumps Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electric Ammonia Pumps Market?
Who are the leading companies in the Electric Ammonia Pumps Market?
Which region commanded the largest share of the Electric Ammonia Pumps Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Electric Ammonia Pumps Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Electric Ammonia Pumps Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 2,147.94 million → forecast year: USD 4,096.94 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Electric Ammonia Pumps Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Electric Ammonia Pumps Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Electric Ammonia Pumps Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Electric Ammonia Pumps Market Drivers
- 3.3 Electric Ammonia Pumps Market Restraints & Challenges
- 3.4 Electric Ammonia Pumps Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Electric Ammonia Pumps Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Electric Ammonia Pumps Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Electric Ammonia Pumps category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Electric Ammonia Pumps Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Electric Ammonia Pumps Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Electric Ammonia Pumps market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Electric Ammonia Pumps Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Electric Ammonia Pumps Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Electric Ammonia Pumps Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Electric Ammonia Pumps (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Electric Ammonia Pumps Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Electric Ammonia Pumps Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Electric Ammonia Pumps Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Electric Ammonia Pumps Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Electric Ammonia Pumps Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Electric Ammonia Pumps Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Electric Ammonia Pumps Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Electric Ammonia Pumps Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Electric Ammonia Pumps Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
