
Market Overview
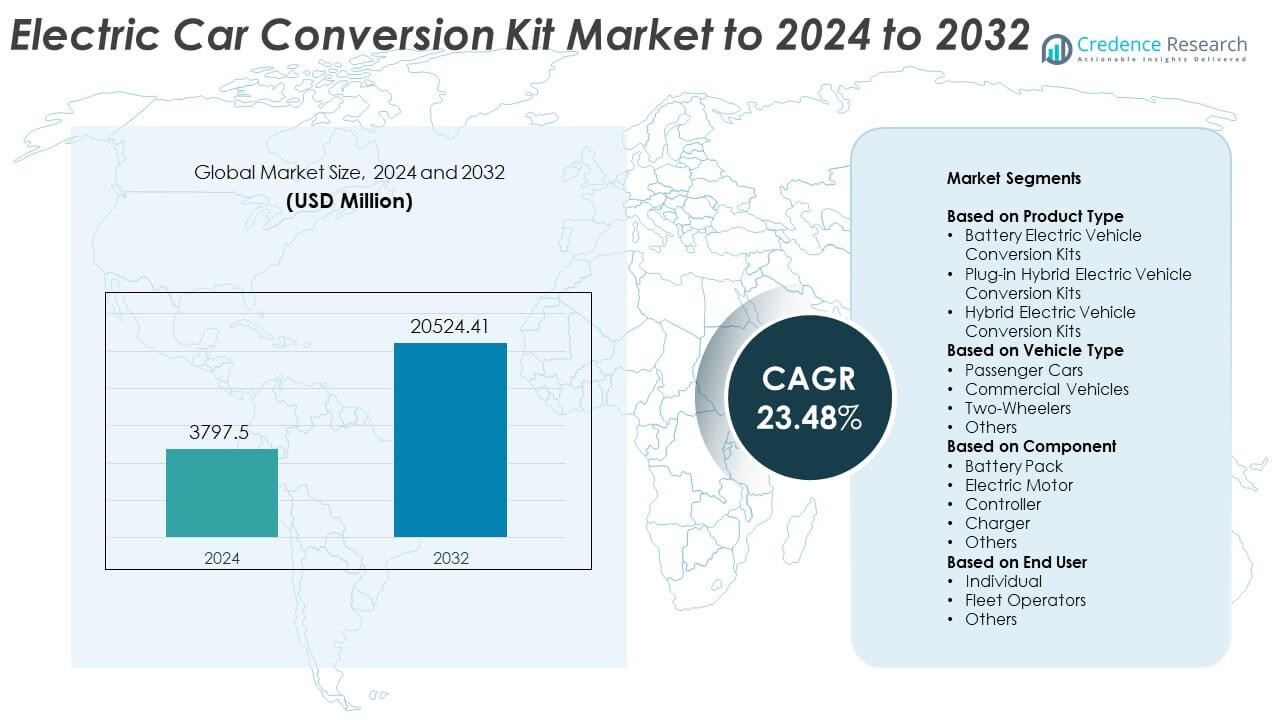
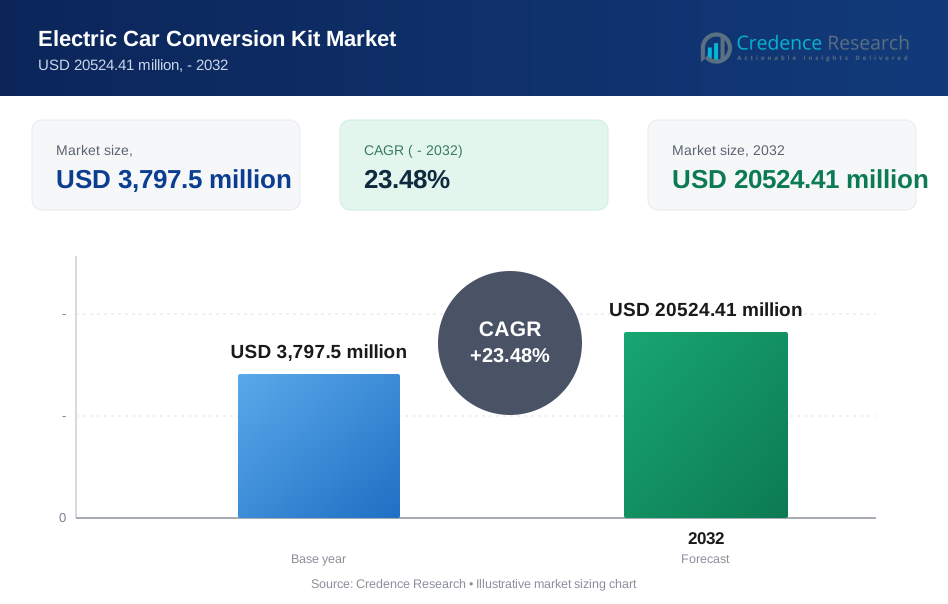
Electric Car Conversion Kit Market size was valued at USD 3797.5 million in 2024 and is anticipated to reach USD 20524.41 million by 2032, at a CAGR of 23.48% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Car Conversion Kit Market Size 2024 | USD 3797.5 Million |
| Electric Car Conversion Kit Market, CAGR | 23.48% |
| Electric Car Conversion Kit Market Size 2032 | USD 20524.41 Million |
The Electric Car Conversion Kit Market is shaped by companies such as Electric Classic Cars, EV-propulsion, EV4U Custom Conversions, Electric GT, Revolt Systems, Canadian Electric Vehicles, EV West, EV Conversion Kits, EVolve Electrics, and E Ink Holdings. These players compete through improved battery systems, compact motors, safer controllers, and modular kit designs that reduce installation time. North America leads the market with about 34% share due to strong retrofit adoption and a large aftermarket ecosystem. Europe follows with nearly 29% share, supported by strict emission rules, while Asia Pacific holds around 27% driven by cost-efficient electrification trends.
Market Insights
- The Electric Car Conversion Kit Market reached USD 3797.5 million in 2024 and will reach USD 20524.41 million by 2032, growing at a 23.48% CAGR. • Rising adoption of cost-effective electrification drives demand, with battery electric conversion kits holding about 58% share due to higher efficiency and zero-emission performance. • Key trends include modular kit designs, advanced battery packs, and expanding certified workshop networks that improve installation speed and safety compliance. • Competition strengthens as players enhance motor efficiency, controller safety, and diagnostic software while expanding service networks to reach hobbyists and fleet users. • North America leads with 34% share, followed by Europe at 29% and Asia Pacific at 27%, with passenger cars dominating by vehicle type at nearly 62% share.
Market Segmentation Analysis:
By Product Type
Battery Electric Vehicle Conversion Kits lead this segment with about 58% share in 2024. Demand rises as owners shift to full-electric systems for zero tailpipe emissions and lower operating costs. Workshops prefer BEV kits because these systems offer simpler architecture, fewer moving parts, and improved reliability. Plug-in hybrid kits grow in urban regions where mixed-mode driving supports range flexibility, while hybrid electric vehicle kits gain traction among cost-sensitive users seeking partial electrification. Growth accelerates as governments expand incentives for vehicle electrification and older cars move toward emission-compliant upgrades.
- For instance, Electrogenic offers drop-in EV conversion kits for models like the Land Rover Defender. The standard 52 kWh battery kit offers a range of approximately 100+ miles (160+ km) on-road.
By Vehicle Type
Passenger Cars dominate this segment with nearly 62% share in 2024. Adoption expands as car owners convert aging petrol and diesel vehicles to meet emission norms and reduce running expenses. Conversion workshops focus on passenger cars due to higher volumes and standardised chassis layouts, which simplify installation. Commercial vehicles see steady adoption for urban delivery fleets aiming to cut fuel costs, while two-wheelers rise in markets with dense city traffic. Growth continues as electrification policies target light-duty vehicles and encourage retrofit solutions.
- For instance, Transition-One develops EV conversion kits for small city cars like the Renault Twingo and Fiat 500. The company claims a driving range of about 60 miles (approximately 100 km) on a single charge due to the small battery size.
By Component
Battery Pack holds the largest share in this segment with around 48% in 2024. The battery pack dominates because it forms the core cost component and determines vehicle range, safety, and performance. Manufacturers invest in lithium-ion upgrades that enhance energy density and speed up the conversion process. Electric motors and controllers gain traction as kit suppliers shift to compact, higher-efficiency designs, while chargers expand with growing home-charging adoption. Market demand strengthens as declining battery prices make conversions more affordable.
Key Growth Drivers
Rising Adoption of Vehicle Electrification
Governments push stricter emission norms, which drives vehicle owners to shift toward cleaner mobility. Many buyers choose conversion kits to avoid the higher cost of new electric cars. Workshops promote full-electric retrofits because these upgrades improve energy efficiency and trim long-term fuel expenses. Rising fuel prices also encourage adoption, especially in urban regions. As charging networks expand and battery technology improves, owners find conversion kits more practical. This factor stands as a key growth driver for the Electric Car Conversion Kit Market.
- For instance, BYD reported selling 3.02 million new energy vehicles in 2023, up from 1.86 million in 2022, demonstrating rapid electrification momentum that supports demand for retrofit and conversion solutions.
Cost-Effective Option Compared to New EV Purchases
Conversion kits offer a cheaper way to switch to electric mobility without buying a new EV. The lower upfront price appeals to budget-sensitive drivers and owners of older vehicles. Many users extend vehicle life while reducing operating costs. Falling battery prices make retrofits even more attractive. Fleet operators also embrace conversions to cut fuel consumption and align with sustainability goals. Growing awareness about lifecycle cost benefits strengthens market growth, making this factor a key growth driver.
- For instance, GoGoA1 offers RTO-approved electric conversion kits for popular models like the Honda Activa. The kit, including a 72V 21Ah Li-Ion battery and motor.
Supportive Government Policies and Incentives
Many regions provide tax rebates and supportive regulations that encourage retrofitting of ICE vehicles. Approval frameworks for conversion workshops and emission compliance boost installation confidence. Incentive programs help reduce the cost gap between traditional vehicles and electric conversions. Municipalities promote retrofits for taxis, delivery vans, and shared vehicles. Policy alignment with climate targets increases market visibility. These supportive actions boost demand and position this factor as a key growth driver for the Electric Car Conversion Kit Market.
Key Trends and Opportunities
Advancement in Battery and Motor Technologies
Manufacturers design lightweight, energy-dense battery packs that enhance range and safety. New motor designs improve torque, efficiency, and installation flexibility. Compact components reduce space needs, making older vehicles easier to convert. Fast-charging compatibility expands user convenience and strengthens long-term adoption. Technology upgrades open opportunities for premium kits targeting performance enthusiasts. This is a major key trend and opportunity in the Electric Car Conversion Kit Market.
- For instance, Tesla has disclosed that its Model 3/Y permanent-magnet drive units can exceed 90 % efficiency over a wide operating range, illustrating how modern motor and inverter designs enhance energy use and range for both factory EVs and conversion-grade components
Growing Adoption of Conversion Kits in Commercial Fleets
Delivery companies and mobility operators retrofit vehicles to reduce fuel use and meet low-emission zone rules. Fleet managers prefer conversions because the process avoids buying new EVs and shortens downtime. Lower operating costs improve fleet profitability, making retrofit programs attractive. Urban logistics growth increases demand for clean vans, taxis, and small trucks. This segment offers strong business potential for kit manufacturers and installers. It stands as a key trend and opportunity shaping market expansion.
- For instance, DHL Group had more than 35,200 electric vehicles in its global pickup-and-delivery fleet by the end of 2023, along with over 25,000 e-bikes, e-trikes, and cargo bikes.
Key Challenges
High Initial Conversion Costs and Limited Standardization
Despite lower costs compared to new EVs, many vehicle owners still face high upfront expenses. Custom fitting for different vehicle models increases service complexity. Lack of universal standards for kit design and installation slows workshop adoption. Safety certification adds extra cost and time. These barriers reduce conversion uptake in cost-sensitive markets. This stands as a key challenge for the Electric Car Conversion Kit Market.
Limited Availability of Skilled Technicians and Infrastructure
Conversion work demands trained technicians familiar with electrical systems, battery integration, and safety rules. Many regions lack certified workshops, slowing installation rates. Weak charging infrastructure limits adoption in rural areas. Delays in regulatory approvals add to operational hurdles. Skill shortages also increase service costs. This factor remains a key challenge, restricting broader market penetration.
Regional Analysis
North America
North America holds about 34% share in 2024, driven by strong EV adoption and rising interest in retrofitting older gasoline vehicles. Many states support conversion programs through incentives and inspection frameworks that ease compliance. Consumer preference for sustainable mobility and lower fuel costs boosts kit installation rates. Workshop networks expand quickly, especially in the U.S., where hobbyist communities and aftermarket suppliers play a key role. Canada sees steady growth as fleets explore conversions for urban routes. Overall demand strengthens as charging access improves and battery prices decline.
Europe
Europe accounts for nearly 29% share in 2024, supported by strict emission regulations and rapid growth in low-emission zones. Drivers convert older petrol and diesel cars to avoid emission penalties and extend vehicle usability. Countries like Germany, France, and the U.K. promote certified retrofit pathways that enhance safety and market credibility. High environmental awareness fuels adoption among private users and small fleets. Workshops benefit from clear regulatory guidance and strong demand for sustainable transport. Growth continues as cities push toward climate-neutral mobility goals across the region.
Asia Pacific
Asia Pacific holds about 27% share in 2024, led by strong interest in cost-effective electrification across India, China, and Southeast Asia. High fuel prices and rising urban pollution levels encourage adoption of conversion kits. Local suppliers design low-cost solutions that fit older compact vehicles common in the region. Growing two-wheeler electrification also contributes to segment expansion. Government targets for cleaner transportation push conversion markets alongside new EV sales. Fleet operators in dense cities drive steady installations, while battery supply chains in China support competitive pricing.
Latin America
Latin America captures around 6% share in 2024, with growth led by Brazil, Mexico, and Chile. Rising fuel expenses and increasing environmental regulations push drivers to consider affordable conversion options. Market expansion remains gradual due to limited certified workshops and varied regulatory approval processes. However, urban taxi fleets and delivery services show growing interest in retrofits to lower operating costs. Local innovators start offering modular kits suited to older regional vehicle models. Awareness campaigns and pilot programs help build confidence among consumers and small fleet owners.
Middle East and Africa
Middle East and Africa hold nearly 4% share in 2024, reflecting early-stage adoption but rising interest in sustainable vehicle upgrades. Wealthier Gulf nations explore conversions for niche applications and vintage vehicles, while African markets focus on cost savings and reduced fuel use. Limited charging access slows adoption, but government clean-mobility initiatives gradually improve conditions. Retrofit demand grows in commercial fleets, especially in urban logistics. Local workshops begin offering basic conversion services, and falling battery costs support long-term potential across both regions.
Market Segmentations:
By Product Type
- Battery Electric Vehicle Conversion Kits
- Plug-in Hybrid Electric Vehicle Conversion Kits
- Hybrid Electric Vehicle Conversion Kits
By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- Two-Wheelers
- Others
By Component
- Battery Pack
- Electric Motor
- Controller
- Charger
- Others
By End User
- Individual
- Fleet Operators
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Electric Car Conversion Kit Market features leading companies such as Electric Classic Cars, EV-propulsion, EV4U Custom Conversions, Electric GT, Revolt Systems, Canadian Electric Vehicles, EV West, EV Conversion Kits, EVolve Electrics, and E Ink Holdings. Market players focus on engineering modular kits that support faster installation, higher efficiency, and improved safety compliance. Many suppliers expand product lines to cover multiple vehicle categories, including passenger cars, commercial fleets, and vintage models. Companies invest in advanced battery systems, compact motors, and smarter controllers to enhance performance and range. Partnerships with certified workshops strengthen service networks and build customer trust. Firms also improve software integration for real-time diagnostics and tuning support. Growing demand from individual users and fleet operators encourages manufacturers to refine cost-effective designs. Continuous innovation, regulatory alignment, and expanding retrofit infrastructure shape competition and support long-term market growth.
Key Player Analysis
- Electric Classic Cars
- EV-propulsion
- EV4U Custom Conversions
- Electric GT
- Revolt Systems
- Canadian Electric Vehicles
- EV West
- EV Conversion Kits
- EVolve Electrics
- E Ink Holdings
Recent Developments
- In 2025, E Ink Holdings and AUO Display Plus formed a joint venture to enhance the production and availability of large-format ePaper modules, a technology that aligns with the sustainable mobility goals of the broader EV industry.
- In 2025, Edison Motors announced they were developing a retrofit kit specifically for pickup trucks.
- In 2022, Electric GT showcased the eGT-413 V8 EV Crate Motor Swap System and the eGT-913 Porsche 911 specific EV conversion system at SEMA, which continue to be dominant offerings.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Vehicle Type, Component, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for conversion kits will rise as emission rules tighten worldwide.
- Battery technology will improve range and make retrofits more efficient.
- More certified workshops will appear to support safe and standardised installations.
- Fleet operators will adopt conversions to cut fuel costs and meet sustainability goals.
- Conversion kit designs will become compact, modular, and easier to install.
- Government incentives will continue to boost retrofit adoption across older vehicles.
- Charging infrastructure growth will increase confidence in long-term electric mobility.
- Local manufacturers will offer low-cost kits tailored to regional vehicle models.
- Digital tools will enhance diagnostics, tuning, and post-installation performance support.
- Partnerships between automakers and retrofit companies will expand market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Vehicle Electrification
Stricter emission norms and growing environmental awareness are pushing vehicle owners to convert existing internal combustion vehicles to electric, driving demand for conversion kits as a practical and sustainable solution.
Cost-Effective Option Compared to New EV Purchases
Conversion kits provide a lower-cost alternative to purchasing new electric vehicles, appealing to budget-conscious consumers and fleet operators who want to extend the life of existing vehicles while reducing operating costs.
Supportive Government Policies and Incentives
Many governments offer tax rebates, regulatory approvals, and incentive programs that lower the cost and complexity of retrofitting vehicles, making conversion kits more accessible and attractive to a wider audience.
Advancement in Battery and Motor Technologies
Improvements in battery energy density, safety, and motor efficiency are making conversion kits more reliable, easier to install, and capable of delivering better range and performance, thus accelerating market growth.
Growing Adoption in Commercial Fleets
Fleet operators are increasingly retrofitting delivery vans, taxis, and light trucks to electric powertrains to comply with low-emission zone regulations and reduce fuel expenses, creating a significant demand segment for conversion kits.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Electric Car Conversion Kit Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electric Car Conversion Kit Market projected to grow between 2025 and 2032?
Which Electric Car Conversion Kit Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electric Car Conversion Kit Market?
Who are the leading companies in the Electric Car Conversion Kit Market?
Which region commanded the largest share of the Electric Car Conversion Kit Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Individual
- 1.2.2 Fleet Operators
- 1.2.3 Others
- 1.3 By Component
- 1.3.1 Battery Pack
- 1.3.2 Electric Motor
- 1.3.3 Controller
- 1.3.4 Charger
- 1.3.5 Others
- 1.4 By Product Type
- 1.4.1 Battery Electric Vehicle Conversion Kits
- 1.4.2 Plug-in Hybrid Electric Vehicle Conversion Kits
- 1.4.3 Hybrid Electric Vehicle Conversion Kits
- 1.5 By Vehicle Type
- 1.5.1 Passenger Cars
- 1.5.2 Commercial Vehicles
- 1.5.3 Two-Wheelers
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,797.5 million → 2032: USD 20524.41 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electric Car Conversion Kit Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electric Car Conversion Kit Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electric Car Conversion Kit Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electric Car Conversion Kit Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electric Car Conversion Kit Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electric Car Conversion Kit Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electric Car Conversion Kit Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electric Car Conversion Kit Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,797.5 million → 2032: USD 20524.41 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electric Car Conversion Kit Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Individual
- 12.3.7.2 Fleet Operators
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Battery Pack
- 12.4.7.2 Electric Motor
- 12.4.7.3 Controller
- 12.4.7.4 Charger
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Battery Electric Vehicle Conversion Kits
- 12.5.7.2 Plug-in Hybrid Electric Vehicle Conversion Kits
- 12.5.7.3 Hybrid Electric Vehicle Conversion Kits
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Passenger Cars
- 12.6.7.2 Commercial Vehicles
- 12.6.7.3 Two-Wheelers
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electric Car Conversion Kit End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electric Car Conversion Kit Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electric Car Conversion Kit Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electric Car Conversion Kit Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Electric Classic Cars
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 EV-propulsion
- 18.4 EV4U Custom Conversions
- 18.5 Electric GT
- 18.6 Revolt Systems
- 18.7 Canadian Electric Vehicles
- 18.8 EV West
- 18.9 EV Conversion Kits
- 18.10 EVolve Electrics
- 18.11 E Ink Holdings
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

