
Market Overview:
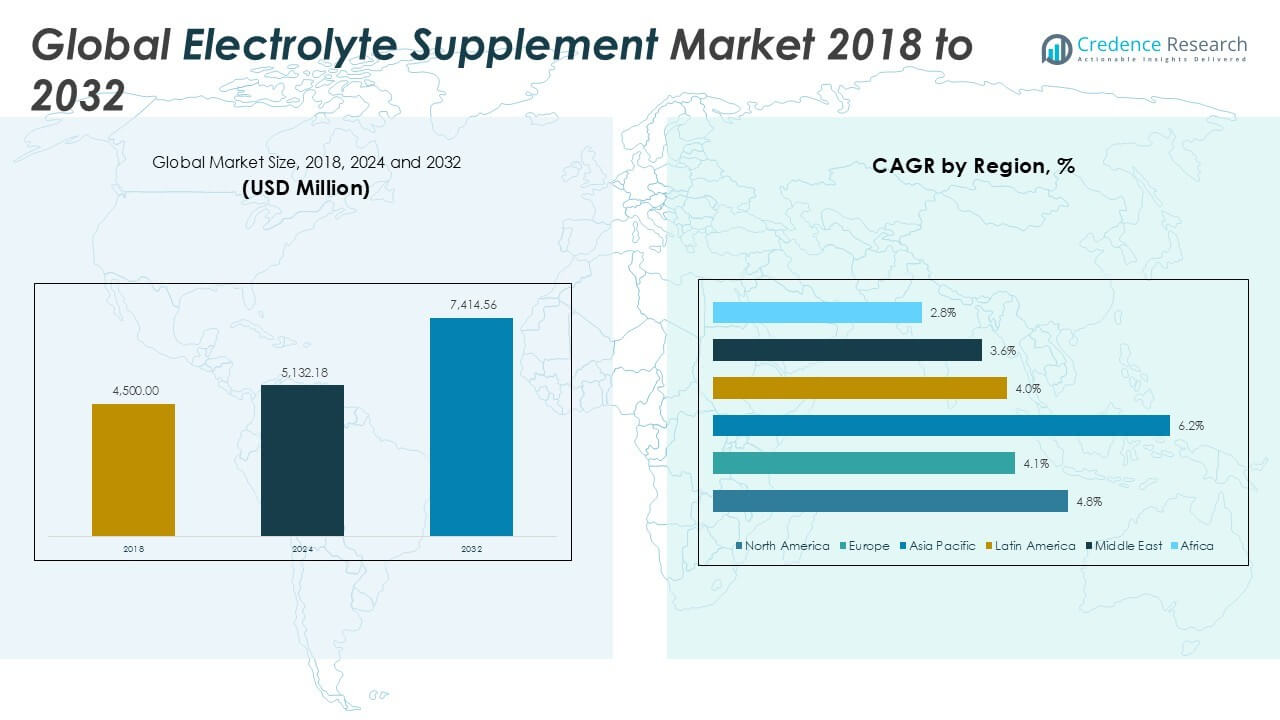
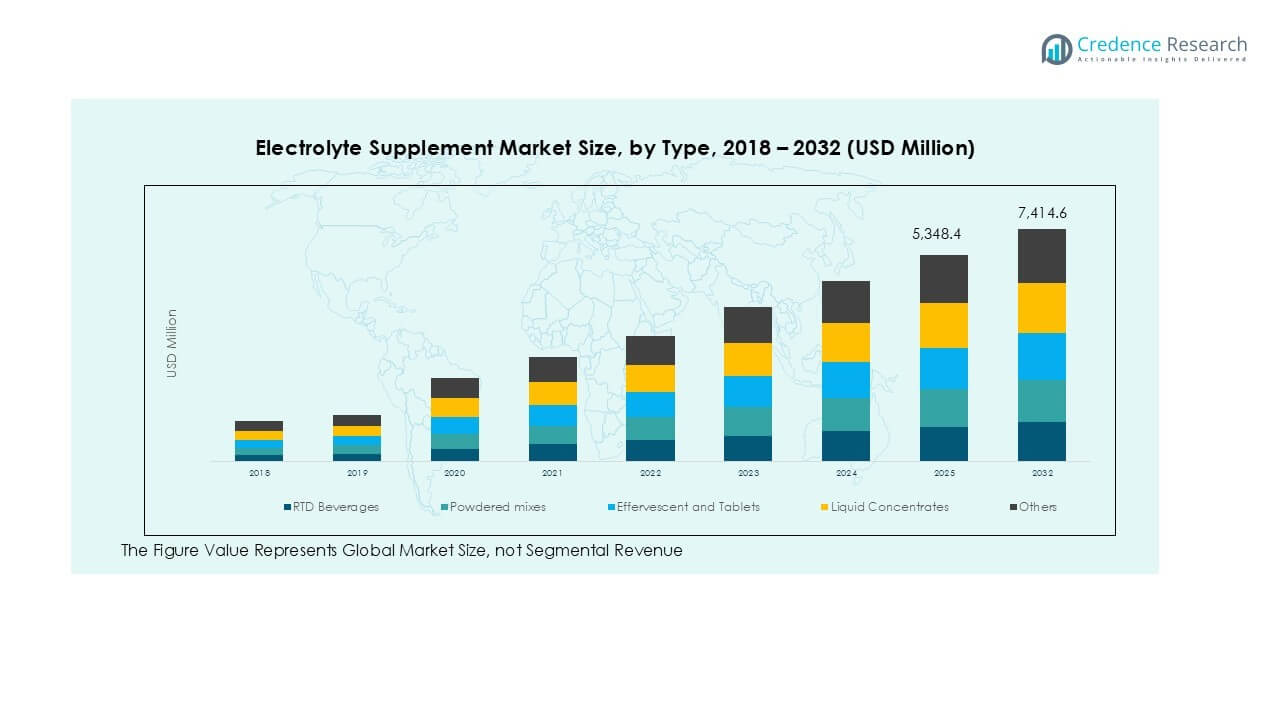
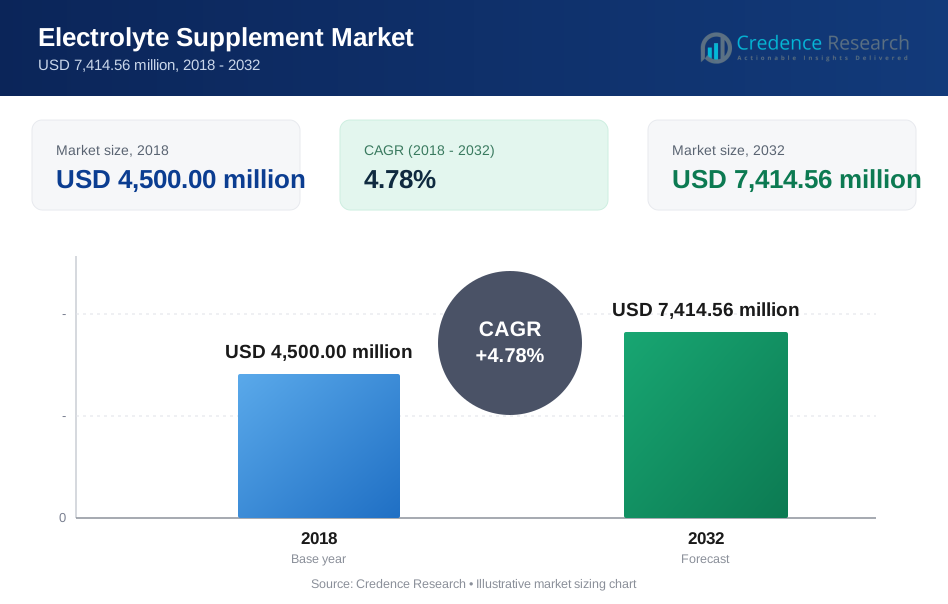
The Electrolyte Supplement Market size was valued at USD 4,500.00 million in 2018 to USD 5,132.18 million in 2024 and is anticipated to reach USD 7,414.56 million by 2032, at a CAGR of 4.78% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electrolyte Supplement Market Size 2024 | USD 5,132.18 Million |
| Electrolyte Supplement Market, CAGR | 4.78% |
| Electrolyte Supplement Market Size 2032 | USD 7,414.56 Million |
Key market drivers include growing consumer awareness of the importance of hydration, especially among athletes and fitness enthusiasts. Increased demand for sports nutrition and performance-enhancing products also contributes to market growth. Additionally, rising health concerns related to dehydration, especially in hot climates or intense physical activities, fuels the adoption of electrolyte supplements in daily routines.
North America is a leading market, primarily driven by a strong presence of fitness-conscious individuals and a developed healthcare system. The U.S. is at the forefront, with increased focus on sports nutrition and preventive healthcare. The Asia Pacific region is emerging rapidly due to growing health awareness and an expanding middle-class population. Countries like China and India are experiencing significant growth due to rising disposable incomes and a shift towards healthier lifestyles.
Market Insights:
- The Global Electrolyte Supplement Market was valued at USD 4,500 million in 2018, expected to grow to USD 7,414.56 million by 2032 at a CAGR of 4.78%.
- Increased consumer awareness of hydration, especially among athletes and fitness enthusiasts, is driving the demand for electrolyte supplements.
- Innovations in product offerings, including powders, tablets, and ready-to-drink beverages, are expanding the market to cater to diverse consumer preferences.
- Participation in physical activities is rising, leading to an increased need for hydration solutions, driving the demand for electrolyte supplements.
- The expansion of online and offline distribution channels is making electrolyte supplements more accessible, facilitating market growth.
- Regulatory challenges and ingredient transparency issues are key factors influencing product development and marketing strategies in the global market.
- North America and Europe are leading markets, driven by strong health-conscious populations and increasing demand for fitness and sports nutrition products.
Market Drivers:
Rising Health and Fitness Consciousness
The Global Electrolyte Supplement Market is experiencing significant growth, driven by increasing health and fitness awareness. Consumers are becoming more conscious of the importance of proper hydration and its role in overall well-being. This shift in mindset has led to a surge in demand for products that support hydration and electrolyte balance. As a result, the market for electrolyte supplements is expanding rapidly, with a growing number of individuals seeking solutions to maintain optimal hydration levels.
- For instance, Gatorade developed the Gx platform, a system that provides personalized hydration recommendations. This technology's algorithms are based on research from the Gatorade Sports Science Institute, including a large-scale study involving over 300 athletes to validate its effectiveness.
Advancements in Product Offerings
Innovations in product formulations are contributing to the market's expansion. Manufacturers are developing a wide range of electrolyte supplements, including powders, tablets, and ready-to-drink beverages, to cater to diverse consumer preferences. These products are often enhanced with additional nutrients such as vitamins and minerals, providing added health benefits. The availability of various product types and formulations is attracting a broader consumer base, further fueling market growth.
Increased Participation in Physical Activities
The growing trend of increased participation in physical activities is another key driver of the electrolyte supplement market. As more individuals engage in regular exercise, the need for effective hydration solutions becomes more pronounced. Electrolyte supplements help replenish essential minerals lost through sweat during physical activities, supporting performance and recovery. This heightened demand among active individuals is propelling the market forward.
Expansion of Distribution Channels
The expansion of distribution channels is making electrolyte supplements more accessible to consumers worldwide. Retailers, both online and offline, are increasingly stocking a variety of electrolyte supplement products, reaching a wider audience. This increased availability is facilitating consumer access to these products, contributing to the overall growth of the market.
- For instance, Gatorade has expanded its digital ecosystem for the Gx platform by making its app compatible with at least 3 major fitness platforms.
Market Trends:
Shift Toward Plant-Based and Clean-Label Electrolyte Supplements
The Global Electrolyte Supplement Market is witnessing a significant shift towards plant-based and clean-label products. Consumers increasingly demand natural, organic, and vegan-friendly options, prompting manufacturers to reformulate products to meet these preferences. This trend is driven by a broader movement towards health-conscious and sustainable living. Companies are responding by offering electrolyte supplements that are free from artificial additives and preservatives, aligning with the clean-label movement. The rise in plant-based diets and environmental awareness is further fueling this demand, as consumers seek products that align with their ethical and health values.
- For instance, in February 2024, the company POSSIBLE launched the first-of-its-kind certified organic Whole Food Electrolyte powder, which contains 5 essential minerals.
Integration of Electrolyte Supplements into Daily Wellness Routines
Electrolyte supplements are increasingly integrated into daily wellness routines, moving beyond traditional use by athletes. Consumers are incorporating these products into their everyday lives to maintain hydration and support overall health. This shift is facilitated by the availability of convenient formats such as tablets, powders, and ready-to-drink beverages. The growing awareness of the importance of hydration for cognitive function, energy levels, and immune support is contributing to this trend. As a result, electrolyte supplements are becoming a staple in the wellness industry, appealing to a broader demographic seeking to enhance their daily health regimen.
- For instance, to support daily energy needs beyond athletic performance, Nuun's Sport + Caffeine tablets are designed for use during the work day and contain 40mg of caffeine from green tea extract in 1 tablet.
Market Challenges Analysis:
Regulatory Compliance and Ingredient Transparency
The Global Electrolyte Supplement Market faces significant challenges related to stringent and varying regulatory standards across different regions. Electrolyte formulations often include active ingredients like sodium, potassium, and magnesium, which are regulated differently depending on the jurisdiction. This inconsistency can complicate product development and marketing strategies for companies operating internationally. Additionally, consumers are increasingly demanding transparency regarding product ingredients. They seek clean-label products free from artificial additives and preservatives, compelling manufacturers to reformulate existing products to meet these expectations.
Consumer Education and Market Differentiation
Another challenge is the need for effective consumer education. Many individuals lack a clear understanding of the benefits and appropriate usage of electrolyte supplements, leading to potential misuse or underuse. This gap in knowledge can hinder market growth and brand loyalty. Furthermore, the market is highly competitive, with numerous brands vying for consumer attention. Companies must invest in innovative marketing strategies and product differentiation to stand out. This includes developing unique formulations, offering diverse product formats, and emphasizing quality to build trust and attract a loyal customer base.
Market Opportunities:
Expansion of Functional Beverage Offerings
The Global Electrolyte Supplement Market presents significant opportunities through the development of functional beverages. Consumers increasingly seek products that offer more than basic hydration, favoring those that provide additional health benefits. This trend has led to the emergence of electrolyte-infused beverages that incorporate vitamins, minerals, and adaptogens, catering to the growing demand for multifunctional wellness products. Brands that innovate by combining electrolytes with other beneficial ingredients can attract health-conscious consumers looking for comprehensive hydration solutions.
Growth in Emerging Markets
Emerging markets offer substantial growth potential for the electrolyte supplement industry. Rising disposable incomes and increasing health awareness in regions such as Asia Pacific and Latin America are driving demand for electrolyte supplements. In these regions, consumers are becoming more proactive about health and wellness, leading to greater adoption of products that support hydration and overall well-being. Companies expanding their presence in these markets can tap into a burgeoning consumer base eager for quality electrolyte supplementation options.
Market Segmentation Analysis:
By Type
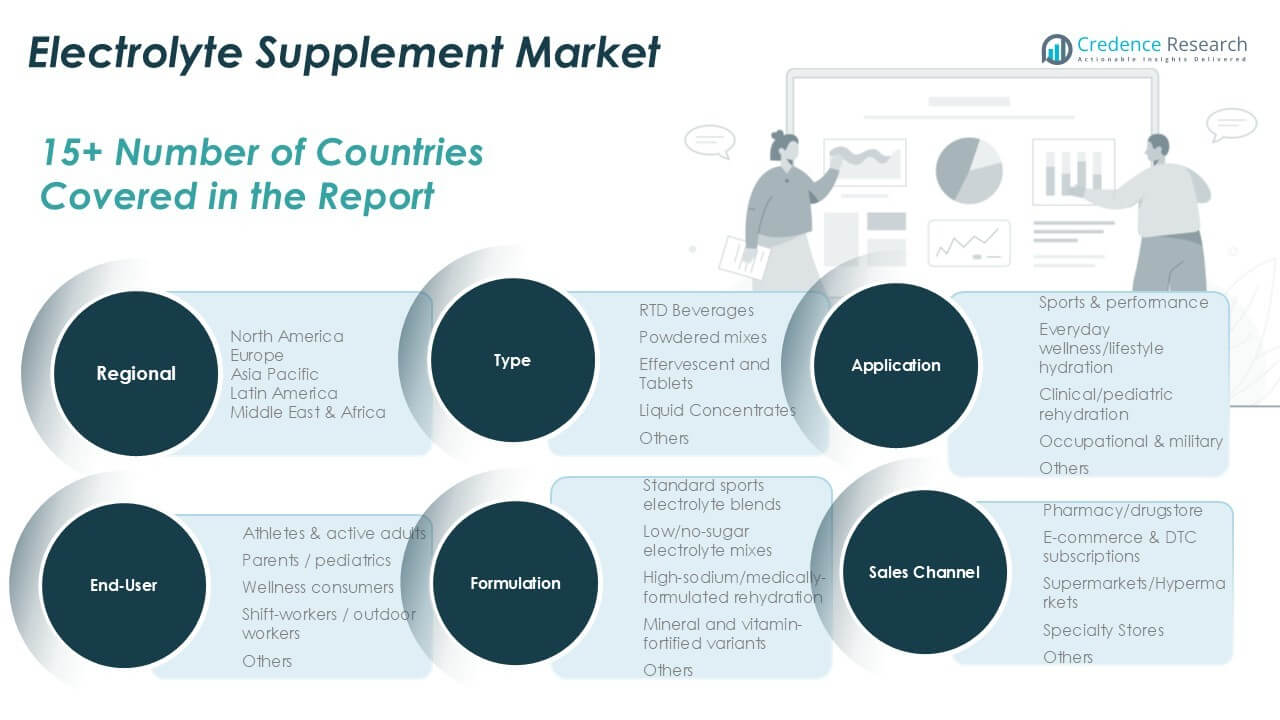
Powdered electrolyte supplements dominate the market, accounting for a significant share due to their portability, cost-effectiveness, and versatility. These products are widely used by athletes and fitness enthusiasts. Ready-to-drink (RTD) beverages follow closely in demand, offering convenience and immediate hydration. Effervescent tablets and liquid concentrates cater to specific consumer preferences, addressing various hydration needs.
- For instance, Dr. Berg’s Electrolyte Powder has distinguished itself by offering a sugar-free formulation that provides 1,000 mg of potassium per serving, catering to health-conscious consumers.
By Application
The sports and fitness sector leads in demand, driven by the growing participation in physical activities and the need for rapid electrolyte replenishment. Everyday wellness and lifestyle hydration applications are expanding as consumers increasingly focus on maintaining a healthy lifestyle. Clinical and pediatric rehydration applications also play a key role in the market, addressing medical needs for electrolyte balance in various health conditions.
- For instance, in clinical settings, oral rehydration therapy for children with moderate dehydration involves administering 100 mL of an electrolyte solution per kilogram of body weight over 4 hours to safely restore fluid balance.
By End-User
Athletes and active adults represent the largest consumer group, utilizing electrolyte supplements for enhanced performance and recovery. Wellness consumers are increasingly adopting these products as part of their daily health routines. Shift-workers and outdoor workers contribute to the market's growth, seeking hydration solutions to maintain energy levels during demanding work conditions.
Segmentations:
By Type- RTD Beverages
- Powdered Mixes
- Effervescent and Tablets
- Liquid Concentrates
- Others
- Sports & Performance
- Everyday Wellness/Lifestyle Hydration
- Clinical/Pediatric Rehydration
- Occupational & Military
- Others
- Athletes & Active Adults
- Parents/Pediatrics
- Wellness Consumers
- Shift-Workers/Outdoor Workers
- Others
- Standard Sports Electrolyte Blends
- Low/No-Sugar Electrolyte Mixes
- High-Sodium/Medically-Formulated Rehydration
- Mineral and Vitamin-Fortified Variants
- Others
- Pharmacy/Drugstore
- E-commerce & DTC Subscriptions
- Supermarkets/Hypermarkets
- Specialty Stores
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North American Electrolyte Supplement Market is anticipated to grow significantly, with its market size increasing from USD 1,629.00 million in 2018 to USD 1,835.24 million in 2024 and expected to reach USD 2,647.75 million by 2032. The region holds a substantial share in the global market, driven by a growing awareness of health and wellness, alongside the rising demand for fitness and sports nutrition products. North America’s large population base, combined with increasing consumer focus on hydration and performance recovery, propels market growth. Key players in the region are introducing innovative electrolyte supplements to cater to diverse consumer needs, which further accelerates market adoption. The rising trend of health-conscious millennials and the expansion of e-commerce platforms contribute to market expansion. As the market continues to grow, it is likely to maintain a significant share in the global electrolyte supplement industry.
Europe
In Europe, the Electrolyte Supplement Market is projected to expand from USD 1,210.50 million in 2018 to USD 1,328.07 million by 2024, ultimately reaching USD 1,814.73 million by 2032. The market’s growth is driven by a heightened focus on fitness, wellness, and the increasing demand for hydration supplements across the region. Europe’s diverse population and rising interest in sports and active lifestyles contribute to this upward trajectory. The adoption of electrolyte supplements in both clinical and non-clinical applications, such as sports hydration and lifestyle wellness, further drives market growth. European consumers are increasingly turning to supplements as part of a healthy lifestyle, particularly in countries with high levels of fitness participation. With continued product innovation and growing awareness of the benefits of electrolyte replenishment, the region is expected to maintain a strong market share in the global landscape.
Key Player Analysis:
- Abbott Laboratories
- Nestlé S.A.
- Unilever PLC
- GlaxoSmithKline plc
- Otsuka Pharmaceutical Co., Ltd.
- GU Energy Labs
- Skratch Labs
- Ultima Health Products, Inc.
- Hammer Nutrition
- SOS Hydration Inc.
- Liquid I.V.
- LyteLine LLC
- Hydralyte LLC
- Atlantic Essential Products, Inc.
- Denver Bodega LLC
- Sequel Natural LLC
- Kent Corporation
- Purity Organic, LLC
- GNC Holdings, Inc.
- Pocari Sweat (Otsuka Holdings Co., Ltd.)
- Osmo Nutrition
- GU Energy Labs
Competitive Analysis:
The global electrolyte supplement market is highly competitive, with major players like Nuun Hydration, Liquid I.V., Pedialyte (Abbott Laboratories), Skratch Labs, and Ultima Replenisher dominating through diverse product offerings and strong brand recognition. Emerging brands such as Hydralyte LLC, GU Energy Labs, and LyteLine LLC are gaining traction by focusing on clean-label formulations and functional benefits. Strategic partnerships and acquisitions, such as Unilever’s acquisition of Liquid I.V. and Celsius Holdings’ entry into hydration with caffeine-free products, are reshaping the competitive landscape. These companies continue to innovate and adapt to meet the growing demand for health-conscious hydration solutions, emphasizing product quality, sustainability, and expanding distribution networks.
Recent Developments:
- In May 2025, the U.S. Food and Drug Administration (FDA) approved Abbott's Tendyne™ transcatheter mitral valve replacement (TMVR) system, a first-of-its-kind device for treating mitral valve disease.
- In May 2025, Unilever began working to unlock AI innovation across its supply chain through its 100+ Accelerator partnership.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, End-User, Formulation, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The global electrolyte supplement market is expanding due to increased health awareness and active lifestyles.
- Consumers are shifting towards clean-label, low-sugar, and plant-based electrolyte products.
- Functional beverages with added electrolytes are gaining popularity, especially among younger demographics.
- E-commerce and direct-to-consumer channels are becoming primary sales avenues for electrolyte supplements.
- North America and Asia Pacific are leading regions in market growth and innovation.
- Athletes, fitness enthusiasts, and wellness-focused individuals are the primary consumers of these products.
- Companies are investing in research to develop natural and organic electrolyte formulations.
- Strategic partnerships and acquisitions are enhancing market presence and product offerings.
- Regulatory compliance and quality standards are becoming more stringent, influencing product development.
- The market is expected to continue growing as consumers prioritize hydration and overall wellness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Health and Fitness Consciousness
Increasing awareness of the importance of hydration and electrolyte balance among athletes, fitness enthusiasts, and the general population is driving demand for electrolyte supplements as part of daily wellness routines.
Product Innovation and Diversification
Manufacturers are expanding their product portfolios with new formulations such as plant-based, clean-label, and low/no-sugar electrolyte supplements, as well as convenient formats like powders, tablets, and RTD beverages, attracting a broader consumer base.
Expansion of Distribution Channels
The proliferation of e-commerce, DTC subscriptions, and wider retail availability is making electrolyte supplements more accessible, enabling brands to reach new customer segments and drive market growth.
Rising Participation in Sports and Physical Activities
A global increase in sports, fitness, and recreational activities is leading to higher demand for effective hydration solutions, as consumers seek products that support performance, recovery, and overall well-being.
Health Concerns Related to Dehydration
Growing awareness of the risks associated with dehydration, especially in hot climates and among vulnerable populations, is prompting consumers to adopt electrolyte supplements for preventive health and clinical rehydration purposes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Electrolyte Supplement Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Electrolyte Supplement market projected to grow between 2024 and 2032?
Which segment held the largest share in the Global Electrolyte Supplement market in 2024?
What are the primary factors fueling the growth of the Global Electrolyte Supplement market?
Which region commanded the largest share of the Global Electrolyte Supplement market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 RTD Beverages
- 1.2.2 Powdered Mixes
- 1.2.3 Effervescent and Tablets
- 1.2.4 Liquid Concentrates
- 1.2.5 Others
- 1.3 By End-User
- 1.3.1 Athletes & Active Adults
- 1.3.2 Parents/Pediatrics
- 1.3.3 Wellness Consumers
- 1.3.4 Shift-Workers/Outdoor Workers
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Sports & Performance
- 1.4.2 Everyday Wellness/Lifestyle Hydration
- 1.4.3 Clinical/Pediatric Rehydration
- 1.4.4 Occupational & Military
- 1.4.5 Others
- 1.5 By Sales Channel
- 1.5.1 Pharmacy/Drugstore
- 1.5.2 E-commerce & DTC Subscriptions
- 1.5.3 Supermarkets/Hypermarkets
- 1.5.4 Specialty Stores
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 4,500.00 million → 2032: USD 7,414.56 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electrolyte Supplement Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electrolyte Supplement Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electrolyte Supplement Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electrolyte Supplement Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electrolyte Supplement Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electrolyte Supplement Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electrolyte Supplement Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electrolyte Supplement Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 4,500.00 million → 2032: USD 7,414.56 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electrolyte Supplement Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 RTD Beverages
- 12.3.7.2 Powdered Mixes
- 12.3.7.3 Effervescent and Tablets
- 12.3.7.4 Liquid Concentrates
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Athletes & Active Adults
- 12.4.7.2 Parents/Pediatrics
- 12.4.7.3 Wellness Consumers
- 12.4.7.4 Shift-Workers/Outdoor Workers
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Sports & Performance
- 12.5.7.2 Everyday Wellness/Lifestyle Hydration
- 12.5.7.3 Clinical/Pediatric Rehydration
- 12.5.7.4 Occupational & Military
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Pharmacy/Drugstore
- 12.6.7.2 E-commerce & DTC Subscriptions
- 12.6.7.3 Supermarkets/Hypermarkets
- 12.6.7.4 Specialty Stores
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electrolyte Supplement End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electrolyte Supplement Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electrolyte Supplement Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electrolyte Supplement Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott Laboratories
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Nestlé S.A.
- 18.4 Unilever PLC
- 18.5 GlaxoSmithKline plc
- 18.6 Otsuka Pharmaceutical Co., Ltd.
- 18.7 GU Energy Labs
- 18.8 Skratch Labs
- 18.9 Ultima Health Products, Inc.
- 18.10 Liquid I.V.
- 18.11 Nuun Hydration
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

