
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
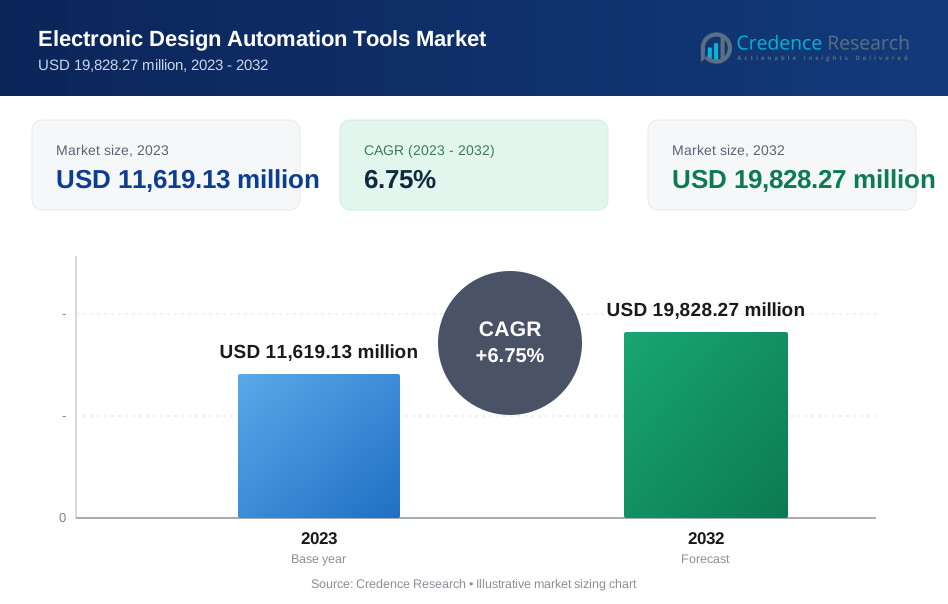
| Electronic Design Automation (EDA) Tools Market Size 2023 | USD 11,619.13 million |
| Electronic Design Automation (EDA) Tools Market, CAGR | 6.75% |
| Electronic Design Automation (EDA) Tools Market Size 2032 | USD 19,828.27 million |
Market Overview
The global Electronic Design Automation (EDA) Tools Market is poised for substantial growth over the forecast period from 2024 to 2032. With a projected increase from USD 11,619.13 million in 2023 to an estimated USD 19,828.27 million by 2032, the market demonstrates a robust compound annual growth rate (CAGR) of 6.75%. This growth trajectory is underpinned by several key factors, including the proliferation of complex integrated circuits (ICs) across various industries such as automotive, consumer electronics, and telecommunications. Additionally, the continuous demand for miniaturization and enhanced performance in electronic devices is driving the adoption of advanced EDA tools to streamline the design process and improve time-to-market for new products.
One of the driving forces behind the growth of the EDA tools market is the increasing complexity of semiconductor designs. As ICs become more intricate, designers require sophisticated tools to manage the design process efficiently. EDA tools offer capabilities such as electronic system-level (ESL) design, simulation, and verification, which are essential for optimizing performance, power consumption, and reliability of ICs. Moreover, the rising demand for System-on-Chip (SoC) and Application-Specific Integrated Circuit (ASIC) designs further fuels the adoption of EDA tools, as these technologies enable the integration of multiple functions onto a single chip, thereby enhancing efficiency and reducing costs.
Furthermore, the advent of advanced technologies such as artificial intelligence (AI), machine learning (ML), and Internet of Things (IoT) is reshaping the landscape of electronic design, driving the need for more sophisticated EDA solutions. AI and ML algorithms are increasingly being integrated into EDA tools to automate design tasks, improve design quality, and accelerate time-to-market. Additionally, the proliferation of IoT devices necessitates the development of specialized ICs with low power consumption and small form factors, driving the demand for EDA tools tailored to IoT applications.
The global Electronic Design Automation Tools Market is witnessing significant growth driven by the increasing complexity of semiconductor designs, the demand for advanced technologies such as AI and IoT, and the need for enhanced efficiency and time-to-market in electronic product development. As industries continue to innovate and introduce more complex electronic devices, the demand for sophisticated EDA tools is expected to rise further, presenting lucrative opportunities for market players to capitalize on this growing trend.
Segmentation Analysis
By Product Type:
- Computer-Aided Engineering (CAE): CAE tools encompass a range of software solutions for simulation, analysis, and optimization of electronic designs. Sub-segments may include electronic system-level (ESL) design, simulation, and verification tools.
- Printed Circuit Board (PCB) and Multi-Chip Module (MCM) Design Tools: These tools focus on the design and layout of PCBs and MCMs, crucial components in electronic device manufacturing. Offer functionalities such as schematic capture, layout design, routing, and signal integrity analysis.
- IC Physical Design and Verification Tools: These tools are essential for the physical implementation and verification of integrated circuits (ICs). Subcategories may include tools for layout design, physical synthesis, timing analysis, and design for manufacturability (DFM).
By End User
- Semiconductor Companies: Major consumers of EDA tools for designing and optimizing semiconductor chips, including SoCs, ASICs, and FPGAs. Require advanced design and verification tools to meet the demands of complex chip designs.
- Electronic Product Manufacturers: Utilize EDA tools for designing electronic products such as smartphones, tablets, laptops, and IoT devices. Require tools tailored to specific application requirements, including power efficiency, performance, and form factor.
By Application:
- Communication and Networking: EDA tools used for designing communication infrastructure, networking equipment, and wireless devices. Demand for high-speed, low-power designs drives the adoption of advanced EDA solutions in this segment.
- Consumer Electronics: EDA tools play a crucial role in designing consumer electronic devices such as smartphones, wearables, and home appliances. Focus on miniaturization, power efficiency, and innovative features drives demand for EDA tools in this segment.
By Deployment Mode:
- On-Premises: Traditional deployment model where EDA tools are installed and operated on the user's premises. Offers greater control and security but may require significant upfront investment in infrastructure.
- Cloud-Based: Emerging trend offering EDA tools as cloud-based services accessible over the internet. Provides scalability, flexibility, and reduced IT overhead, appealing to companies seeking cost-effective solutions.
By Region:
- North America: Leading region in terms of EDA tool adoption, driven by the presence of major semiconductor companies and technological innovation hubs.
- Europe: Significant market for EDA tools, particularly in automotive, aerospace, and industrial automation sectors.
- Asia Pacific: Fastest-growing region due to the proliferation of electronic manufacturing and semiconductor industries, particularly in China, Japan, South Korea, and Taiwan.
- Latin America, Middle East, and Africa (LAMEA): Emerging markets with increasing demand for EDA tools driven by industrialization and technological advancement efforts.
Segments
By Product Type:
- Computer-Aided Engineering (CAE)
- Printed Circuit Board (PCB) and Multi-Chip Module (MCM) Design Tools
- IC Physical Design and Verification Tools
By End User
- Semiconductor Companies
- Electronic Product Manufacturers
By Application:
- Communication and Networking
- Consumer Electronics
By Deployment Mode:
- On-Premises
- Cloud-Based
By Region:
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Australia
- Rest of Asia-Pacific
- Rest of the World
- Middle East
- Africa
- Latin America
Market Drivers
Firstly, the increasing complexity of integrated circuits (ICs) and semiconductor devices drives the demand for advanced EDA tools. As semiconductor technology continues to evolve, IC designs become more intricate, requiring sophisticated software solutions to facilitate the design process. For instance, modern microprocessors can contain over 2 billion transistors, highlighting the complexity of IC designs. EDA tools offer essential functionalities such as schematic capture, simulation, and layout automation, enabling engineers to design and verify complex ICs efficiently. The demand for EDA tools is further fueled by the rising adoption of emerging technologies such as artificial intelligence (AI), Internet of Things (IoT), and 5G telecommunications, which rely heavily on intricate semiconductor designs.
Secondly, the relentless pursuit of innovation and performance improvement in the electronics industry propels the EDA tools market forward. Companies strive to develop products with enhanced functionality, smaller form factors, and lower power consumption to meet the demands of consumers and industrial applications. For instance, the power consumption of ICs has been reduced by 90% over the past decade, demonstrating the industry’s focus on performance improvement. EDA tools play a critical role in this process by enabling designers to optimize IC designs for performance, power efficiency, and reliability. Whether it’s designing high-speed data processing systems or low-power IoT devices, EDA tools empower engineers to achieve design objectives efficiently, thereby driving innovation and competitiveness in the electronics market.
Thirdly, the growing emphasis on time-to-market and cost efficiency drives the adoption of EDA tools across the electronics industry. In today’s fast-paced business environment, companies face intense pressure to deliver products to market quickly while minimizing development costs. EDA tools streamline the design process, reduce iteration cycles, and enable designers to identify and address issues early in the development phase, thereby accelerating time-to-market. For example, using EDA tools can reduce the design cycle time by up to 50%. Additionally, the use of EDA tools helps companies optimize resource utilization, minimize design errors, and reduce overall development costs, making them indispensable assets for electronics manufacturers striving to maintain a competitive edge. As a result, the demand for EDA tools is expected to continue growing as companies prioritize efficiency and agility in product development to capitalize on market opportunities.
Market Trends
Rise of Artificial Intelligence (AI) and Machine Learning (ML):
The rise of Artificial Intelligence (AI) and Machine Learning (ML) is transforming the landscape of electronic design automation (EDA) tools, with these technologies being increasingly integrated into the software to enhance design automation, optimization, and verification processes. AI algorithms are utilized for tasks such as layout synthesis, pattern recognition, and design rule checking, facilitating faster and more accurate design iterations. For instance, AI algorithms can reduce the time required for layout synthesis by up to 30%, significantly expediting the design process. EDA vendors are investing in AI-driven solutions to cope with the growing complexity of integrated circuit (IC) designs, aiming to improve productivity for design engineers while addressing the evolving demands of the electronics industry.
Shift Towards Cloud-Based EDA Solutions:
There's a noticeable shift towards cloud-based electronic design automation (EDA) solutions, driven by the need for scalability, flexibility, and collaboration in design projects. Cloud-based EDA platforms offer on-demand access to powerful computing resources, enabling faster simulation, analysis, and collaboration among distributed design teams. For example, cloud-based EDA platforms can offer up to 5x the computational power of traditional on-premise solutions, facilitating faster simulation and analysis. Additionally, cloud-based solutions facilitate seamless integration with other design tools and allow companies to optimize their IT infrastructure costs.
Focus on Low-Power Design and Energy Efficiency:
With the proliferation of battery-powered devices and IoT applications, there's a growing emphasis on low-power design and energy efficiency in the electronic design automation (EDA) tools market. Designers are leveraging EDA tools to optimize power consumption, extend battery life, and meet stringent energy efficiency requirements. For instance, using EDA tools for power-aware design can improve the energy efficiency of integrated circuits (ICs) by up to 40%. EDA vendors are developing specialized tools and methodologies for power-aware design, including power analysis, optimization, and management techniques, to address the evolving needs of the industry in this regard.
Emergence of Low-Power Design Tools:
The demand for low-power electronic devices, particularly in IoT applications, is driving the emergence of specialized EDA tools focused on low-power design. According to a Synopsys article, these tools offer capabilities for power estimation, optimization, and management throughout the design process, enabling designers to meet stringent power consumption requirements without sacrificing performance or functionality. For instance, the emergence and exponential growth of breakthrough low-power IoT, wearable, hearable and edge devices has led to new system and IC design challenges where every nanowatt of power consumption or every picojoule of energy is drawn from the battery itself.
Adoption of Hardware-Assisted Verification:
Hardware-assisted verification methodologies, such as emulation and FPGA prototyping, are gaining traction in the EDA tools market. These technologies enable designers to accelerate the verification process by executing real-world tests on hardware platforms, providing more accurate results compared to traditional simulation-based approaches. The adoption of hardware-assisted verification tools is driven by the need to verify increasingly complex designs within shrinking time-to-market windows.
Growing Demand for System-Level Design Tools:
There is a growing demand for system-level design tools that enable designers to model, simulate, and optimize entire electronic systems rather than individual components. System-level design tools facilitate early architectural exploration, performance analysis, and trade-off analysis, helping designers make informed decisions and achieve optimal system-level performance. This trend is particularly prominent in industries such as automotive, aerospace, and telecommunications, where systems are becoming increasingly complex and interconnected.
Market Restraints and Challenges
High Initial Investment and Licensing Costs:
One of the primary challenges hindering the widespread adoption of EDA tools is the high initial investment and licensing costs associated with acquiring and maintaining these software solutions. The upfront costs of purchasing EDA tools, coupled with ongoing licensing fees for updates and support, can pose a significant financial barrier for small and medium-sized companies, limiting their ability to invest in advanced design technologies. Additionally, the complexity of pricing models and the need for specialized training further add to the total cost of ownership, making it challenging for organizations to justify the investment in EDA tools, particularly in cost-sensitive markets.
Complexity and Integration Challenges:
The increasing complexity of semiconductor designs poses significant challenges for designers in terms of managing design complexity, integrating disparate design components, and ensuring compatibility across various design tools and platforms. As designs become more intricate, designers face difficulties in optimizing performance, power consumption, and reliability, requiring sophisticated EDA tools with robust integration capabilities. However, the interoperability issues between different EDA tools and the lack of standardized design methodologies can impede seamless collaboration and hinder design productivity, leading to delays and increased design costs.
Shortage of Skilled Talent:
Another critical challenge facing the EDA tools market is the shortage of skilled talent with expertise in using advanced EDA software and methodologies. Designing complex electronic systems requires specialized knowledge and experience in areas such as IC design, verification, and system-level design. However, there is a growing gap between the demand for skilled EDA professionals and the availability of qualified talent, resulting in recruitment challenges for companies and potential productivity losses. Moreover, the rapid pace of technological innovation in the EDA industry necessitates continuous training and upskilling of existing workforce, further exacerbating the talent shortage issue.
Intellectual Property (IP) Protection Concerns:
IP protection concerns present a significant restraint for companies operating in the EDA tools market, particularly in the context of outsourcing design tasks to third-party vendors or collaborating with external partners. The sensitive nature of design data, including proprietary algorithms, architectures, and trade secrets, raises concerns about the risk of IP theft, unauthorized access, and infringement. As a result, companies may hesitate to fully leverage external resources or adopt cloud-based EDA solutions due to apprehensions regarding data security and confidentiality, limiting their ability to explore collaborative design opportunities and access scalable computing resources.
Regulatory Compliance and Standards Adherence:
The EDA tools market is subject to stringent regulatory requirements and industry standards governing the design and manufacture of electronic products, particularly in safety-critical sectors such as automotive, aerospace, and medical devices. Ensuring compliance with regulatory standards such as ISO 26262, DO-254, and IEC 61508 imposes additional burdens on EDA tool vendors and users in terms of documentation, validation, and certification. Non-compliance with regulatory requirements can result in costly penalties, product recalls, and damage to brand reputation, underscoring the importance of robust design methodologies and verification processes in the EDA industry.
Key players
- Cadence Design Systems, Inc.
- Synopsys, Inc.
- Mentor Graphics Corporation (A Siemens Business)
- ANSYS, Inc.
- Altium Limited
- Keysight Technologies, Inc.
- Zuken Inc.
- Silvaco, Inc.
- Xilinx, Inc.
- National Instruments Corporation
Recent Developments
- In July 2021, Zuken Inc. introduced CR-8000 2021, an enhanced iteration of CR-8000 with a primary emphasis on early design analysis and reuse functionality. This updated version aims to empower design teams with advanced tools for comprehensive analysis at the initial stages of the design process, facilitating more efficient and optimized product development cycles. By focusing on early design analysis and reuse functionality, Zuken Inc. seeks to streamline workflows and enhance productivity for engineers and designers working on complex electronic systems.
- In April 2021, ANSYS, Inc. unveiled a strategic collaboration with Advanced Micro Devices, Inc., aimed at empowering engineering teams across various industries to elevate their product design capabilities through the development of modeling run times. The collaboration leverages the performance capabilities of the 3rd Gen AMD EPYC 7003 Series processors, which have been shown to double the run time of Ansys simulations. By harnessing the enhanced computational power provided by AMD's processors, ANSYS aims to accelerate the simulation and modeling processes, enabling engineers to conduct more comprehensive analyses and iterate on designs more rapidly, ultimately leading to more innovative and competitive product designs.
Regional Analysis
North America holds a dominant position in the global EDA tools market, accounting for the largest market share percentage of approximately 40%. This region is characterized by a strong presence of leading EDA tool vendors, such as Cadence Design Systems, Synopsys, and Mentor Graphics (a Siemens Business), as well as a robust ecosystem of semiconductor companies and electronic product manufacturers. The United States, in particular, serves as a major hub for technological innovation and research and development activities in the EDA industry, driving significant market growth. Additionally, the increasing adoption of advanced technologies such as artificial intelligence (AI), machine learning (ML), and Internet of Things (IoT) further fuels demand for sophisticated EDA solutions in North America.
Europe is another significant market for EDA tools, accounting for a market share percentage of approximately 30%. The region is home to a diverse range of industries, including automotive, aerospace, telecommunications, and consumer electronics, all of which rely heavily on EDA tools for semiconductor design and electronic product development. Countries such as Germany, the United Kingdom, and France have well-established semiconductor industries and a strong engineering talent pool, driving market growth in the region. Moreover, the increasing emphasis on automotive electrification, Industry 4.0 initiatives, and smart city projects further stimulates demand for EDA tools in Europe, particularly for designing complex electronic systems and integrated circuits.
The Asia Pacific region is the fastest-growing market for EDA tools, with a market share percentage of approximately 25%. Rapid industrialization, technological advancement, and the proliferation of electronic manufacturing in countries such as China, Japan, South Korea, and Taiwan are driving significant market expansion in the region. Asia Pacific serves as a manufacturing hub for consumer electronics, automotive components, and semiconductor devices, driving substantial demand for EDA tools across various industries. Moreover, government initiatives aimed at promoting semiconductor manufacturing and fostering innovation, such as China's "Made in China 2025" and India's National Policy on Electronics, further contribute to market growth in the Asia Pacific region.
Future Outlook
- The EDA tools market is poised for sustained growth driven by increasing demand for complex semiconductor designs across various industries, with a projected compound annual growth rate (CAGR) of over 6% in the coming years.
- Adoption of artificial intelligence (AI) and machine learning (ML) technologies will continue to reshape the EDA landscape, enabling automation of design tasks, optimization of performance, and acceleration of time-to-market.
- The proliferation of Internet of Things (IoT) devices and automotive electronics will fuel demand for specialized EDA tools tailored to power-efficient, small-form-factor designs, driving innovation in the market.
- There will be a growing emphasis on system-level design tools that enable holistic optimization of electronic systems, addressing challenges related to performance, power, and reliability across interconnected components.
- With increasing concerns about cybersecurity and functional safety in electronic systems, EDA tool vendors will prioritize the development of solutions that incorporate robust security features and compliance with industry standards.
- As quantum computing technologies advance, there will be a growing need for specialized EDA tools for quantum circuit design, simulation, and verification, opening up new avenues for market expansion.
- With the growing complexity of semiconductor designs, there will be increased demand for design-for-test (DFT) solutions that enable efficient testing and diagnosis of ICs, ensuring high product reliability and yield.
- The shift towards cloud-based EDA solutions will accelerate, driven by the need for scalability, flexibility, and cost efficiency, enabling companies to access powerful computational resources on-demand.
- Collaboration among geographically dispersed design teams will become more prevalent, facilitated by cloud-based collaboration platforms and virtual design environments, fostering innovation and accelerating product development cycles
- Compliance with regulatory requirements such as ISO standards and environmental regulations will become increasingly important, influencing the development of EDA tools that enable sustainable and compliant design practices.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for the Electronic Design Automation (EDA) Tools Market in 2023, 2032, and the Compound Annual Growth Rate (CAGR)?
What is driving the growth of the EDA tools market?
What are the key segments in the EDA tools market?
How do EDA tools address challenges in semiconductor design?
What are the future trends shaping the EDA tools market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 11,619.13 million → 2032: USD 19,828.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electronic Design Automation Tools Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electronic Design Automation Tools Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electronic Design Automation Tools Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electronic Design Automation Tools Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electronic Design Automation Tools Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electronic Design Automation Tools Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electronic Design Automation Tools Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electronic Design Automation Tools Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 11,619.13 million → 2032: USD 19,828.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electronic Design Automation Tools Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electronic Design Automation Tools Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Share, 2023
- 13.2 Regional Market Forecast, 2023-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Electronic Design Automation Tools Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Electronic Design Automation Tools Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
