
Market Overview:
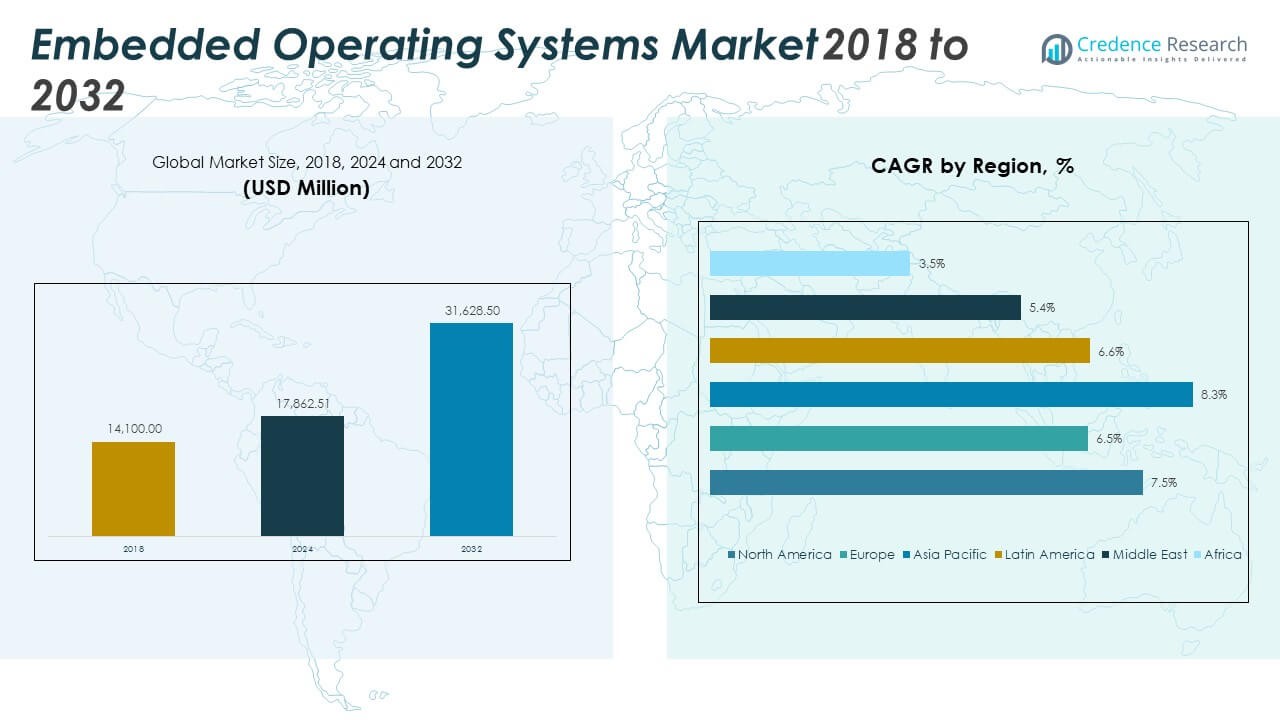
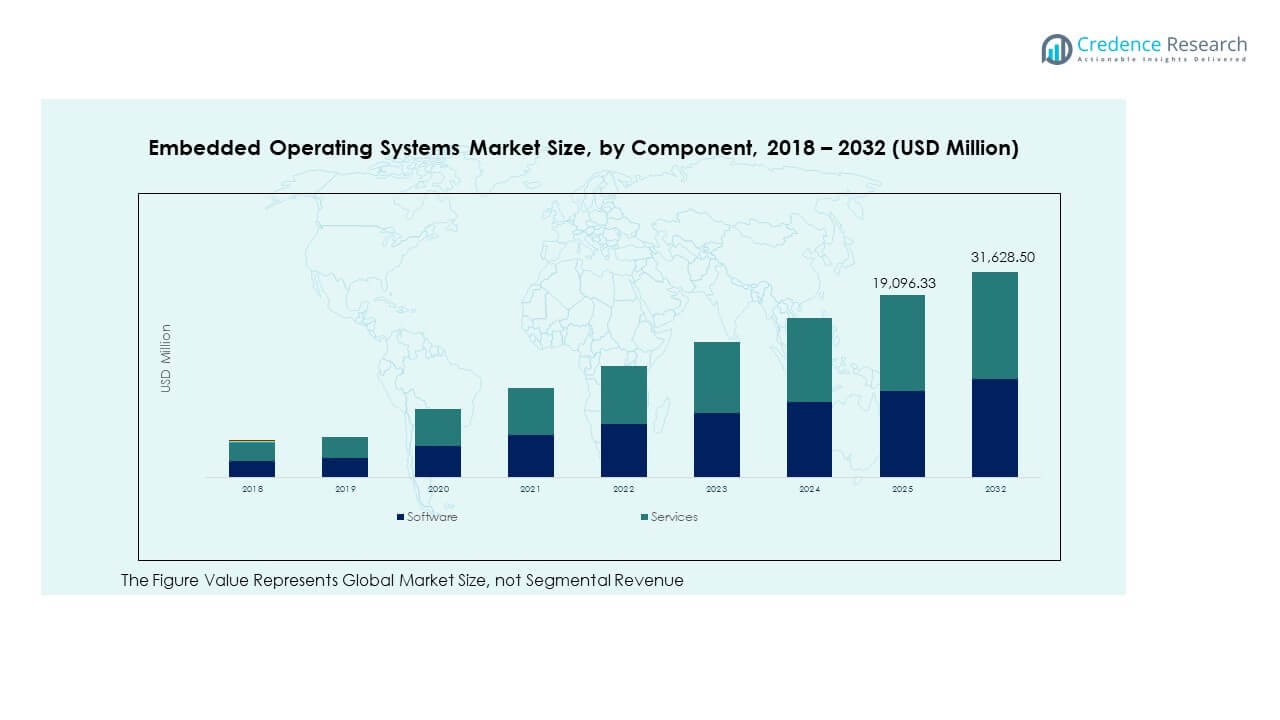
The Embedded Operating Systems Market size was valued at USD 14,100.00 million in 2018 to USD 17,862.51 million in 2024 and is anticipated to reach USD 31,628.50 million by 2032, at a CAGR of 7.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Embedded Operating Systems Market Size 2024 | USD 17,862.51 Million |
| Embedded Operating Systems Market, CAGR | 7.47% |
| Embedded Operating Systems Market Size 2032 | USD 31,628.50 Million |
Strong adoption of IoT, AI integration, and edge computing is driving demand across industries. Automotive and industrial automation companies use embedded OS to enable real-time operations and enhance system performance. It supports advanced connectivity, security, and scalability for mission-critical applications. Vendors focus on developing lightweight, secure platforms optimized for next-generation devices. Growing emphasis on intelligent systems further accelerates product innovation and ecosystem expansion.
North America leads the market due to its mature technology infrastructure and strong enterprise adoption. Europe shows steady growth with advanced automotive and industrial applications. Asia Pacific emerges as the fastest-growing region, supported by strong manufacturing capacity and rising digital transformation initiatives. Latin America, the Middle East, and Africa are expanding steadily, backed by smart infrastructure investments and increasing IoT deployment.
Market Insights:
- The Embedded Operating Systems Market was valued at USD 14,100.00 million in 2018, reached USD 17,862.51 million in 2024, and is projected to reach USD 31,628.50 million by 2032, growing at a CAGR of 7.47%.
- Asia Pacific holds the largest share at 41.1%, driven by strong manufacturing, IoT adoption, and 5G expansion. North America follows with 29.3% share due to advanced infrastructure and innovation, while Europe contributes 22.7% supported by its automotive and industrial base.
- Asia Pacific is the fastest-growing region, supported by rapid digital transformation, large-scale production ecosystems, and strong technology investments.
- Software accounts for 60% of the market share, reflecting its central role in system functionality, security, and real-time processing.
- Services represent 40% of the market share, driven by rising integration, customization, and lifecycle support across industries.
Market Drivers
Rising Integration of Embedded OS in Automotive and Industrial Applications
Growing adoption of smart and automated systems drives strong demand in the automotive and industrial sectors. Companies deploy embedded operating systems to support advanced control systems, real-time monitoring, and connected vehicle solutions. Automotive OEMs focus on enhancing safety, infotainment, and ADAS features using efficient OS platforms. Industrial firms use these systems to optimize manufacturing lines, reduce downtime, and boost operational visibility. The [Embedded Operating Systems Market] benefits from the rapid shift toward Industry 4.0. It plays a critical role in enabling interoperability between machines and devices. Standardized platforms simplify deployment and reduce integration complexity. This trend accelerates market penetration across multiple industries.
- For example, according to BlackBerry (October 2024), QNX OS powers more than 255 million vehicles globally. It supports advanced driver assistance systems, digital cockpits, and domain controllers for major OEMs such as BMW, Volkswagen, and Toyota.
Expanding IoT Ecosystem and Connected Device Adoption
The fast-growing IoT landscape fuels strong demand for embedded OS platforms. Businesses deploy these systems to manage large-scale networks of sensors, controllers, and smart devices. Advanced connectivity enables real-time data exchange and improved decision-making. It supports automation across home automation, healthcare, industrial operations, and retail. Manufacturers aim to enhance energy efficiency and performance through optimized OS solutions. The [Embedded Operating Systems Market] gains strength from increasing IoT device shipments worldwide. Widespread connectivity requires stable, secure, and lightweight operating systems. This demand pushes vendors to innovate and deliver scalable architectures.
- For example, according to the Eclipse Foundation’s 2024 IoT & Embedded Developer Survey, FreeRTOS held 29% adoption among connected device developers, while Zephyr accounted for 21%. The findings highlight the strong and expanding open-source ecosystem driving IoT and industrial applications.
Advancements in Edge Computing and Real-Time Processing
Edge computing adoption is driving a need for highly responsive and reliable embedded systems. Companies use these solutions to process data locally, reduce latency, and enhance system performance. Real-time processing improves automation in healthcare, automotive, defense, and telecommunications. It enables faster analytics and improved device responsiveness in mission-critical applications. The [Embedded Operating Systems Market] benefits from this shift toward decentralized data management. Vendors develop lightweight, secure OS platforms that integrate easily with edge infrastructure. It improves system efficiency and lowers bandwidth costs. This driver enhances the value proposition of embedded operating solutions.
Growing Focus on Cybersecurity and System Reliability
Strong emphasis on security is fueling demand for robust embedded OS platforms. Organizations face increasing risks of data breaches and system vulnerabilities. Reliable OS frameworks help secure sensitive operations in automotive, defense, healthcare, and telecom applications. Built-in encryption, secure boot, and authentication mechanisms strengthen system resilience. The [Embedded Operating Systems Market] responds to this demand by offering advanced security features. It provides controlled environments that minimize external threats. Vendors also focus on compliance with global security standards. This growing focus ensures higher trust in mission-critical embedded systems.
Market Trends
Increased Use of AI and Machine Learning in Embedded OS Platforms
AI and machine learning are shaping how modern embedded operating systems function. Integration of intelligent algorithms improves system adaptability and performance in complex environments. Companies deploy these technologies in automotive, robotics, and healthcare devices. AI-powered embedded systems enhance predictive maintenance and autonomous decision-making. It strengthens the capability of OS platforms to handle advanced analytics at the edge. The [Embedded Operating Systems Market] is witnessing rising investment in AI frameworks for embedded devices. Machine learning models are being optimized for low-power environments. This trend supports advanced applications with minimal resource use.
- For example, according to NVIDIA, the Jetson Orin Nano Super Developer Kit delivers up to 67 TOPS of AI performance and provides a 1.7× performance boost over the previous generation. It is designed to power edge AI applications, including robotics and autonomous machines.
Growing Popularity of Open-Source and Modular OS Architectures
Enterprises are shifting toward open-source embedded OS platforms for flexibility and cost advantages. Modular architectures enable developers to build customized solutions for specific applications. This approach supports faster integration and easier scalability across devices. It reduces vendor dependency and fosters innovation across industries. The [Embedded Operating Systems Market] benefits from the rapid adoption of Linux-based and real-time OS platforms. It helps organizations achieve better interoperability between hardware and software layers. Community-driven development accelerates feature enhancements and improves reliability. This trend strengthens ecosystem collaboration between vendors and developers.
- For example, according to the Zephyr Project, co-managed by the Linux Foundation, the platform supports hardware from major vendors such as Nordic Semiconductor, NXP, Intel, and STMicroelectronics. Its upstream GitHub repository tracks hundreds of supported boards and SoCs, making it a widely adopted choice for embedded and IoT development.
Increased Adoption of 5G Connectivity to Enable High-Performance Applications
5G technology drives major changes in how embedded systems operate across industries. Faster data transmission and ultra-low latency support advanced applications in autonomous vehicles, robotics, and smart manufacturing. Embedded OS platforms enable stable performance in high-speed networks. It allows seamless connectivity between multiple smart devices. The [Embedded Operating Systems Market] benefits from the deployment of 5G infrastructure worldwide. Vendors are optimizing their OS platforms for better network integration. This trend enables real-time control in critical systems and improves operational agility. High-speed connectivity creates new growth avenues for embedded technologies.
Expansion of Cloud-Native Embedded Systems for Scalable Deployments
Cloud-native architectures are gaining momentum across embedded system deployments. Companies integrate embedded OS with cloud platforms to enable real-time updates, remote monitoring, and predictive analytics. It simplifies lifecycle management and improves operational flexibility. The [Embedded Operating Systems Market] sees strong adoption of containerized environments that allow scalable rollouts. Developers use microservices and virtualization to enhance deployment speed. This approach ensures better system availability and cost efficiency. Cloud-native strategies also enhance interoperability with enterprise IT infrastructure. This trend pushes innovation in embedded OS platforms.
Market Challenges Analysis
Complexity of Integration Across Diverse Hardware and Software Ecosystems
Integrating embedded OS platforms with a wide variety of hardware and software ecosystems poses major technical challenges. Companies face difficulties aligning different architectures, interfaces, and communication protocols. It increases development cycles and raises integration costs for large-scale deployments. Fragmented standards across industries complicate compatibility efforts further. The [Embedded Operating Systems Market] must overcome these obstacles to ensure smooth interoperability. Vendor-specific systems often lack flexibility, limiting adaptability to new environments. This challenge slows innovation and restricts scalability in several critical applications. Improved standardization and unified frameworks are essential to address this issue.
High Security Risks and Compliance Barriers in Mission-Critical Applications
Security remains a critical concern due to increasing threats and compliance demands. Embedded OS platforms handle sensitive functions in healthcare, automotive, and defense. Any vulnerability can lead to system failures or data breaches. Meeting strict security certifications and regulatory requirements requires major investment. The [Embedded Operating Systems Market] faces mounting pressure to ensure protection against evolving cyberattacks. It must address issues related to secure boot, encryption, and access control. Achieving consistent compliance across multiple geographies and sectors remains difficult. These security challenges limit widespread adoption in certain high-risk industries.
Market Opportunities
Rising Demand for Embedded OS in Smart Cities and Industrial Automation
Expanding smart city projects and automated industrial operations offer strong opportunities for growth. Embedded OS platforms play a key role in powering intelligent transportation, smart grids, and connected infrastructure. Industrial players adopt these solutions to improve productivity and reduce energy costs. The [Embedded Operating Systems Market] stands to gain from this surge in deployment across public and private sectors. It aligns well with the ongoing digital transformation initiatives. Vendors can develop specialized OS platforms to support scalable and secure operations. This opens new revenue streams for global suppliers.
Emergence of New Applications in Healthcare and Consumer Electronics
Healthcare and consumer electronics industries present major opportunities for embedded OS providers. Hospitals deploy connected devices for patient monitoring, diagnostics, and data collection. Consumer electronics brands integrate lightweight OS platforms into wearables, home automation, and AR/VR systems. The [Embedded Operating Systems Market] is expanding through these dynamic application areas. It enables companies to diversify their portfolios and target new customer segments. These opportunities support stronger market penetration in both developed and emerging economies. Vendors focusing on innovation can capture long-term growth potential in these high-demand verticals.
Market Segmentation Analysis:
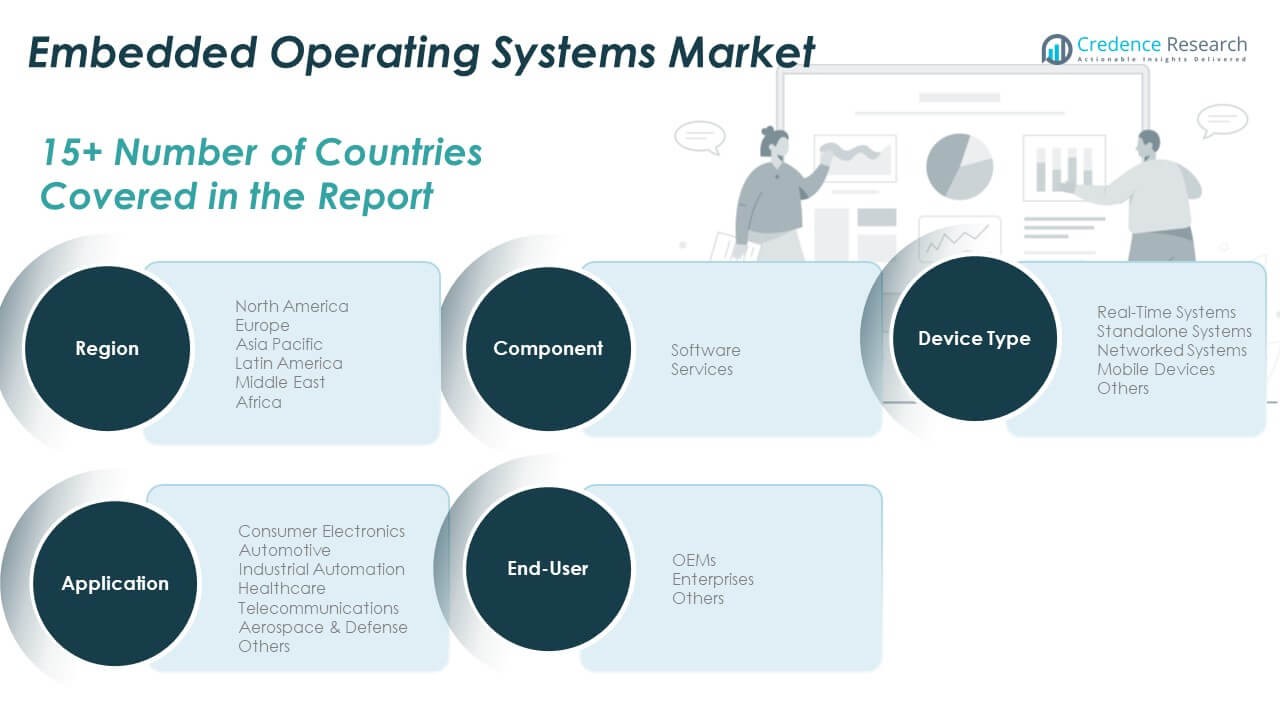
By Component, software holds the dominant share due to its critical role in enabling device functionality, security, and performance. Vendors focus on real-time operating systems and open-source solutions to meet growing connectivity needs. Services also play a significant role, supporting integration, updates, and maintenance across industries.
- For example, according to the Linux Foundation (July 2024), the Zephyr RTOS supports over 700 hardware boards and introduced new HTTP/2 server and IEEE 1588 PTP protocol features in its 3.7 Long-Term Support release, enhancing industrial-grade reliability for connected devices.
By Application, consumer electronics leads due to the widespread use of smart devices, wearables, and home automation products. Automotive and industrial automation segments show strong demand driven by advanced vehicle systems and Industry 4.0 adoption. Healthcare, telecommunications, and aerospace & defense contribute steady growth through specialized, secure applications that require real-time processing and high system reliability.
By End-User, OEMs dominate the market with large-scale deployments across manufacturing and automotive sectors. Enterprises increasingly adopt embedded OS platforms to improve operational efficiency, security, and device interoperability. Other end users support niche applications in defense, telecom, and healthcare.
- For example, according to Wind River, VxWorks 653 is used by more than 360 customers across over 600 safety programs in more than 100 civilian and military aircraft. It supports certification to safety standards such as ISO 26262 and IEC 61508, and is widely deployed in aerospace and industrial applications.
By Device Type, real-time systems maintain strong market presence due to their role in mission-critical operations. Networked systems and mobile devices are expanding rapidly with the growth of IoT and 5G connectivity. Standalone systems and other device types continue to support embedded solutions in specialized environments. The [Embedded Operating Systems Market] benefits from this broad application landscape, driving innovation and competitive differentiation across all segments.
Segmentation:
By Component
- Software
- Services
By Application
- Consumer Electronics
- Automotive
- Industrial Automation
- Healthcare
- Telecommunications
- Aerospace & Defense
- Others
By End-User
- OEMs
- Enterprises
- Others
By Device Type
- Real-Time Systems
- Standalone Systems
- Networked Systems
- Mobile Devices
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Embedded Operating Systems Market size was valued at USD 4,201.80 million in 2018 to USD 5,244.33 million in 2024 and is anticipated to reach USD 9,270.37 million by 2032, at a CAGR of 7.5% during the forecast period. North America holds a 29.3% share of the global market. Strong adoption of IoT and edge computing across automotive, healthcare, and industrial automation fuels growth in this region. It benefits from advanced infrastructure and high R&D investments by leading technology companies. Government and private sector initiatives promote smart manufacturing and autonomous mobility solutions. It sees rising integration of AI in embedded systems to enhance performance and cybersecurity. Major players expand their presence through strategic partnerships and product innovation. The demand for real-time systems and mobile devices continues to rise, driven by connectivity advancements. The [Embedded Operating Systems Market] in this region remains a hub for early adoption and innovation.
Europe
The Europe Embedded Operating Systems Market size was valued at USD 3,003.30 million in 2018 to USD 3,622.03 million in 2024 and is anticipated to reach USD 5,969.96 million by 2032, at a CAGR of 6.5% during the forecast period. Europe accounts for a 22.7% share of the global market. Strong automotive and industrial automation industries anchor market demand. Germany, France, and the UK drive growth with heavy investments in automotive electronics and smart manufacturing. It benefits from regulatory support for secure and efficient embedded platforms. Rising demand for sustainable and connected systems supports the adoption of real-time operating environments. Enterprises in aerospace and defense expand the use of embedded OS for advanced control systems. The market also grows through collaboration between OEMs and software vendors. Strong focus on security and compliance strengthens the regional competitive edge.
Asia Pacific
The Asia Pacific Embedded Operating Systems Market size was valued at USD 5,414.40 million in 2018 to USD 7,052.94 million in 2024 and is anticipated to reach USD 13,325.11 million by 2032, at a CAGR of 8.3% during the forecast period. Asia Pacific leads the global market with a 41.1% share. Strong growth in consumer electronics and telecommunications drives demand for embedded platforms. China, Japan, South Korea, and India are key contributors, supported by large-scale manufacturing and strong government initiatives. It benefits from the rapid expansion of IoT ecosystems and 5G infrastructure. Rising investment in industrial automation and smart cities creates strong opportunities. Vendors expand their presence through partnerships with local OEMs and component suppliers. The region also sees increasing use of embedded OS in healthcare and automotive sectors. Asia Pacific remains a core growth engine for global market expansion.
Latin America
The Latin America Embedded Operating Systems Market size was valued at USD 958.80 million in 2018 to USD 1,203.75 million in 2024 and is anticipated to reach USD 1,988.48 million by 2032, at a CAGR of 6.6% during the forecast period. Latin America holds a 6.1% share of the global market. Rapid digital transformation in manufacturing, automotive, and telecommunications sectors supports steady growth. Brazil and Argentina lead adoption with investments in smart devices and automation solutions. It benefits from government initiatives focused on Industry 4.0 and connected infrastructure. Enterprises are expanding IoT networks to improve operational efficiency and reduce costs. Healthcare and defense applications also contribute to growing OS deployment. International vendors are partnering with local firms to strengthen distribution. The market gains momentum with improved connectivity and increasing smart technology adoption.
Middle East
The Middle East Embedded Operating Systems Market size was valued at USD 366.60 million in 2018 to USD 421.44 million in 2024 and is anticipated to reach USD 635.91 million by 2032, at a CAGR of 5.4% during the forecast period. The Middle East accounts for a 2.0% share of the global market. Smart city projects and industrial modernization initiatives drive demand. GCC countries lead with major infrastructure investments and IoT integration programs. It benefits from the rising deployment of real-time embedded systems in transportation, energy, and security. Enterprises focus on digital transformation to enhance competitiveness. Vendors target the region with secure and scalable OS platforms suitable for harsh environments. Strong emphasis on automation boosts the adoption of embedded solutions. Market growth remains steady, supported by long-term infrastructure planning.
Africa
The Africa Embedded Operating Systems Market size was valued at USD 155.10 million in 2018 to USD 318.03 million in 2024 and is anticipated to reach USD 438.66 million by 2032, at a CAGR of 3.5% during the forecast period. Africa holds a 1.4% share of the global market. Growth is driven by the gradual expansion of digital infrastructure and increased adoption of smart devices. South Africa and Egypt lead in deploying embedded OS in telecommunications and industrial sectors. It benefits from rising investment in connectivity and smart city projects. Healthcare and energy segments contribute to increasing OS integration. International vendors explore partnerships to tap into emerging opportunities. Market growth is slower compared to other regions due to infrastructure challenges. Strategic investments in connectivity are expected to drive future expansion of the [Embedded Operating Systems Market] across the region.
Key Player Analysis:
- Microsoft Corporation
- Green Hills Software
- Wind River Systems
- Mentor Graphics (Siemens)
- IBM Corporation
- Apple Inc.
- Google LLC
- BlackBerry QNX
- ARM Holdings
- Express Logic (acquired by Microsoft)
- SYSGO GmbH
- ENEA AB
- Micrium (acquired by Silicon Labs)
- Altera (Intel Corporation)
- Texas Instruments
- NXP Semiconductors
- STMicroelectronics
- Renesas Electronics Corporation
- Huawei Technologies Co., Ltd.
- Samsung Electronics Co., Ltd.
Competitive Analysis:
The Embedded Operating Systems Market features strong competition among global and regional players focusing on innovation, scalability, and security. Major companies such as Microsoft Corporation, Green Hills Software, Wind River Systems, IBM Corporation, Apple Inc., and Google LLC lead with extensive product portfolios and advanced OS platforms. It benefits from continuous investments in AI, edge computing, and cybersecurity features to strengthen performance. Vendors target automotive, industrial, and consumer electronics sectors with real-time solutions tailored to specific applications. Strategic partnerships, mergers, and acquisitions help expand market reach and technical capabilities. Open-source adoption drives flexibility and competitive pricing strategies. Emerging players focus on niche applications and customized OS platforms to gain market share. Strong competition pushes innovation cycles faster, creating a dynamic and evolving ecosystem.
Recent Developments:
- In October 2025, Wind River Systems formed a strategic partnership with Black Box to accelerate intelligent edge and private cloud computing solutions. Utilizing the Wind River Cloud Platform and eLxr Pro, the collaboration aims to enhance edge infrastructure efficiency and scalability across industrial, telecommunications, and automotive applications, reinforcing Wind River’s dominance in real-time embedded systems.
- In April 2025, Microsoft Corporation launched its next-generation Windows Server 2025 specifically designed for industrial and embedded environments. The release integrates AI-driven automation, advanced hybrid cloud capabilities via Azure Arc, and cybersecurity enhancements aimed at supporting smart manufacturing infrastructures.
- In March 2025, Green Hills Software announced a collaboration with NXP Semiconductors focused on integrated software and hardware solutions for the newly launched S32K5 microcontroller family. The partnership combines Green Hills’ ASIL D-certified µ-velOSity RTOS and µ-visor hypervisor with NXP’s cutting-edge automotive architecture, targeting safety-critical embedded systems such as those in next-generation vehicles.
- In March 2025, IBM Corporation extended its collaboration with Nvidia to deliver GPU-accelerated AI and embedded solutions on IBM Cloud and Power Systems. This partnership integrates IBM’s AI-powered watsonx.data offering with Nvidia's BlueField-3 DPUs and Spectrum-X networking technologies, optimizing performance for embedded AI workloads across hybrid and edge systems.
Report Coverage:
The research report offers an in-depth analysis based on Component, Application, End-User and Device Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for IoT and smart devices will accelerate adoption across multiple industries.
- Edge computing integration will strengthen real-time processing capabilities in critical applications.
- AI-driven embedded platforms will enhance automation and predictive intelligence in connected systems.
- Cybersecurity advancements will shape future OS architecture and compliance strategies.
- Cloud-native deployment models will expand flexible and scalable system integration.
- Automotive and industrial automation will remain key growth drivers for next-generation OS platforms.
- Open-source frameworks will gain traction, offering customization and cost efficiency.
- 5G infrastructure growth will boost networked and mobile device adoption.
- Strategic partnerships and M&A will expand global reach and technical capabilities.
- Emerging regions will experience steady growth with rising digital infrastructure investments in the [Embedded Operating Systems Market].

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Integration of Embedded OS in Automotive and Industrial Applications
Automotive and industrial sectors are increasingly deploying embedded operating systems to enable advanced control, real-time monitoring, and connected vehicle solutions. This trend is driven by the need for enhanced safety, infotainment, and automation, supporting the shift toward Industry 4.0 and smart manufacturing.
Expanding IoT Ecosystem and Connected Device Adoption
The proliferation of IoT devices across industries such as home automation, healthcare, and retail is fueling demand for embedded OS platforms that can manage large-scale, secure, and real-time device networks. This expansion requires lightweight, scalable, and secure operating systems to support billions of connected devices.
Advancements in Edge Computing and Real-Time Processing
Edge computing adoption is increasing the need for embedded OS solutions that can process data locally, reduce latency, and ensure high system responsiveness. Real-time processing capabilities are critical for mission-critical applications in healthcare, automotive, and telecommunications, driving innovation in embedded OS design.
Growing Focus on Cybersecurity and System Reliability
With rising threats of data breaches and system vulnerabilities, organizations are prioritizing robust embedded OS platforms with advanced security features such as encryption, secure boot, and authentication. This focus on cybersecurity and compliance is essential for adoption in automotive, defense, healthcare, and telecom sectors.
Increased Use of AI and Machine Learning in Embedded OS Platforms
The integration of AI and machine learning into embedded operating systems is enhancing system adaptability, predictive maintenance, and autonomous decision-making. This enables smarter, more efficient devices in automotive, robotics, and industrial automation, further accelerating market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Embedded Operating Systems Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Embedded Operating Systems Market projected to grow between 2024 and 2032?
Which Embedded Operating Systems Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Embedded Operating Systems Market?
Who are the leading companies in the Embedded Operating Systems Market?
Which region commanded the largest share of the Embedded Operating Systems Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 OEMs
- 1.2.2 Enterprises
- 1.2.3 Others
- 1.3 By Component
- 1.3.1 Software
- 1.3.2 Services
- 1.4 By Application
- 1.4.1 Consumer Electronics
- 1.4.2 Automotive
- 1.4.3 Industrial Automation
- 1.4.4 Healthcare
- 1.4.5 Telecommunications
- 1.4.6 Aerospace & Defense
- 1.4.7 Others
- 1.5 By Device Type
- 1.5.1 Real-Time Systems
- 1.5.2 Standalone Systems
- 1.5.3 Networked Systems
- 1.5.4 Mobile Devices
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 17,862.51 million → 2032: USD 31,628.50 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Embedded Operating Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Embedded Operating Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Embedded Operating Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Embedded Operating Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Embedded Operating Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Embedded Operating Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Embedded Operating Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Embedded Operating Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 17,862.51 million → 2032: USD 31,628.50 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Embedded Operating Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 OEMs
- 12.3.7.2 Enterprises
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Software
- 12.4.7.2 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Consumer Electronics
- 12.5.7.2 Automotive
- 12.5.7.3 Industrial Automation
- 12.5.7.4 Healthcare
- 12.5.7.5 Telecommunications
- 12.5.7.6 Aerospace & Defense
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Device Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Real-Time Systems
- 12.6.7.2 Standalone Systems
- 12.6.7.3 Networked Systems
- 12.6.7.4 Mobile Devices
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Embedded Operating Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Embedded Operating Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Embedded Operating Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Embedded Operating Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Microsoft Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Wind River Systems
- 18.4 Green Hills Software
- 18.5 BlackBerry QNX
- 18.6 Apple Inc.
- 18.7 Google LLC
- 18.8 IBM Corporation
- 18.9 Mentor Graphics (Siemens)
- 18.10 NXP Semiconductors
- 18.11 ARM Holdings
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

