
Market Overview
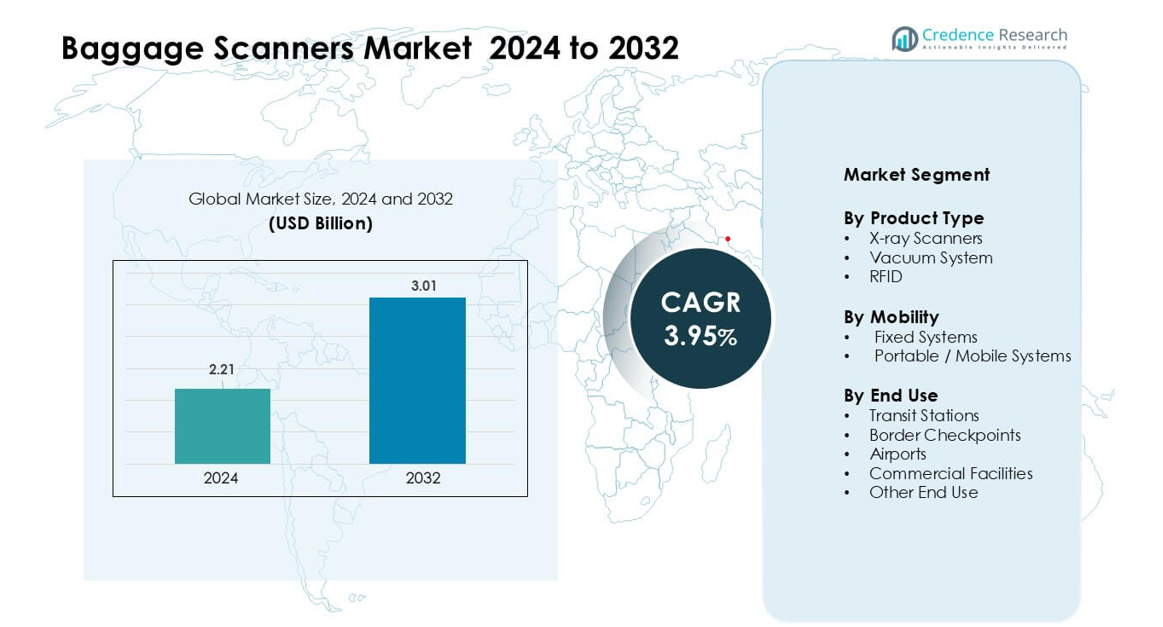
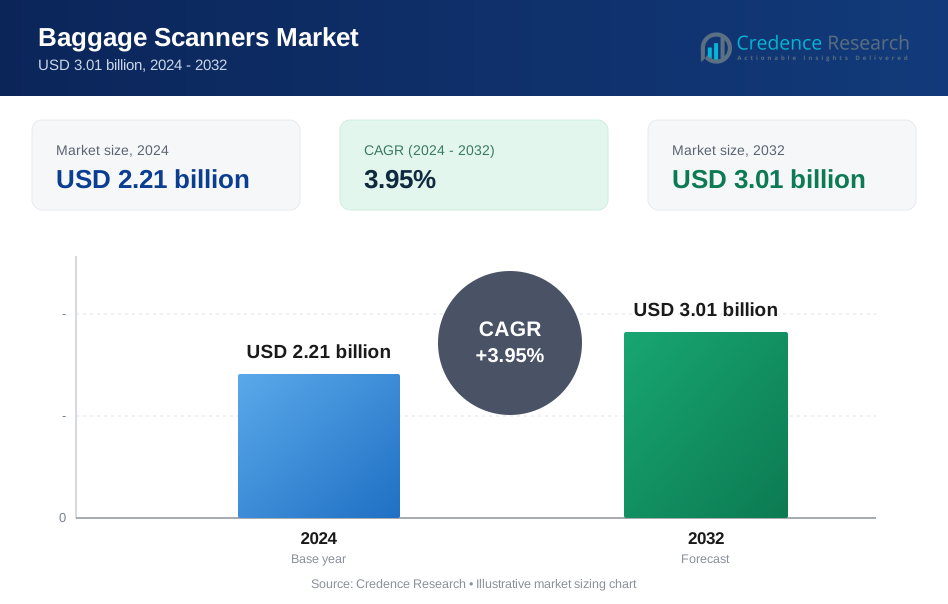
Baggage Scanners Market was valued at USD 2.21 billion in 2024 and is anticipated to reach USD 3.01 billion by 2032, growing at a CAGR of 3.95 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Baggage Scanners Market Size 2024 | USD 2.21 billion |
| Baggage Scanners Market, CAGR | 3.95% |
| Baggage Scanners Market Size 2032 | USD 3.01 billion |
The Baggage Scanners Market is shaped by key players such as CEIA SpA, Kromek Group plc, Teledyne ICM, Autoclear LLC, Gilardoni S.p.A., Astrophysics Inc., IDSS, Nikon Metrology, L3Harris Technologies’ legacy security units, and VOTI Detection Inc. These companies compete by offering advanced multi-view, dual-energy, and CT-based scanners that enhance detection accuracy and reduce screening time. Continuous upgrades in AI analytics, automated threat identification, and integrated security platforms further strengthen their market presence. North America remained the leading region in 2024 with a 37% share, supported by strict aviation security standards and rapid modernization of screening infrastructure.
Market Insights
- The Baggage Scanners Market was valued at USD 2.21 billion in 2024 and is expected to reach USD 3.01 billion by 2032, registering a CAGR of 3.95% during the forecast period.
- Growth is driven by rising global air travel, strict security regulations, and strong demand for advanced dual-energy and CT-based scanners across airports and border checkpoints.
- Major trends include rapid adoption of AI-driven detection, automation of screening lanes, and expansion of portable scanners for events and temporary checkpoints.
- Competition remains strong as CEIA SpA, Kromek Group plc, Teledyne ICM, Autoclear LLC, Gilardoni S.p.A., and other players enhance imaging quality, cybersecurity, and remote screening capabilities to strengthen market presence.
- North America led the market with 37% share in 2024, while airports dominated the end-use segment with about 58% share, supported by modernization of screening systems across major transit hubs.
Market Segmentation Analysis:
By Product Type
X-ray scanners led the product type segment in 2024 with about 64% share. Their strong position came from high deployment across airports, rail stations, and secured buildings due to reliable threat detection. Demand grew as modern X-ray units offer dual-energy imaging, real-time alerts, and better material discrimination. Vacuum systems expanded in facilities that handle sensitive goods, while RFID gained traction for baggage tracking and workflow automation. Rising global travel volumes and strict security mandates continued to push X-ray scanner adoption across major transit hubs.
- For instance, Smiths Detection deployed CT-based baggage scanners with automated threat detection by 2023, enabling airports to reduce manual bag checks and increase screening throughput while maintaining regulatory compliance.
By Mobility
Fixed systems dominated the mobility segment in 2024 with nearly 71% share. These systems remained preferred in airports, border points, and metro stations because fixed installations offer higher throughput, stronger scanning performance, and durability for 24/7 operations. Portable and mobile scanners gained demand from events, rapid-response units, and small terminals requiring flexible screening. Growth in fixed systems was driven by infrastructure upgrades, government safety programs, and rising investment in integrated surveillance platforms designed to streamline large-scale passenger movement.
- For instance, Hawkberg offers portable X-ray baggage scanners designed for rapid setup and compact operation. These systems support temporary checkpoints, mobile security units, and remote screening needs where fixed infrastructure is limited.
By End Use
Airports led the end-use segment in 2024 with around 58% share. The dominance came from stringent aviation security standards and the need to manage rising passenger traffic. Airports invested in advanced scanners that detect explosives, contraband, and high-risk items with faster processing speeds. Transit stations and border checkpoints expanded as countries strengthened transportation security. Commercial facilities also adopted scanners to protect high-value assets and control access. Growth across all end uses aligned with tightening regulations and increased global focus on screening efficiency.
Key Growth Drivers
Rising Global Air Traffic and Security Mandates
Growing international travel and increasing cross-border movement continue to push airports, seaports, and transit hubs to expand screening capacity. Aviation agencies worldwide enforce strict rules on baggage inspection, which drives investments in advanced scanners with higher accuracy and faster throughput. Authorities adopt dual-energy, multi-view, and CT-based systems to meet emerging threats linked to explosives, weapons, and prohibited goods. Airports upgrade legacy systems to handle peak loads and reduce wait times during security checks. Rising tourism, expanding airline fleets, and new airport terminals further strengthen demand. This shift toward efficient and automated screening fuels sustained growth in the baggage scanners market.
- For instance, Smiths Detection deployed the HI-SCAN 6040 CTiX, a CT carry-on baggage scanner certified to ECAC EDS CB C3 and TSA APSS 6.2 Level 1 standards. The system supports screening without removing electronics or liquids, helping airports streamline passenger inspection workflows.
Growing Threat Landscape and Need for Advanced Detection
Threat patterns are evolving rapidly, increasing the need for scanners that detect a wide range of dangerous items. Security agencies seek systems capable of identifying concealed objects, powder-based substances, lithium batteries, narcotics, and chemically hazardous materials. AI-driven analysis, pattern recognition, and automated threat highlighting improve operator efficiency and reduce error rates. Countries also invest in integrated screening networks that link scanners with real-time intelligence platforms. These upgrades help authorities respond to smuggling attempts, terrorism risks, and contraband flow. The rising focus on national security and tightening border control measures makes high-performance detection technology a major growth driver.
- For instance, Smiths Detection’s HI-SCAN 10080 XCT is a high-speed CT-based explosives detection system for hold baggage and air cargo. The platform delivers 3D volumetric imaging and is designed to support high screening throughput at large airports while maintaining certified detection performance.
Infrastructure Modernization and Digital Transformation
Many nations are modernizing airports, railway hubs, and border facilities, creating strong demand for next-generation scanning systems. Public and private operators deploy high-speed scanners, robotics-assisted baggage handling, and automated inspection lanes to streamline passenger flow. Digital transformation fuels adoption of cloud-based monitoring, predictive maintenance, and centralized command systems that enhance operational visibility. Governments increasingly fund smart-security projects, especially in Asia-Pacific, the Middle East, and Europe. As infrastructure projects expand, operators replace outdated scanners with energy-efficient, networked, and high-resolution systems. This modernization wave accelerates procurement cycles and boosts long-term market growth.
Key Trends & Opportunities
AI Integration and Automation Across Screening Systems
AI plays a major role in shaping the future of baggage scanners by improving both accuracy and speed. Machine-learning algorithms help identify complex threats and automate routine decision-making, reducing operator fatigue and lowering false-alarm rates. Automated tray return systems, remote screening, and self-service security lanes improve passenger flow in busy terminals. Integration with airport data platforms supports risk-based screening and predictive threat mapping. These advancements create strong opportunities for manufacturers offering scalable, intelligent solutions.
- For instance, Smiths Detection’s iCMORE AI software integrates with CT baggage scanners to support automated threat recognition using machine-learning algorithms, improving image consistency and reducing operator workload across certified EDS screening systems.
Shift Toward Contactless and Touch-Free Security
Airports and commercial hubs are adopting touch-free and automated screening solutions to improve hygiene and efficiency. New scanners support remote viewing, mobile operator consoles, and automated scanning tunnels that reduce human contact. Contactless identification through RFID and automated tray handling also streamline movement. This shift opens opportunities for companies delivering systems optimized for speed, minimal contact, and improved passenger comfort.
- For instance, Rapiscan Systems’ Orion 920CT is a CT-based carry-on baggage scanner that supports screening without removing electronics or liquids under approved operating rules. The platform enables remote image analysis and centralized screening while meeting applicable ECAC and TSA certification requirements.
Expansion of Mobile and Portable Scanning Solutions
Demand for portable scanners is rising across border checkpoints, public events, and temporary security installations. Mobile units support fast deployment and flexible scanning where permanent systems cannot be installed. This trend creates opportunities for lightweight, rugged, and battery-efficient scanner designs.
Key Challenges
High Procurement and Maintenance Costs
Advanced scanners require significant capital investment, which limits adoption in smaller airports and commercial sites. CT-based and multi-view systems involve high installation, calibration, and maintenance expenses. Operators must also train staff and manage continuous software updates to maintain compliance. For developing regions with limited budgets, these costs slow procurement and extend replacement cycles. The financial burden remains a major challenge for wider market penetration.
Operational Complexity and Skill Gaps
Modern scanners rely on sophisticated imaging, software analytics, and integrated networks, requiring skilled operators. Many regions face shortages of trained personnel capable of interpreting images and managing automated systems. Poor training increases false alarms and reduces efficiency. Additionally, integrating scanners with existing security infrastructure often creates technical challenges. This skills gap slows full-scale adoption and impacts operational reliability.
Regional Analysis
North America
North America led the Baggage Scanners Market in 2024 with about 37% share. Strong federal aviation mandates, high international passenger traffic, and frequent upgrades to screening systems supported continued adoption. Airports expanded CT-based and multi-view scanners to improve detection accuracy and reduce congestion. Border checkpoints also strengthened procurement due to rising cross-border movement and advanced threat screening needs. Investments in AI-integrated scanning platforms and modernization of transportation hubs further boosted demand. The region’s mature infrastructure and strong security compliance requirements continued to drive sustained system replacement and technological upgrades.
Europe
Europe held nearly 31% share in 2024, supported by strict aviation security rules and continuous modernization across major airports. EU regulatory frameworks pushed operators to adopt advanced scanners that meet updated threat-detection standards. Nations such as the U.K., Germany, France, and the Netherlands upgraded systems to handle dense passenger flow and improve border security efficiency. The expansion of intra-EU travel and rising cargo screening needs further supported demand. Investments in automated screening lanes and AI-enabled inspection tools also accelerated adoption across transit hubs, seaports, and high-traffic commercial facilities.
Asia-Pacific
Asia-Pacific accounted for approximately 26% share in 2024, driven by rapid airport expansion, rising tourism, and growing airline fleets. Countries such as China, India, Japan, and South Korea invested heavily in next-generation scanners to support new terminals and high-traffic transit systems. Regional governments strengthened border security and cargo screening to manage increasing passenger volumes and trade flow. Growing interest in AI-enabled screening, automated baggage lanes, and integrated security management platforms also accelerated momentum. The region’s fast-growing aviation ecosystem positioned Asia-Pacific as one of the strongest future demand centers.
Latin America
Latin America captured around 4% share in 2024, supported by gradual upgrades in airport screening and growing emphasis on border security. Nations such as Brazil, Mexico, and Colombia invested in new imaging systems to improve threat detection and reduce operational bottlenecks. Rising tourism and expansion of regional airlines also encouraged scanning system adoption. Budget constraints slowed full-scale modernization, but international funding programs and private-sector investment improved deployment rates. The region’s need for enhanced security at public venues and transport hubs continued to create steady replacement opportunities.
Middle East & Africa
The Middle East & Africa region held nearly 2% share in 2024, yet showed rising long-term potential due to expanding airport infrastructure and tourism-driven travel growth. Gulf countries invested in advanced screening systems for large international hubs, focusing on CT-based scanners and automated lanes. African nations gradually adopted modern scanners to strengthen border control and improve cargo inspection. Security upgrades for major events and new construction projects also supported demand. Although investment levels vary widely, ongoing infrastructure development positions the region for steady adoption over the next decade.
Market Segmentations:
By Product Type
- X-ray Scanners
- Vacuum System
- RFID
By Mobility
- Fixed Systems
- Portable / Mobile Systems
By End Use
- Transit Stations
- Border Checkpoints
- Airports
- Commercial Facilities
- Other End Use
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Baggage Scanners Market features strong competition among leading companies such as CEIA SpA, Kromek Group plc, Teledyne ICM, Autoclear LLC, Gilardoni S.p.A., Astrophysics Inc., IDSS, Nikon Metrology, L3Harris Technologies’ legacy security units, and VOTI Detection Inc. These manufacturers compete through advanced imaging technologies, AI-enabled threat detection, and multi-view or CT-based scanning platforms that enhance screening accuracy and throughput. Companies strengthen their positions by expanding product portfolios, improving cybersecurity features, and integrating scanners with automated lanes and centralized screening systems. Strategic partnerships with airports, government agencies, and border authorities help secure long-term contracts. Many players focus on developing energy-efficient, compact, and networked systems tailored to both high-traffic hubs and smaller facilities. Continuous R&D investment, regulatory compliance, and global service networks remain central to maintaining competitiveness in this evolving security market.
Key Player Analysis
- CEIA SpA
- Kromek Group plc
- Teledyne ICM
- Autoclear LLC
- Gilardoni S.p.A.
- Astrophysics Inc.
- IDSS (Integrated Defense and Security Solutions)
- Nikon Metrology
- L3Harris Technologies (legacy security units)
- VOTI Detection Inc.
Recent Developments
- In March 2024, Kromek received a US$ 2.1 million order from a U.S.-based OEM serving the homeland security sector to supply radiation-detector components for advanced explosive detection systems. The contract, scheduled for delivery in the first half of FY 2025, highlights continued demand for Kromek’s detector technology within the security screening equipment supply chain.
Report Coverage
The research report offers an in-depth analysis based on ProductType, Mobility, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for CT-based scanners will rise as airports replace older X-ray systems.
- AI-driven threat detection will become standard to improve accuracy and reduce false alarms.
- Automated screening lanes will expand to speed up passenger flow in high-traffic terminals.
- Portable and mobile scanners will gain traction for rapid deployment in temporary security zones.
- Integration with centralized security command platforms will strengthen real-time monitoring.
- Manufacturers will focus on energy-efficient and low-maintenance scanners to reduce operating costs.
- Border checkpoints will increase adoption due to growing cross-border movement and smuggling concerns.
- Smart scanning systems will support touchless and remote screening to enhance operator safety.
- Governments will boost investments in modernization programs across airports and transport hubs.
- Hybrid imaging technologies will emerge to detect complex threats and improve screening precision.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Baggage Scanners market?
At what Compound Annual Growth Rate is Baggage Scanners Market projected to grow between 2024 and 2032?
What factors are driving the growth of the Baggage Scanners market?
What are the key segments within the Baggage Scanners market?
What are some challenges faced by the Baggage Scanners market?
Who are the major players in the Baggage Scanners market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Baggage Scanners Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Baggage Scanners Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2.21 billion → 2032: USD 3.01 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Baggage Scanners Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Baggage Scanners Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Baggage Scanners Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Baggage Scanners Market Drivers
- 3.3 Baggage Scanners Market Restraints & Challenges
- 3.4 Baggage Scanners Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Baggage Scanners Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Baggage Scanners Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Baggage Scanners category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Baggage Scanners Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Baggage Scanners Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Baggage Scanners market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Baggage Scanners Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Baggage Scanners Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Baggage Scanners Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Baggage Scanners (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Baggage Scanners Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Baggage Scanners Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Baggage Scanners Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Baggage Scanners Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Baggage Scanners Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Baggage Scanners Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Baggage Scanners Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Baggage Scanners Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Baggage Scanners Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
